
 Aerogel Market | 2026-2036
Aerogel Market Size, Share, and Industry Trends Forecast 2026-2036
Aerogel Market Intelligence
New production capacity additions in China are fragmenting the supplier base, traditionally centered in North America and Europe. Aspen Aerogels, Inc. leverages its specialization in blanket forms for demanding industrial applications. Cabot Corporation competes with its portfolio of silica aerogel particles for coatings and composites. BASF SE sustains its market position through extensive R&D in polymer and metal oxide aerogels, targeting niche electronics and chemical plant end-users.
Aerogel is a synthetic porous ultralight material derived from a gel, in which the liquid component has been replaced with a gas. Its structure, often over 99% air, provides exceptional thermal insulating properties and extremely low density. Silica aerogel remains the dominant product type due to its established manufacturing processes and performance in thermal insulation applications. Carbon and polymer aerogels are gaining traction in specialized uses like energy storage and catalyst support.
Regulatory frameworks such as the EU's REACH and RoHS directives influence material composition and market access in Europe. In the United States, building codes and standards referenced by the EPA dictate performance requirements for insulation products. In China, GB standards for construction materials also shape product specifications. Material suppliers must now decide whether to focus on high-volume, standardized products or pursue higher-margin, application-specific formulations.
Market Dynamics
The aerogel market's central dynamic is the tension between high-volume production, driven by new capacity in China, and the demand for specialized, high-margin formulations from aerospace and electronics end-users. This creates a strategic divergence for suppliers between standardization and customization.
Growth Catalysts
- Energy Efficiency Mandates:Regulations like the EU Green Deal are tightening thermal performance requirements for buildings, creating significant demand for high-performance insulation materials like aerogel blankets to reduce energy consumption.
- Aerospace Sector Demand:The push for lighter, more fuel-efficient aircraft is a major catalyst, with aerospace firms specifying aerogel for its superior thermal insulation-to-weight ratio in engine and fuselage components.
- Industrial Upgrading in Asia:Manufacturing investment in China for high-tech sectors like electronics and chemical processing is concentrating demand for advanced industrial insulation to ensure process stability and safety.
Market Restraints
- High Production Costs:The supercritical drying process, essential for creating the aerogel structure, is energy-intensive and expensive, keeping the material's price point significantly above conventional insulation alternatives.
- Material Brittleness:Monolithic silica aerogels are inherently fragile and susceptible to fracture, which limits their use in applications requiring mechanical durability without reinforcement in composites or blankets.
- Substitution from Incumbents:In applications where thermal performance is not the absolute priority, aerogels face strong competition from lower-cost incumbent materials like polyurethane foam and mineral wool.
Strategic Opportunities
- Electric Vehicle Batteries:The need to prevent thermal runaway in electric vehicle battery packs presents a major opportunity for aerogel insulation sheets as lightweight, fire-resistant thermal barriers between cells.
- Advanced Composite Forms:Developing more flexible and robust aerogel composites and blankets opens new applications in apparel, personal protective equipment, and complex industrial geometries where rigid panels are unsuitable.
- Biomedical Applications:The biocompatibility and high porosity of certain aerogel types create opportunities in high-margin medical niches such as advanced wound care and controlled drug delivery systems.
Industry Challenges
- Capital Investment Hurdles:The substantial capital expenditure required to build and commission production facilities, particularly those with supercritical drying capabilities, acts as a significant barrier to new market entrants.
- Standardization Gaps:A lack of globally harmonized standards for testing and classifying different aerogel types (silica, carbon, polymer) creates performance ambiguity for engineers and procurement managers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerogel Market |
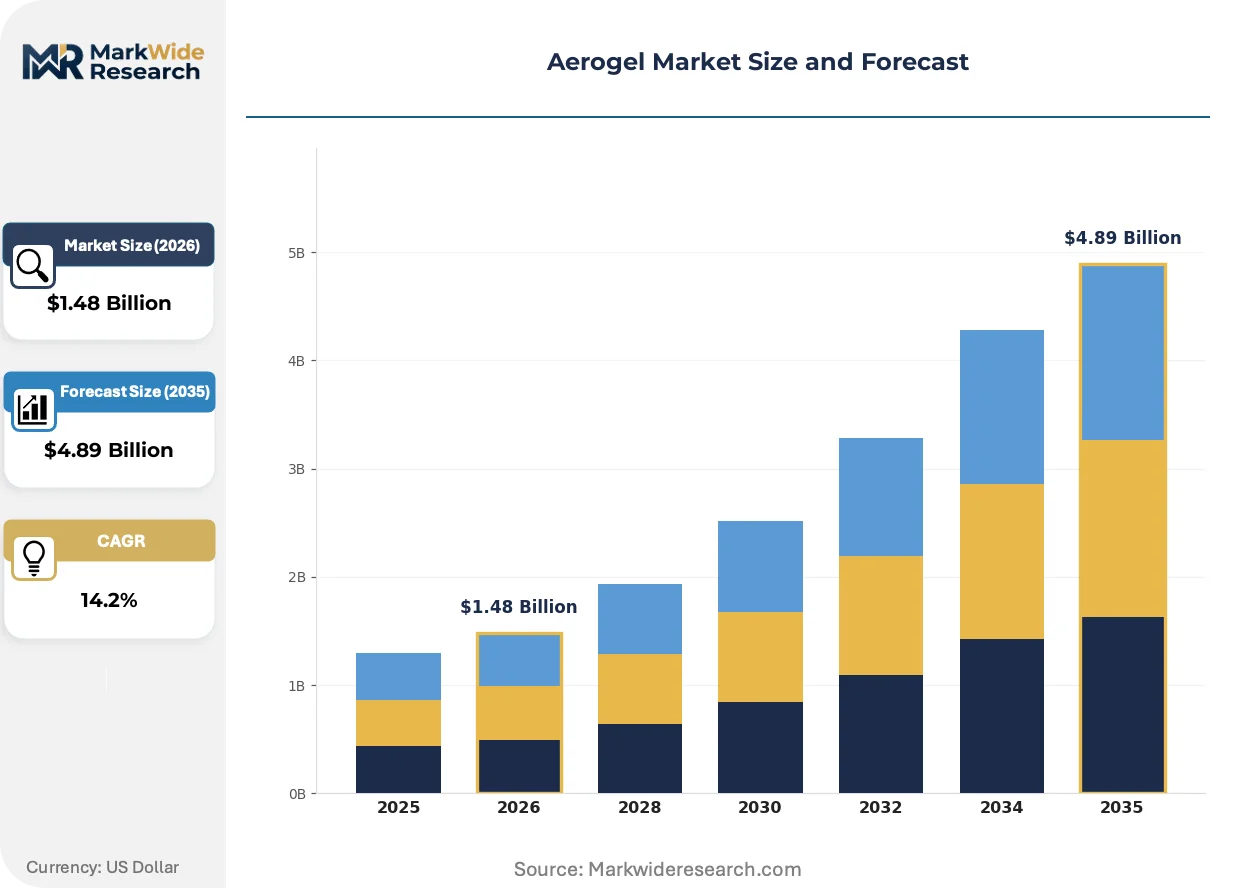
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica Aerogel, Carbon Aerogel, Alumina Aerogel, Polymer Aerogel, Metal Oxide Aerogel Application: Thermal Insulation, Oil Spill Cleanup, Acoustic Insulation, Catalyst Support, Energy Storage End User Industry: Construction Sector, Aerospace Firms, Environmental Agencies, Electronics Manufacturers, Chemical Plants Form: Blanket, Granules, Monolith, Powder, Composite Sheets |
| Companies Covered | Aspen Aerogels, Inc., Cabot Corporation, Armacell International S.A., Aerogel Technologies, LLC, Guangdong Alison Hi-Tech Co., Ltd., Svenska Aerogel AB, BASF SE, Enersens, Nano Tech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerogel Market Strategic Shifts & Innovations
The market is shifting from a focus on raw material production toward the development of integrated, application-specific systems. This evolution is driven by end-user demands for guaranteed performance in complex operating environments, moving suppliers up the value chain.
New material formulations are expanding the functional scope of aerogels beyond simple thermal insulation. Carbon and polymer aerogels are gaining traction in the electronics and energy storage sectors for their unique electrical and catalytic properties. This development is hybridizing the market, allowing for the creation of multifunctional components that combine thermal management with electrical conductivity or chemical reactivity.
Regulatory frameworks are increasingly specifying material performance over composition, creating pathways for innovative materials. China's GB standards for energy efficiency in industrial equipment and construction are becoming more stringent, forcing a move away from traditional insulation. The industrial insulation segment in China is most affected, accelerating the adoption of aerogel-based solutions to meet the new performance thresholds.
A notable shift in purchasing behavior is occurring among sophisticated end-users. Customers in the oil and gas and aerospace industries are increasingly specifying thermal performance outcomes for engineered systems rather than procuring aerogel as a bulk material. This disrupts the traditional distributor channel, favoring suppliers who can provide integrated design, engineering, and installation support, a pattern most visible in North American and European project markets.
Aerogel Market Segmentation
The aerogel market's segmentation highlights the diverse functional requirements across its end-use sectors. Understanding these distinct segments allows suppliers to tailor product development and market strategies for optimal penetration. Each segment reflects specific material properties and performance thresholds demanded by specialized applications.
Product Type:
After-sales service intensity varies significantly across aerogel product types, driven by complexity of application and material handling requirements.
- Silica Aerogel:This material is characterized by its high porosity and excellent thermal insulation properties, derived from silicon dioxide. Demand concentrates in the construction sector where EU Green Deal regulations mandate enhanced energy efficiency for buildings.
- Carbon Aerogel:Composed primarily of carbon, this type exhibits high electrical conductivity and large surface area, making it suitable for electrochemical applications. The electronics manufacturing sector in China increasingly specifies carbon aerogels for advanced energy storage devices.
- Alumina Aerogel:Alumina aerogel offers high-temperature stability for catalytic converters and specialized industrial processes.
- Polymer Aerogel:Polymer aerogels provide greater flexibility and robustness, expanding into advanced composites for aerospace lightweighting.
- Metal Oxide Aerogel:Metal oxide aerogels, like titanium or iron oxides, are explored for sensors and photocatalysis.
Silica Aerogel holds the largest share; momentum sits with Polymer Aerogel.
Application:
The market for aerogels is fundamentally shaped by the specific performance requirements of each application area.
- Thermal Insulation:This primary application leverages aerogel's extremely low thermal conductivity to prevent heat transfer across various temperature gradients. Aerospace firms and the construction sector in Germany prioritize aerogel for critical thermal barriers in aircraft and high-performance building envelopes.
- Energy Storage:Aerogels with high surface area and tunable pore structures are crucial for next-generation batteries and supercapacitors. Electric vehicle battery manufacturers in South Korea are exploring aerogel sheets as lightweight, fire-resistant thermal barriers.
- Oil Spill Cleanup:Hydrophobic aerogels efficiently absorb oil from water, offering an environmentally friendly marine spill solution.
- Acoustic Insulation:Aerogel's porous structure dampens sound, valuable for noise reduction in industrial and automotive interiors.
- Catalyst Support:High surface area aerogels support catalytic materials, enhancing reaction efficiency in chemical processing plants.
Thermal Insulation remains the dominant application, while Energy Storage is expanding most quickly.
End User Industry:
Different end-user industries exhibit distinct procurement patterns and technical specifications for aerogel materials.
- Construction Sector:This industry uses aerogel primarily in blanket and panel forms for building envelopes, roofing, and window insulation to meet stringent energy efficiency codes. The EU Green Deal mandates drive significant demand for aerogel solutions in residential and commercial buildings across France and Italy.
- Aerospace Firms:Aerospace manufacturers demand ultralight, high-performance thermal insulation for fuselage, engine, and cryogenic fuel tank applications. Companies like Boeing and Airbus integrate aerogel composites to reduce aircraft weight and improve fuel efficiency.
- Environmental Agencies:Environmental agencies utilize aerogels for remediation, especially in water purification and hazardous waste absorption.
- Electronics Manufacturers:Aerogels offer thermal management and dielectric properties for sensitive electronics and high-power devices.
- Chemical Plants:Chemical plants require robust aerogel insulation to maintain process temperatures and pipeline safety.
The Construction Sector accounts for the largest volume, with Electronics Manufacturers demonstrating significant growth potential.
Form:
The physical form of aerogel dictates its ease of handling, application method, and suitability for high-volume standardization versus custom solutions.
- Blanket:Flexible aerogel blankets, often reinforced with fibers, offer ease of installation and conformability for large-scale industrial and building insulation projects. North American project markets increasingly specify aerogel blankets for pipeline insulation in oil and gas facilities.
- Composite Sheets:These forms integrate aerogel particles into a matrix, enhancing mechanical strength and enabling tailored performance for specific applications. The automotive industry in Germany is exploring composite sheets for lightweight thermal barriers in electric vehicle battery packs.
- Granules:Free-flowing aerogel granules serve as additives in coatings, insulation fillers, and filtration systems.
- Monolith:Rigid, unreinforced aerogel monoliths offer superior insulation but are fragile, limiting use to low-stress areas.
- Powder:Fine aerogel powder functions as an opacifier in vacuum insulation panels and high-performance paints.
Aerogel Blankets command the largest market share, while Composite Sheets are experiencing the most rapid adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New production capacity additions in China are reshaping global supply dynamics for aerogel materials. This shift is fragmenting a supplier base traditionally centered in North America and Europe. The global market now sees a strategic divergence between high-volume standardization and application-specific customization.
China
Manufacturing investment in China for high-tech sectors drives significant demand for advanced industrial insulation. China's GB standards for construction materials are becoming more stringent, forcing a move away from traditional insulation. Industrial upgrading in the Yangtze River Delta region particularly accelerates the adoption of aerogel-based solutions.
United States
The aerospace sector's push for lighter, more fuel-efficient aircraft is a major demand catalyst for aerogels. Building codes and standards referenced by the EPA dictate performance requirements for insulation products. Aerospace firms in the Seattle area integrate aerogel composites to reduce aircraft weight and improve fuel efficiency.
Germany
The construction sector in Germany prioritizes aerogel for critical thermal barriers in high-performance building envelopes. Regulations like the EU Green Deal are tightening thermal performance requirements for buildings. The automotive industry in Bavaria explores composite sheets for lightweight thermal barriers in electric vehicle battery packs.
South Korea
Energy storage applications, especially for next-generation batteries and supercapacitors, drive aerogel demand in South Korea. Electric vehicle battery manufacturers are exploring aerogel sheets as lightweight, fire-resistant thermal barriers. The Seoul Capital Area sees significant R&D and manufacturing for advanced electronics and EV components.
France
Construction sector demand for enhanced energy efficiency in residential and commercial buildings across France is substantial. The EU Green Deal mandates drive the adoption of aerogel solutions for building envelopes and window insulation. Companies in the Île-de-France region are increasingly specifying aerogel for large-scale renovation and new construction projects.
Aerogel Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing foundational materials. The market exhibits a tiered structure, with established players focusing on both raw material production and integrated solutions. Strategic archetypes include specialized material producers, application-focused solution providers, and diversified chemical giants. Capacity expansion, particularly in Asia, and portfolio diversification are dominant competitive moves.
Specialists in advanced material formulations like Aspen Aerogels, Inc. leverage their expertise in blanket forms for demanding industrial applications. Cabot Corporation occupies a strong position with its portfolio of silica aerogel particles for coatings and composites. Diversified chemical companies such as Germany-based BASF SE sustain their market presence through extensive R&D in polymer and metal oxide aerogels.
| Leading Market Players |
|---|
| Aspen Aerogels, Inc. |
| Cabot Corporation |
| Armacell International S.A. |
| Aerogel Technologies, LLC |
| Guangdong Alison Hi-Tech Co., Ltd. |
| Svenska Aerogel AB |
| BASF SE |
| Enersens |
| Nano Tech Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lane costs influence aerogel pricing dynamics, especially as new production capacity in China concentrates supply. This shift impacts downstream price differentiation for construction and aerospace materials in North America and Europe.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure for aerogel insulation in European construction, emphasizing performance outcomes. Pricing models combine project-based contracts for specialized aerospace and electronics applications with per-unit transactional pricing for high-volume construction materials. Price differentiation stems from customization levels for niche formulations and stringent certification requirements. New high-volume production capacity in China creates pricing pressure for standardized products, making the construction sector more price-sensitive than aerospace firms.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support aerogel manufacturers, especially those sourcing raw materials from diverse regions. Geographic supply concentrates in China for new capacity, alongside established production in North America and Europe. The industry relies on silica, carbon, and polymer precursors, plus specialized reinforcing fibers, creating commodity price volatility risk. Distribution runs through direct sales channels for project-based aerospace applications, with construction materials utilizing specialized distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands a robust substitution defense strategy, as incumbents must navigate competition from lower-cost alternatives like polyurethane foam. Aerogel manufacturers need to continually demonstrate superior performance benefits to justify premium pricing.
For Market Incumbents:
Build application engineering moats by developing integrated, performance-guaranteed systems for complex end-user requirements. Incumbents should invest in R&D for advanced polymer and metal oxide aerogels, targeting niche electronics and chemical plant applications. Deepen relationships with aerospace firms and EV battery manufacturers, providing full design and installation support to counter material brittleness concerns. Pursue certifications for fire-resistant thermal barriers in electric vehicles to differentiate from conventional insulation.
For New Entrants and Emerging Players:
Build out niche capabilities in high-margin, application-specific formulations, particularly for biomedical applications like advanced wound care. Target emerging energy storage markets in South Korea and Japan, focusing on lightweight, fire-resistant aerogel sheets for EV batteries. Develop cost-effective supercritical drying processes to overcome capital investment hurdles. Emphasize performance outcomes over raw material cost, offering integrated solutions to gain market traction.
For Investors and Strategic Acquirers:
Carve-out targets emerge from diversified chemical giants with underutilized polymer or metal oxide aerogel portfolios, offering specialized intellectual property. The market exhibits strong long-term growth potential, driven by persistent energy efficiency mandates and lightweighting trends across industries. Focus on acquiring specialized material producers with proprietary carbon or polymer aerogel technologies. Increased capital expenditure announcements for non-silica aerogel production facilities indicate inflection points for strategic investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | New production facilities in China address growing industrial and construction demand. |
| Advanced Composite Development | Flexible aerogel composites expand applications into apparel and complex industrial geometries. |
| Green Manufacturing Transition | Optimizing supercritical drying processes reduces energy consumption and production costs. |
| Long-term Supply Agreements | Securing contracts with aerospace firms ensures stable demand for high-performance insulation. |
| EV Battery Safety Certification | Achieving safety certifications unlocks significant opportunities in the electric vehicle market. |
Research Approach
Operator-level perspectives from plant managers, R&D directors, procurement leads, and aerospace engineers anchored the qualitative base for this analysis. The approach combined extensive primary interviews with rigorous secondary validation from SEC 10-K filings and industry association reports. Bottom-up and top-down triangulation ensured data consistency and comprehensive market coverage across segments. This multi-faceted methodology provided deep insights into aerogel market dynamics.
Scenario-bracketing framed the quantitative model, projecting market evolution across the analysis window under various adoption rates. The analytical framework integrated segmentation dimensions including product type, application, end-user industry, and form, alongside regional regulatory impacts. Compound annual growth rates were derived through regression analysis and expert consensus. Key inputs included energy efficiency mandates, aerospace production forecasts, and electric vehicle battery demand projections.
Stress conditions across raw material price volatility, regulatory stringency, and new production technology adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions and current market structures. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Supersonic Wind Tunnel Market
Aerospace and Aircraft Materials
Aerospace Composite Ducting Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Radiation Shielding Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Advanced Materials for Flying Cars Market
Aerospace and Aircraft Materials
Global Aerospace Titanium Machining Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace Coatings Market
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
Russia Space Electronics Market