
 Space Mobile Service Market | 2026-2036
Space Mobile Service Market Size, Share, and Industry Trends Forecast 2026-2036
Space Mobile Service Market Insights
Direct-to-device service revenue is rewriting profit allocation across the satellite communications value chain. SpaceX leverages its Starship launch cadence to drive down constellation deployment costs and capture upstream margin. AST SpaceMobile anchors the premium handset-compatible segment through phased array technology partnerships with terrestrial carriers. Iridium Communications Inc. sustains its pole position in government and maritime channels with cross-linked LEO architecture that resists jamming.
Space mobile service denotes the provision of voice, data, and broadband connectivity to standard consumer and enterprise devices via satellite constellations operating in low, medium, and geostationary Earth orbits, typically using S-band, L-band, or Ka-band frequencies with latency profiles ranging from 20 milliseconds to 600 milliseconds depending on orbital altitude. The primary purpose is to eliminate coverage dead zones beyond terrestrial cellular reach, serving maritime vessels, aircraft, remote industrial sites, and emergency responders who require uninterrupted links regardless of geography. Broadband connectivity and IoT connectivity represent the fastest-expanding service type categories, as enterprise fleet operators and agricultural sensor networks seek always-on telemetry outside fiber or tower footprints. Low Earth orbit satellites dominate deployment model discussions due to their latency advantage, though geostationary assets retain margin strength in broadcast and backhaul applications where real-time interactivity matters less.
The FCC governs spectrum allocation and orbital debris mitigation requirements for U.S.-based operators, while the ITU coordinates cross-border frequency registrations and interference protocols among national regulators. ESA member states apply the EU Space Surveillance and Tracking framework to mandate collision-avoidance capabilities for constellation operators accessing European ports and airspace. Stakeholders must monitor evolving debris-liability regimes and dual-use export classifications that could restrict component sourcing or limit addressable defense segments.
Market Dynamics
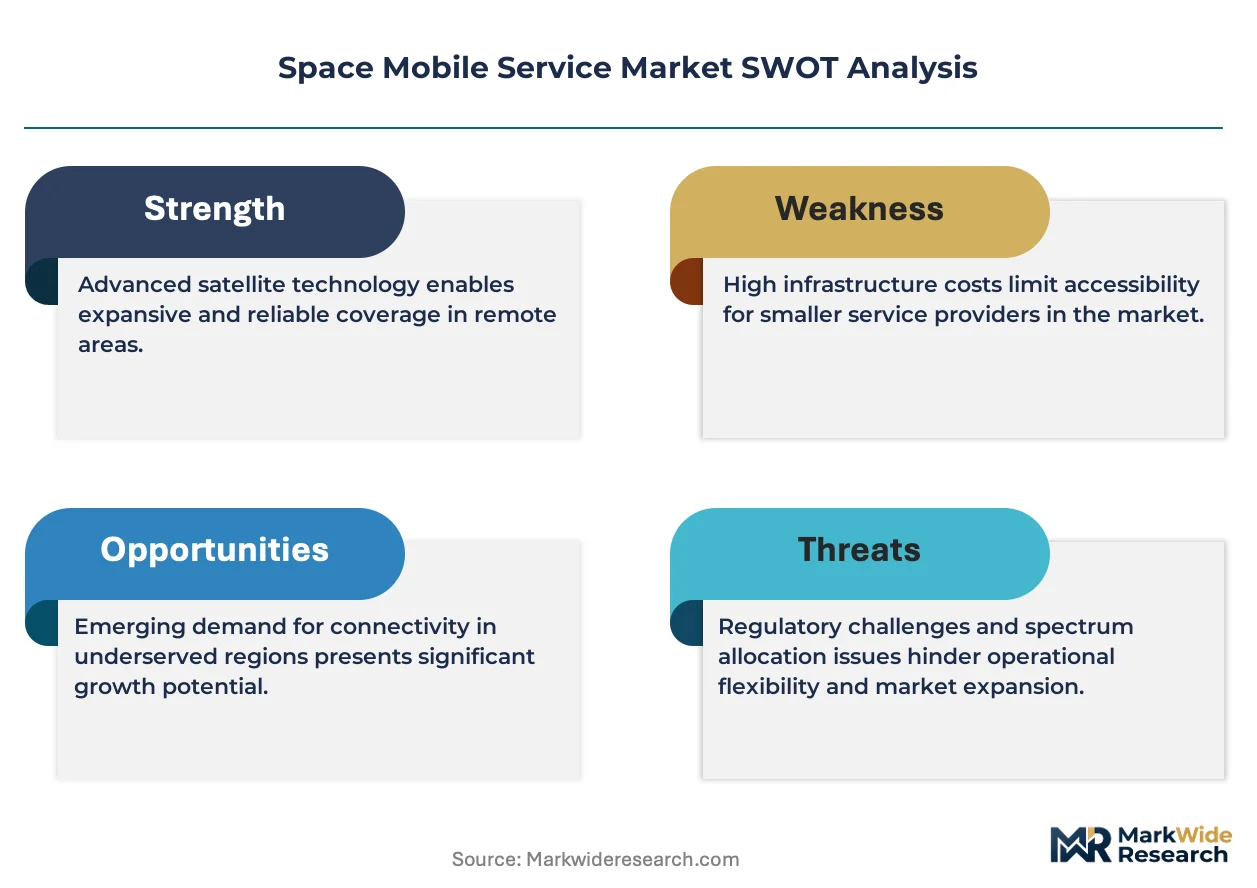
Direct-to-device satellite connectivity is compressing the traditional ground infrastructure value chain, as constellation operators bypass terrestrial tower networks to serve handsets directly from low Earth orbit. This structural shift redistributes margin from cellular carriers to satellite operators while forcing incumbents to renegotiate roaming and spectrum-sharing agreements.
Growth Catalysts
- FCC Part 25 Licensing Reform:Streamlined approval timelines for non-geostationary orbit systems accelerate constellation deployment schedules across U.S. coastal shipping corridors.
- Maritime Fleet Digitization:Container shipping operators mandate always-on telemetry for engine diagnostics and route optimization across Pacific and Atlantic lanes.
- Phased Array Antenna Maturation:Electronically steerable flat-panel terminals reduce installation costs for commercial aviation retrofit programs.
Market Restraints
- Launch Capacity Bottlenecks:Limited heavy-lift vehicle availability constrains constellation refresh cycles and orbital plane expansion timelines.
- Spectrum Coordination Friction:ITU notification procedures create multi-year delays for cross-border frequency assignments in contested bands.
- Terrestrial Interference Risks:Shared S-band allocations with legacy cellular networks necessitate expensive filtering and power-control mitigation.
Strategic Opportunities
- Sub-Saharan Africa Coverage Gaps:Sparse fiber infrastructure and low cellular tower density create addressable demand for direct-to-handset services.
- Defense Dual-Use Contracts:Military resilient communications mandates open classified procurement channels for anti-jam LEO architectures.
- IoT Sensor Backhaul Convergence:Agricultural monitoring networks and pipeline integrity systems seek unified satellite-cellular connectivity platforms.
Industry Challenges
- Orbital Debris Liability Exposure:Constellation operators face uncertain financial responsibility frameworks for collision avoidance and post-mission disposal.
- RF Engineer Talent Scarcity:Specialized expertise in satellite-ground link budget optimization and rain fade mitigation commands premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Mobile Service Market |
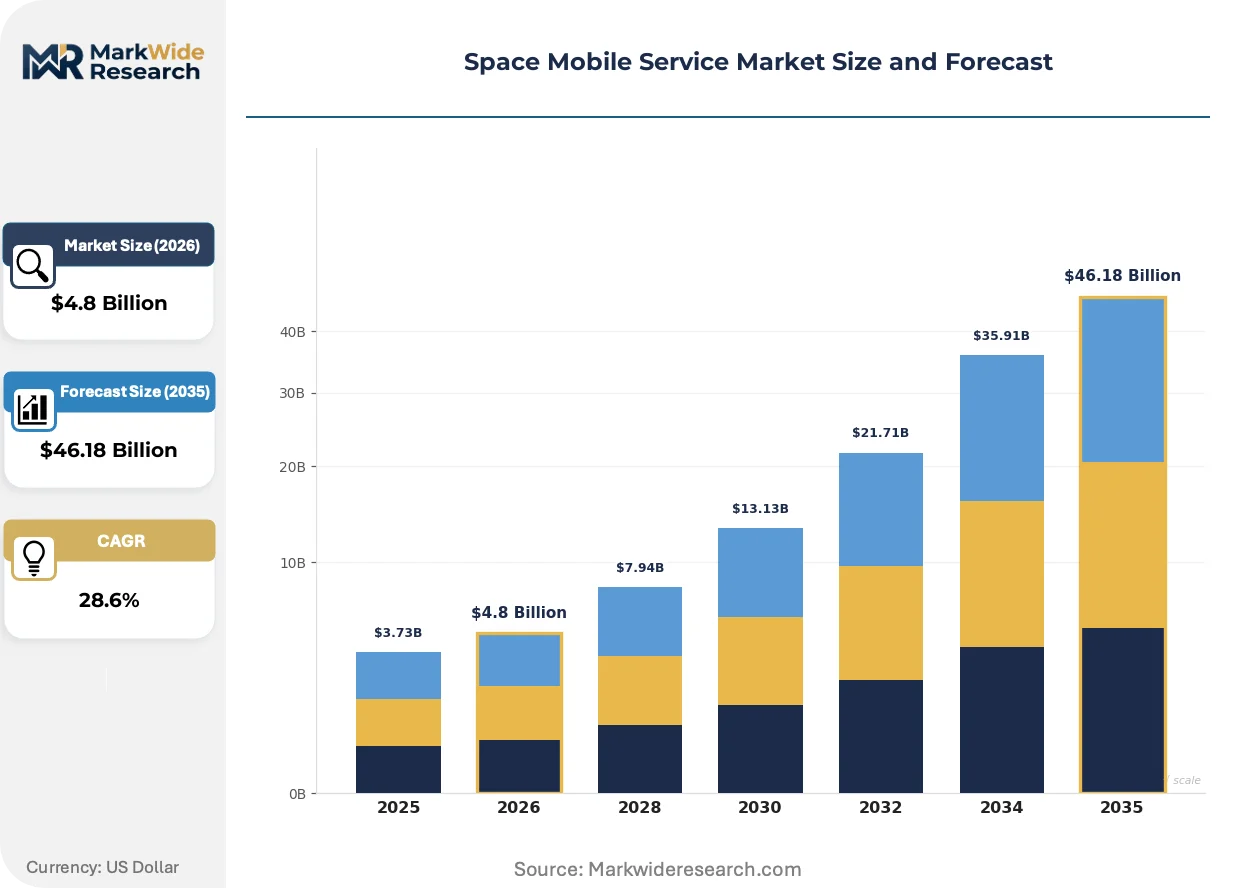
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice Communication, Data Transmission, Broadband Connectivity, Messaging Services, IoT Connectivity Application: Maritime Operations, Disaster Management, Remote Exploration, Aviation Communication, Scientific Research Deployment Model: Satellite Constellations, High Throughput Satellites, Geostationary Satellites, Low Earth Orbit Satellites, Medium Earth Orbit Satellites End User: Telecom Operators, Emergency Services, Research Institutions, Shipping Companies, Aviation Authorities |
| Companies Covered | AST SpaceMobile, SpaceX, Globalstar Inc., Iridium Communications Inc., Inmarsat plc, EchoStar Mobile Ltd, Skylo Technologies, Telesat Lightspeed, OneWeb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Mobile Service Market Trends and Innovations
Electronically steerable antenna technology and software-defined radio payloads are collapsing the cost structure for user terminals while enabling dynamic spectrum reallocation. These advances compress deployment timelines and expand addressable device categories beyond traditional maritime and aviation markets.
Flat-panel phased array terminals are rendering obsolete mechanically steered parabolic dishes for mobile platforms. Commercial airlines retrofit narrow-body fleets with low-profile fuselage-mounted units that maintain connectivity during banking maneuvers. This technology is rendering obsolete the three-year installation cycles and aerodynamic penalties of legacy radome systems.
EU Space Surveillance and Tracking framework mandates collision-avoidance capabilities for constellation operators accessing European ports and airspace. ESA member states now require maneuverability demonstrations and post-mission disposal plans as conditions for market access. Satellite operators with European gateway earth stations must integrate SST data feeds into autonomous navigation systems.
Enterprise buyers now specify interoperability certifications before procurement rather than accepting proprietary lock-in. Agricultural cooperatives and mining consortia demand multi-constellation receivers that switch between LEO and GEO assets based on latency requirements. This specification shift is most visible in Australian and Canadian remote resource operations where single-vendor dependency creates operational risk.
Space Mobile Service Market Segmentation
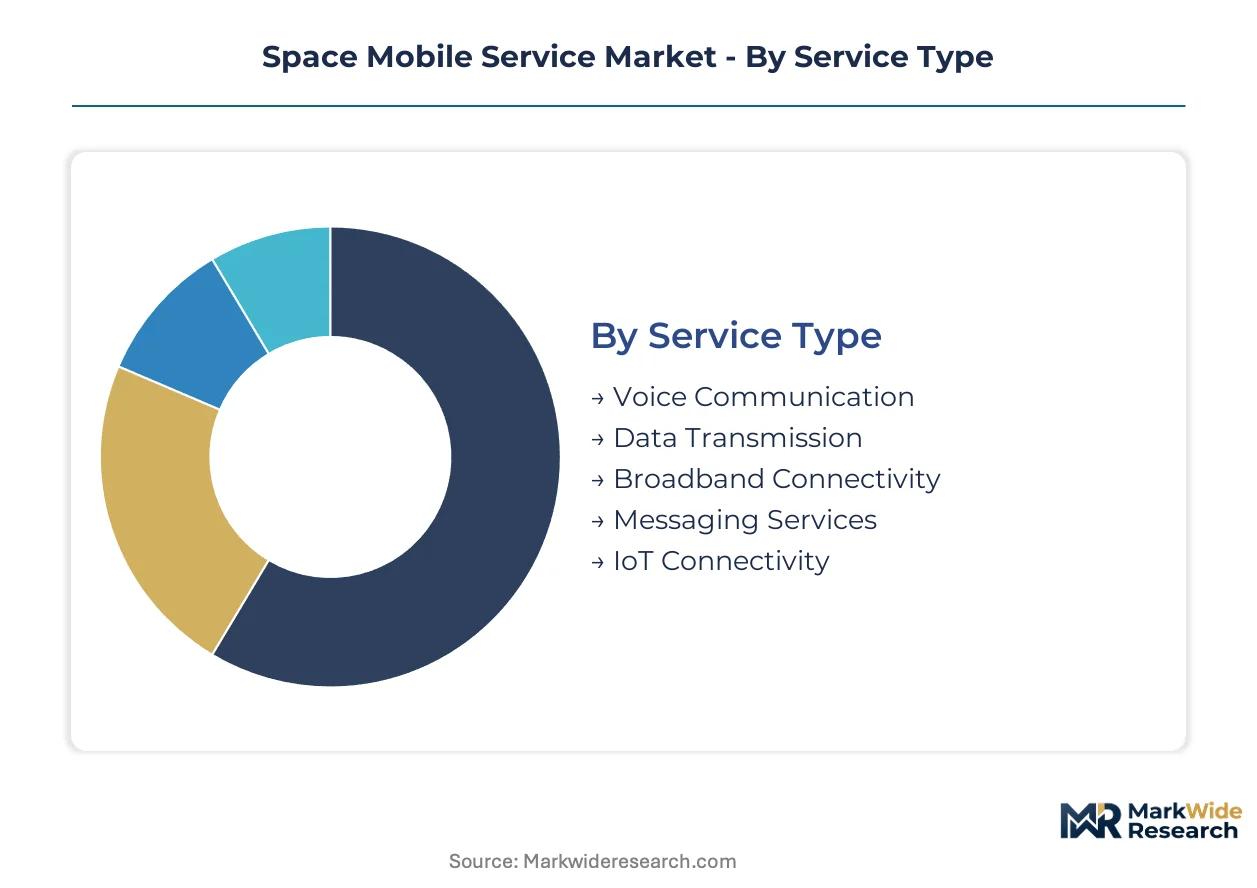
Segmentation in space mobile services reveals how orbital altitude, bandwidth economics, and end-use resilience requirements partition addressable demand. Operators configure constellation architectures and pricing tiers around these fault lines, with maritime and aviation procurement specifications driving hardware standardization.
Service Type:
Mature voice and messaging services anchor revenue stability while emerging broadband and IoT categories capture expansion capital.
- Broadband Connectivity:High-throughput Ka-band links deliver 100+ Mbps to moving platforms. Container shipping operators across Pacific lanes now mandate continuous broadband for engine telemetry and crew welfare systems.
- IoT Connectivity:Narrowband protocols transmit sensor data from agricultural monitors and pipeline integrity systems. Australian mining consortia deploy these networks where cellular backhaul remains economically unviable.
- Voice Communication:Legacy L-band services sustain maritime distress calling and government emergency channels.
- Data Transmission:Store-and-forward architectures serve scientific buoys and remote weather stations with intermittent burst requirements.
- Messaging Services:Short-burst data packets support fleet check-in protocols and aviation position reporting.
Voice Communication retains volume leadership; IoT Connectivity holds the steepest expansion curve.
Application:
Operational criticality varies sharply across use cases, with life-safety mandates in aviation and disaster response imposing certification burdens that consumer-grade services avoid.
- Maritime Operations:SOLAS-mandated GMDSS compliance drives terminal specifications for commercial fleets. Singapore-flagged vessels now require dual-redundant satellite links for route optimization and regulatory reporting.
- Aviation Communication:In-flight connectivity contracts specify 99.9% availability for narrow-body retrofits. Phased-array terminals from Alaska to Dubai maintain links through banking maneuvers that disrupt legacy mechanical dishes.
- Disaster Management:First responders deploy rapidly deployable terminals where terrestrial infrastructure fails.
- Remote Exploration:Antarctic research stations and Arctic drilling camps rely on satellite as sole connectivity path.
- Scientific Research:Oceanographic drifters and atmospheric balloons transmit datasets via store-and-forward protocols.
Maritime Operations commands the largest procurement budgets; Aviation Communication is climbing fastest as airline retrofit cycles accelerate.
Deployment Model:
Latency tolerance and capital intensity divide procurement between low-orbit newcomers and geostationary incumbents with depreciated assets.
- Low Earth Orbit Satellites:20-40 millisecond latency enables real-time gaming and video conferencing from moving platforms. Starlink and competitors target this architecture for direct-to-handset services.
- Geostationary Satellites:Fixed orbital position simplifies antenna pointing for broadcast and rural broadband. HughesNet and Viasat leverage mature ground infrastructure across CONUS rural markets.
- Satellite Constellations:Cross-linked architectures provide polar coverage and jam resistance for defense applications.
- High Throughput Satellites:Spot-beam frequency reuse concentrates capacity over dense demand zones.
- Medium Earth Orbit Satellites:Intermediate latency trade-offs serve navigation augmentation and specialized backhaul.
Geostationary Satellites retain installed base dominance; Low Earth Orbit Satellites are gaining share fastest through direct-to-device deployments.
End User:
Procurement sophistication ranges from standardized government tenders to bespoke enterprise integrations requiring multi-constellation receivers.
- Telecom Operators:Roaming agreements and spectrum leasing reshape carrier economics. T-Mobile and Verizon partnerships with satellite operators extend coverage maps without tower buildouts.
- Shipping Companies:Fleet-wide mandates for engine diagnostics and route optimization drive terminal standardization. Mediterranean Shipping Company and Maersk specify interoperable multi-constellation receivers.
- Emergency Services:FEMA and state agencies stockpile deployable terminals for hurricane and wildfire response.
- Aviation Authorities:FAA certification requirements govern terminal installation on commercial aircraft.
- Research Institutions:NSF and ESA grant programs fund polar and oceanographic connectivity.
Shipping Companies generate the highest terminal shipment volumes; Telecom Operators are expanding most quickly through carrier partnership models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal shipping lanes and remote oilfield operations in the United States consume space mobile services differently than inland markets, prioritizing fleet-wide telemetry over consumer broadband. Maritime operators across the Pacific and Atlantic mandate continuous connectivity for engine diagnostics and crew welfare. Defense procurement in polar regions drives demand for jam-resistant architectures unavailable through terrestrial alternatives.
United States
Coastal shipping corridors and Gulf of Mexico oilfield operations drive commercial uptake of satellite-linked fleet management systems. The FCC's streamlined Part 25 licensing framework for non-geostationary orbit systems accelerates constellation deployment timelines across domestic waters. Houston and New Orleans anchor maritime terminal procurement clusters where shipping operators specify dual-redundant satellite links.
United Kingdom
North Sea offshore energy platforms and transatlantic aviation routes generate concentrated demand for low-latency connectivity. The UK Space Agency coordinates with the ITU on cross-border frequency registrations for operators accessing British ports and airspace. London and Aberdeen host procurement decision centers where energy majors mandate interoperable multi-constellation receivers.
Singapore
Strait of Malacca container traffic and flag-registry compliance requirements sustain dense terminal deployment. The Infocomm Media Development Authority enforces spectrum coordination protocols for satellite services overlapping with terrestrial cellular networks. The Port of Singapore and surrounding Jurong industrial zone specify always-on telemetry for engine diagnostics and regulatory reporting.
Norway
Arctic offshore drilling camps and North Atlantic fishing fleets require uninterrupted links beyond fiber or tower footprints. The Norwegian Communications Authority applies ESA Space Surveillance and Tracking framework mandates for collision-avoidance capabilities. Stavanger and Bergen concentrate energy sector procurement where operators seek polar coverage and jam resistance.
Australia
Pilbara mining operations and Outback agricultural sensor networks create addressable demand where cellular backhaul remains economically unviable. The Australian Communications and Media Authority governs spectrum allocation for satellite services under ITU coordination protocols. Perth and Brisbane anchor remote resource operations where enterprise buyers specify multi-constellation receivers to avoid single-vendor dependency.
Space Mobile Service Market Competitive Landscape
Capability concentration sits with constellation architects possessing phased array and cross-linked LEO expertise; scale advantage sits with launch-integrated operators controlling deployment cadence. The market structures around three tiers: vertically integrated launch-to-service providers, specialized direct-to-device architects, and legacy geostationary incumbents with depreciated orbital assets. Dominant competitive moves include spectrum leasing partnerships with terrestrial carriers and heavy-lift capacity reservation agreements securing deployment timelines.
Within the vertically integrated tier, SpaceX exemplifies launch-cadence scale advantage through Starship deployment economics. AST SpaceMobile occupies a position in the premium handset-compatible segment through phased array technology partnerships. Iridium Communications Inc. anchors the government and maritime channel focus with cross-linked LEO architecture representation. These three entities illustrate how orbital altitude strategy and terrestrial carrier integration separate competitive positioning in direct-to-device markets.
| Leading Market Players |
|---|
| AST SpaceMobile |
| SpaceX |
| Globalstar Inc. |
| Iridium Communications Inc. |
| Inmarsat plc |
| EchoStar Mobile Ltd |
| Skylo Technologies |
| Telesat Lightspeed |
| OneWeb |
| Others |
Pricing and Supply Chain Analysis
Heavy-lift launch undercapacity across U.S. coastal ranges is compressing constellation deployment schedules and amplifying pricing power for operators controlling dedicated Starship cadence. This utilization squeeze simultaneously elevates premium tiers for guaranteed orbital slots while forcing price-sensitive maritime buyers toward multi-year offtake commitments.
Pricing Analysis
Long-term offtake contracts dominate procurement for container shipping operators mandating fleet-wide telemetry, while spot arrangements serve emergency response agencies with unpredictable deployment needs. Price differentiation hinges on latency grade and ITU frequency priority, with Ka-band low-latency links commanding substantial premiums over L-band legacy services. Cost compression in standard broadband tiers is intensifying because SpaceX launch economics are cascading downstream. Government defense channels exhibit the lowest price sensitivity due to jam-resilience mandates, whereas agricultural cooperatives in Australian Outback operations demonstrate acute sensitivity to per-terminal acquisition costs.
Supply Chain Analysis
Extended payment terms from phased array antenna manufacturers are stretching working capital for terminal integrators serving aviation retrofit programs. Component sourcing concentrates in the United States for RF semiconductor fabrication, Taiwan for advanced packaging, and Germany for precision mechanical subassemblies. Raw material dependencies include gallium nitride substrates, rare earth magnets for reaction wheels, and specialized aluminum-lithium alloys for satellite bus structures. Single-source vulnerability around ITAR-controlled radiation-hardened processors presents acute disruption risk. Distribution runs through authorized integrators holding FAA and maritime classification society certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is emerging from a capital-intensive deployment cycle as Starship cadence inflects constellation refresh economics, positioning early launch-integrated operators to capture margin expansion through the recovery phase.
For Market Incumbents: Build switching-cost moats through multi-constellation receiver certification programs that lock agricultural and mining consortia into proprietary firmware ecosystems. Deepen backward integration into gallium nitride amplifier production to defend margin position against emerging flat-panel terminal entrants. Prioritize FCC Part 25 licensing speed as the critical lever, as accelerated orbital deployment timelines widen coverage gaps before competitors secure frequency priority. For New Entrants and Emerging Players: Sub-Saharan African coverage gaps present the most penetrable white space, given sparse fiber infrastructure and minimal legacy geostationary incumbent presence. Target direct-to-handset partnerships with regional carriers lacking capital for terrestrial tower buildouts. Pursue ITU frequency coordination as the primary go-to-market angle, securing cross-border S-band assignments before established operators file competing notifications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across LEO constellation architectures as reusable launch economics mature, compressing payback periods for orbital assets. Target acquisition profiles should emphasize phased array patent portfolios and terrestrial carrier roaming agreements over pure satellite manufacturing capability. Watch Starship launch manifest reliability as the critical inflection signal, as deployment cadence volatility directly revises constellation refresh timelines and revenue recognition schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Leasing Partnership | T-Mobile and Verizon roaming agreements extend coverage maps without tower capital deployment. |
| Heavy-Lift Capacity Reservation | Starship block bookings secure orbital plane expansion timelines against launch queue congestion. |
| Phased Array Terminal Certification | FAA airworthiness approval enables narrow-body retrofit programs across Alaska-to-Dubai routes. |
| Multi-Constellation Receiver Development | Australian mining consortia specify interoperability to eliminate single-vendor operational dependency. |
| Defense Dual-Use Contracting | Anti-jam LEO architectures access classified procurement channels through resilient cross-linked design. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC licensing databases, ITU frequency notification filings, and ESA Space Surveillance and Tracking compliance records. Constellation operators, maritime fleet managers, aviation retrofit procurement officers, and RF engineering specialists provided operational perspectives through structured interviews. SEC filings from publicly traded satellite operators and customs data for terminal equipment imports furnished validation anchors. Bottom-up terminal shipment estimates and top-down service revenue aggregates were cross-referenced for consistency.
Forecast inputs span service type evolution, orbital altitude migration patterns, and end-user procurement sophistication across the projection horizon. Segmentation dimensions include deployment model architecture, application criticality tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated against historical constellation deployment timelines and maritime fleet digitization trajectories. Launch cost elasticity and phased array manufacturing yield curves served as satellite-specific model parameters.
Practitioners should monitor ITU notification backlogs, Starship manifest delays, and ESA debris-liability rulemaking for early signals of trajectory revision. Forecasts reflect documented assumptions regarding spectrum coordination timelines and launch vehicle availability. Macroeconomic contraction affecting maritime shipping volumes, regulatory restriction on dual-use component exports, or technological breakthrough in optical inter-satellite links would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Europe Space Electronics Market
Space
Mexico Space Electronics Market
Space
Space-Based C4ISR Market
Space
Private Space Travel Market
Space
India Aviation, Defense, and Space Market
Space
Spacecraft Market
Space
Astronaut Spacesuit Market
Space
Space Propulsion Systems Market
Space
Germany Space Electronics Market
Space
Spain Space Electronics Market
Space
Africa Space Propulsion System Market
Space
Space-Based Smart Sensors Market
Space
North America Spacesuit Market
Space
Space Service Market
Space
Africa Space Electronics Market
Space
Space on Board Computing Platform Market