
 Spain Space Electronics Market | 2026-2036
Spain Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Space Electronics Market Insights
Spanish Earth observation programs are recalibrating component sourcing toward radiation-tolerant electronics. Airbus Defense and Space leverages its Madrid manufacturing footprint to anchor domestic procurement chains for satellite payloads. BAE Systems plc competes through specialized radiation-hardening capabilities that sustain long-duration mission reliability. Honeywell International Inc. dominates avionics-grade sensor integration for launch vehicle applications.
Space electronics encompass semiconductor and electromechanical systems engineered to withstand ionizing radiation, extreme thermal cycling, and vacuum conditions, typically fabricated on silicon-on-insulator substrates or using triple-modular redundancy architectures to ensure operational integrity in orbital environments. FPGA technology leads deployment in reconfigurable satellite payloads where post-launch software updates extend mission utility. Radiation-hardened ASICs command concentrated margin pools in deep-space probe applications where component failure carries irrecoverable mission cost. Ground station RF modules represent a maturing segment with stable replacement demand across Spain's existing satellite communication infrastructure.
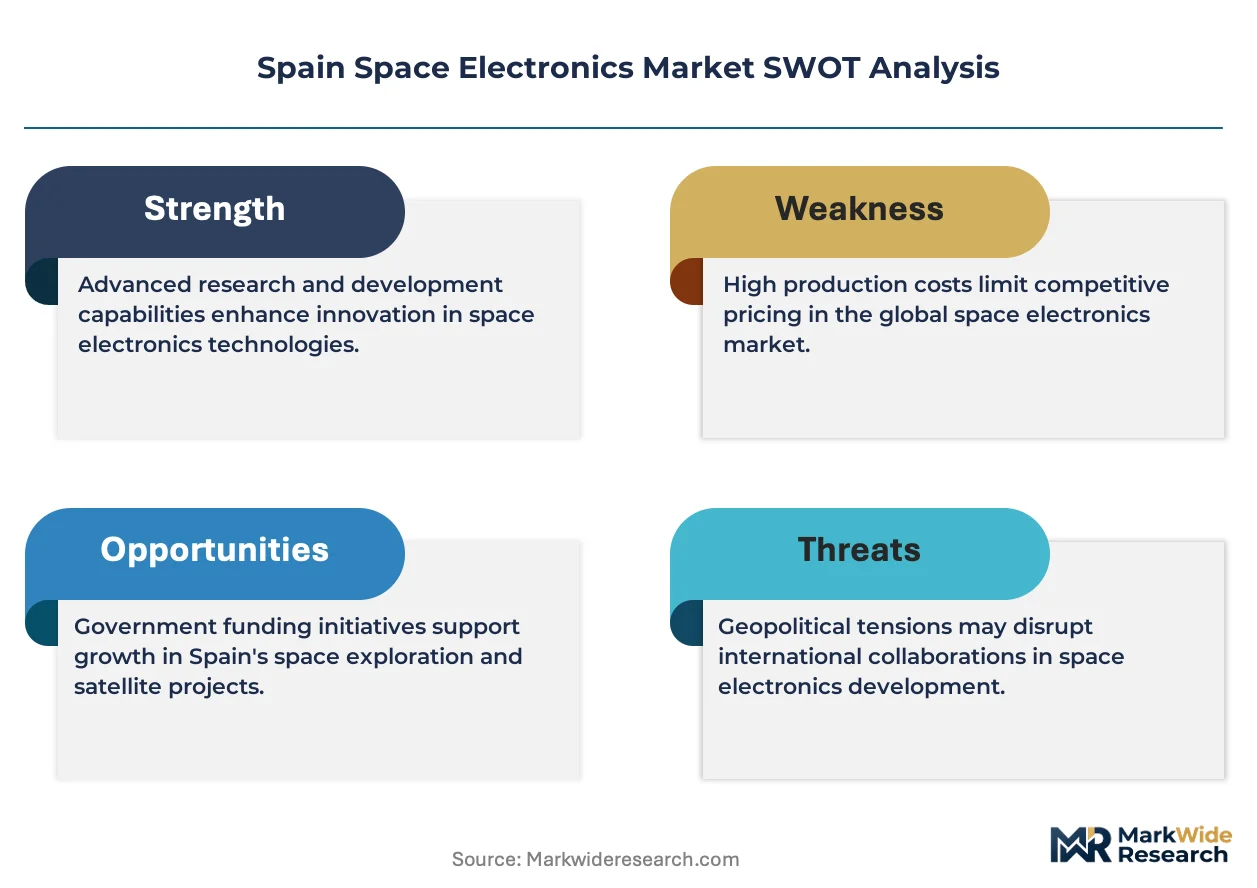
Spain's national space strategy aligns with ESA procurement standards and CDTI technology certification requirements, creating dual compliance layers for domestic suppliers. REACH chemical restrictions and EU Green Deal material sourcing rules are reshaping semiconductor fabrication supply chains accessible to Spanish manufacturers. Stakeholders must monitor ESA's evolving component qualification timelines against Spain's planned small satellite constellation deployments.
Market Dynamics
Spain's space electronics sector is recalibrating around ESA's component qualification timelines and CDTI technology certification requirements, which compress supplier readiness windows ahead of planned small satellite constellation deployments.
Growth Catalysts
- ESA Funding Directives:European Space Agency procurement standards mandate radiation-hardened component sourcing, pulling Spanish manufacturers into qualified supply chains for satellite payloads.
- Madrid Aerospace Corridor:Concentrated design-to-manufacture infrastructure enables rapid prototyping of radiation-tolerant electronics for domestic satellite programs.
- FPGA Technology:Reconfigurable payload architectures allow post-launch software updates, extending mission utility and creating recurring component refresh cycles.
Market Restraints
- Radiation-Hardened ASIC Costs:Deep-space probe applications require triple-modular redundancy architectures that multiply fabrication expenses versus commercial-grade alternatives.
- Silicon-on-Insulator Supply Concentration:Specialized substrate fabrication concentrates among a limited supplier base, creating input bottlenecks for Spanish semiconductor foundries.
- REACH Chemical Restrictions:EU Green Deal material sourcing rules limit available fabrication chemistries, extending qualification timelines for new component introductions.
Strategic Opportunities
- Barcelona Satellite Electronics Cluster:Underutilized RF module production capacity can pivot toward emerging small satellite ground station infrastructure.
- Earth Observation Programs:Spain's national space strategy prioritizes domestic component sourcing for optical and radar payload electronics.
- Dual-Use Technology Convergence:Defense and civil space electronics specifications are converging, enabling single qualification pathways for dual-market suppliers.
Industry Challenges
- Radiation Effects Engineering Talent:Specialized expertise in single-event upset mitigation and total ionizing dose modeling remains concentrated among a limited workforce pool.
- CDTI Certification Timelines:Component qualification against Spain's national technology certification requirements extends development cycles by 18-24 months.
- Legacy System Integration:New radiation-hardened electronics must interface with existing satellite bus architectures designed around obsolete component specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Space Electronics Market |
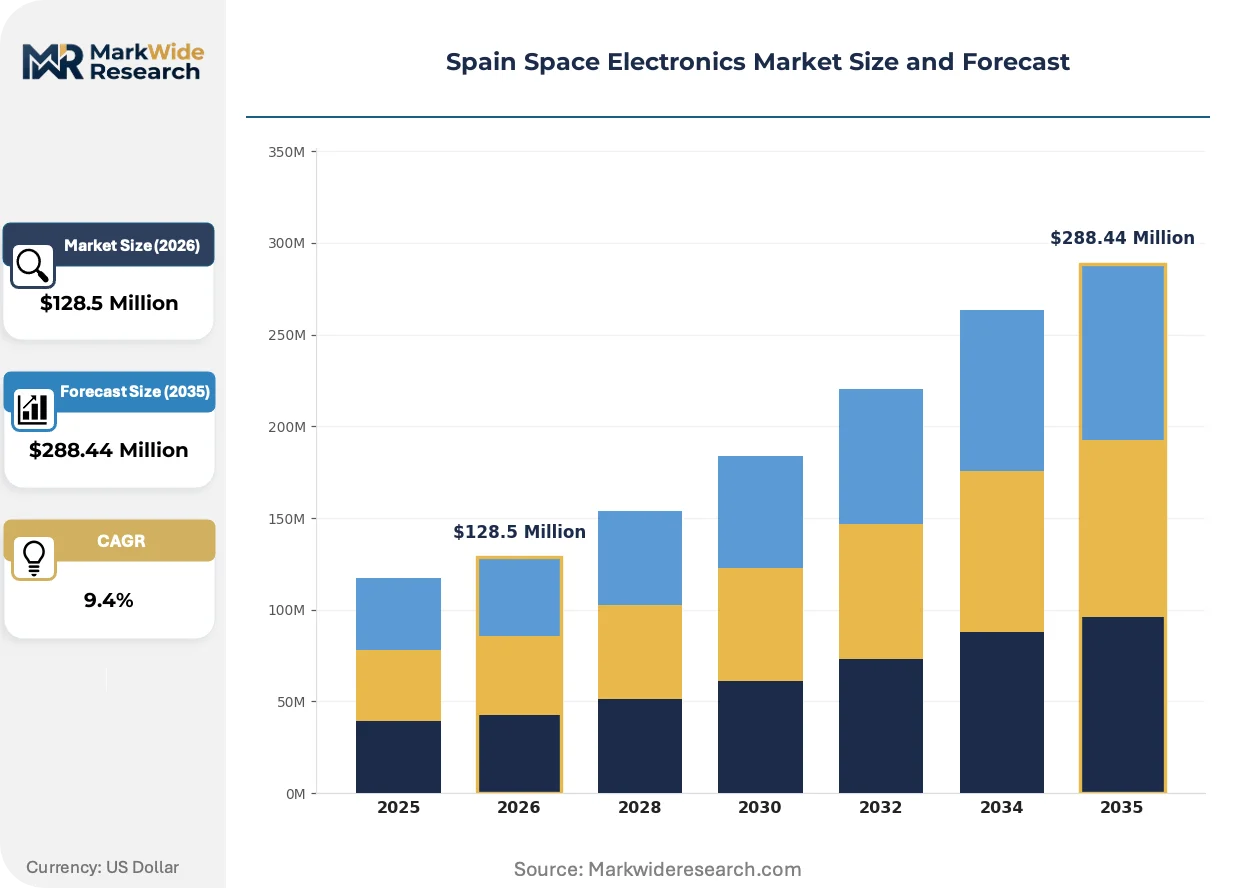
| Market Size in 2026 | $128.5 Million |
| Market Size in 2035 | $288.44 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Power Amplifiers, RF Modules, Sensors Technology: FPGA, ASIC, Radiation-Hardened, Analog Components Application: Satellite Systems, Space Probes, Launch Vehicles, Ground Stations End User: Aerospace Manufacturers, Research Institutions, Government Agencies, Private Corporations |
| Companies Covered | STMicroelectronics N.V., Texas Instruments Inc., Honeywell International Inc., BAE Systems plc, Airbus Defense and Space, Eaton Corporation PLC, Microchip Technology Incorporated, Teledyne Technologies Inc., Renesas Electronics Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Space Electronics Market Trends and Innovations
Spanish space electronics manufacturing is absorbing three concurrent pressures: radiation-hardening technology migration, regulatory compliance layering, and procurement model restructuring toward domestic anchor tenants.
Silicon-on-insulator substrates with specialized epitaxial layers are absorbing the primary radiation-hardening burden for reconfigurable satellite payloads. Airbus Defense and Space's Madrid manufacturing footprint is adopting these substrates at accelerated pace for next-generation Earth observation platforms. The technology is absorbing margin pressure from commercial-off-the-shelf alternatives by enabling longer mission durations without component replacement.
EU Green Deal material sourcing rules are reshaping semiconductor fabrication supply chains accessible to Spanish manufacturers. REACH chemical restrictions now prohibit several legacy etching compounds, forcing reformulation of radiation-hardening processes. Ground station RF module producers in Barcelona are responding fastest, having requalified alternative chemistries ahead of satellite payload suppliers.
Domestic anchor tenancy is displacing pan-European procurement for Spanish space programs. CDTI certification requirements now weight domestic supplier location in technology readiness assessments, compressing foreign component share in qualified bids. Madrid's aerospace corridor is capturing the bulk of this restructured demand, with Barcelona satellite electronics clusters following at narrower scale.
Spain Space Electronics Market Segmentation
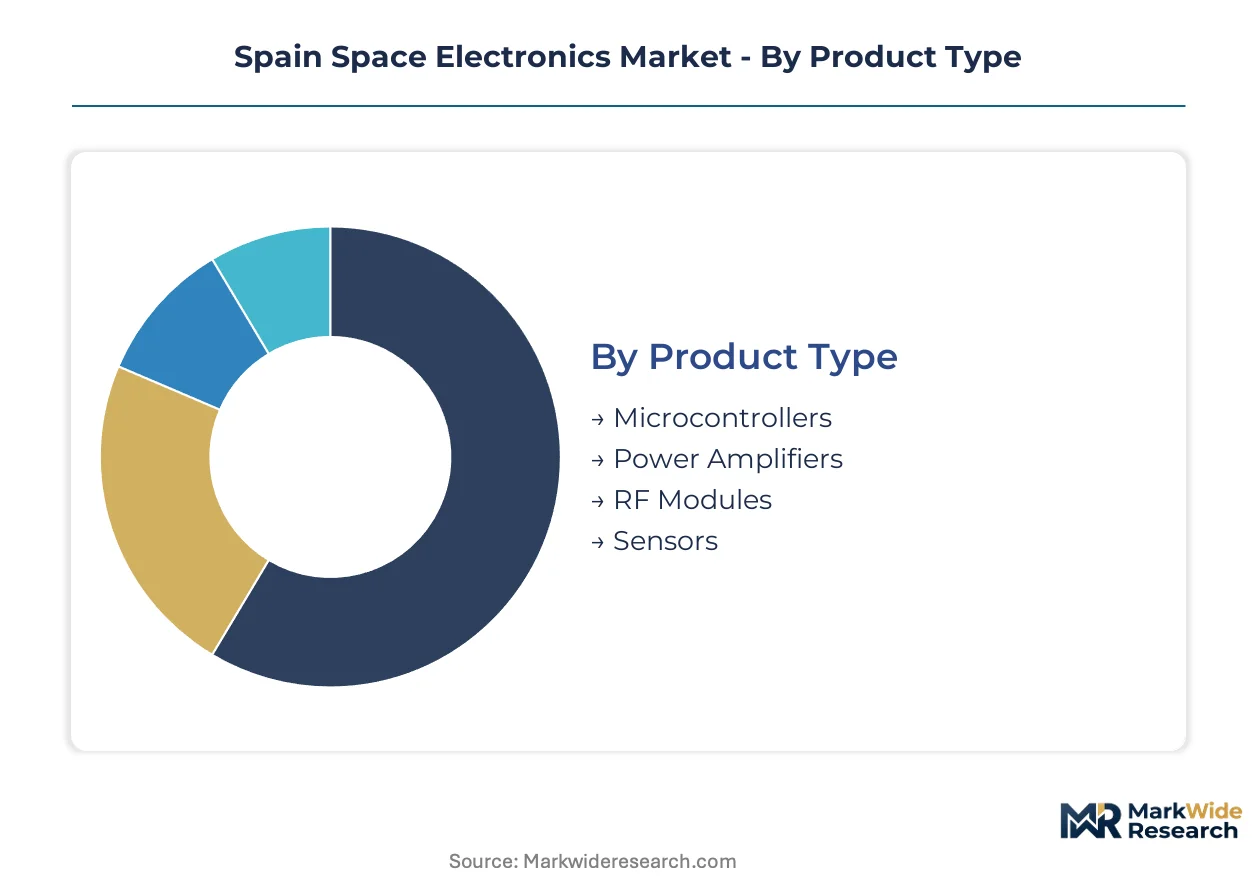
Segmentation in Spain's space electronics market exposes procurement friction points where ESA qualification requirements collide with CDTI certification timelines. Buyers prioritize radiation tolerance specifications over unit cost in deep-space applications while ground station deployments tolerate commercial-grade alternatives.
Product Type:
Procurement decisions pivot on mission-criticality tiers, with radiation tolerance specifications driving supplier selection more than per-unit pricing.
- Microcontrollers:Central processing units fabricated on silicon-on-insulator substrates with triple-modular redundancy architectures. Demand concentrates in Madrid's aerospace corridor for Earth observation satellite buses where ESA mandates extended operational lifecycles.
- Power Amplifiers:High-efficiency RF amplification stages engineered for thermal vacuum environments with minimal power degradation. Barcelona's satellite electronics cluster anchors procurement for small satellite constellations where CDTI certification timelines compress supplier readiness windows.
- RF Modules:Integrated transceiver assemblies for telemetry and command links.
- Sensors:Avionics-grade measurement devices for attitude determination and orbital positioning.
Volume sits with Microcontrollers; growth tilts toward Power Amplifiers.
Technology:
Technology selection traces mission duration requirements, with reconfigurability premiums justifying FPGA deployment despite higher unit costs.
- FPGA:Field-programmable gate arrays enabling post-launch payload reconfiguration through software updates. Spain's national space strategy prioritizes these for Earth observation programs where mission utility extension justifies qualification expense.
- Radiation-Hardened:Components with specialized epitaxial layers and error-correction architectures for total ionizing dose environments. Madrid manufacturers absorb concentrated demand from deep-space probe applications where component failure carries irrecoverable mission cost.
- ASIC:Application-specific integrated circuits for fixed-function high-volume deployments.
- Analog Components:Discrete signal conditioning and power management devices.
Deployment tilts toward Radiation-Hardened for deep-space missions; FPGA climbs fastest for reconfigurable payloads.
Application:
Application segmentation reveals divergent qualification burdens, with orbital hardware facing stricter ESA component standards than ground infrastructure.
- Satellite Systems:Bus and payload electronics for orbital platforms spanning LEO to GEO altitudes. Airbus Defense and Space's Madrid manufacturing footprint anchors domestic procurement chains with CDTI-weighted supplier assessments.
- Ground Stations:RF infrastructure and control systems for telemetry, tracking, and command operations. Barcelona clusters capture replacement demand across Spain's existing satellite communication infrastructure with REACH-compliant chemistries already requalified.
- Space Probes:Deep-space electronics for interplanetary missions.
- Launch Vehicles:Avionics systems for ascent and stage separation sequences.
Revenue concentrates in Satellite Systems; expansion steepest in Ground Stations.
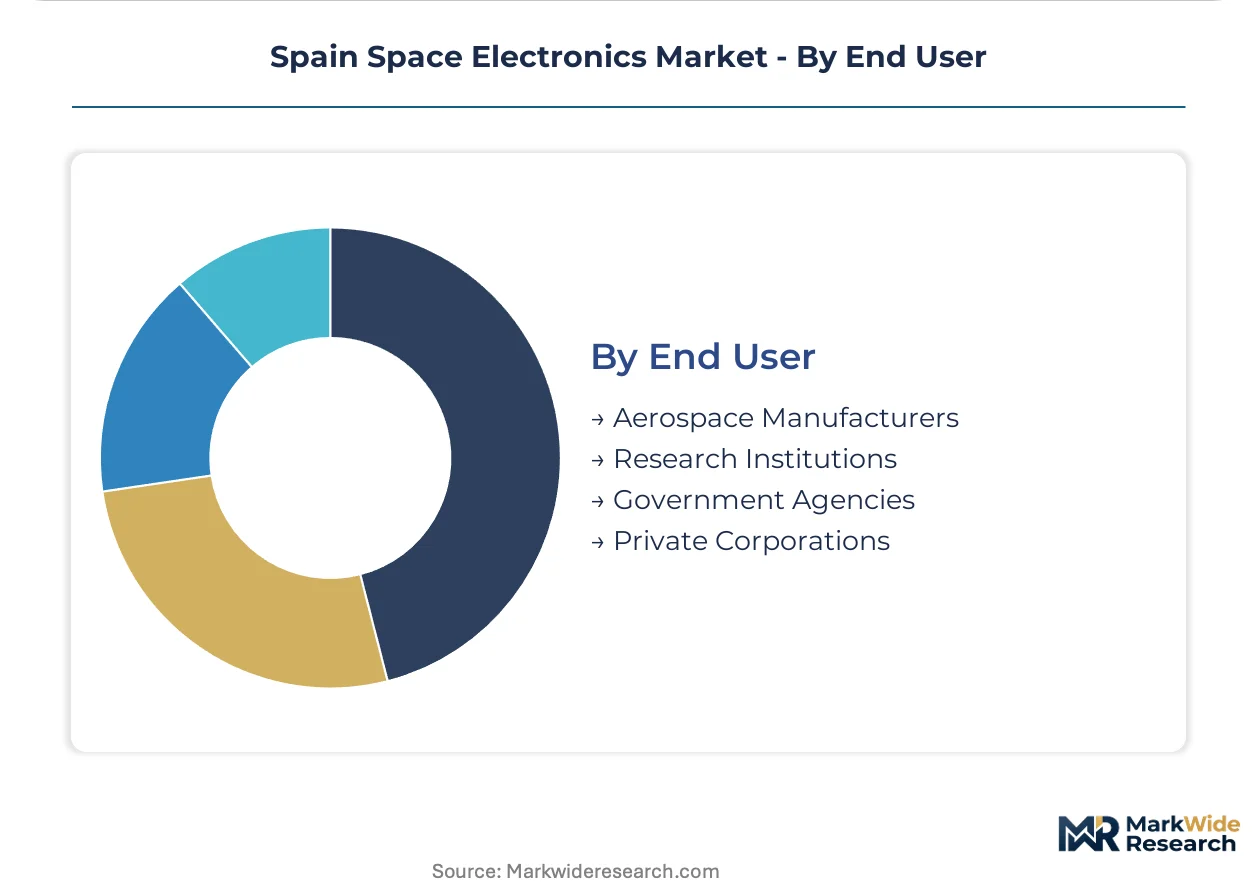
End User:
End-user structure reflects procurement authority concentration, with government-funded programs dictating qualification standards that cascade to private suppliers.
- Government Agencies:National space programs administered through CDTI with ESA-aligned procurement standards. These entities mandate domestic supplier location weighting in technology readiness assessments, compressing foreign component share.
- Aerospace Manufacturers:Prime contractors integrating qualified subsystems for satellite and launch vehicle platforms. Madrid's aerospace corridor enables rapid prototyping partnerships with CDTI-certified component suppliers.
- Research Institutions:University and laboratory programs for technology demonstration missions.
- Private Corporations:Commercial satellite operators and emerging space ventures.
Procurement volume centers on Government Agencies; commercial momentum builds fastest among Private Corporations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's aerospace special economic zones concentrate design-to-manufacture infrastructure around Madrid and Barcelona. CDTI technology certification requirements and ESA procurement standards create dual compliance layers that reshape regional supplier networks.
Madrid
Earth observation satellite buses drive microcontroller demand through Airbus Defense and Space's manufacturing footprint. ESA funding directives mandate radiation-hardened component sourcing for extended operational lifecycles. The Madrid aerospace corridor enables rapid prototyping partnerships with CDTI-certified suppliers.
Catalonia
Small satellite constellations compress supplier readiness windows for power amplifier procurement. REACH chemical restrictions force reformulation of radiation-hardening processes for RF module producers. Barcelona's satellite electronics cluster has requalified alternative chemistries ahead of payload suppliers.
Basque Country
Ground station infrastructure generates stable replacement demand for telemetry and command systems. EU Green Deal material sourcing rules limit available fabrication chemistries for semiconductor foundries. Bilbao's industrial electronics sector pivots toward satellite communication hardware with domestic anchor tenancy weighting.
Andalusia
Research institutions coordinate technology demonstration missions through university-laboratory partnerships. Spain's national space strategy prioritizes domestic component sourcing for optical payload electronics. Seville's aerospace research cluster absorbs CDTI-weighted supplier assessments for qualification pathways.
Valencia
Launch vehicle avionics systems require avionics-grade sensor integration for ascent sequences. Dual-use technology convergence enables single qualification pathways for defense and civil applications. Valencia's precision manufacturing corridor supplies electromechanical systems for thermal vacuum environments.
Spain Space Electronics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with radiation-hardening capabilities concentrating margin in deep-space applications while commercial-grade alternatives serve ground infrastructure. The vendor base organizes around three strategic archetypes: integrated prime contractors with captive electronics divisions, specialized radiation-effects engineering houses, and commercial semiconductor suppliers with space-qualified product lines. M&A activity targets single-event upset mitigation expertise, while capacity expansion concentrates in silicon-on-insulator substrate fabrication.
Among European-anchored prime contractors, Airbus Defense and Space exemplifies the integrated archetype through Madrid-based manufacturing. BAE Systems plc occupies a position within the specialized radiation-hardening tier. Honeywell International Inc. represents the diversified industrial conglomerate model with avionics-grade sensor capabilities. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| STMicroelectronics N.V. |
| Texas Instruments Inc. |
| Honeywell International Inc. |
| BAE Systems plc |
| Airbus Defense and Space |
| Eaton Corporation PLC |
| Microchip Technology Incorporated |
| Teledyne Technologies Inc. |
| Renesas Electronics Corporation |
| Others |
Pricing and Supply Chain Analysis
ESA-mandated radiation-hardening specifications are compressing supplier qualification timelines and forcing Spanish manufacturers to absorb premium input costs for silicon-on-insulator substrates. CDTI certification requirements add parallel compliance layers that extend development cycles and concentrate pricing power among qualified foundries.
Pricing Analysis
Short-lead-time premiums dominate procurement negotiations as small satellite constellation deployments accelerate supplier readiness windows. Three-tier pricing structure across radiation-hardened, radiation-tolerant, and commercial-grade levels separates mission-critical deep-space applications from ground station infrastructure. Cost compression in commercial-grade tiers is intensifying because REACH-compliant chemistry reformulation has raised fabrication overhead. Government agencies exhibit lowest price sensitivity due to ESA funding directives, while private corporations face tightening procurement budgets.
Supply Chain Analysis
Silicon-on-insulator substrate supply rests on Japanese and German specialty foundries with limited qualified capacity for space-grade epitaxial layers. Spanish semiconductor fabricators draw from French photoresist suppliers and Dutch lithography equipment providers for radiation-hardening process steps. Single-source vulnerability concentrates in triple-modular redundancy architecture components where qualified alternatives remain scarce. Distribution runs through Madrid's aerospace corridor for satellite payload integration and Barcelona's electronics cluster for ground station RF modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's space electronics sector sits in a technology-transition phase as FPGA-based reconfigurable payloads displace fixed-function ASIC architectures for Earth observation programs.
For Market Incumbents: Hedge against silicon-on-insulator supply concentration by cultivating dual-source relationships with Japanese and German substrate foundries. Invest in CDTI certification pre-qualification for next-generation radiation-tolerant microcontrollers to defend against emerging Spanish fabless competitors targeting small satellite constellations. For New Entrants and Emerging Players: Enter via Barcelona's underutilized RF module production capacity, pivoting toward small satellite ground station infrastructure where REACH-compliant chemistries are already requalified. Target power amplifier procurement for LEO constellations, leveraging existing cleanroom assets and compressed CDTI timelines versus Madrid's saturated aerospace corridor. For Investors and Strategic Acquirers: The window for entry favors specialized radiation-effects engineering houses with single-event upset mitigation expertise. Long-term viability hinges on ESA's evolving component qualification timelines against Spain's planned constellation deployments. Watch CDTI's domestic supplier weighting criteria as the inflection signal for foreign component share compression.| Strategic Initiative | Industry Significance |
|---|---|
| Radiation-Effects Engineering Acquisition | Single-event upset mitigation expertise commands scarcity premiums in deep-space probe applications. |
| Silicon-on-Insulator Capacity Partnership | Japanese substrate foundry relationships secure qualified supply for Madrid's Earth observation satellite programs. |
| CDTI Certification Fast-Track Investment | Accelerated qualification pathways capture small satellite constellation procurement before foreign competitors adapt. |
| Dual-Use Technology Convergence Program | Defense and civil specification alignment enables single qualification for Madrid and Valencia aerospace corridors. |
| REACH-Compliant Chemistry Reformulation | Alternative etching compound qualification ahead of payload suppliers secures Barcelona RF module positioning. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with satellite program managers, radiation-effects engineers, CDTI certification officers, and semiconductor procurement leads at Madrid aerospace manufacturers combined with ESA component qualification databases, CDTI technology readiness assessments, and Spanish customs import records for specialized substrates. Bottom-up demand modeling and top-down supply validation triangulated market estimates.
Segmentation granularity operated at product type, technology architecture, application tier, and end-user procurement authority levels across the projection horizon. CAGRs derived from fitted growth curves applied to ESA funding trajectories, CDTI certification pipeline data, and small satellite constellation deployment schedules. Modeled dimensions included radiation tolerance grade, reconfigurability requirement, orbital altitude class, and domestic supplier weighting eligibility.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ESA procurement standard revisions or REACH chemical restriction expansions. Forecasts reflect assumptions about qualification timeline stability and substrate supply continuity. ESA funding directive shifts, CDTI domestic weighting criteria changes, and silicon-on-insulator foundry capacity constraints warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
China Space Electronics Market
Space
Asia-Pacific Space Electronics Market
Space
Space-Based C4ISR Market
Space
Asia-Pacific Space Logistics Market
Space
France Space Electronics Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
Space Debris Monitoring and Removal Market
Space
Space Launch Services Market
Space
Space Robots Market
Space
Space in Orbit Refueling Market
Space
Space Ground System Market
Space
China Space Propulsion System Market
Space
Europe Space Logistics Market
Space
Space As a Service Market
Space
Space Tourism Market
Space
Japan Space Electronics Market