
 Data Center Interconnect Market | 2026-2036
Data Center Interconnect Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Interconnect Market Intelligence
Market Context
OpenZR+ certification is rotating vendor eligibility for metro and regional data center interconnect deployments, filtering participants by coherent DSP interoperability and power envelope compliance. Nokia leverages its Bell Labs silicon photonics program to sustain leadership in 400G and 800G coherent transport systems. Arista Networks anchors its position through merchant silicon-based switching platforms optimized for cloud-scale leaf-spine architectures. Ciena Corporation differentiates via its WaveLogic coherent modem portfolio and programmable optical layer control.
Technical Definition and Segment Structure
Data center interconnect comprises the optical, electronic, and software systems that transport traffic between geographically separated computing facilities at rates from 100 Gbps to multiple terabits per second using coherent modulation, forward error correction, and software-defined provisioning. Its primary purpose is to extend Layer 2 and Layer 3 network domains across metro, regional, and intercontinental distances while maintaining latency, jitter, and availability service levels. Optical fiber technology dominates capital deployment due to the insatiable bandwidth requirements of machine learning training clusters, while cloud service providers represent the fastest-growing end user segment as they stitch together multi-region availability zones. Managed services command premium pricing from enterprises lacking internal optical engineering expertise, whereas professional services margins concentrate in complex submarine and terrestrial route planning engagements.
Regulatory Framework and Outlook
The FCC governs spectrum allocation and fiber infrastructure access in the United States, while the EU AI Act and GDPR impose data sovereignty requirements that mandate domestic or regional interconnection paths for sensitive workloads. China's MIIT enforces GB standards for optical transmission equipment and cross-border data flow restrictions that localize interconnect demand. Stakeholders must monitor evolving national security review frameworks for submarine cable landing licenses and spectrum auctions that could abruptly reshape viable routes between major data center clusters.
Market Dynamics
OpenZR+ coherent pluggable optics are compressing deployment timelines and collapsing traditional optical transport hierarchies, forcing incumbents to recalibrate their metro and regional portfolio strategies around interoperability certification rather than proprietary chassis lock-in.
Growth Catalysts
- Cloud Campus Buildouts:Hyperscale operators in the United States, China, and Germany are stitching together distributed availability zones with 400G and 800G fiber pairs to support machine learning training clusters.
- EU AI Act Data Sovereignty Mandates:Cross-border traffic restrictions are forcing European enterprises to establish domestic interconnection paths, creating localized demand for managed optical services.
- Coherent DSP Interoperability:OpenZR+ certification programs are standardizing pluggable optics across multiple vendor ecosystems, reducing procurement friction for multi-source network architectures.
Market Restraints
- Indium Phosphide Supply Concentration:Coherent optical engine production depends on a narrow supplier base concentrated in East Asian foundries, exposing procurement to geopolitical disruption.
- Submarine Cable Licensing Delays:FCC and national security review frameworks for transoceanic fiber landing permits are extending route activation timelines by 18-36 months.
- Power Envelope Limitations:Pluggable 800G ZR+ modules are approaching thermal dissipation thresholds in legacy data center environments, constraining deployment flexibility.
Strategic Opportunities
- India Data Center Corridor Expansion:Mumbai-Chennai-Hyderabad fiber routes remain underprovisioned relative to projected cloud capacity additions through 2030.
- AI Training Cluster Interconnection:GPU-intensive workloads are creating demand for ultra-low-latency dark fiber between geographically separated compute pools.
- China MIIT Localization Incentives:Domestic optical equipment procurement preferences under GB standards are creating captive demand for locally certified interconnect solutions.
Industry Challenges
- Coherent Optical Engineering Talent Scarcity:DSP algorithm design and silicon photonics integration expertise concentrates within a handful of research institutions and incumbent vendors.
- Multi-Vendor Interoperability Certification:OpenZR+ compliance testing requires sustained investment in reference platforms and testbed infrastructure.
- Legacy ROADM Integration Complexity:Brownfield deployments must reconcile flexible-grid coherent signals with fixed-filter optical add-drop architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Interconnect Market |
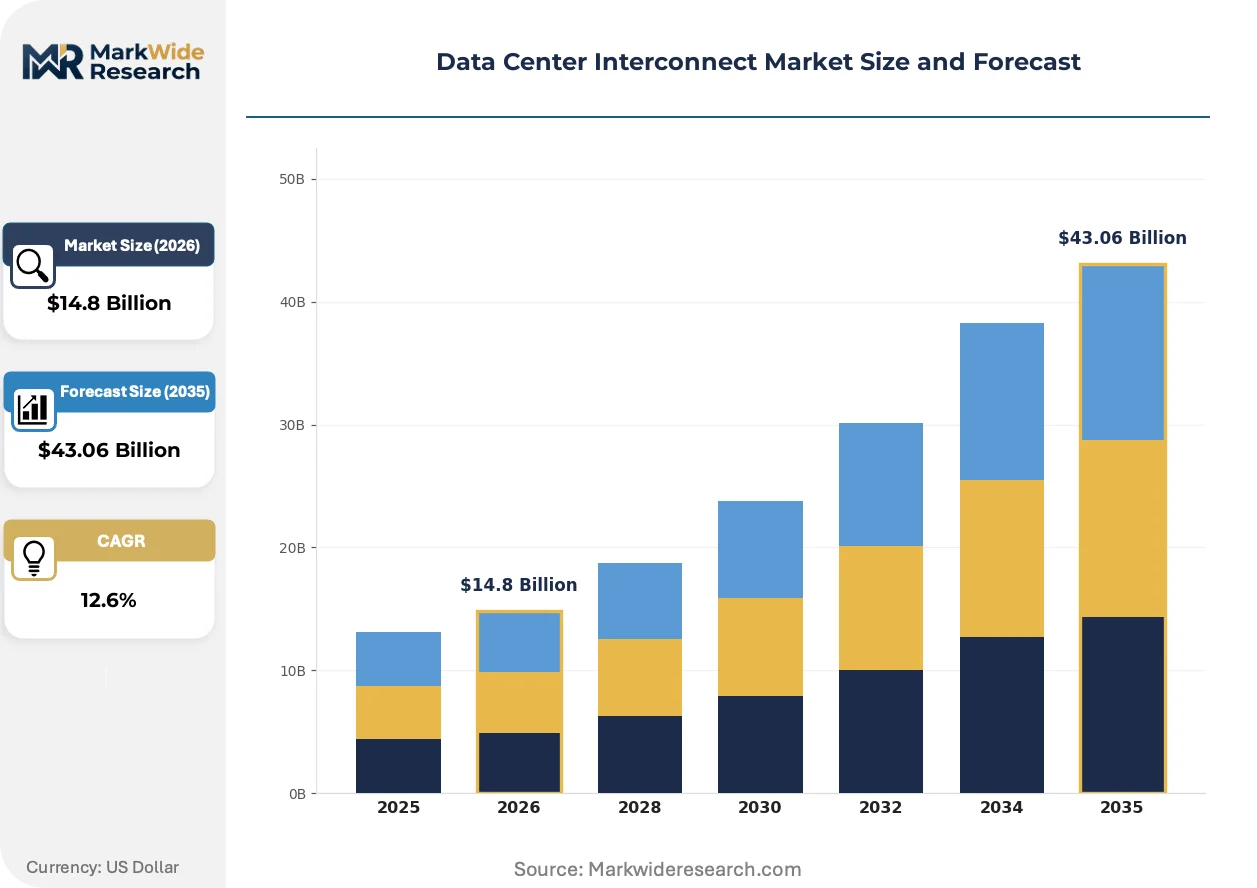
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $43.06 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Optical Fiber, Ethernet, MPLS, DWDM Service Type: Managed Service, Professional Service, Data Transfer Service, Network Management Service End User: Telecommunication Providers, Cloud Service Providers, Enterprises, Colocation Providers Installation: On-Premises, Off-Premises, Hybrid, Cloud-Based |
| Companies Covered | Nokia, Arista Networks, Ciena Corporation, ADVA Optical Networking, Infinera Corporation, Cisco Systems, Juniper Networks, Equinix, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Interconnect Market Strategic Shifts & Innovations
Silicon photonics integration and software-defined optical control are converging to collapse the traditional boundary between packet switching and coherent transport, compressing network layers and redefining vendor competitive boundaries.
Linear-drive pluggable optics (LPO) are supplanting traditional retimed transceiver architectures in intra-campus and metro reach applications. Cloud operators with internal optical engineering teams are accelerating LPO qualification timelines to reduce power per bit and eliminate digital signal processor overhead. This transition is compressing margins for established coherent modem suppliers while creating entry points for merchant silicon photonics foundries.
The EU AI Act and GDPR data localization requirements are mandating domestic routing for sensitive AI training workloads across European member states. Enterprises serving regulated industries must now provision dedicated interconnect paths that never traverse third-country territories, complicating submarine cable utilization patterns. German and French cloud providers are responding by accelerating terrestrial fiber builds between domestic availability zones.
Consumption patterns among hyperscale buyers are fragmenting procurement authority from centralized network architecture teams to individual service line engineering groups. This organizational shift is displacing traditional multi-year framework agreements with spot-market purchasing for specific route segments. The United States market exhibits the most pronounced decentralization, with individual cloud regions operating semi-autonomous capacity planning functions.
Data Center Interconnect Market Segmentation
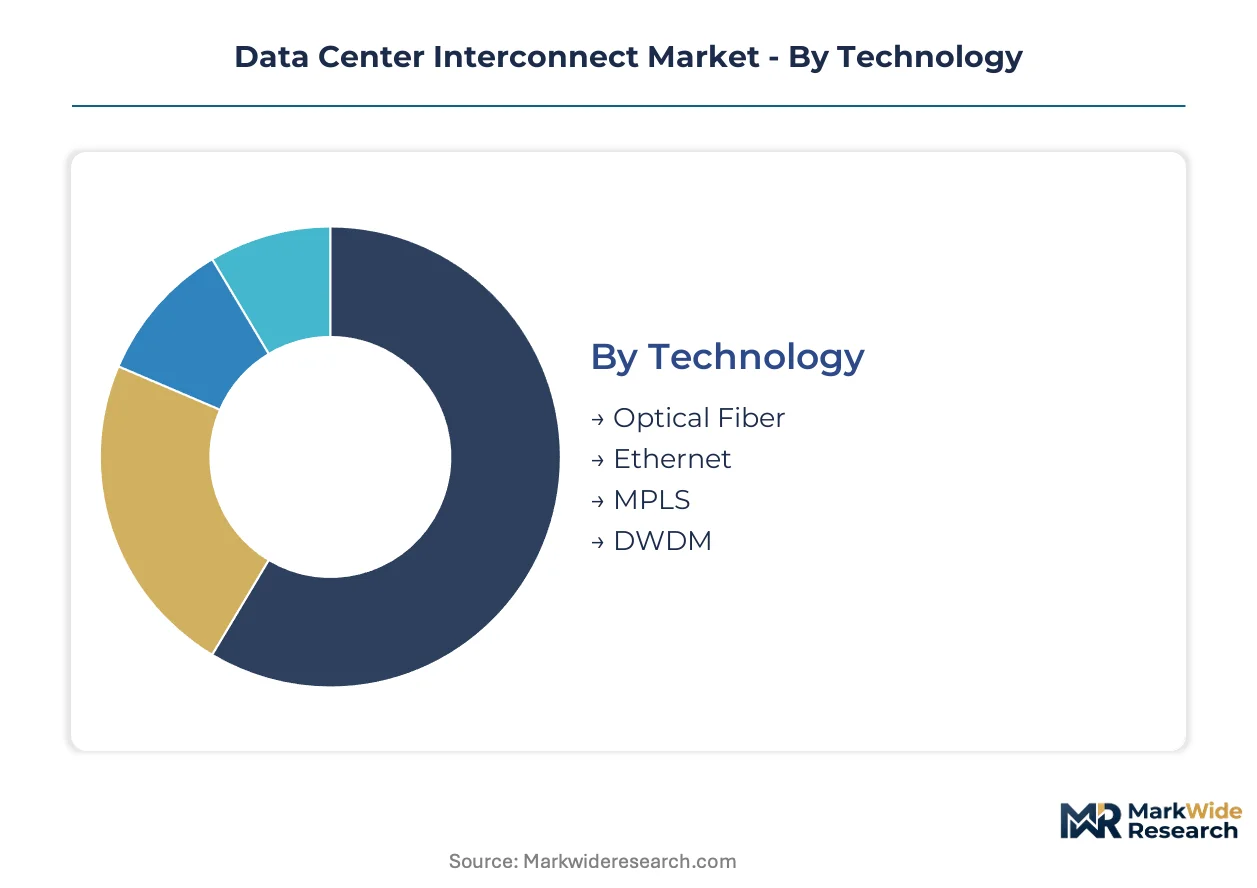
Segmentation in data center interconnect markets reveals how procurement authority fragments across technology layers and service models. Cloud operators, telecommunications carriers, and enterprises each impose distinct performance requirements that reshape vendor positioning and margin structures.
Technology:
Optical fiber deployments concentrate in domestic hyperscale campus expansions across the United States, Germany, and China, while Ethernet and MPLS solutions serve export-oriented enterprise interconnect needs spanning multiple regulatory jurisdictions.
- Optical Fiber:Coherent modulation systems using C-band and L-band spectrum deliver 400G to 800G per wavelength across metro, regional, and submarine distances. Demand clusters in United States hyperscale campuses and Chinese MIIT-certified domestic routes where machine learning training clusters require massive east-west bandwidth between availability zones.
- DWDM:Dense wavelength division multiplexing platforms maximize spectral efficiency across constrained fiber pairs through flexible-grid ROADM architectures and software-defined optical control planes. German and French cloud providers are accelerating terrestrial DWDM builds to satisfy EU AI Act data sovereignty mandates requiring domestic-only routing paths.
- Ethernet:Standardized Layer 2 interconnects using 100G, 400G, and 800G pluggable optics for shorter-reach campus and metro applications.
- MPLS:Label-switched transport providing traffic engineering and quality-of-service guarantees for enterprise multi-site VPN extensions.
Optical fiber holds the largest share; momentum sits with DWDM as coherent pluggable optics compress traditional transport hierarchies.
Service Type:
Cost tier differentiation separates premium managed optical services from commoditized data transfer offerings, with professional services commanding margin premiums in complex submarine and terrestrial route planning engagements.
- Managed Service:Third-party operation of optical transport infrastructure including 24/7 network operations center monitoring, performance reporting, and SLA-backed availability commitments. European enterprises lacking internal coherent optical engineering expertise are driving premium pricing for managed services under GDPR and EU AI Act compliance pressures.
- Professional Service:Route planning, fiber characterization, optical link engineering, and deployment project management for complex multi-vendor environments. United States hyperscale operators are displacing traditional multi-year framework agreements with spot-market purchasing for specific professional service engagements tied to individual cloud region buildouts.
- Data Transfer Service:Bulk data migration and synchronization across geographically separated facilities using scheduled optical capacity.
- Network Management Service:Software-defined provisioning, performance analytics, and automated fault correlation across multi-vendor optical layers.
Managed service captures the highest margin tier; professional service is expanding most quickly as OpenZR+ interoperability testing creates specialized engineering demand.
End User:
Customer type determines procurement scale and technical sophistication, with cloud service providers operating semi-autonomous regional capacity planning while enterprises depend on external optical expertise.
- Cloud Service Providers:Hyperscale operators stitching together distributed availability zones with 400G and 800G fiber pairs. United States market exhibits pronounced decentralization as individual cloud regions operate independent procurement functions, fragmenting traditional centralized network architecture authority.
- Telecommunication Providers:Incumbent carriers and competitive local exchange carriers offering wholesale optical transport to enterprise and cloud customers.
- Enterprises:Financial services, healthcare, and media companies requiring dedicated interconnect for disaster recovery and data sovereignty compliance.
- Colocation Providers:Multi-tenant data center operators offering cross-connect and inter-facility fiber services within metro clusters.
Cloud service providers hold the largest share; momentum sits with colocation providers as edge computing deployments multiply interconnection points.
Installation:
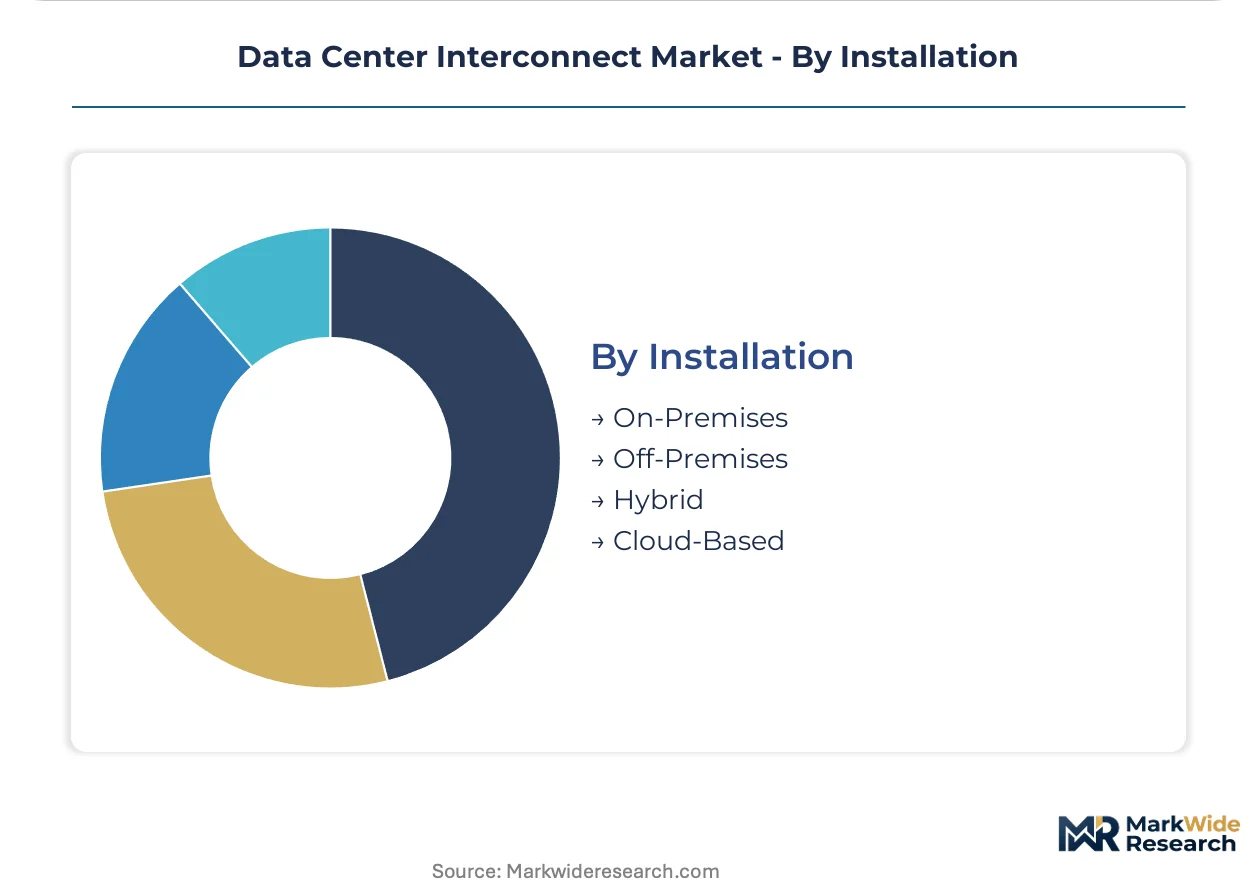
Maturity curves separate established on-premises optical transport from emerging cloud-based control plane deployments, with hybrid architectures dominating transitional enterprise environments.
- On-Premises:Customer-owned and operated optical transport equipment including coherent modems, amplifiers, and ROADM nodes deployed in private facilities. Chinese MIIT GB standards enforcement and domestic procurement preferences are creating captive demand for on-premises installations using locally certified equipment.
- Cloud-Based:Software-defined optical control and virtualized transport functions delivered as subscription services without physical infrastructure ownership.
- Off-Premises:Third-party data center and carrier hotel facilities housing customer equipment with cross-connect services.
- Hybrid:Mixed deployment combining on-premises active equipment with cloud-based management orchestration and analytics platforms.
On-premises installation holds the largest share; cloud-based deployment is gaining share fastest as software-defined optical control matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators in the United States, China, and Germany account for the densest interconnection demand, with machine learning training clusters and data sovereignty mandates reshaping fiber deployment patterns across metro and regional distances.
United States
Virginia's Loudoun County and Oregon's Hillsboro campus host the largest concentration of hyperscale availability zones, driving 400G and 800G fiber pair procurement. FCC spectrum auctions and submarine cable landing licenses govern transoceanic route activation timelines. Northern Virginia data center operators are expanding dark fiber contracts to link distributed GPU clusters for AI training workloads.
China
MIIT enforcement of GB standards for optical transmission equipment creates captive demand for domestically certified interconnect solutions. Cross-border data flow restrictions under cybersecurity law localize traffic routing within national boundaries. Beijing-Tianjin-Hebei and Yangtze River Delta clusters are adding terabit-scale fiber capacity between government-approved data center zones.
Germany
EU AI Act data sovereignty requirements and GDPR territorial restrictions mandate domestic-only routing paths for sensitive AI workloads. German cloud providers are accelerating terrestrial DWDM builds between Frankfurt, Berlin, and Munich availability zones. Bavaria and Hesse industrial corridors are seeing specialized fiber engineering for financial services latency requirements.
India
Mumbai-Chennai-Hyderabad fiber routes remain underprovisioned relative to projected cloud capacity additions through 2030. TRAI infrastructure sharing regulations and right-of-way policies influence terrestrial route economics. Maharashtra and Telangana state governments are fast-tracking data center park approvals with bundled fiber connectivity mandates.
Japan
METI digital infrastructure investment programs support domestic hyperscale campus expansion in Osaka and Tokyo metro areas. Submarine cable landings at Chikura and Maruyama create interconnection gateways for Asia-Pacific traffic exchange. Kanto and Kansai regions are deploying coherent pluggable optics for low-latency financial services interconnect.
Data Center Interconnect Market Key Industry Players
Player mix skews toward integrated optical transport specialists and merchant silicon-based switching vendors, with coherent DSP interoperability certification filtering participation. The vendor base separates into three strategic archetypes: Bell Labs-style research-driven integrated suppliers, merchant silicon platform builders, and programmable optical layer specialists. Dominant competitive moves include OpenZR+ interoperability testing investments and metro fiber route capacity pre-positioning.
Within the integrated optical transport tier, Nokia leverages silicon photonics research heritage while Ciena Corporation anchors coherent modem portfolio positioning. Arista Networks exemplifies the merchant silicon platform archetype optimized for cloud-scale architectures. These three companies represent the dominant competitive positioning vectors as OpenZR+ certification programs standardize procurement across multi-vendor environments.
| Leading Market Players |
|---|
| Nokia |
| Arista Networks |
| Ciena Corporation |
| ADVA Optical Networking |
| Infinera Corporation |
| Cisco Systems |
| Juniper Networks |
| Equinix |
| Huawei Technologies |
| Others |
Cost & Logistics Intelligence
OpenZR+ certification programs gate both vendor qualification and price differentiation simultaneously, creating tiered access where interoperable coherent DSP modules command premium positioning against proprietary alternatives while compressing margins for non-compliant suppliers.
Pricing Analysis
Cost-plus contracts with indium phosphide wafer price indexation dominate coherent optical engine procurement. Three-tier pricing structure across premium, standard, and economy levels separates OpenZR+ certified modules from merchant silicon alternatives and legacy proprietary systems. Price differentiation rests on DSP interoperability certification and power envelope compliance. Cost compression in 800G pluggable tiers is intensifying because cloud operators are consolidating procurement volumes around qualified multi-source suppliers. Hyperscale cloud service providers exhibit lowest price sensitivity due to total cost of ownership optimization, while regional enterprises lacking optical engineering expertise face highest budget constraints.
Supply Chain Analysis
Inventory lead times for coherent DSP chips extend substantially beyond standard optical component cycles due to foundry capacity constraints. Indium phosphide wafer fabrication concentrates in Taiwan, South Korea, and Japan, while silicon photonics packaging clusters in the United States, China, and Germany. Raw material dependencies include rare earth elements for optical amplifiers, specialized substrates for photonic integrated circuits, and high-purity gases for epitaxial growth. Single-source vulnerability around coherent DSP design houses creates concentrated supply risk. Distribution runs through direct vendor relationships with hyperscale operators and tier-one systems integrators serving enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where switching costs lock customers into certified optical transport ecosystems, with OpenZR+ interoperability investments creating regulatory entrenchment that sustains incumbent positioning.
For Market Incumbents: Compound certification advantages by accelerating silicon photonics integration investments and pre-positioning metro fiber route capacity in United States cloud campus corridors. Threat from merchant silicon platform builders displacing proprietary chassis architectures demands backward integration into coherent DSP design to preserve margin structure. Priority lever sits with OpenZR+ testbed infrastructure ownership that gates competitor market access.
For New Entrants and Emerging Players: Managed optical services for GDPR and EU AI Act compliance represent the most penetrable white-space where incumbents under-serve European enterprises lacking internal coherent engineering teams. India data center corridor expansion offers geographic entry point with underprovisioned Mumbai-Chennai-Hyderabad routes relative to projected cloud capacity. Go-to-market angle should emphasize spot-market professional service engagements displacing traditional multi-year framework agreements.
For Investors and Strategic Acquirers: EU AI Act data sovereignty mandates reshape the acquisition landscape by elevating terrestrial DWDM asset values and domestic-only routing capabilities. Long-term viability favors vertically integrated optical transport specialists with captive silicon photonics programs over merchant silicon assemblers. Acquisition target archetype combines coherent modem portfolio with programmable optical layer control. Signal to watch is submarine cable licensing velocity under FCC national security review frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| OpenZR+ Interoperability Certification | Gates vendor participation in hyperscale procurement and collapses proprietary transport hierarchies. |
| Silicon Photonics Integration | Reduces power per bit and compresses deployment timelines for 400G and 800G coherent modules. |
| Metro Fiber Route Pre-positioning | Captures cloud campus buildout demand in Northern Virginia, Hillsboro, and Frankfurt corridors. |
| Managed Service Capability Buildout | Captures GDPR and EU AI Act compliance premiums from European enterprises lacking optical expertise. |
| Coherent DSP Talent Acquisition | Addresses engineering scarcity in algorithm design and photonic integration disciplines. |
Research Approach
Cross-validation between hyperscaler capex disclosures and optical component vendor order backlogs anchors the qualitative findings across the data center interconnect landscape. Primary interviews with network architecture executives at cloud service providers, optical transport engineering directors at telecommunications carriers, procurement leads at colocation operators, and coherent DSP design specialists inform demand-side validation. Secondary sources include FCC spectrum auction records, MIIT GB standard filings, EU regulatory impact assessments, submarine cable landing license databases, and vendor SEC filings. Bottom-up route-level capacity planning models triangulate against top-down market sizing frameworks.
Sensitivity analysis around coherent pluggable optics adoption curves and cloud region buildout timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include technology layer, service type, end user category, and installation deployment mode, with geographic regulatory cluster as an additional industry-specific dimension. CAGRs derive from fitted growth curves against historical hyperscale infrastructure investment patterns. Industry-specific forecast inputs encompass GPU cluster interconnection bandwidth requirements and data sovereignty mandate implementation schedules.
Underlying assumptions cover OpenZR+ certification velocity, indium phosphide foundry capacity expansion, and submarine cable licensing throughput, with deviation risk concentrated in geopolitical disruption to East Asian optical component supply chains and abrupt shifts in national security review frameworks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Data Deduplication Tools Market
Data Center and Networking
Mobile Data Traffic Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Service Provider Router Market
Data Center and Networking
South Korea Data Center Networking Market
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
Australia Data Center Networking Market
Data Center and Networking
Dark Fiber Network Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Germany Data Center Networking Market
Data Center and Networking
Mobile Data Offload Market
Data Center and Networking
Brazil Data Center Networking Market
Data Center and Networking
Broadband Network Gateway Market
Data Center and Networking
Switzerland Data Center Networking Market