
 Global Data Center and Network Third-Party Hardware Maintenance Service Market | 2026-2036
Global Data Center and Network Third-Party Hardware Maintenance Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Center and Network Third-Party Hardware Maintenance Service Market Foresight
The direct sales channel from original equipment manufacturers is narrowing as enterprise buyers seek cost alternatives for post-warranty server and storage support. Park Place Technologies leverages its global parts logistics network to compete with manufacturer service contracts. Service Express anchors its position through specialized coverage for end-of-life Cisco and Dell hardware. Evernex differentiates via circular economy-certified refurbishment operations across North America and Europe.
Data center and network third-party hardware maintenance services encompass independent technical support, spare parts provisioning, and lifecycle extension for IT infrastructure outside manufacturer warranty terms, typically delivered through multi-vendor contracts with guaranteed response times measured in hours. The primary commercial purpose is reducing total cost of ownership by delaying capital refresh cycles while maintaining operational uptime commitments. Corrective maintenance commands the largest revenue share due to emergency break-fix demand, while predictive maintenance represents the fastest-expanding service type as AI-driven failure forecasting tools mature. Deployment across hyperscale data centers generates the highest contract values, though edge facilities are emerging as a concentrated growth vector for distributed maintenance networks.
The EPA's electronics sustainability guidelines and the EU Green Deal's circular economy action plan are shaping service standards by incentivizing parts reuse and refurbishment certification. ISO 14001 environmental management and ISO 9001 quality frameworks increasingly filter into procurement requirements for third-party maintenance contracts. Stakeholders must monitor how evolving right-to-repair legislation across multiple jurisdictions alters OEM lock-in strategies and parts availability.
Market Dynamics
Hyperscale operators are compressing hardware refresh cycles while simultaneously extending post-warranty support terms, creating structural tension between capital efficiency mandates and uptime reliability requirements.
Growth Catalysts
- EU Green Deal circular economy mandates:European facilities face binding refurbishment and reuse targets that OEM support models cannot satisfy, accelerating third-party service procurement.
- AI-driven predictive maintenance tools:Machine learning failure forecasting is maturing rapidly, enabling service providers to guarantee uptime commitments that rival manufacturer contracts at lower cost structures.
- United States hyperscale concentration:Cloud service firms operating massive domestic server fleets generate contract volumes sufficient to sustain specialized third-party logistics networks.
Market Restraints
- Spare parts supply concentration:Critical server and storage components remain captive to OEM-controlled distribution channels, limiting independent service provider procurement flexibility.
- Right-to-repair legislative fragmentation:Inconsistent repair access laws across US states and EU member countries create compliance complexity that favors incumbent manufacturer service architectures.
- Technical limitation in firmware access:Proprietary diagnostic tools and locked firmware updates restrict third-party technicians from performing complete system restoration on latest-generation hardware.
Strategic Opportunities
- India data center buildout:Domestic cloud infrastructure expansion under PLI scheme incentives is creating demand for post-warranty support before local OEM service networks mature.
- Edge computing facility networks:Distributed micro data centers in remote locations require maintenance models that centralized manufacturer dispatch cannot economically serve.
- ISO 14001 certification premium:Environmental management framework compliance is filtering into enterprise procurement requirements, rewarding certified refurbishment operators.
Industry Challenges
- Field engineering talent scarcity:Specialized skills in legacy Cisco, Dell, and HP hardware diagnostics are concentrating among aging technician cohorts with limited pipeline replenishment.
- Multi-vendor integration complexity:Enterprise contracts spanning heterogeneous server, storage, and networking estates require cross-platform expertise that training programs struggle to produce at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Center and Network Third-Party Hardware Maintenance Service Market |
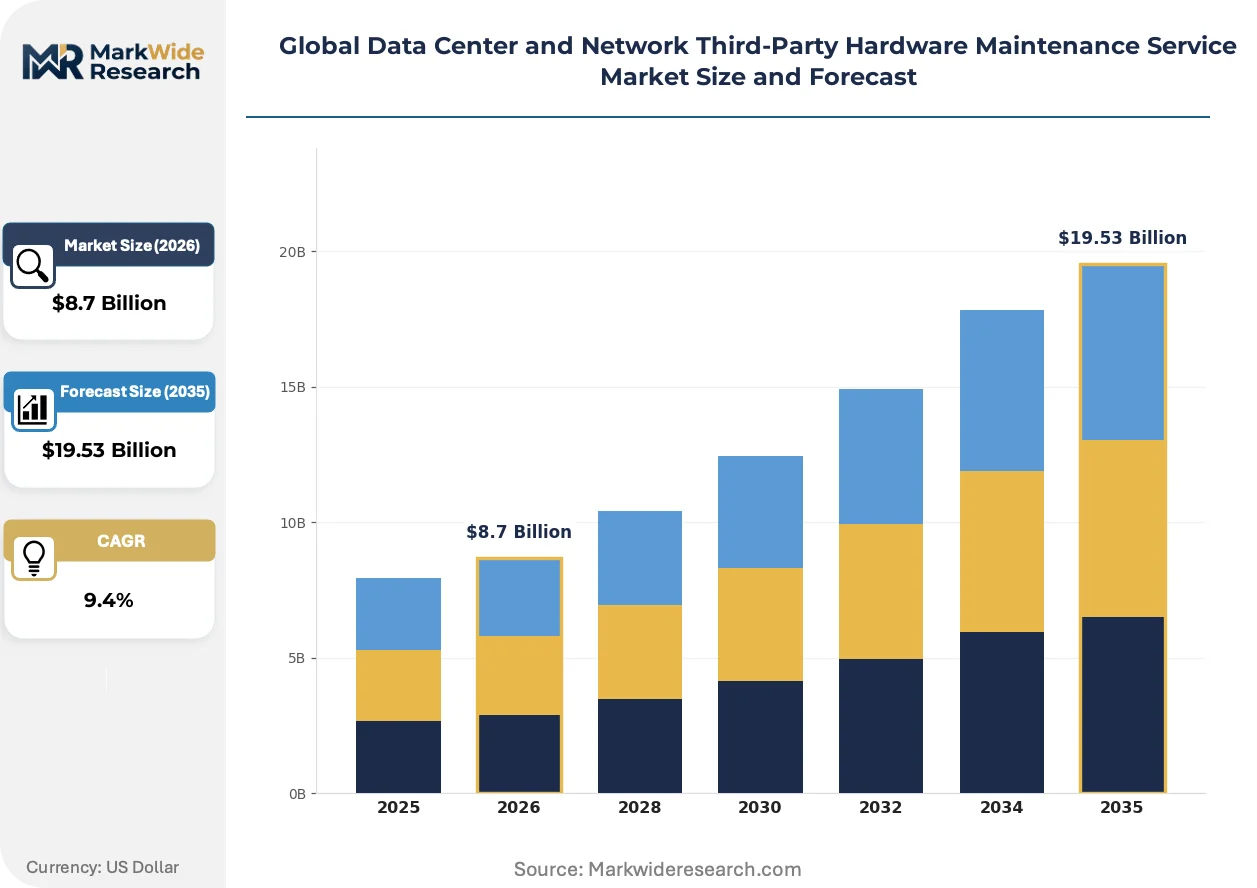
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corrective Maintenance, Preventive Maintenance, Predictive Maintenance, Remote Maintenance, Onsite Maintenance End User: Telecom Service Providers, Cloud Service Firms, Managed Service Providers, Colocation Providers, Content Delivery Networks Equipment Type: Servers, Routers, Switches, Storage Systems, Firewalls, Load Balancers Deployment Model: Private Data Centers, Hybrid Data Centers, Enterprise Networks, Hyperscale Data Centers, Edge Facilities |
| Companies Covered | Park Place Technologies, Service Express, Evernex, Curvature, CentricsIT, DataSpan, Cxtec, Reliant Technology, Atlantix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Center and Network Third-Party Hardware Maintenance Service Market Shifts & Advancements
Remote monitoring infrastructure is displacing physical dispatch models across the maintenance value chain, compressing response time guarantees while expanding geographic coverage without proportional headcount growth.
Digital twin technology is virtualizing physical server and network hardware environments, creating software replicas that simulate failure modes and test remediation protocols without production system disruption. Hyperscale operators in the United States are deploying these virtualized environments across multi-vendor estates to validate third-party technician procedures before field authorization. This virtualization is compressing training timelines and enabling service providers to certify remote technicians for complex corrective maintenance without historical hardware access requirements.
REACH substance restrictions and RoHS compliance updates are forcing component substitution across European refurbishment operations, eliminating certain solder formulations and capacitor chemistries from reuse pipelines. The industrial consequence is elevated testing overhead for circular economy-certified operators seeking to maintain ISO 14001 standing. German and French facilities are responding by consolidating pre-certification screening into centralized testing hubs rather than distributed depot models.
Enterprise sourcing departments are unbundling break-fix services from comprehensive maintenance contracts, creating discrete procurement categories for preventive monitoring, spare parts logistics, and emergency dispatch. This unbundling is fragmenting contract values while elevating price transparency pressures on service providers. The pattern is most visible among United States financial services and healthcare verticals where procurement functions have matured dedicated IT service category management functions.
Global Data Center and Network Third-Party Hardware Maintenance Service Market Segmentation
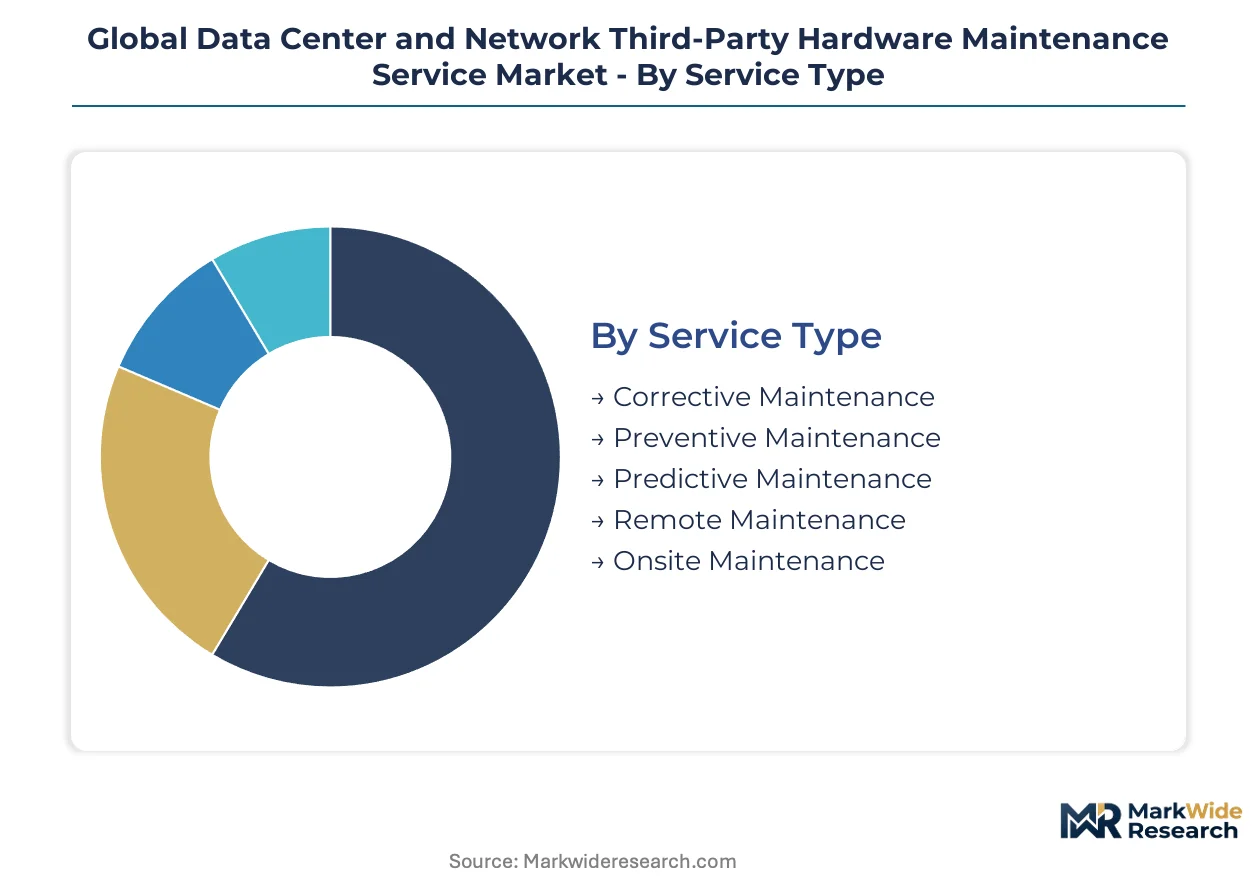
Third-party hardware maintenance contracts vary sharply in margin structure and renewal rates across service modalities and infrastructure scales. Procurement teams negotiate distinct SLA tiers based on equipment criticality and downtime tolerance, fragmenting what appears as a uniform service category into multiple price-performance bands.
Service Type:
After-sales-service intensity escalates from scheduled interventions to AI-augmented predictive regimes, with labor deployment and parts inventory requirements shifting dramatically across the spectrum.
- Corrective Maintenance:Emergency break-fix interventions triggered by hardware failures demand 24/7 dispatch availability and rapid parts logistics. Cloud service firms in the United States absorb the highest contract volumes here due to hyperscale uptime commitments and compressed response windows.
- Predictive Maintenance:Machine learning algorithms analyze telemetry streams to forecast component degradation before failure manifests. German and French facilities under EU Green Deal circular economy mandates are adopting these services fastest to optimize refurbishment timing and minimize unplanned downtime.
- Preventive Maintenance:Scheduled inspections and component replacements at fixed intervals reduce catastrophic failure probability.
- Remote Maintenance:Diagnostics and software remediation executed without physical technician presence.
- Onsite Maintenance:Hands-on hardware intervention requiring dispatched field engineering resources.
Corrective maintenance holds the largest share; momentum sits with predictive maintenance.
End User:
Contract values scale with infrastructure density and the financial cost of downtime, creating tiered purchasing power across the customer base.
- Cloud Service Firms:Massive server fleets under continuous load generate multi-year, multi-vendor maintenance agreements with stringent SLA penalties. These buyers in the United States are unbundling break-fix from monitoring services to drive price transparency.
- Telecom Service Providers:Legacy network infrastructure with extended depreciation schedules requires specialized support for end-of-life Cisco and Juniper equipment. Indian operators expanding under PLI scheme incentives are procuring third-party coverage ahead of mature OEM service networks.
- Managed Service Providers:Multi-tenant infrastructure creates complex liability allocation between MSP and maintenance vendor.
- Colocation Providers:Facility operators must support heterogeneous customer equipment without standardization.
- Content Delivery Networks:Distributed edge nodes demand maintenance models adapted to remote locations.
Cloud service firms dominate contract value; CDN edge networks are climbing the fastest.
Equipment Type:
Technical complexity and parts availability constraints fragment service economics across hardware categories.
- Servers:Compute infrastructure generates the highest absolute maintenance spend due to volume and component density. Firmware lock-in on latest-generation processors restricts third-party diagnostic depth, particularly for United States hyperscale operators.
- Storage Systems:RAID configurations and data retention requirements elevate recovery complexity. European facilities face REACH substance restrictions on capacitor chemistries during refurbishment, elevating testing overhead for circular economy-certified operators.
- Routers:Core network equipment with proprietary operating systems.
- Switches:Data center interconnect hardware with standardized management protocols.
- Firewalls:Security appliances requiring certified technician access.
- Load Balancers:Traffic distribution equipment with software-defined configuration layers.
Servers command the greatest revenue pool; storage systems show the steepest expansion trajectory.
Deployment Model:
Infrastructure scale and geographic concentration determine whether centralized dispatch or distributed field networks prove economically viable.
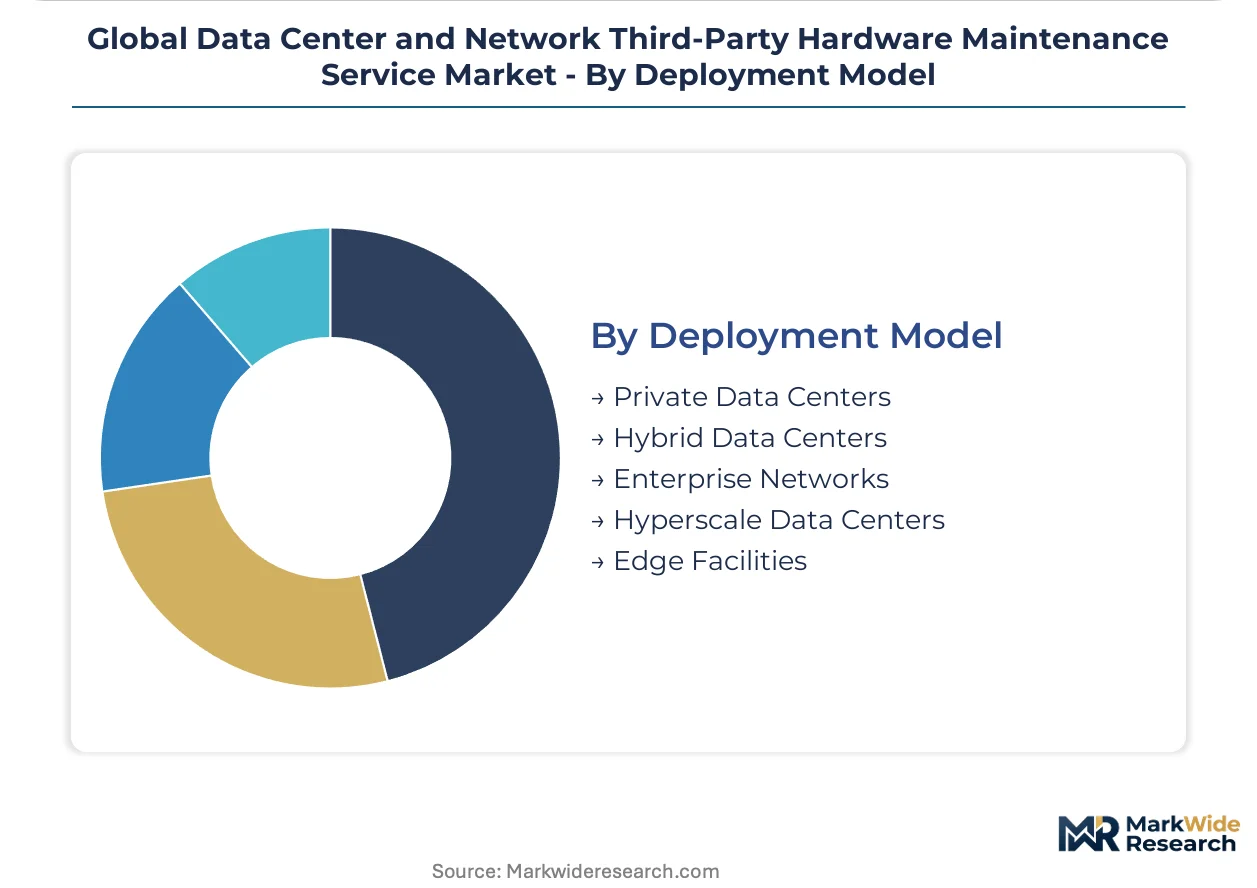
- Hyperscale Data Centers:Concentrated server populations justify dedicated on-site spare parts inventories and resident engineering teams. United States facilities are deploying digital twin technology to validate third-party procedures before field authorization.
- Edge Facilities:Distributed micro data centers in remote locations defy centralized manufacturer dispatch economics. Indian edge buildouts under domestic cloud infrastructure expansion are creating demand for localized maintenance networks.
- Private Data Centers:Single-tenant facilities with customized infrastructure stacks.
- Hybrid Data Centers:Mixed on-premise and cloud-resident workloads with integrated monitoring requirements.
- Enterprise Networks:Distributed corporate infrastructure spanning multiple locations.
Hyperscale data centers generate the highest contract values; edge facilities are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal circular economy mandates and India's PLI scheme for data center infrastructure are redirecting maintenance procurement toward third-party channels across multiple jurisdictions.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth are compressing hardware refresh cycles while extending post-warranty support terms. EPA electronics sustainability guidelines incentivize parts reuse in enterprise procurement. The Phoenix data center cluster is deploying digital twin technology to validate third-party technician procedures before field authorization.
Germany
Frankfurt's banking and colocation facilities face binding refurbishment targets under EU Green Deal implementation. ECHA REACH substance restrictions eliminate certain solder formulations from reuse pipelines, elevating testing overhead. Bavarian refurbishment operators are consolidating pre-certification screening into centralized testing hubs rather than distributed depot models.
India
Domestic cloud infrastructure expansion under the PLI scheme is creating demand for post-warranty support before local OEM service networks mature. Mumbai and Hyderabad data center buildouts are procuring third-party coverage for end-of-life Cisco and Dell hardware. Field engineering talent scarcity concentrates in legacy equipment diagnostics among aging technician cohorts.
United Kingdom
London financial services verticals are unbundling break-fix services from comprehensive maintenance contracts to drive price transparency. CSRD reporting requirements filter into procurement specifications for ISO 14001-certified refurbishment operators. Slough and Docklands data center clusters are adopting AI-driven predictive maintenance tools to optimize component replacement timing.
Japan
Tokyo and Osaka enterprise data centers maintain extended depreciation schedules on storage systems, requiring specialized support for end-of-life equipment. METI circular economy guidelines shape service standards for parts reuse certification. Kanto region facilities are deploying remote monitoring infrastructure to compress response times without proportional field engineering headcount growth.
Global Data Center and Network Third-Party Hardware Maintenance Service Market Competitive Landscape
On the supply side, the industry is consolidating around multi-vendor contract specialists with global parts logistics networks. Independent service providers compete with manufacturer service architectures through guaranteed response time commitments and circular economy certification. Two strategic archetypes dominate: global parts logistics operators with distributed depot networks, and refurbishment specialists with ISO 14001 environmental management credentials. Competitive moves center on geographic expansion into emerging data center markets and portfolio diversification into predictive maintenance tooling.
Among North American-based service providers, Park Place Technologies exemplifies the global logistics archetype through its distributed spare parts infrastructure. Service Express occupies a position within the specialized coverage tier for end-of-life enterprise hardware. Evernex anchors the circular economy-certified segment with refurbishment operations spanning multiple continents. These three companies represent the dominant competitive positioning patterns visible across the vendor landscape.
| Leading Market Players |
|---|
| Park Place Technologies |
| Service Express |
| Evernex |
| Curvature |
| CentricsIT |
| DataSpan |
| Cxtec |
| Reliant Technology |
| Atlantix |
| Others |
Supply & Pricing Matrix
Frankfurt's banking and colocation cluster concentrates spare parts inventory capacity for European refurbishment operations, with centralized testing hubs in Bavaria creating downstream pricing power for ISO 14001-certified operators serving EU Green Deal mandates.
Pricing Analysis
Certification level creates the primary spread between service tiers, with ISO 14001 environmental management and ISO 9001 quality frameworks commanding premium positioning over uncertified competitors. Three-tier pricing structure across premium, standard, and economy levels segments buyers by response time guarantees and parts availability commitments. Cost compression in the standard tier is intensifying because hyperscale operators in the United States are unbundling break-fix from monitoring services to drive price transparency. Cloud service firms exhibit the lowest price sensitivity due to uptime penalty exposure, while colocation providers face acute margin pressure from heterogeneous equipment support complexity.
Supply Chain Analysis
Original equipment manufacturers in the United States, Germany, and Japan retain captive control over critical server processors, storage controllers, and network firmware distribution. Third-party service providers draw from secondary markets, authorized reseller channels, and specialized brokers for end-of-life Cisco, Dell, and HP components. Single-source vulnerability concentrates in proprietary diagnostic tools and locked firmware updates that restrict complete system restoration. Distribution runs through multi-vendor contract specialists with distributed depot networks rather than manufacturer-direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent service providers face substitution pressure from AI-driven predictive maintenance platforms that internalize failure forecasting capabilities previously outsourced to third-party vendors.
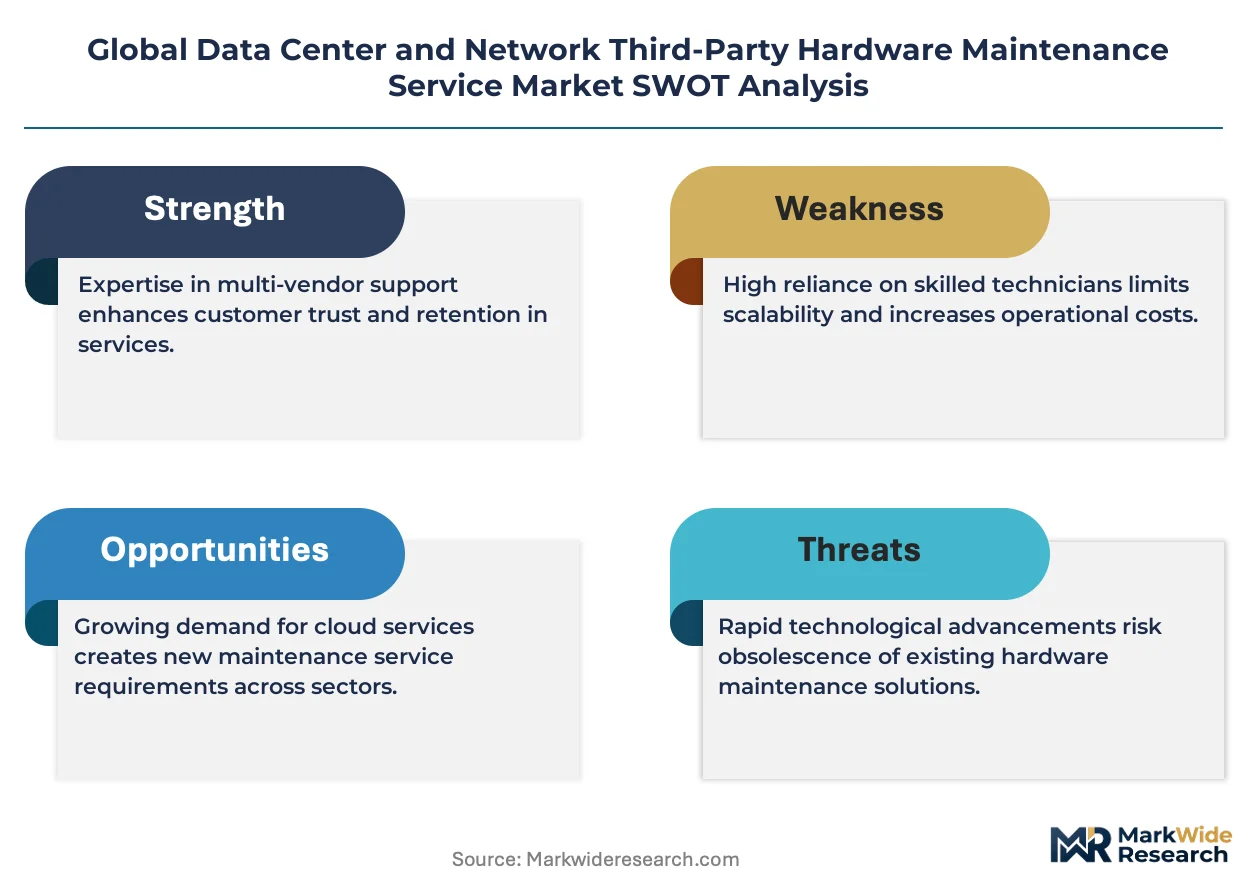
For Market Incumbents: Insulate core maintenance contracts by embedding digital twin validation protocols that manufacturer service architectures cannot replicate without hardware access. Deepen backward integration into proprietary parts sourcing networks to reduce OEM-controlled procurement chokepoints. Acquire specialized refurbishment operators with existing ISO 14001 credentials to preempt circular economy certification requirements under tightening EU Green Deal implementation. For New Entrants and Emerging Players: India's domestic cloud infrastructure buildout under PLI scheme incentives presents the most penetrable geography, with post-warranty demand outpacing mature OEM service network development. Edge computing facility networks in remote locations offer white-space entry where centralized manufacturer dispatch economics fail. Lead with AI-augmented predictive maintenance tooling to differentiate against legacy break-fix incumbents lacking telemetry infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a circular economy infrastructure play because binding refurbishment and reuse targets across European jurisdictions create durable demand for certified operators regardless of hardware refresh cycle compression. Target acquisition candidates combining global parts logistics networks with established ISO 14001 environmental management frameworks. Monitor right-to-repair legislative progression across US states and EU member countries as the primary inflection signal for OEM lock-in erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Machine learning failure forecasting enables uptime guarantees rivaling manufacturer contracts at lower cost structures. |
| ISO 14001 Certification Investment | Environmental management framework compliance filters into enterprise procurement specifications under EU Green Deal mandates. |
| Geographic Expansion into India | Domestic cloud infrastructure buildout under PLI scheme incentives creates demand before local OEM service networks mature. |
| Digital Twin Technology Deployment | Virtualized hardware environments validate third-party technician procedures without production system disruption. |
| Refurbishment Operator Acquisition | Consolidation of circular economy-certified capabilities preempts tightening circular economy action plan requirements. |
Research Methodology
A standing panel of data center operations directors, third-party maintenance procurement managers, field service engineering heads, and sustainability compliance officers provided ongoing calibration across the study period. Primary interviews with hyperscale operator infrastructure teams and enterprise IT asset management leaders combined with secondary validation against EPA electronics sustainability guidelines, EU Green Deal implementation documents, SEC 10-K filings from listed service providers, and ISO certification registry data. Bottom-up contract value analysis triangulated against top-down market sizing from hardware installed base estimates.
Scenario bracketing anchored projections across baseline, accelerated circular economy adoption, and extended OEM lock-in persistence cases. Segmentation modeling spanned service type modality, equipment category technical complexity, deployment model scale tier, and end-user vertical purchasing power. CAGRs derived from historical contract renewal rate analysis, parts cost inflation trajectories, and predictive maintenance adoption curve benchmarking. Forecast inputs incorporated PLI scheme infrastructure buildout timelines and REACH substance restriction compliance cost impacts.
Practitioners should monitor right-to-repair legislative passage, firmware access litigation outcomes, and hyperscale operator unbundling depth for early signals of structural market revision. Forecasts embed assumptions regarding OEM spare parts channel openness and circular economy certification procurement weighting. Quarterly review of EU Green Deal enforcement intensity, EPA guideline updates, and predictive maintenance platform internalization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Datacenter Network Consulting and Integration Service Market
Data Center and Networking
Global DNS Service Market
Data Center and Networking
South Africa Data Center Networking Market
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
Thailand Data Center Networking Market
Data Center and Networking
Nosql Market
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
Automotive Data Management Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Brazil Optical Transceiver Market
Data Center and Networking
Managed DNS Services Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Mobile Data Traffic Market
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
Application Delivery Network (ADN) Market