
 Global Network Configuration and Change Management Market | 2026-2036
Global Network Configuration and Change Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Network Configuration and Change Management Market Foresight
Market Context
Software-defined networking is tilting enterprise architecture toward programmable infrastructure that demands real-time configuration governance. Cisco Systems, Inc. anchors its position through deep integration with existing routing hardware and extensive channel partnerships. IBM leverages its Red Hat acquisition to compete in hybrid-cloud network automation, while SolarWinds Worldwide, LLC specializes in mid-market network monitoring with accessible pricing.
Technical Definition and Segments
Network configuration and change management encompasses the systematic tracking, versioning, and automated deployment of device settings across routers, switches, firewalls, and load balancers, typically operating through SNMP, NETCONF, or REST APIs to maintain service continuity and security posture. Cloud-based deployment leads solution adoption as enterprises migrate from capital-intensive on-premises toolchains to subscription models with faster update cycles. Configuration management and automation segments capture the strongest growth momentum, while compliance management retains stable margins among financial services and government agencies subject to audit requirements.
Regulatory Frame and Outlook
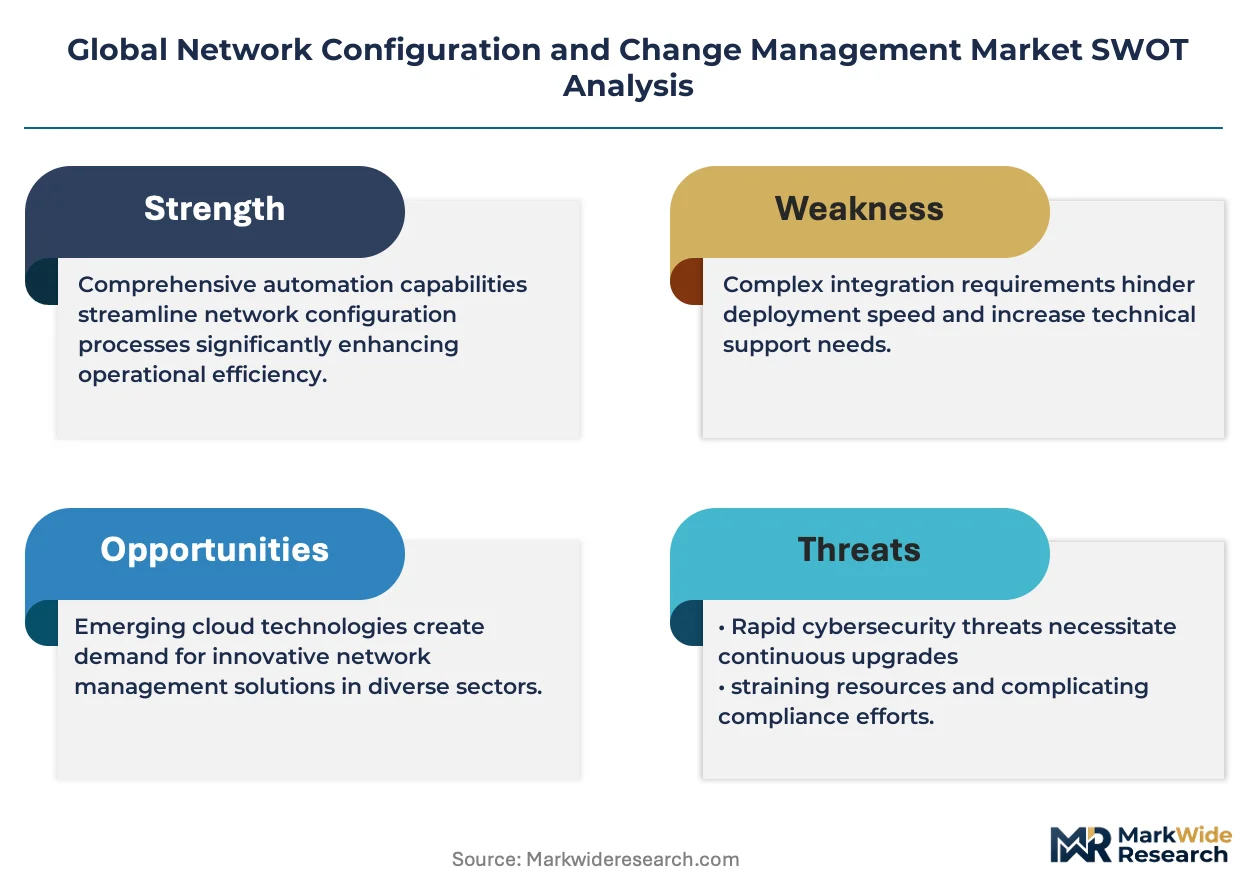
The EU NIS2 Directive and GDPR impose breach-notification and resilience mandates on network operators across Europe, while the US FCC and NIST Cybersecurity Framework shape procurement standards for federal contractors and critical infrastructure owners. Japan's METI guidelines on operational technology security further tighten configuration audit requirements for manufacturing and energy networks. Stakeholders must weigh API-based integration investments against the risk of vendor lock-in as multi-vendor environments become the operational norm.
Market Dynamics
Telecommunications carriers are consolidating vendor relationships to manage 5G network complexity, creating procurement concentration that favors integrated platform providers over point-solution vendors.
Growth Catalysts
- EU NIS2 Directive:Breach-notification and resilience mandates force European critical infrastructure operators to automate configuration audit trails, expanding addressable market for compliance-integrated tooling.
- 5G Standalone Core Deployments:Network slicing architectures in telecommunications require real-time configuration orchestration across distributed radio access networks, driving demand for programmable infrastructure governance.
- Japan METI Guidelines:Operational technology security mandates for manufacturing and energy networks tighten configuration documentation requirements, creating regulatory pull in Asia-Pacific's most advanced industrial economy.
Market Restraints
- Specialized Engineering Talent Scarcity:Shortage of NETCONF and YANG modeling expertise constrains enterprise implementation velocity, particularly among mid-market organizations lacking dedicated network engineering functions.
- Multi-Vendor Integration Friction:Proprietary API implementations across Cisco, Juniper, and Arista equipment create interoperability gaps that increase deployment complexity and total cost of ownership.
- Legacy SNMP Dependency:Persistent reliance on polling-based monitoring protocols in established enterprises limits real-time visibility, delaying migration to event-driven configuration management architectures.
Strategic Opportunities
- India Manufacturing Digitization:PLI scheme incentives for semiconductor and electronics production are accelerating smart factory deployments, creating greenfield demand for industrial network configuration tools.
- Zero Trust Architecture Convergence:Integration of network access control with identity-aware policy engines enables unified microsegmentation and configuration enforcement across hybrid cloud environments.
- API-First Distribution Models:Native integration with ServiceNow and Terraform registries is displacing traditional reseller channels for DevOps-oriented buyer segments.
Industry Challenges
- Configuration Drift Detection:Maintaining authoritative state repositories across ephemeral cloud-native network functions requires continuous reconciliation capabilities that strain existing operational workflows.
- Cross-Functional Skill Gaps:Bridging network engineering and software development competencies remains difficult as infrastructure-as-code practices permeate traditional network operations teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Network Configuration and Change Management Market |
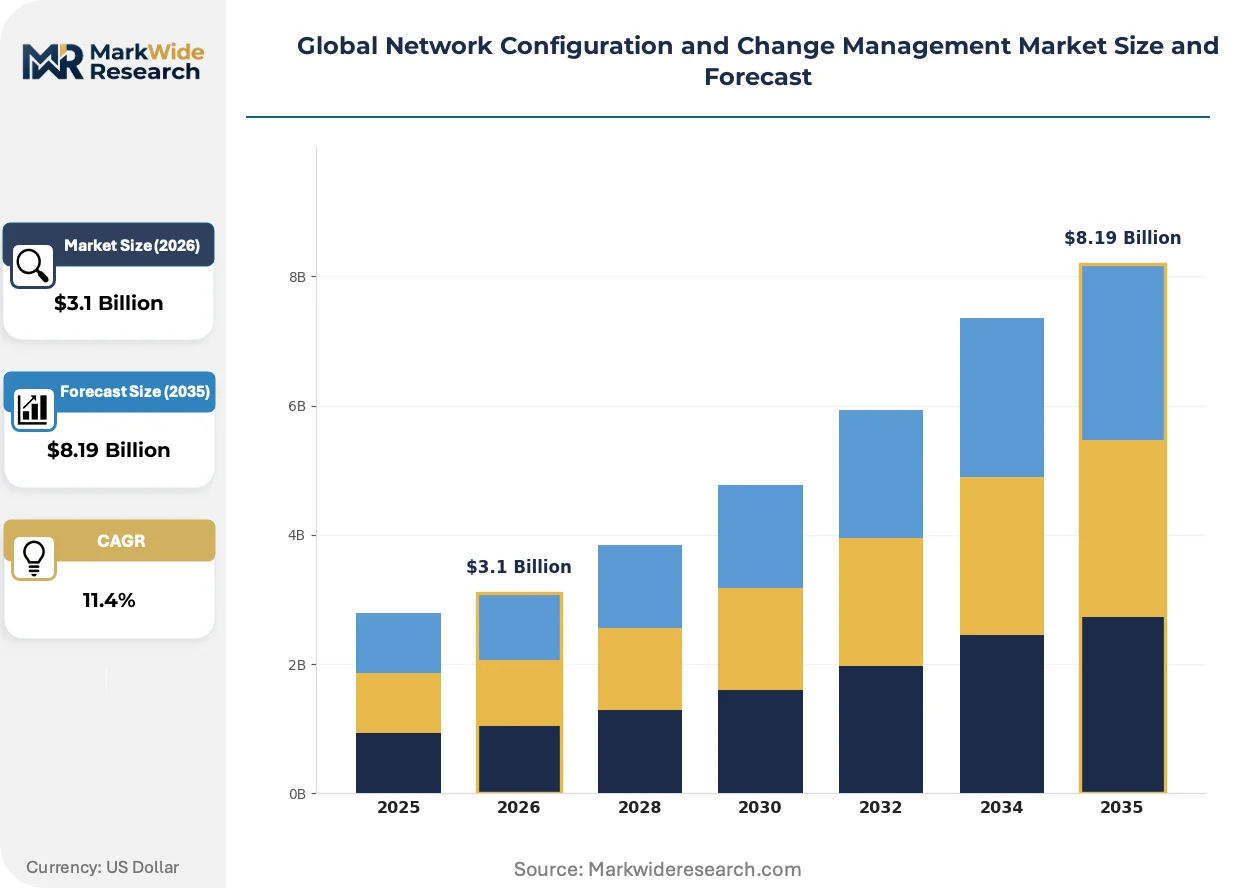
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $8.19 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Virtualized Environments Solution Type: Configuration Management, Change Tracking, Compliance Management, Automation, Analytics End User Industry: Telecommunications, Financial Services, Government Agencies, Manufacturing, Education Integration Level: Standalone, Enterprise-Wide, Multi-Vendor, API-Based |
| Companies Covered | Juniper Networks, Inc., BMC Software, Inc., Cisco Systems, Inc., Zoho Corporation Private Limited, Micro Focus International plc, SolarWinds Worldwide, LLC, IBM, Device42, Inc., Hewlett Packard Enterprise Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Network Configuration and Change Management Market Shifts & Advancements
Intent-based networking systems are compressing the gap between business policy statements and device-level configurations, eliminating manual translation layers that previously introduced error vectors and change latency.
AI-powered configuration anomaly detection is rendering obsolete rule-based threshold alerting in large-scale enterprise networks. Financial services institutions with over ten thousand managed devices are deploying machine learning models to baseline normal configuration states and flag deviations within minutes rather than days. This compression of incident detection windows is shifting competitive advantage toward vendors with proprietary training datasets and reinforcement learning pipelines.
The EU AI Act's risk classification framework for automated decision systems is forcing network management vendors to document algorithmic transparency and human oversight mechanisms in their configuration recommendation engines. European critical infrastructure operators must now maintain audit trails for AI-assisted change approvals, creating product differentiation around explainability features. German energy utilities are responding by demanding vendor-provided model cards and bias assessment documentation as standard procurement requirements.
Consumption-based licensing for configuration management platforms is displacing perpetual seat-based models in mid-market enterprise accounts. Channel partners are unbundling implementation services from software subscriptions, enabling self-service adoption through pre-built automation templates. This shift is most visible in United States healthcare networks, where capital constraints and rapid cloud migration are accelerating preference for operational expenditure structures with monthly commit thresholds.
Global Network Configuration and Change Management Market Segmentation
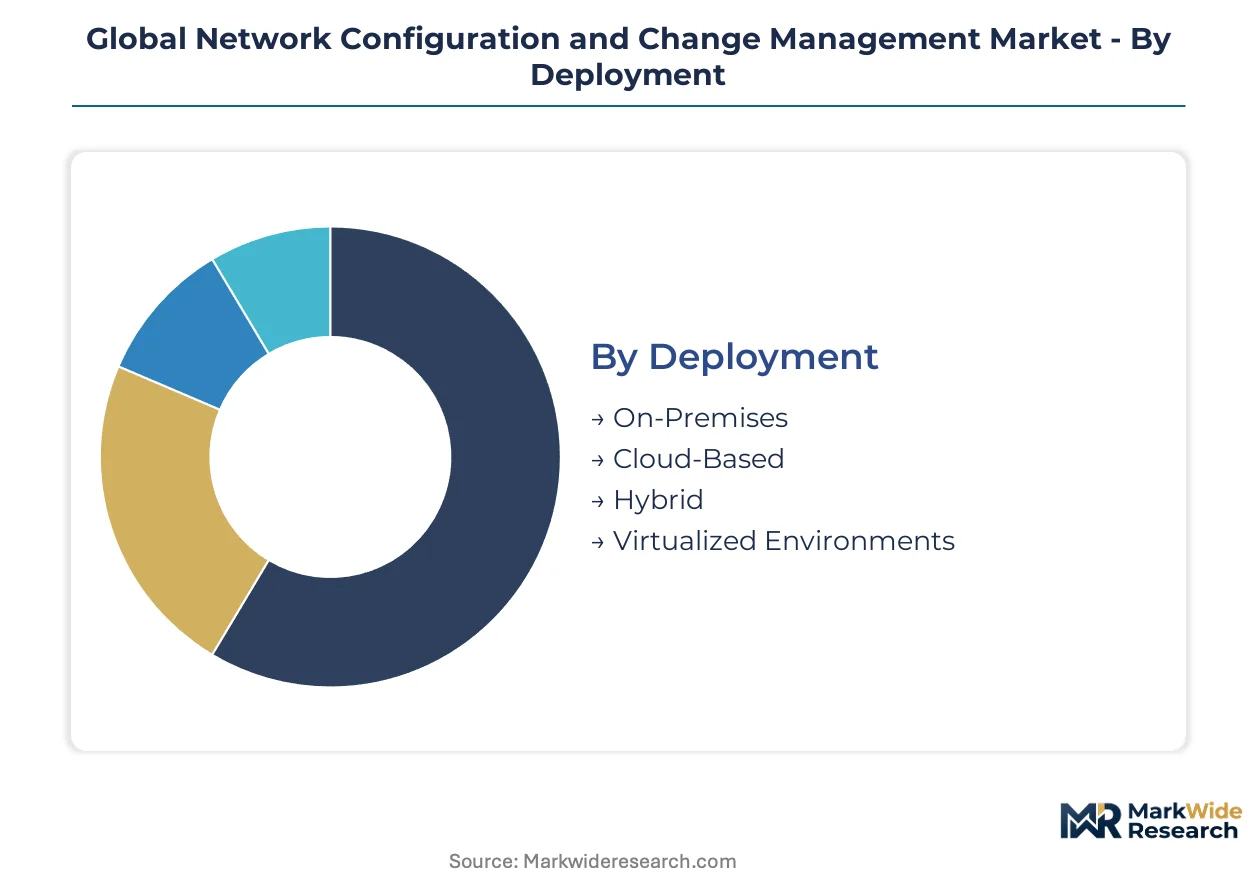
Network configuration and change management solutions span heterogeneous infrastructure layers, each with distinct procurement cycles and integration requirements. Segmentation reveals where automation investments concentrate versus where legacy tooling persists.
Deployment:
Cloud-based deployments refresh on quarterly release cycles, while on-premises installations typically lock in three-to-five-year refresh horizons.
- On-Premises:Hardware-resident tooling deployed within enterprise data centers or private facilities. Financial services institutions in Germany and Japan retain these configurations for air-gapped compliance environments subject to national banking regulator audit requirements.
- Cloud-Based:SaaS delivery models with continuous feature deployment and elastic capacity scaling. United States healthcare networks and mid-market enterprises are migrating here fastest to shift capital expenditure to operational structures.
- Hybrid:Orchestration across on-premises and cloud control planes with unified policy enforcement. Telecommunications carriers deploying 5G standalone cores favor this architecture for distributed radio access network management.
- Virtualized Environments:Containerized or VM-based deployment for ephemeral network functions and cloud-native infrastructure. DevOps-oriented teams in software-driven enterprises are adopting these for infrastructure-as-code workflows.
On-premises dominates installed base. Cloud-based is where expansion concentrates.
Solution Type:
Cost tiers separate commodity tooling from premium platforms with AI-powered anomaly detection and integrated compliance engines.
- Configuration Management:Baseline repository and versioning systems for device state documentation. Network engineering teams in manufacturing and energy sectors rely on these for METI-mandated audit trails in Japan.
- Change Tracking:Diff engines and rollback capabilities for configuration drift identification. Financial services institutions subject to SEC and GDPR breach-notification rules deploy these for forensic reconstruction.
- Compliance Management:Policy mapping to regulatory frameworks with automated evidence collection. Government agencies and critical infrastructure operators under NIS2 Directive mandates represent concentrated demand.
- Automation:Intent-based provisioning and closed-loop remediation across multi-vendor estates. Telecommunications carriers managing 5G network slicing complexity are expanding procurement fastest here.
- Analytics:ML-driven baseline establishment and deviation detection at scale. Large enterprises with ten-thousand-plus managed devices are deploying these to compress incident detection windows from days to minutes.
Configuration management anchors legacy revenue. Automation is climbing the fastest.
End User Industry:
Application criticality varies sharply—telecommunications tolerates near-zero downtime while education segments accept maintenance windows.
- Telecommunications:Real-time orchestration across radio access, transport, and core networks. Carriers in the United States, Germany, and Japan are consolidating vendor relationships to manage 5G standalone complexity.
- Financial Services:Audit-integrated tooling for trading infrastructure and payment networks. EU AI Act documentation requirements and GDPR breach-notification mandates are tightening procurement specifications.
- Government Agencies:Classified and civilian network hardening with FedRAMP or national-equivalent certification. NIST Cybersecurity Framework alignment shapes United States federal contractor selection criteria.
- Manufacturing:Operational technology network governance for smart factory deployments. India's PLI scheme incentives for semiconductor production are accelerating greenfield demand.
- Education:Campus network management with constrained capital budgets. Cloud-based subscription models are displacing perpetual licenses fastest in this segment.
Telecommunications dominates installed base. Manufacturing is where expansion concentrates.
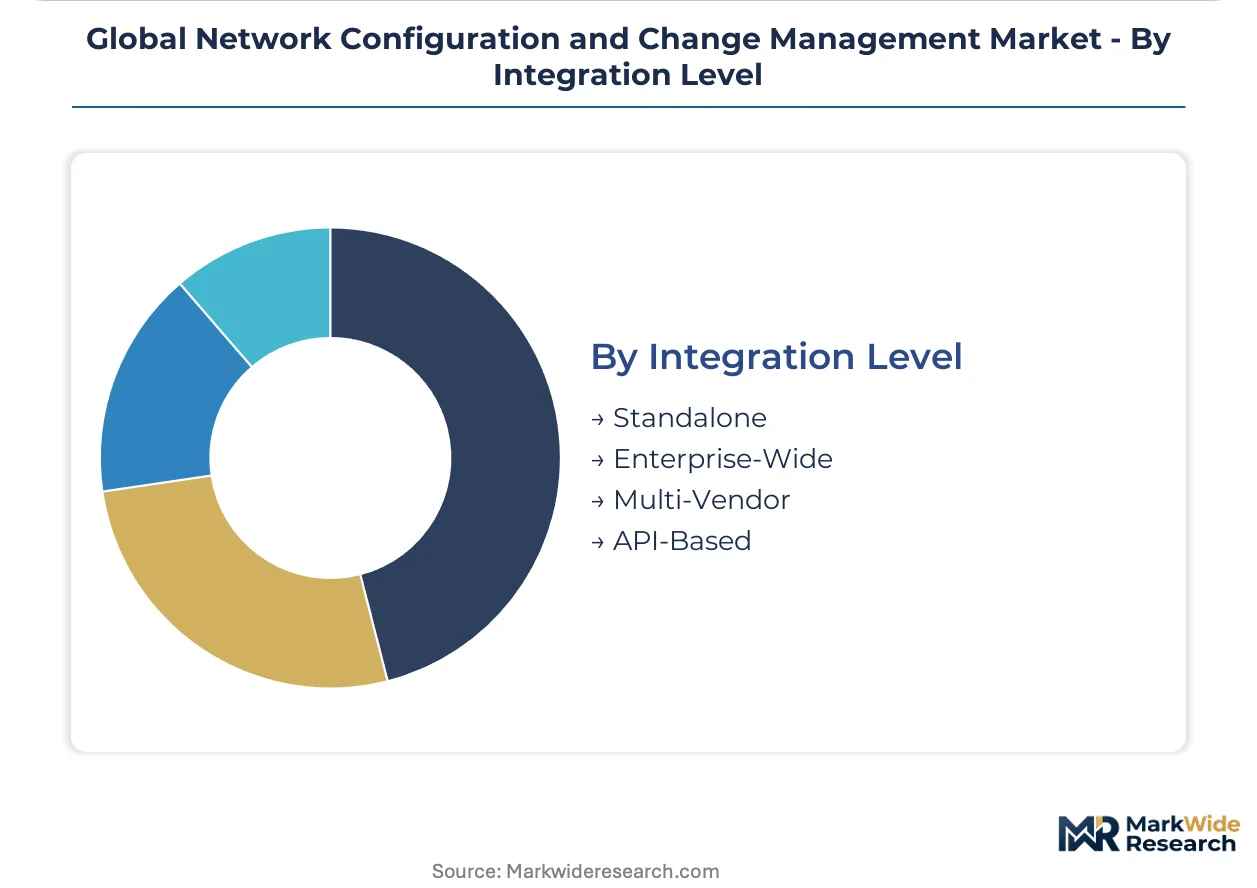
Integration Level:
Customer type separates point-solution buyers from platform consolidators seeking unified control planes.
- Standalone:Single-purpose tools for specific device classes or vendor ecosystems. Mid-market organizations lacking dedicated network engineering functions default here due to implementation simplicity.
- Enterprise-Wide:Centralized governance across all network assets with role-based access control. Large United States healthcare networks and federal agencies require these for unified security posture management.
- Multi-Vendor:Abstraction layers normalizing Cisco, Juniper, Arista, and white-box switch configurations. Proprietary API friction increases deployment complexity but reduces vendor lock-in risk.
- API-Based:Native integration with ServiceNow, Terraform, and CI/CD pipelines for DevOps workflows. Cloud-native enterprises and telecommunications operators building infrastructure-as-code practices are adopting these.
Standalone dominates installed base. API-based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German network automation vendors export configuration management platforms to telecommunications operators across Central and Eastern Europe, establishing a trade corridor that channels regulatory-compliant tooling into emerging EU member states.
United States
Federal contractors and critical infrastructure operators drive procurement under NIST Cybersecurity Framework alignment requirements. The FCC shapes procurement standards for telecommunications carriers managing 5G standalone core complexity. Dallas-Fort Worth metroplex hosts concentrated telecommunications infrastructure investment where carriers consolidate vendor relationships.
Germany
Energy utilities and automotive manufacturers automate configuration audit trails under EU NIS2 Directive breach-notification mandates. German regulators demand vendor-provided model cards and bias assessment documentation for AI-assisted change approvals. Ruhr industrial corridor utilities are deploying explainability-integrated tooling for operational technology networks.
Japan
Manufacturing and energy networks tighten configuration documentation under METI operational technology security guidelines. Smart factory deployments in automotive and electronics sectors require real-time orchestration across distributed industrial control systems. Nagoya-Toyota industrial cluster represents concentrated demand for programmable infrastructure governance.
India
Semiconductor and electronics production incentives through the PLI scheme accelerate smart factory deployments requiring industrial network configuration tools. TRAI frameworks shape telecommunications infrastructure standards as carriers expand 5G radio access networks. Bengaluru-Chennai manufacturing corridor generates greenfield demand for cloud-native automation platforms.
United Kingdom
Financial services institutions deploy audit-integrated tooling for trading infrastructure under GDPR breach-notification and operational resilience mandates. London's concentrated fintech and banking cluster drives premium-platform procurement with integrated compliance engines. Thames Valley technology corridor hosts hybrid-cloud network automation adoption among enterprise software firms.
Global Network Configuration and Change Management Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement decisions in telecommunications and financial services verticals. The vendor base organizes around three archetypes: integrated platform providers with hardware-software bundles, pure-play SaaS vendors with API-first distribution, and compliance-specialized firms serving regulated industries. Dominant competitive moves include strategic partnerships with cloud hyperscalers and portfolio diversification into adjacent security domains.
Among United States-based platform providers, Cisco Systems, Inc. and IBM exemplify integrated infrastructure governance archetypes, while SolarWinds Worldwide, LLC occupies a position within the mid-market accessibility tier. These three anchors represent distinct competitive vectors: hardware-originated ecosystem control, hybrid-cloud automation through acquisition-led expansion, and subscription pricing disruption in underserved segments.
| Leading Market Players |
|---|
| Juniper Networks, Inc. |
| BMC Software, Inc. |
| Cisco Systems, Inc. |
| Zoho Corporation Private Limited |
| Micro Focus International plc |
| SolarWinds Worldwide, LLC |
| IBM |
| Device42, Inc. |
| Hewlett Packard Enterprise Company |
| Others |
Supply & Pricing Matrix
Bengaluru-Chennai manufacturing corridor capacity expansion for cloud-native automation platforms feeds downstream pricing power to SaaS vendors serving India's PLI-accelerated smart factory deployments.
Pricing Analysis
Next-generation AI-powered anomaly detection platforms command 40-60% premiums over legacy SNMP-based configuration tools, while prior-generation on-premises perpetual licenses face margin compression from subscription displacement. Three-tier pricing structure across premium AI-integrated, standard automation, and economy monitoring tiers stratifies by integration complexity and compliance engine depth. Pricing pressure stems from hyperscaler marketplace listings compressing channel margins. Mid-market education and healthcare segments exhibit highest price sensitivity; telecommunications carriers with 5G slicing mandates show lowest.
Supply Chain Analysis
Upstream open-source YANG model libraries and NETCONF protocol stacks from the IETF standards body feed product development pipelines for commercial platform vendors. Software engineering talent concentrates in the United States, Germany, and India, while hardware-originated vendors anchor manufacturing in Taiwan and China for network appliance integration. Single-source vulnerability rests on concentrated hyperscaler cloud infrastructure for SaaS delivery. Distribution runs through direct enterprise sales teams and API-first marketplace integrations with ServiceNow and Terraform registries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification framework for automated decision systems creates a regulatory inflection that will bifurcate vendor competitiveness between explainability-integrated platforms and opaque legacy tooling.
For Market Incumbents: Entrench hybrid-cloud orchestration capabilities through Red Hat-style container platform integration, defending against pure-play SaaS disintermediation. Prioritize NIST Cybersecurity Framework certification investments to maintain federal contractor eligibility. Channel control through systems integrator partnerships remains critical for telecommunications procurement consolidation.
For New Entrants and Emerging Players: Establish a beachhead in India's manufacturing digitization wave targeting PLI scheme semiconductor fabs with cloud-native, API-first configuration tools. India's greenfield smart factory deployments offer lowest competitive density against entrenched Cisco-IBM incumbency. Go-to-market through Terraform registry native integration bypasses traditional reseller channel friction.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-integrated infrastructure software play because regulatory mandates across EU NIS2, US NIST, and Japan METI create durable demand tailwinds independent of macro cycles. Target acquisition archetype: mid-market SaaS vendors with ServiceNow-native integrations and FedRAMP authorization progress. Signal to watch: telecommunications carrier RFP language shifting from "configuration management" to "intent-based networking" as procurement specification.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Native ServiceNow and Terraform registry embedding displaces legacy reseller channels for DevOps-oriented buyer segments. |
| AI Explainability Certification | EU AI Act model card documentation creates procurement differentiation for German energy utilities under NIS2 mandates. |
| Hybrid-Cloud Orchestration | Red Hat-derived container platforms enable IBM to compete for telecommunications 5G standalone core deployments. |
| FedRAMP Authorization Pathway | US federal contractor eligibility requires NIST Cybersecurity Framework alignment for government agency procurement. |
| India Manufacturing Localization | Bengaluru-Chennai corridor PLI incentives create greenfield demand for industrial network configuration tooling. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with network engineering directors, IT procurement officers, DevOps platform engineers, and telecommunications infrastructure planners. Secondary validation drew from SEC 10-K filings, hyperscaler capex disclosures, IETF standards documentation, and EU regulatory filings. Bottom-up triangulation across deployment model, solution type, end-user industry, and integration level segmentation combined with top-down macroeconomic calibration.
Calibration anchored volume and value outputs to disclosed vendor bookings, carrier procurement patterns, and compliance-driven replacement cycles across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution functionality tier, vertical application criticality, and API integration depth. CAGRs derived from regression analysis against telecommunications infrastructure investment trajectories and regulatory mandate enforcement timelines, with 5G standalone core deployment velocity and AI Act implementation pacing as key sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in enterprise cloud migration spend and critical infrastructure capital allocation would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and vendor consolidation pace. Technology transition risk from SNMP to NETCONF/YANG architectures and hyperscaler marketplace margin compression represent primary revision vectors. Cross-checking against disclosed telecommunications carrier vendor consolidation announcements and EU NIS2 national implementation schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market
Data Center and Networking
Network Slicing Market
Data Center and Networking
Italy Data Center Networking Market
Data Center and Networking
Germany Data Center Networking Market
Data Center and Networking
Vietnam Data Center Networking Market
Data Center and Networking
North America Subscriber Data Management Market
Data Center and Networking
Global Heterogeneous Network Market
Data Center and Networking
Global Data Warehouse Market
Data Center and Networking
US Dark Fiber Network Market
Data Center and Networking
SDN Orchestration Market
Data Center and Networking
APAC Data Center Networking Market
Data Center and Networking
Network As a Service (Naas) Market
Data Center and Networking
Cluster Computing Market
Data Center and Networking
Managed DNS Services Market
Data Center and Networking
Sweden Data Center Networking Market