
 Network Function Virtualization (NFV) Market | 2026-2036
Network Function Virtualization (NFV) Market Size, Share, and Industry Trends Forecast 2026-2036
Network Function Virtualization (NFV) Market Analysis
The EU Green Deal is pivoting telecom infrastructure procurement toward energy-efficient virtualized networks. Nokia Corporation leverages its cloud-native core portfolio to sustain European operator relationships. Cisco Systems anchors enterprise NFV deployments through integrated security and routing virtualization. Huawei Technologies competes aggressively in Asia-Pacific markets with end-to-end 5G core solutions despite trade restrictions.
Network Function Virtualization decouples proprietary network functions from dedicated hardware, enabling software-based deployment on commercial off-the-shelf servers using containerized or hypervisor-based architectures such as KVM and Docker. Its primary purpose is to reduce capital expenditure, accelerate service deployment cycles, and enable elastic scaling of network capacity. Managed Services captures recurring revenue streams as operators outsource virtualized network operations. Hybrid Cloud deployments are expanding fastest as enterprises balance latency requirements with cost optimization. OpenStack retains significance in telecom-grade deployments despite Kubernetes encroachment.
ETSI NFV standards, the EU AI Act, and national spectrum regulators including the FCC and Germany's BNetzA shape product certification timelines and interoperability mandates for virtualized network equipment. The FCC's open RAN initiatives indirectly accelerate NFV adoption by mandating software-disaggregated network architectures. Stakeholders must monitor evolving container orchestration standards and sovereign cloud requirements as procurement criteria shift from hardware specifications to software compliance frameworks.
Market Dynamics
Telecom operators are dismantling purpose-built network appliances in favor of software-defined functions running on commodity servers, compressing equipment refresh cycles from seven years to under three.
Growth Catalysts
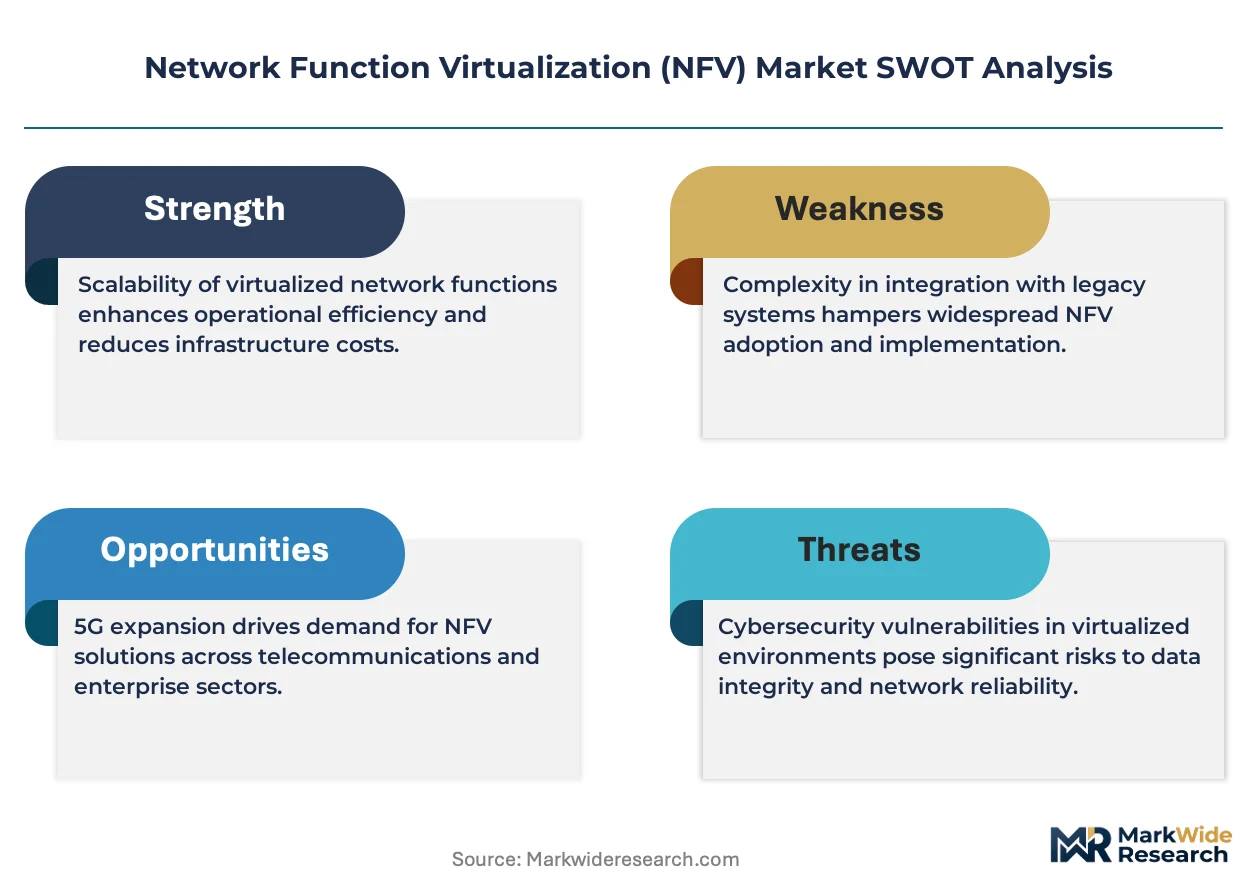
- ETSI NFV Framework:Standardized reference architectures eliminate vendor lock-in and accelerate multi-supplier interoperability testing. European operators now mandate ETSI compliance in core network tenders.
- 5G Standalone Core:Cloud-native 5G core deployments require virtualized network functions as foundational infrastructure. Mobile operators in Germany and Japan are prioritizing containerized core implementations.
- Edge Computing Clusters:Distributed edge nodes demand lightweight, portable network functions. Manufacturing and autonomous vehicle sectors are driving low-latency virtualized routing demand.
Market Restraints
- Silicon Supply Concentration:High-performance server CPU and SmartNIC fabrication concentrates among three foundry operators. NFV infrastructure vendors face allocation uncertainty for x86 and ARM-based silicon.
- Container Orchestration Fragmentation:Divergence between Kubernetes and OpenStack operational models forces dual-skill maintenance. Operators struggle to unify monitoring and lifecycle management across both stacks.
- Legacy Hardware Stranding:Existing physical network function investments carry depreciation schedules extending to 2028. CFO resistance accelerates where hardware refresh cycles conflict with virtualization timelines.
Strategic Opportunities
- EU Green Deal Procurement Mandates:Energy efficiency criteria now weight 30% in public telecom tenders. Virtualized network functions with verified power consumption metrics qualify for preferential scoring.
- AI-Driven Network Automation:Convergence of machine learning inference with packet processing creates demand for GPU-accelerated virtualized functions. Telcos are piloting automated traffic engineering in Frankfurt and Singapore.
- Private 5G Enterprise Deployments:Manufacturing campuses and logistics hubs require localized virtualized cores. Systems integrators are packaging pre-certified NFV stacks for non-telecom buyers.
Industry Challenges
- Cloud-Native Engineering Talent Scarcity:Container networking, service mesh configuration, and GitOps pipelines require skills absent from traditional telecom engineering ranks. Operators compete with hyperscalers for identical talent pools.
- Multi-Vendor Integration Complexity:Disaggregated virtualized functions from separate suppliers demand custom interoperability testing. Integration timelines frequently exceed original deployment schedules by 40-60%.
- Certification Cycle Compression:National regulators including Germany's BNetzA and Japan's MIC require re-certification for each software version update. Continuous delivery pipelines conflict with sequential approval processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Function Virtualization (NFV) Market |
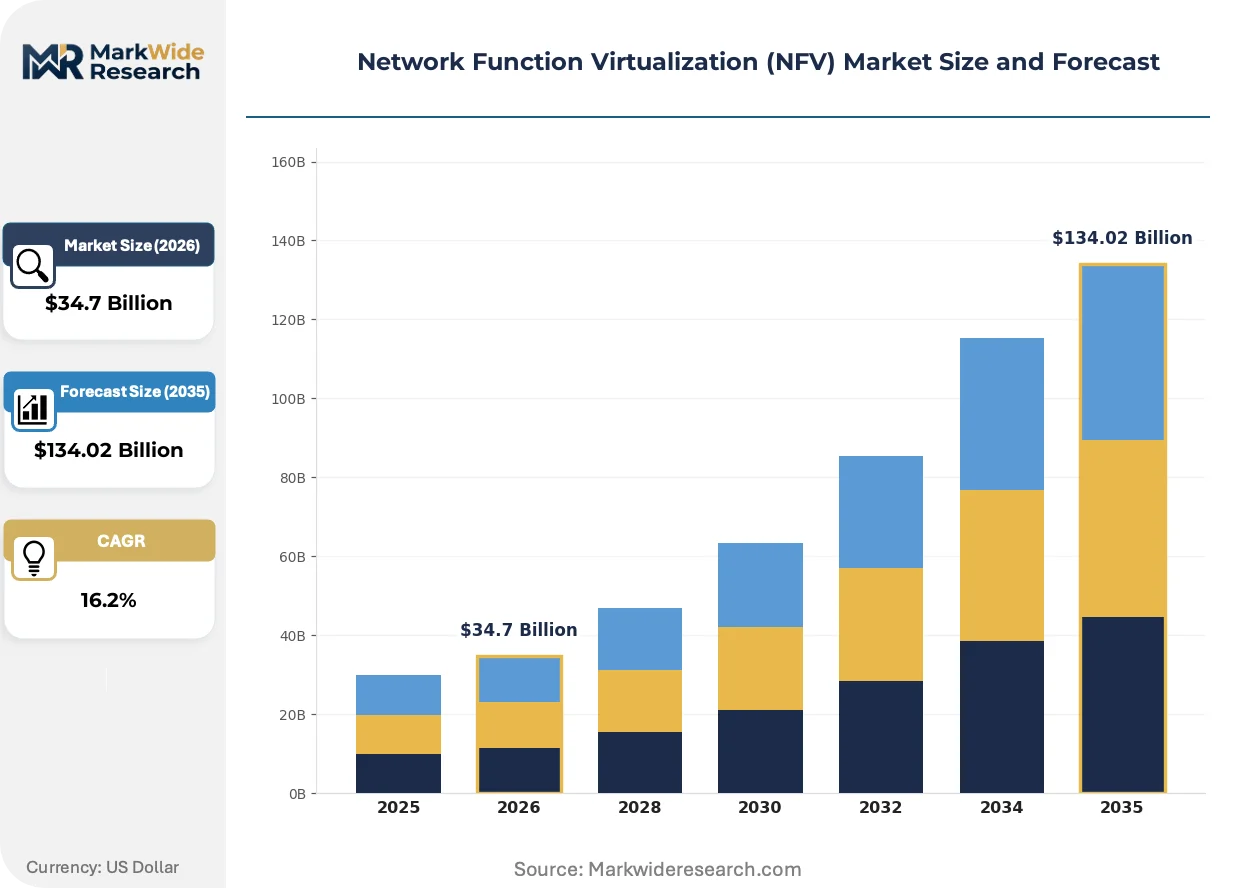
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $134.02 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Managed Services, Professional Services, Consulting Services, Technical Support End User: Telecom Operators, Enterprises, Data Centers, Managed Service Providers Technology: OpenStack, VMware, KVM, Docker |
| Companies Covered | Nokia Corporation, VMware, Cisco Systems, AT&T, Amdocs, Huawei Technologies, Juniper Networks, Mavenir, Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Function Virtualization (NFV) Market Emerging Trajectories
Software architectures are fragmenting monolithic network functions into microservices, enabling independent scaling and failure isolation while complicating operational visibility.
Service mesh technology is decentralizing east-west traffic management within Kubernetes-orchestrated NFV deployments. Tier-1 operators in the United States are replacing hardware load balancers with Envoy-based sidecar proxies. This architecture is decentralizing security policy enforcement from perimeter appliances to individual pod boundaries.
The EU AI Act's risk classification framework is extending to network automation systems using machine learning for traffic prediction. Virtualized functions incorporating AI inference now face conformity assessment requirements previously limited to safety-critical applications. European operators are segregating AI-enabled and deterministic network functions to isolate compliance scope.
Enterprise buyers are unbundling professional services from software licenses, contracting systems integrators separately for design, deployment, and optimization. Channel partners in Germany and Japan are building NFV practices independent of vendor professional services organizations. Manufacturing verticals show strongest appetite for disaggregated procurement, treating virtualized networking as infrastructure software rather than telecom equipment.
Network Function Virtualization (NFV) Market Segmentation
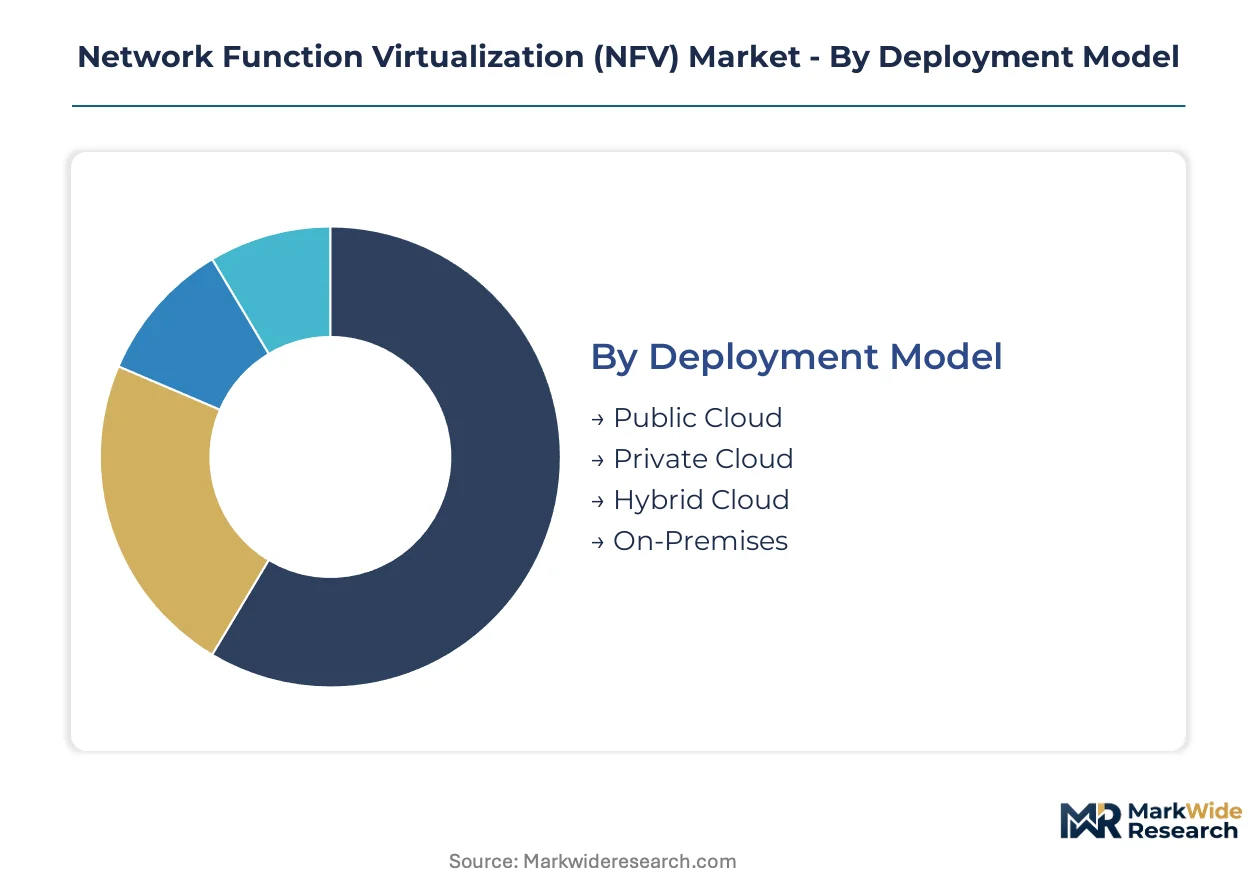
NFV procurement patterns diverge sharply across deployment models, service arrangements, and underlying infrastructure choices. Understanding these fault lines clarifies where vendor investments concentrate and which customer segments command pricing power.
Deployment Model:
Cost sensitivity and latency requirements split buyers into distinct infrastructure tiers with opposing refresh cadences.
- Hybrid Cloud:Workloads split between on-premises edge nodes and hyperscaler capacity, balancing sub-10ms latency for real-time functions against burst economics. Manufacturing campuses in Germany and Japan favor this model for private 5G cores. Expansion accelerates as enterprises reconcile operational technology uptime requirements with cloud cost arbitrage.
- Private Cloud:Dedicated infrastructure serves regulated sectors and sovereign data requirements. Telecom operators in the United States deploy these for subscriber data processing under FCC privacy frameworks. Capital intensity limits adoption to tier-1 carriers and defense contractors with depreciation tolerance.
- Public Cloud:Shared infrastructure delivers lowest unit costs for non-latency-sensitive functions. Development and testing environments dominate current utilization.
- On-Premises:Legacy appliance retention in facilities with decade-long hardware amortization schedules. Stranded asset concerns delay virtualization timelines.
Volume sits with Private Cloud; growth tilts toward Hybrid Cloud.
Service Type:
Customer engineering maturity determines whether buyers self-operate or outsource lifecycle management.
- Managed Services:Third-party operation of virtualized network functions spans deployment, patching, and capacity scaling. European operators under EU Green Deal pressure outsource energy optimization to specialists. Recurring revenue stability attracts systems integrators building telecom practices.
- Professional Services:Project-based implementation covers migration from physical appliances and multi-vendor integration. Complexity premiums apply where OpenStack-Kubernetes interoperability demands custom engineering.
- Consulting Services:Architecture design and vendor selection support precede procurement decisions. Enterprise buyers unbundling these from software licenses drives channel independence.
- Technical Support:Break-fix and software version management for self-operated deployments. Regulatory re-certification requirements in Germany and Japan expand scope beyond traditional maintenance.
Revenue concentrates in Managed Services; margin expansion favors Professional Services.
End User:
Scale economies and technical sophistication create divergent purchasing behaviors across buyer categories.
- Telecom Operators:Largest absolute demand from mobile network virtualization and 5G standalone core deployments. Containerized implementations in Germany and Japan set architecture standards for tier-2 carriers.
- Enterprises:Manufacturing verticals lead private 5G campus deployments with localized virtualized cores. Procurement treats NFV as infrastructure software rather than telecom equipment.
- Data Centers:Colocation providers adding network function virtualization to interconnect and security service portfolios.
- Managed Service Providers:Multi-tenant platform investments to serve mid-market enterprises lacking internal cloud-native engineering capacity.
Absolute spending rests with Telecom Operators; fastest uptake occurs among Enterprises.
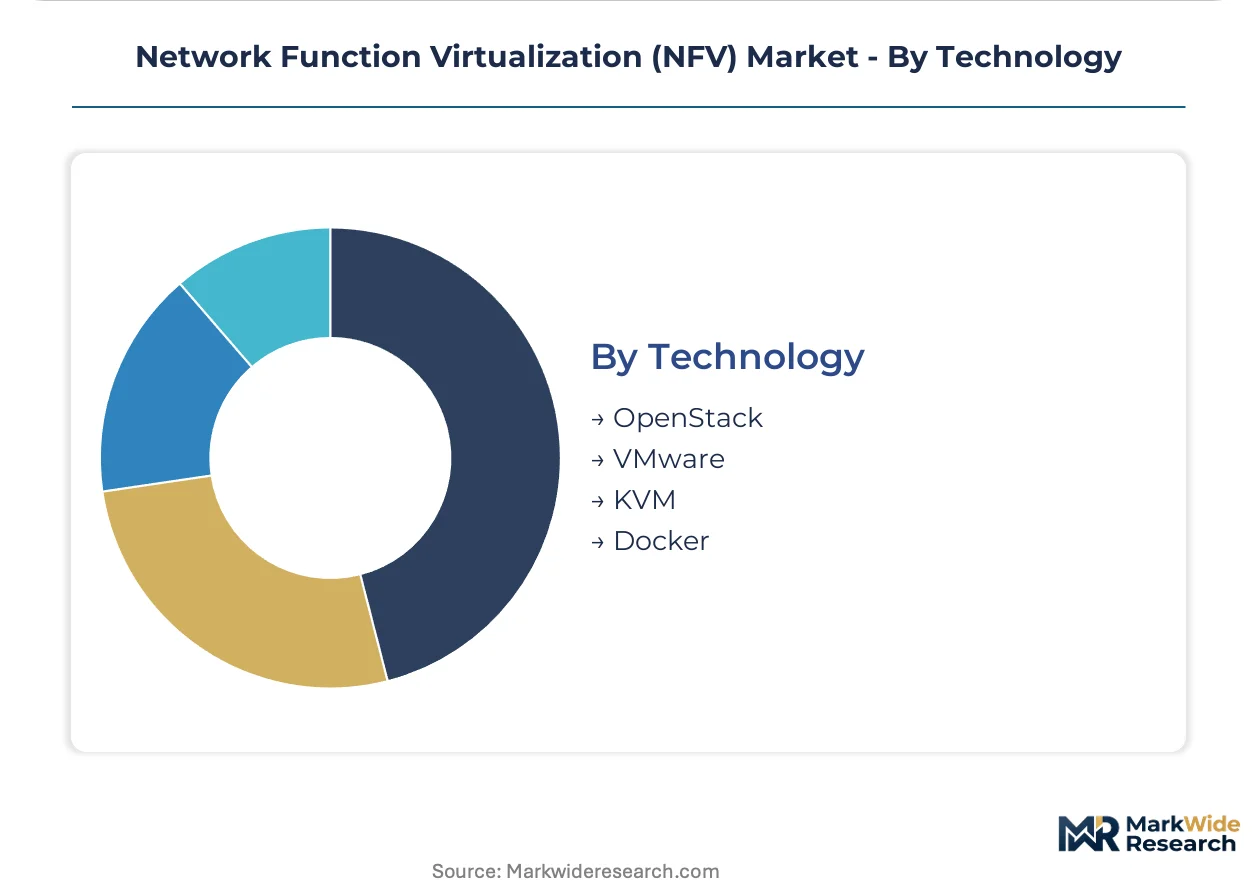
Technology:
Virtualization architecture choices commit buyers to distinct operational toolchains and talent requirements.
- Kubernetes:Container orchestration enables microservices decomposition and elastic scaling of individual network functions. Tier-1 operators in the United States replace hardware load balancers with Envoy-based service mesh architectures. GitOps pipelines demand skills scarce in traditional telecom engineering ranks.
- OpenStack:Mature telecom-grade orchestration retains significance for stateful network functions requiring persistent storage and deterministic performance. European operators mandate ETSI NFV compliance that OpenStack distributions certify most comprehensively.
- VMware:Enterprise virtualization familiarity accelerates departmental NFV pilots without container retraining investments.
- Docker:Lightweight container runtime for edge node deployments with constrained compute resources. Autonomous vehicle and industrial IoT applications drive specialized demand.
Deployment share favors OpenStack; Kubernetes gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's banking and telecommunications corridor hosts Europe's densest concentration of NFV infrastructure deployments, with Deutsche Telekom's cloud-native core serving as the continent's reference architecture for virtualized mobile networks.
United States
AT&T and Verizon drive containerized 5G standalone core rollouts across Dallas-Fort Worth and Seattle tech corridors. The FCC's open RAN initiatives mandate software-disaggregated architectures that accelerate NFV procurement timelines. Denver and Phoenix data center clusters host the largest hybrid cloud network function deployments outside hyperscaler facilities.
Germany
Deutsche Telekom and Vodafone Germany prioritize ETSI-compliant virtualized cores under EU Green Deal procurement mandates. BNetzA requires re-certification for each software version update, compressing vendor release cycles. Munich and Stuttgart manufacturing hubs deploy private 5G campus networks with localized NFV stacks for industrial automation.
Japan
NTT Docomo and KDDI advance containerized core implementations in Tokyo and Osaka metropolitan zones. Japan's MIC imposes sequential approval processes that conflict with continuous delivery pipelines. Yokohama's smart city initiatives pilot GPU-accelerated virtualized functions for AI-driven traffic engineering.
China
China Mobile and China Telecom scale OpenStack-based virtualized cores across Beijing-Tianjin-Hebei and Yangtze River Delta corridors. MIIT standards prioritize domestic silicon integration in NFV infrastructure procurement. Shenzhen's equipment vendors supply end-to-end 5G core solutions throughout Asia-Pacific markets despite trade restrictions.
India
Reliance Jio and Bharti Airtel deploy cloud-native network functions in Mumbai and Bangalore data center clusters. TRAI spectrum policies accelerate virtualization timelines for 5G service launches. Hyderabad's systems integrators build NFV practices serving mid-market enterprises lacking internal cloud-native engineering capacity.
Network Function Virtualization (NFV) Market Vendor Landscape
The competitive structure tilts toward diversified technology conglomerates with existing carrier relationships. Vendor concentration remains moderate, with incumbent telecom equipment suppliers holding core network positions while enterprise software vendors encroach on edge and campus deployments. Three archetypes dominate: cloud-native specialists, legacy equipment incumbents with virtualization portfolios, and systems integrators packaging multi-vendor stacks. Competitive intensity centers on ETSI compliance certification and energy efficiency benchmarking under EU procurement rules.
Among legacy equipment incumbents, Nokia Corporation exemplifies the European carrier-centric archetype with cloud-native core specialization. Cisco Systems anchors enterprise NFV deployments through integrated security and routing virtualization portfolios. Huawei Technologies occupies a position in Asia-Pacific markets with end-to-end 5G core solutions, though trade restrictions constrain geographic reach. Mavenir represents the cloud-native specialist archetype with container-first architectures targeting open RAN and private 5G segments.
| Leading Market Players |
|---|
| Nokia Corporation |
| VMware |
| Cisco Systems |
| AT&T |
| Amdocs |
| Huawei Technologies |
| Juniper Networks |
| Mavenir |
| Ericsson |
| Others |
Supply Flow & Price Mechanics
Tier-1 telecom operators in Germany and Japan concentrate procurement volume for containerized core implementations, anchoring value-based pricing models tied to network uptime guarantees and throughput scalability rather than perpetual software licenses.
Pricing Analysis
Outcome-based pricing tied to service availability metrics anchors NFV commercial structures. Three-tier pricing structure across premium, standard, and economy levels separates ETSI-compliant certified stacks from uncertified alternatives and open-source distributions. Price differentiation rests on energy efficiency benchmarking under EU Green Deal procurement mandates and multi-vendor integration complexity. Cost compression in standard-tier deployments is intensifying because hyperscalers are entering managed services competition. Enterprise manufacturing verticals exhibit highest price sensitivity, while defense contractors and sovereign cloud operators show lowest.
Supply Chain Analysis
Cloud-native engineering talent scarcity in Bangalore and Shenzhen constrains deployment velocity for Kubernetes-orchestrated network functions. High-performance server CPU and SmartNIC fabrication concentrates in Taiwan, South Korea, and the United States. Raw material dependencies span silicon wafers, advanced packaging substrates, and specialized networking ASICs. Single-source vulnerability in three-fabrication-site concentration for x86 and ARM-based processors threatens allocation certainty. Distribution runs through systems integrators building independent NFV practices in Frankfurt, Tokyo, and Dallas-Fort Worth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NFV procurement represents a hardware-to-software transition phase as Kubernetes container orchestration displaces OpenStack hypervisor architectures across telecom core networks.
For Market Incumbents: Hedge against hyperscaler encroachment by deepening managed services recurring revenue and securing ETSI NFV compliance certification ahead of EU tender mandates. Incumbents must accelerate cloud-native engineering recruitment to match emerging specialist firms' deployment velocity. Vertical integration into SmartNIC silicon design mitigates foundry allocation risk. For New Entrants and Emerging Players: The mid-market price-point gap between premium ETSI-certified stacks and economy-tier open-source distributions offers white-space entry. Target private 5G campus deployments in Stuttgart and Yokohama manufacturing hubs lacking internal cloud-native capacity. Go-to-market through channel partners building NFV practices independent of vendor professional services organizations. For Investors and Strategic Acquirers: Distressed-cycle entries favor container-first specialists with proven Kubernetes service mesh deployments in Asia-Pacific markets. Long-term viability hinges on sustained R&D commitment across multi-vendor integration tooling. Watch ETSI compliance certification timelines as inflection indicator for vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ETSI Compliance Certification | European operators now mandate standardized reference architectures in core network tenders. |
| Kubernetes Service Mesh Integration | Tier-1 carriers in Dallas-Fort Worth replace hardware load balancers with Envoy-based sidecar proxies. |
| SmartNIC Silicon Partnership | NFV infrastructure vendors secure allocation certainty for x86 and ARM-based processor supply. |
| Private 5G Campus Packaging | Systems integrators in Stuttgart bundle pre-certified stacks for manufacturing automation buyers. |
| Energy Efficiency Benchmarking | Verified power consumption metrics qualify virtualized functions for EU Green Deal preferential scoring. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this NFV market assessment. Primary interviews with cloud-native platform engineers, telecom procurement directors, systems integrators, and ETSI standards committee participants combined with secondary validation from FCC open RAN initiative documentation, BNetzA certification registries, and hyperscaler capex disclosures. Bottom-up deployment tallies and top-down infrastructure spending estimates underwent triangulation.
Data-stream reconciliation across deployment model, service type, end user vertical, and virtualization technology dimensions shaped the analytical framework. CAGRs were derived from segmented adoption curves and infrastructure refresh cycle compression. Industry-specific forecast inputs incorporated 5G standalone core rollout timelines and EU Green Deal procurement weighting shifts across the analysis window.
Inputs from regulatory certification databases and operator procurement portals were available through the study window; gaps in private 5G enterprise deployment tallies introduce uncertainty bands. Forecasts reflect assumptions around container orchestration standardization velocity and sovereign cloud mandate expansion. Material deviation in ETSI compliance adoption rates or foundry allocation disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Europe Data Center Networking Market
Data Center and Networking
Network Slicing Market
Data Center and Networking
Fog Networking Market
Data Center and Networking
Global Virtual Private Server Market
Data Center and Networking
Communications Service Provider (CSP) Network Market
Data Center and Networking
Global Optical Communication and Networking Market
Data Center and Networking
Data Deduplication Tools Market
Data Center and Networking
North America Data Center Networking Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
Sweden Data Center Networking Market
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
Germany Data Center Networking Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
United Kingdom Data Center Networking Market
Data Center and Networking
North America Subscriber Data Management Market