
 Network Consulting Services Market | 2026-2036
Network Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Network Consulting Services Market Analysis
North American systems integrators is realigning around cloud-native network architectures and zero-trust security frameworks. Cisco Systems dominates enterprise routing and switching consulting through its certified partner ecosystem and proprietary design methodologies. IBM Global Services anchors large-scale transformation programs with deep mainframe-to-cloud integration expertise. Accenture leverages its strategy consulting heritage to bundle network modernization with broader digital transformation roadmaps.
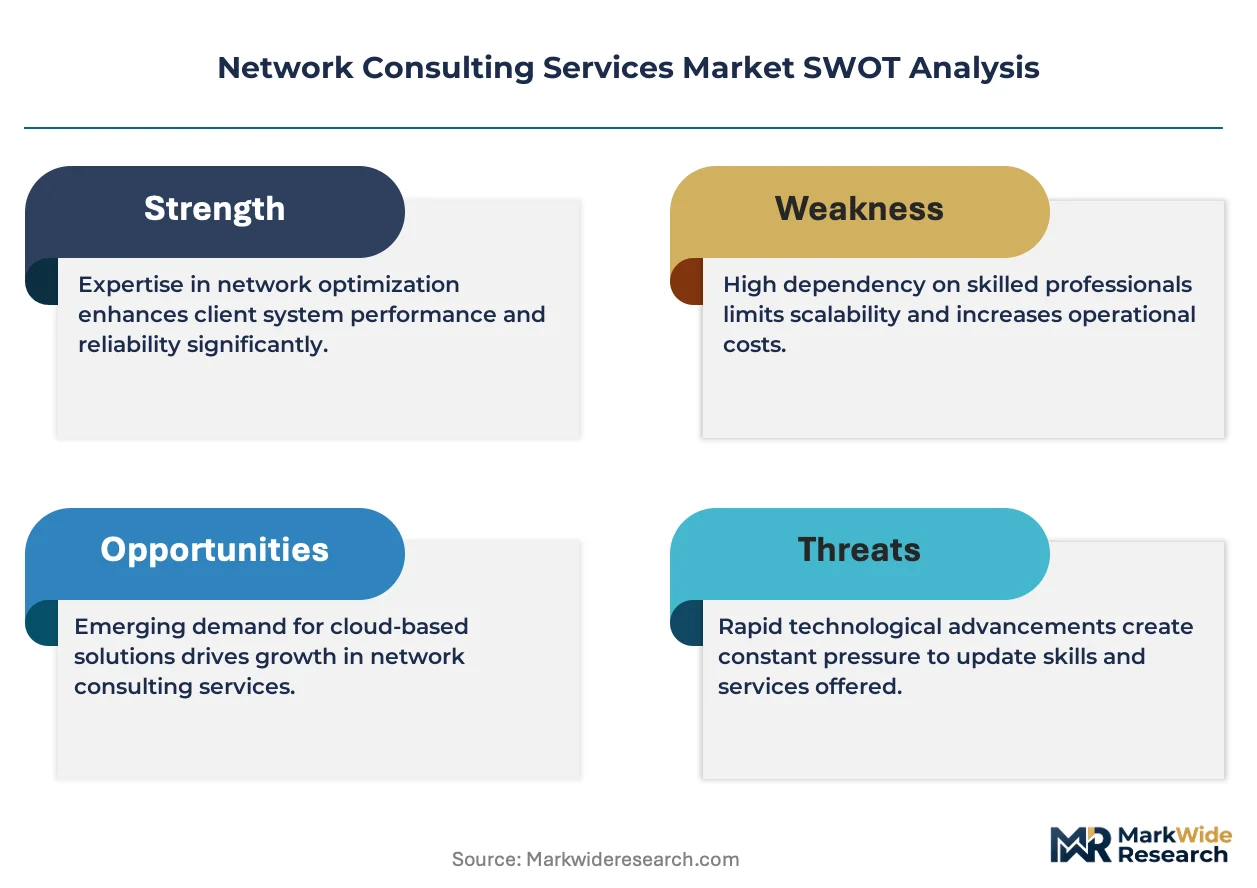
Network consulting services encompass the assessment, design, implementation, and optimization of enterprise communication infrastructure, including latency thresholds below 5 milliseconds for real-time applications and redundant path architectures ensuring 99.999% uptime availability. These services enable organizations to align physical and virtual network layers with business continuity requirements and cybersecurity postures. Security consulting commands premium pricing due to regulatory complexity and talent scarcity, while cloud-based deployment models are expanding fastest as enterprises exit owned data centers. SD-WAN technology segments are maturing rapidly with vendor consolidation, though network automation represents the emerging margin pool where specialized skills remain scarce.
FCC guidelines on broadband infrastructure deployment, EU GDPR data residency requirements, and HIPAA security rule mandates for healthcare networks collectively shape compliance-driven demand for documented network architectures and audit-ready configurations. NIST cybersecurity frameworks further tighten procurement specifications for government agencies and defense contractors. Stakeholders must monitor how AI-driven network operations tools reshape workforce requirements and service delivery models.
Market Dynamics
Enterprise migration from hardware-centric networks to software-defined architectures is compressing traditional consulting margins while expanding automation-led service lines. This structural shift forces incumbents to retrain delivery teams and rebalance revenue mix toward recurring managed services.
Growth Catalysts
- EU AI Act enforcement:Enterprises across Germany, France, and Italy are commissioning network architecture reviews to ensure AI training clusters meet data residency and audit trail requirements.
- Industrial edge computing:Automotive and manufacturing facilities in Stuttgart and Wolfsburg are deploying sub-5-millisecond latency networks, requiring specialized RF planning and redundant path design consulting.
- HIPAA security rule audits:US healthcare systems are procuring documented network segmentation assessments to demonstrate compliance with access control and transmission security mandates.
Market Restraints
- Certified engineer scarcity:Cisco CCIE and AWS networking specialist credentials command 40-60% salary premiums, constraining project scaling for mid-tier consultancies.
- Vendor consolidation in SD-WAN:VMware-VeloCloud and Cisco-Viptela acquisitions have reduced independent platform options, locking consulting firms into single-vendor implementation playbooks.
- Cloud repatriation hesitation:Enterprises that moved workloads to public clouds are now delaying network redesigns due to sunk cost concerns and contractual lock-in with hyperscalers.
Strategic Opportunities
- Network-as-a-Service bundling:Consulting firms can wrap design, implementation, and lifecycle management into single subscription contracts, capturing recurring revenue from mid-market manufacturers.
- Private 5G campus networks:Industrial sites in Germany's Ruhr region and France's Lyon corridor are seeking turnkey design-to-operate partnerships for spectrum-licensed local networks.
- NIST framework adoption:US federal contractors and defense industrial base suppliers are mandating zero-trust architecture assessments, creating compliant service packaging opportunities.
Industry Challenges
- Multi-cloud orchestration complexity:Consulting teams struggle to maintain expertise across AWS, Azure, and GCP networking stacks simultaneously, fragmenting project staffing.
- Legacy mainframe integration:Financial services modernization programs require consultants who bridge IBM z/OS networking protocols with Kubernetes container orchestration, a skill intersection with limited supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Consulting Services Market |
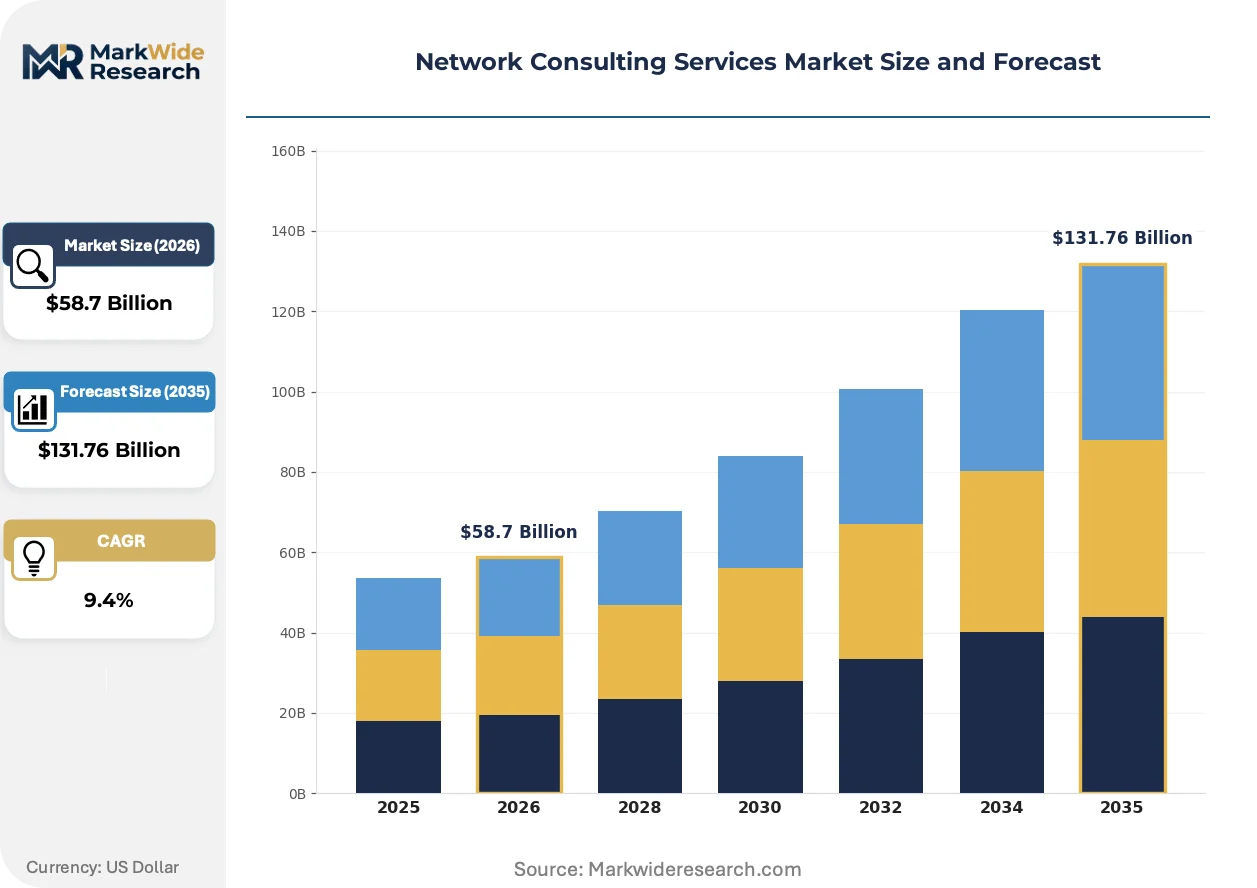
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $131.76 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Network Design, Network Optimization, Security Consulting, Performance Monitoring Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services Client Type: Small Enterprises, Large Corporations, Government Agencies, Nonprofits Technology: SD-WAN, VoIP, Firewall Solutions, Network Automation |
| Companies Covered | Hewlett Packard Enterprise, IBM Global Services, Cisco Systems, Capgemini, HCL Technologies, Accenture, Amazon Web Services, Lumen Technologies, Deloitte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Consulting Services Market Emerging Trajectories
Artificial intelligence is embedding into network operations tools, compressing mean-time-to-resolution metrics and forcing consulting firms to redefine their value proposition around strategic architecture rather than reactive troubleshooting.
Intent-based networking software is automating configuration drift detection and self-healing across enterprise campuses and branch locations. Fortune 500 retailers and logistics operators are deploying these platforms aggressively, reducing their dependence on break-fix support contracts. This capability shift is automating tier-one troubleshooting work that historically consumed 30-40% of consulting hours.
The EU AI Act's risk classification system is mandating documented network isolation for high-risk AI systems processing personal data. German automotive suppliers and French healthcare AI developers must now demonstrate segmentation controls through third-party assessments. This regulatory layer is expanding security consulting scopes to include AI infrastructure topology reviews.
Enterprise buyers are unbundling implementation from ongoing optimization, awarding design contracts to strategy-heavy firms while pushing operational work to managed service providers. This bifurcation is visible most acutely in the US financial services sector, where CIOs maintain separate vendor rosters for transformation architecture and run-state support.
Network Consulting Services Market Segmentation
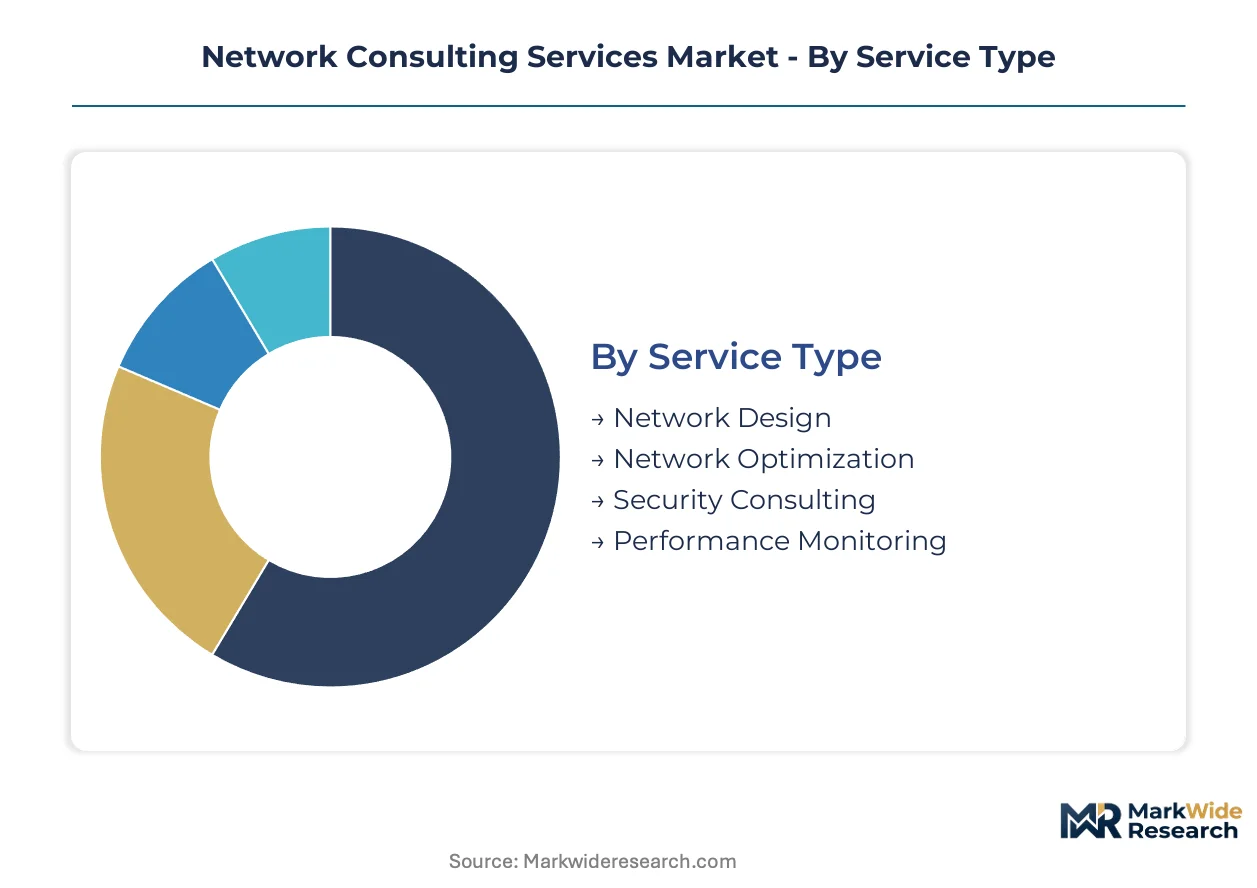
Network consulting engagements fragment sharply by integration depth, with standalone advisory contracts commanding premium pricing while embedded implementation services scale through recurring revenue models. Service providers must align capability investments to where segments intersect with compliance mandates and latency-sensitive workloads.
Service Type:
Standalone advisory segments operate at higher margins but require discrete project wins, while embedded optimization services integrate into ongoing operational budgets with longer sales cycles.
- Network Design:Encompasses topology planning, capacity modeling, and redundancy architecture for sub-5-millisecond latency requirements. German automotive manufacturers in Stuttgart and Wolfsburg commission these services for industrial edge computing deployments where RF planning expertise commands scarcity premiums.
- Security Consulting:Delivers documented network segmentation assessments, zero-trust architecture reviews, and audit-ready configurations for regulatory compliance. US healthcare systems procuring HIPAA-mandated transmission security documentation drive concentrated demand alongside EU AI Act data residency reviews.
- Network Optimization:Post-implementation tuning and performance validation services.
- Performance Monitoring:Continuous latency and availability tracking with automated alerting integration.
Volume placements concentrate in Network Design; the faster expansion belongs to Security Consulting.
Deployment Model:
Cost tier stratification separates capital-intensive ownership models from operational expenditure approaches that accelerate procurement approvals.
- Cloud-Based:Delivers scalable network infrastructure through subscription frameworks, eliminating hardware procurement cycles. Enterprises exiting owned data centers in France and Italy favor this model for rapid AI training cluster deployment under EU data residency constraints.
- Managed Services:Bundles design, implementation, and lifecycle management into single recurring contracts. Mid-market manufacturers across Germany's Ruhr region adopt these partnerships to internalize operational complexity without captive engineering benches.
- On-Premises:Traditional hardware-centric deployment with full capital ownership.
- Hybrid:Split architectures maintaining sensitive workloads locally while bursting to cloud.
Managed Services captures the largest contract volume; cloud-based configurations are climbing the fastest as hyperscaler networking matures.
Client Type:
Application complexity and procurement sophistication separate segments, with regulated industries demanding documented architectures that informal buyers bypass.
- Government Agencies:Mandates NIST cybersecurity framework compliance and zero-trust assessments for federal contractors and defense industrial base suppliers. US procurement specifications require audit-ready network configurations with formal change documentation.
- Large Corporations:Multi-site transformation programs spanning mainframe-to-cloud integration. Financial services firms modernizing legacy IBM z/OS protocols alongside Kubernetes orchestration create demand for rare skill intersections.
- Small Enterprises:Standardized SD-WAN deployments with limited customization scope.
- Nonprofits:Cost-constrained implementations prioritizing grant-funded security baselines.
Large Corporations dominate absolute spending; Government Agencies show the steepest expansion trajectory under tightening federal cybersecurity mandates.
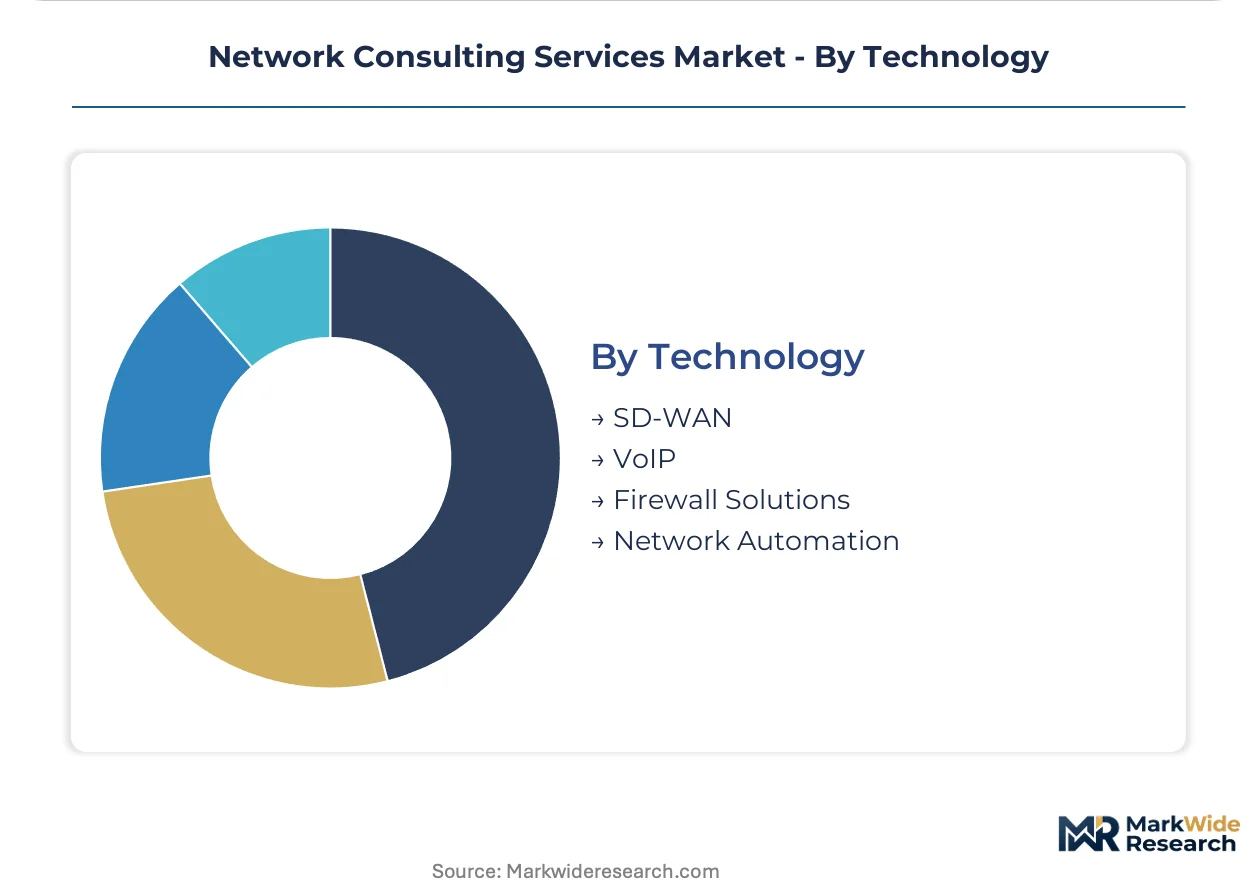
Technology:
Maturity curves and margin erosion differentiate segments, with established platforms facing vendor consolidation pressure while emerging stacks retain scarcity pricing.
- Network Automation:Intent-based configuration management and self-healing infrastructure that compresses mean-time-to-resolution metrics. Fortune 500 retailers deploy these platforms aggressively, forcing consulting firms to pivot value propositions toward strategic architecture as tier-one troubleshooting automates.
- SD-WAN:Software-defined wide area networking with centralized policy orchestration. VMware-VeloCloud and Cisco-Viptela acquisitions have reduced independent platform options, locking consultancies into single-vendor implementation playbooks with compressed differentiation.
- VoIP:Voice-over-IP unified communications planning and quality-of-service tuning.
- Firewall Solutions:Perimeter and microsegmentation security architecture design.
SD-WAN holds the broadest installed base; Network Automation is gaining share fastest as AI-driven operations tools reshape workforce requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's hyperscaler concentration anchors North American demand for cloud-native network architecture consulting. German industrial clusters drive European procurement for latency-sensitive edge computing infrastructure. Asian financial centers in Singapore and Tokyo commission compliance-heavy security consulting for cross-border data flows.
United States
Federal contractors face NIST cybersecurity framework mandates requiring zero-trust architecture assessments and documented network segmentation. HIPAA security rule audits compel healthcare systems in Boston and Minneapolis to procure transmission security documentation. The Pentagon's defense industrial base suppliers in Virginia and California drive concentrated demand for audit-ready configurations.
Germany
EU AI Act enforcement compels automotive suppliers in Stuttgart and Wolfsburg to commission network isolation reviews for AI training clusters. GDPR data residency requirements shape procurement specifications for cloud-based deployment models. Industrial digitization investments across the Ruhr region accelerate private 5G campus network consulting for manufacturing facilities.
United Kingdom
Financial services firms in the City of London modernize legacy IBM mainframe networking protocols alongside Kubernetes container orchestration. Post-Brexit data sovereignty rules reshape cross-border network architecture requirements for multinational headquarters. Edinburgh's fintech cluster drives specialized demand for sub-5-millisecond latency trading infrastructure design.
France
Healthcare AI developers in Paris and Lyon must demonstrate network segmentation controls under EU AI Act risk classification mandates. CNIL enforcement of GDPR technical measures elevates security consulting premiums for documented audit trails. The Lyon corridor's pharmaceutical manufacturing sites seek turnkey private 5G design-to-operate partnerships.
Japan
METI industrial digitization subsidies accelerate network automation adoption among Osaka-based precision manufacturers. Tokyo's financial exchanges commission redundant path architectures ensuring 99.999% uptime for high-frequency trading systems. Automotive connectivity investments in Nagoya's Chubu region require specialized RF planning for vehicle-to-infrastructure networks.
Network Consulting Services Market Vendor Landscape
Global majors compete with regional champions across certification ecosystems and vertical specialization depth. The vendor base organizes into three tiers: integrated technology providers with proprietary design methodologies, strategy-heavy consultancies bundling network modernization with digital transformation, and mid-tier specialists concentrated in compliance-heavy regulated industries. Dominant competitive moves include retraining delivery teams for automation-led service lines and rebalancing revenue mix toward recurring managed services subscriptions.
Within the integrated technology tier, Cisco Systems and IBM Global Services exemplify divergent archetypes—one anchored in certified partner ecosystems for enterprise routing and switching, the other in mainframe-to-cloud integration expertise for large-scale transformation programs. Accenture occupies a position bridging strategy consulting heritage with network modernization roadmaps. Hewlett Packard Enterprise and Capgemini represent European-rooted alternatives competing on hybrid cloud networking and industrial edge computing specialization respectively.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| IBM Global Services |
| Cisco Systems |
| Capgemini |
| HCL Technologies |
| Accenture |
| Amazon Web Services |
| Lumen Technologies |
| Deloitte |
| Others |
Supply Flow & Price Mechanics
Captive engineering talent pools in Germany, India, and Poland anchor supply positioning and pricing power for network consulting services, with firms maintaining certified delivery benches capturing premium project economics while outsourced labor models compete on cost efficiency.
Pricing Analysis
Warranty and post-implementation support bundling separates premium consulting engagements from unbundled design-only contracts. Project-based pricing with outcome-based milestones dominates security consulting, where HIPAA and EU AI Act documentation requirements command scarcity premiums. Price differentiation rests on certification tier—Cisco CCIE and AWS networking specialists earn 40-60% salary premiums—and vertical specialization depth. Cost compression in SD-WAN implementation is intensifying because vendor consolidation has reduced platform choice. Small enterprises exhibit highest price sensitivity, while government agencies under NIST mandates show lowest.
Supply Chain Analysis
Engineering workforce availability in Bangalore, Warsaw, and Berlin determines delivery capacity for network automation and zero-trust architecture projects. Talent pipelines draw from university partnerships, vendor certification programs, and military cybersecurity exits. Single-source vulnerability concentrates in Cisco and VMware platform expertise, where acquisition-driven consolidation has narrowed implementation playbooks. Distribution runs through direct enterprise sales, hyperscaler marketplace listings, and systems integrator subcontracting networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified engineer scarcity props pricing across all service tiers, with CCIE and AWS networking credential gaps constraining project scaling and sustaining margin premiums for qualified delivery benches.
For Market Incumbents: Extend managed services subscriptions to capture recurring revenue from mid-market manufacturers exiting captive engineering investments. Acquire boutique security consultancies in Germany and France to deepen EU AI Act compliance expertise. Consolidate vendor certification partnerships before hyperscalers verticalize networking services. For New Entrants and Emerging Players: The price-point gap between premium strategy-heavy firms and economy-tier implementation shops creates entry space for mid-market network-as-a-service bundling. Target private 5G campus networks in Germany's Ruhr region and France's Lyon corridor, where industrial buyers seek turnkey design-to-operate partnerships without legacy vendor lock-in. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler platform acquisitions and private equity roll-ups of regional compliance specialists. Network automation capabilities retain scarcity value across a 5-10 year capability build window. Watch NIST framework adoption velocity among US federal contractors as inflection indicator for zero-trust consulting demand.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Services Subscription Conversion | Captures recurring revenue from manufacturers in Germany's industrial clusters seeking operational flexibility. |
| EU AI Act Compliance Certification | Opens documented network architecture reviews for automotive suppliers in Stuttgart and Wolfsburg. |
| Private 5G Campus Network Partnership | Delivers turnkey spectrum-licensed infrastructure for Lyon pharmaceutical manufacturing sites. |
| Network Automation Capability Build | Positions consulting teams for intent-based configuration management as tier-one troubleshooting automates. |
| Zero-Trust Architecture Assessment Packaging | Addresses NIST mandate compliance for US defense industrial base suppliers in Virginia and California. |
Methodological Framework
Multi-period observation of certified engineer salary premiums, project backlog durations, and vendor certification velocity anchored the trend analysis, supplemented by interviews with network operations directors, cybersecurity compliance officers, hyperscaler partnership managers, and mid-market CIOs. Secondary validation drew from FCC broadband deployment filings, EU AI Act implementation guidance, NIST cybersecurity framework updates, and hyperscaler networking capex disclosures. Bottom-up project pipeline tracking and top-down market sizing triangulated demand estimates.
Segment-weighting approaches distributed value across service type, deployment model, client vertical, and technology stack dimensions throughout the forecast period. CAGRs derived from regression analysis of historical consulting spend against IT infrastructure investment cycles and regulatory enforcement timelines. Intent-based networking adoption curves and mainframe-to-cloud integration project backlogs fed industry-specific trajectory inputs.
Inputs from certification vendor reporting and government procurement databases were available through the study window; gaps in private mid-market project win rates introduce uncertainty bands around segment splits. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and hyperscaler service expansion. Material deviation in EU AI Act audit frequency or Cisco certification program scaling warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Europe Managed Services Market
Enterprise Services
Workforce Management Market
Enterprise Services
Global Supply Chain As a Service (Scaas) Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Global AWS Managed Services Market
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
Proactive Services Market
Enterprise Services
North America Public Sector Consulting and Advisory Services Market
Enterprise Services
Global Intranet As a Service Market
Enterprise Services
Enterprise A2P SMS Market
Enterprise Services
Global Enterprise Data Warehouse (EDW) Market
Enterprise Services
Global Enterprise Content Collaboration Market
Enterprise Services
Asia-Pacific Warehouse Management Systems Market
Enterprise Services
Shared Services Center Market
Enterprise Services
Qatar Cloud Managed Services Market
Enterprise Services
United States Managed Services Market