
 South Korea Data Center Networking Market | 2026-2036
South Korea Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Data Center Networking Market Insights
South Korea's Green Data Center Certification System is hardening efficiency requirements for network power consumption and thermal management. Cisco Systems Inc anchors its position through deep channel relationships with domestic system integrators serving government cloud projects. Arista Networks Inc specializes in high-density leaf-spine architectures optimized for AI workload east-west traffic patterns. Huawei Technologies Co Ltd navigates procurement restrictions by focusing on private enterprise and colocation segments outside sensitive public infrastructure.
South Korea data center networking encompasses the interconnected switching, routing, and software-defined fabric infrastructure enabling compute-to-compute and compute-to-storage communication within and between facilities, typically operating at 100G/400G port speeds with sub-microsecond latency requirements for high-performance computing environments. Ethernet switches dominate physical layer expenditure as hyperscalers deploy 400G spine layers to support GPU cluster scaling. Software-defined networking represents the fastest-growing technology dimension as cloud service providers and colocation providers adopt intent-based automation to reduce operational overhead across multi-tenant environments. Load balancers command premium positioning within the product mix due to their critical role in distributing AI inference traffic across distributed compute nodes.
MFDS data integrity standards intersect with network security protocols for pharmaceutical and biotech cloud deployments, while KISA's cloud security certification program shapes vendor qualification requirements for public sector contracts. BIS technical standards govern electromagnetic compatibility and energy efficiency benchmarks for networking equipment deployed in certified green facilities. Stakeholders must weigh domestic certification compliance against interoperability with global hyperscale architectures when selecting core switching platforms.
Market Dynamics
AI training cluster expansion in the Pangyo-Yongin corridor is compressing network refresh cycles from five years to eighteen months as hyperscalers chase GPU-to-GPU bandwidth density.
Growth Catalysts
- Green Data Center Certification System:MFDS efficiency mandates are accelerating replacement of legacy switching hardware with liquid-cooled spine architectures in pharmaceutical cloud facilities.
- AI inference traffic patterns:East-west data flows between GPU nodes now dominate rack-level design, pulling 400G port deployment forward by two generations.
- Seoul-Busan cloud corridor:Government cloud consolidation projects are concentrating procurement authority with domestic system integrators holding KISA security certifications.
Market Restraints
- Optical transceiver supply concentration:Single-source dependency on Taiwanese 800G coherent DSP modules creates six-month lead time vulnerability for spine layer upgrades.
- Copper price volatility:Raw material swings in high-speed cable assemblies are compressing gross margins on top-of-rack switch deployments by twelve to fifteen points.
- Procurement restrictions on foreign vendors:Sensitive public infrastructure projects now require KISA-certified equipment, excluding non-domestic supply for core routing layers.
Strategic Opportunities
- Busan maritime edge zones:Underpenetrated colocation capacity near submarine cable landing stations offers low-latency interconnection arbitrage for AI inference serving Japan and Taiwan markets.
- Intent-based automation convergence:Integration of telemetry analytics with closed-loop remediation is opening managed fabric services revenue streams for domestic operators.
- Biotech cloud specialization:MFDS data integrity requirements for genomic pipelines are creating certified networking service tiers priced at forty percent premiums over standard colocation.
Industry Challenges
- Silicon photonics packaging expertise:Domestic supply of co-packaged optics engineering talent remains concentrated with three research institutes, constraining 51.2T switch development timelines.
- Legacy SONET/SDH migration friction:Financial services incumbents in Yeouido maintain parallel circuit-switched backup networks, doubling certification complexity for software-defined fabric rollouts.
- Multi-vendor interoperability testing:KISA security certification requires six-month validation cycles against domestic encryption modules, delaying multi-tenant environment launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Data Center Networking Market |
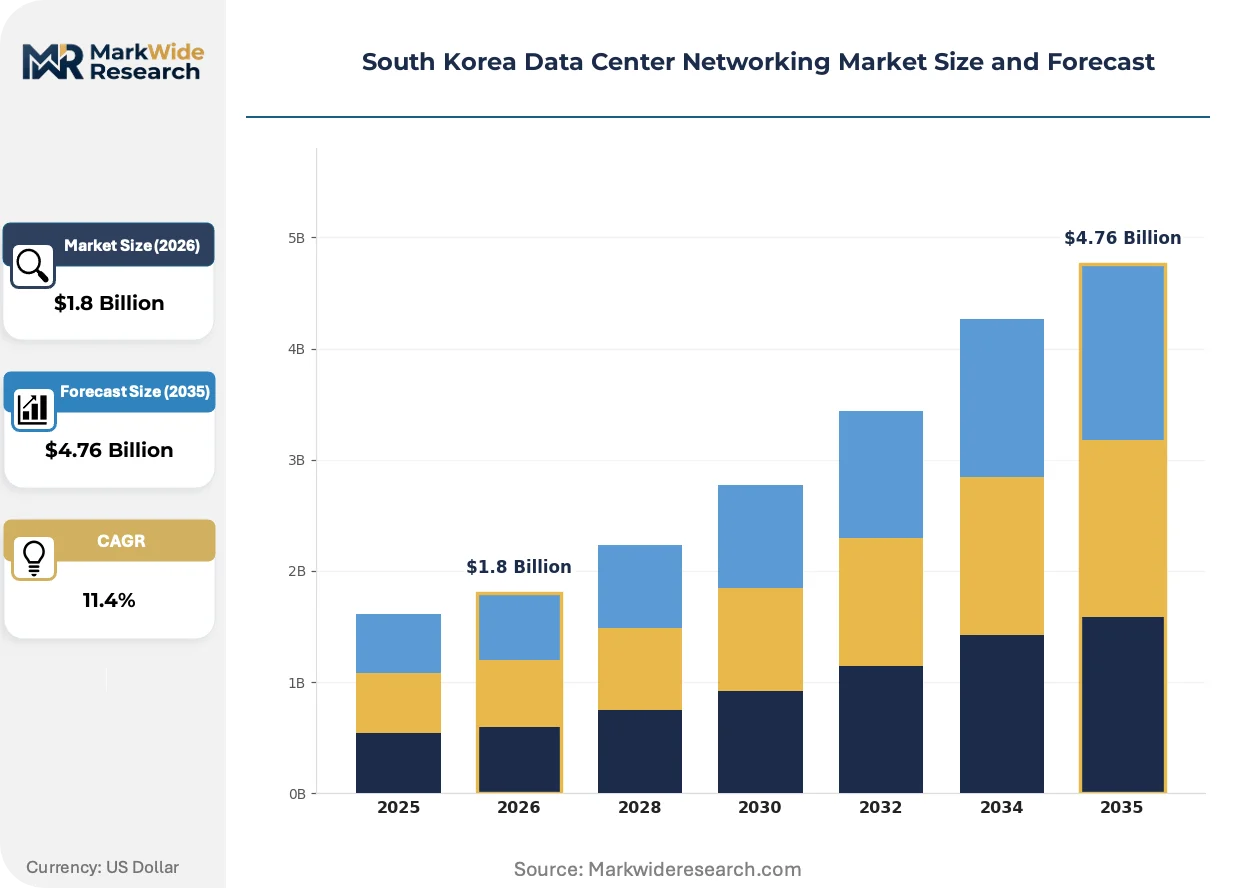
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Load Balancers, Network Interface Cards Technology: Ethernet, Fiber Channel, InfiniBand, Software-Defined Networking End User: Cloud Service Providers, Colocation Providers, Enterprises, Government Institutions Deployment Model: On-Premises, Hybrid, Multi-Cloud, Dedicated |
| Companies Covered | F5 Inc, Broadcom Corporation, Cisco Systems Inc, Dell Technologies, Hewlett Packard Enterprise, Arista Networks Inc, Juniper Networks Inc, Huawei Technologies Co Ltd, NVIDIA (Cumulus Networks Inc), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Data Center Networking Market Trends and Innovations
Co-packaged optics and liquid-cooled switching substrates are compressing power-per-bit metrics while KISA certification requirements are hardening procurement specifications for public sector deployments.
Silicon photonics is integrating electrical-to-optical conversion directly onto switch ASIC packages, eliminating pluggable transceivers from high-density spine positions. Naver Cloud and Kakao Enterprise are piloting 51.2T co-packaged platforms in their Pangyo training facilities ahead of general availability. This integration is collapsing physical layer cost structures while introducing new thermal management constraints requiring direct-to-chip liquid cooling.
KISA's cloud security certification program now mandates hardware root-of-trust attestation for all network equipment processing government data workloads. The framework requires domestic cryptographic module integration, creating bifurcated product SKUs between public and private deployment contexts. Equipment vendors are responding with KISA-certified variants manufactured at local integration facilities to preserve public sector access.
Consumption-based network capacity contracts are displacing traditional capital purchase models among mid-sized colocation tenants in Yongin. Monthly subscription pricing for spine-layer bandwidth allows AI startups to align networking costs with training job scheduling rather than peak-provisioned capacity. This shift is most visible in the biotech vertical, where MFDS-regulated workloads require burst elasticity without permanent infrastructure commitment.
South Korea Data Center Networking Market Segmentation
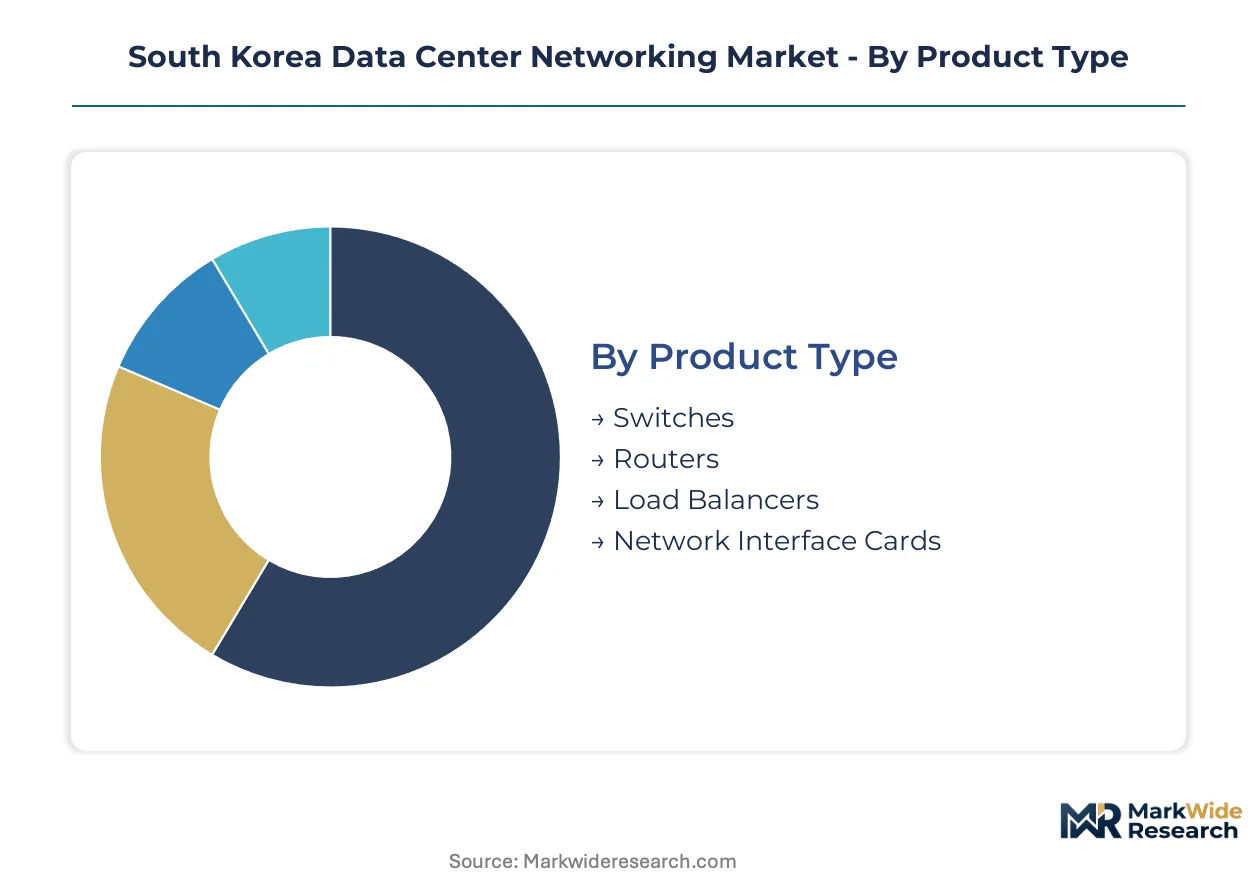
Segmentation in South Korea's data center networking market reveals divergent procurement patterns between hyperscale cloud operators and regulated enterprise deployments. Understanding these splits enables vendors to align certification requirements with customer infrastructure maturity.
Product Type:
Ethernet switches command the volume tier while load balancers capture premium positioning through AI inference traffic management.
- Switches:Spine and leaf architectures operating at 400G port speeds form the physical foundation of hyperscale facilities in Pangyo. Naver Cloud and Kakao Enterprise are compressing refresh cycles to eighteen months as GPU cluster density requirements intensify.
- Load Balancers:Application delivery controllers distribute AI inference workloads across distributed compute nodes with sub-microsecond latency requirements. MFDS-certified biotech cloud deployments in Songdo command forty percent pricing premiums for these specialized configurations.
- Routers:Border gateway infrastructure enabling Seoul-Busan cloud corridor connectivity with KISA-mandated encryption modules.
- Network Interface Cards:SmartNICs with DPU offloading capabilities for bare-metal cloud instances in Yongin colocation facilities.
Mature deployment sits with switches at legacy 100G port densities. Newer deployment is concentrated in 400G spine layers with liquid-cooled substrates.
Technology:
Software-defined networking is climbing the fastest as intent-based automation reduces operational overhead across multi-tenant environments.
- Software-Defined Networking:Controller-based fabrics with telemetry analytics enable closed-loop remediation for colocation providers managing hundreds of tenant environments. Domestic operators are monetizing this as managed fabric services with consumption-based pricing.
- Ethernet:Dominant physical layer protocol with 800G coherent optics development constrained by Taiwanese DSP module supply concentration. Copper price volatility is compressing gross margins on high-speed cable assemblies by twelve to fifteen points.
- InfiniBand:Low-latency interconnect for GPU-to-GPU communication in Naver Cloud's Pangyo training clusters with RDMA capabilities.
- Fiber Channel:Legacy storage area network protocols maintained by financial services incumbents in Yeouido with parallel SONET/SDH backup requirements.
Established deployment persists with Ethernet at 100G/400G port speeds. Emerging deployment concentrates in software-defined fabrics with KISA-certified hardware root-of-trust.
End User:
Cloud service providers drive volume procurement while government institutions impose the strictest certification barriers.
- Cloud Service Providers:Hyperscalers in the Pangyo-Yongin corridor are scaling 51.2T co-packaged optics platforms ahead of general availability. Silicon photonics packaging expertise remains concentrated with three domestic research institutes, constraining development timelines.
- Government Institutions:KISA cloud security certification mandates hardware attestation for all network equipment processing public data. Procurement restrictions now exclude non-domestic supply for core routing layers in sensitive infrastructure.
- Colocation Providers:Yongin-based operators offering consumption-based spine-layer bandwidth subscriptions to AI startups aligning costs with training job scheduling.
- Enterprises:Private cloud deployments in Busan maritime edge zones targeting low-latency interconnection arbitrage for Japan and Taiwan markets.
Volume concentration sits with cloud service providers at hyperscale. Regulatory complexity concentrates with government institutions requiring bifurcated product SKUs.
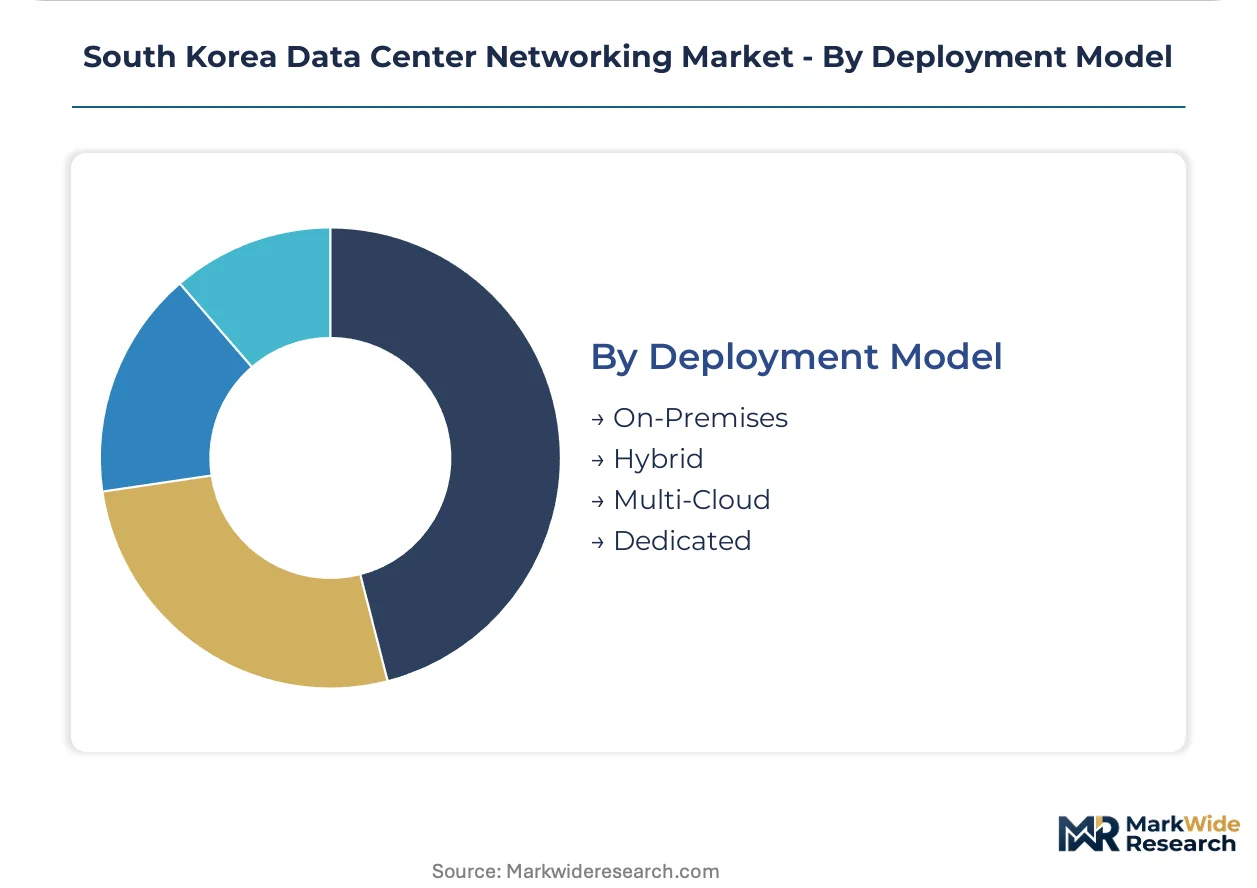
Deployment Model:
Hybrid architectures balance sovereignty requirements with burst elasticity needs in MFDS-regulated verticals.
- Hybrid:Split workload placement between on-premises certified infrastructure and public cloud burst capacity. Biotech enterprises in Songdo leverage this for genomic pipelines requiring MFDS data integrity without permanent infrastructure commitment.
- Multi-Cloud:Interconnection fabrics spanning Naver Cloud, Kakao Enterprise, and international hyperscalers with consistent policy enforcement. KISA security certification requires six-month validation cycles against domestic encryption modules, delaying environment launches.
- On-Premises:Fully captive facilities for defense and intelligence workloads with air-gapped network segmentation.
- Dedicated:Single-tenant cage deployments in Busan submarine cable landing stations for content delivery networks serving East Asian markets.
Legacy deployment persists with on-premises sovereign facilities. Expansion concentrates in hybrid configurations bridging certified private infrastructure with elastic public resources.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pangyo-Yongin corridor anchors South Korea's data center networking concentration, with hyperscalers compressing refresh cycles to eighteen months as GPU cluster density requirements intensify across the Seoul Capital Area.
Seoul Capital Area
Naver Cloud and Kakao Enterprise drive 400G spine layer procurement in Pangyo technology clusters. KISA's cloud security certification mandates hardware root-of-trust attestation for all network equipment processing government data workloads. Yongin colocation providers now offer consumption-based spine-layer bandwidth subscriptions to AI startups aligning networking costs with training job scheduling.
Busan-Ulsan
Maritime edge zones near submarine cable landing stations attract low-latency interconnection arbitrage for AI inference serving Japan and Taiwan markets. BIS technical standards govern electromagnetic compatibility for networking equipment deployed in certified green facilities. Domestic operators in Busan are monetizing intent-based automation as managed fabric services with telemetry analytics.
Daegu-Gyeongbuk
Legacy financial services incumbents maintain parallel circuit-switched backup networks alongside software-defined fabric rollouts. MFDS data integrity standards intersect with network security protocols for pharmaceutical and biotech cloud deployments. The region's industrial automation sector pulls demand for deterministic Ethernet in smart factory data center extensions.
Daejeon-Sejong
Government cloud consolidation projects concentrate procurement authority with domestic system integrators holding KISA security certifications. The national research complex houses three institutes supplying silicon photonics packaging expertise for 51.2T switch development. Sejong administrative city deployments require bifurcated product SKUs between public and private deployment contexts.
Gwangju-Honam
Biotech cloud specialization in Songdo creates certified networking service tiers priced at forty percent premiums over standard colocation for genomic pipelines. MFDS-regulated workloads demand burst elasticity without permanent infrastructure commitment. The region's agricultural technology sector drives edge data center networking for precision farming analytics.
South Korea Data Center Networking Market Competitive Landscape
The competitive structure tilts toward diversified technology conglomerates with deep channel relationships serving government cloud projects. The vendor base spans three distinct tiers: premium-tier specialists in high-density leaf-spine architectures, mid-market generalists offering integrated compute-networking stacks, and domestic system integrators holding mandatory security certifications. Strategic moves concentrate on local manufacturing partnerships to preserve public sector access and co-development agreements for liquid-cooled substrate technologies.
Among US-based networking specialists, Cisco Systems Inc, Arista Networks Inc, and F5 Inc exemplify contrasting archetypes within the premium tier. Cisco anchors its position through deep channel relationships with domestic system integrators serving government cloud projects. Arista occupies a position specializing in high-density architectures optimized for AI workload traffic patterns. F5 represents the application delivery controller segment commanding premium positioning through AI inference traffic management capabilities.
| Leading Market Players |
|---|
| F5 Inc |
| Broadcom Corporation |
| Cisco Systems Inc |
| Dell Technologies |
| Hewlett Packard Enterprise |
| Arista Networks Inc |
| Juniper Networks Inc |
| Huawei Technologies Co Ltd |
| NVIDIA (Cumulus Networks Inc) |
| Others |
Pricing and Supply Chain Analysis
KISA certification mandates for government cloud workloads are forcing equipment vendors to establish local manufacturing partnerships, compressing margins on bifurcated product SKUs while creating pricing power for domestic system integrators holding security clearances.
Pricing Analysis
Throughput-based subscription pricing for spine-layer bandwidth anchors value capture in Yongin colocation facilities. Pricing stratifies across KISA-certified public sector tiers, liquid-cooled AI-optimized tiers, and standard enterprise Ethernet tiers. Cost compression in copper-based high-speed cable assemblies is intensifying because raw material volatility feeds directly into top-of-rack switch procurement. AI startups exhibit highest price sensitivity, while MFDS-regulated biotech cloud deployments show lowest sensitivity due to compliance-driven specification lock-in.
Supply Chain Analysis
Freight costs for 800G coherent optical modules from Taiwan and silicon photonics substrates from Japan are amplifying landed cost vulnerability for spine layer upgrades. The supply chain draws from Taiwanese DSP foundries, Japanese precision optics houses, and domestic Korean system integration facilities. Single-source dependency on Taiwanese coherent DSP modules creates structural vulnerability for 51.2T switch development timelines. Distribution runs through domestic system integrators holding KISA certifications for public sector access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification barriers and silicon photonics packaging bottlenecks are consolidating vendor positions, forcing non-compliant foreign suppliers toward private enterprise segments while domestic players capture public infrastructure procurement authority.
For Market Incumbents: Deepen captive silicon photonics packaging capabilities through partnerships with Daejeon's three research institutes to secure 51.2T switch development timelines. Reinforce channel control by embedding technical specialists within domestic system integrators serving Sejong government cloud consolidation projects. The threat of procurement restrictions excluding non-KISA-certified equipment demands immediate local manufacturing footprint expansion. For New Entrants and Emerging Players: Launch via managed fabric services partnerships with Yongin colocation providers offering consumption-based bandwidth subscriptions to AI startups. White-space concentrates in Busan maritime edge zones serving Japan and Taiwan inference markets with low-latency submarine cable arbitrage. Biotech cloud specialization in Songdo offers certification-premium positioning for genomic pipeline networking. For Investors and Strategic Acquirers: The window for entry favors domestic system integrators with KISA security certifications and established government relationships. Long-term viability centers on consolidation plays bridging silicon photonics R&D with public sector procurement access. Watch for MFDS regulatory expansion into broader pharmaceutical cloud compliance as the inflection signal for certified service tier proliferation.| Strategic Initiative | Industry Significance |
|---|---|
| KISA Certification Investment | Hardware root-of-trust attestation unlocks Sejong government cloud procurement authority. |
| Liquid-Cooled Substrate Partnership | Co-packaged optics integration with direct-to-chip cooling addresses Pangyo GPU density constraints. |
| Silicon Photonics R&D Alliance | Daejeon research institute collaboration accelerates 51.2T switch development timelines. |
| Busan Edge Zone Expansion | Submarine cable landing station proximity enables Japan-Taiwan inference market arbitrage. |
| Managed Fabric Service Launch | Telemetry analytics with closed-loop remediation monetizes Yongin colocation operational complexity. |
Research Methodology
Document review covered hyperscaler capex disclosures, KISA certification databases, and MFDS regulatory filings, complemented by interviews with network architects at Naver Cloud and Kakao Enterprise, procurement leads at Yongin colocation providers, and regulatory affairs specialists at domestic system integrators. Secondary validation drew from equipment vendor SEC filings, BIS technical standards documentation, and trade flow data for optical component imports. Bottom-up demand modeling triangulated against top-down infrastructure investment tracking.
Cross-referencing historical refresh cycle compression patterns against panel input from Pangyo facility operators shaped the projection framework. Segmentation dimensions modeled include product type, technology protocol, end-user vertical, and deployment architecture across the analysis window. CAGRs were derived from equipment procurement pipeline analysis and hyperscaler GPU cluster expansion schedules. Forecast inputs incorporated KISA certification timeline assumptions and silicon photonics packaging capacity constraints.
Optical component supply disruptions, KISA regulatory scope expansion, and copper price volatility are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
GPU Database Market
Data Center and Networking
DNA Digital Data Storage Market
Data Center and Networking
Data Center Networks Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
Denmark Data Center Networking Market
Data Center and Networking
Managed DNS Services Market
Data Center and Networking
Global Data Lakes Market
Data Center and Networking
Mexico Data Center Networking Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
Virtual Data Optimizer Market
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
Dynamic Data Management System Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
Mobile Data Market