
 Network Optimization Services Market | 2026-2036
Network Optimization Services Market Size, Share, and Industry Trends Forecast 2026-2036
Network Optimization Services Market Intelligence
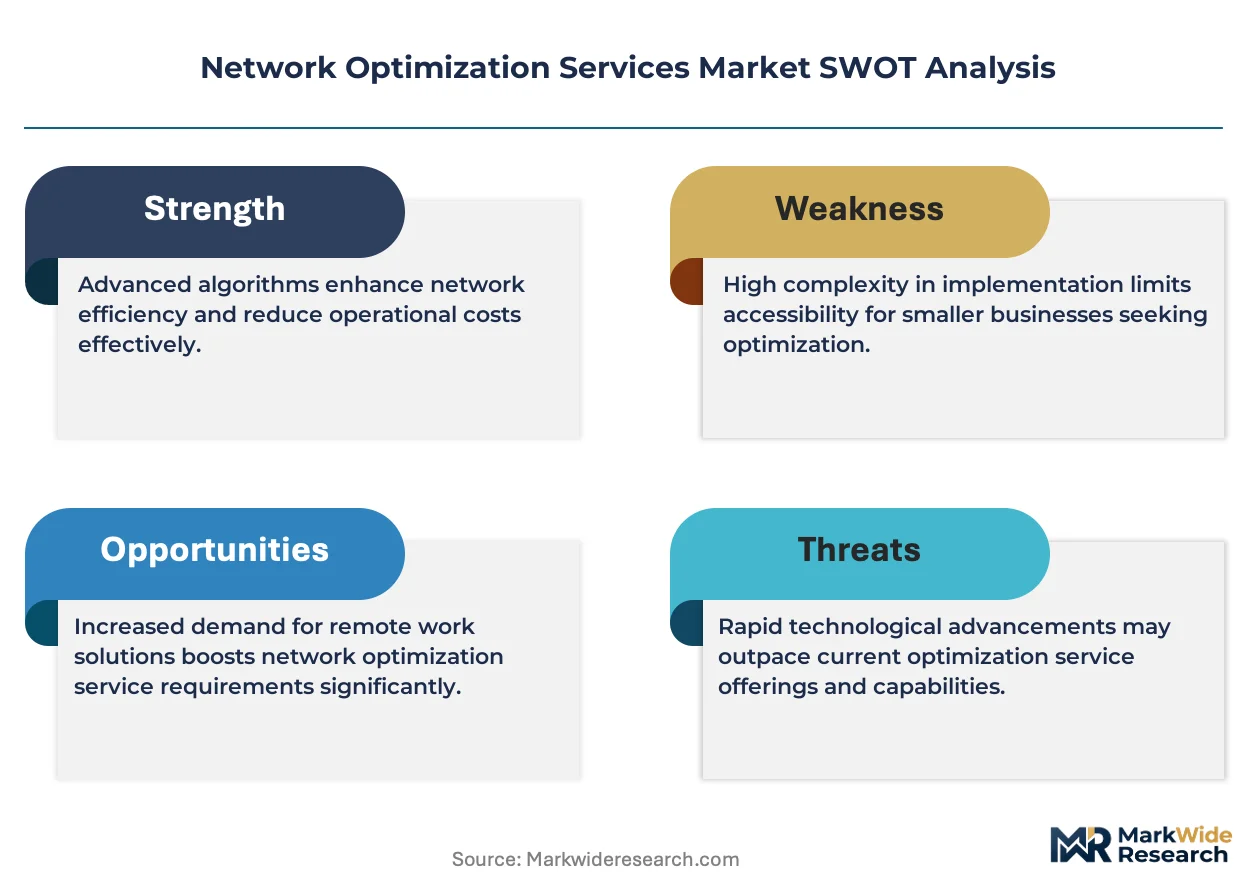
Enterprise-grade SLA guarantees is redrawing competitive boundaries in network optimization services. Nokia Corporation leverages its telco heritage to anchor large-scale carrier deployments across European and Asian markets. Cisco Systems dominates enterprise SD-WAN integration with deep channel control over Fortune 500 accounts. Huawei sustains cost-engineered positioning in emerging markets despite geopolitical headwinds.
Network optimization services encompass engineered methodologies for latency reduction, throughput maximization, and congestion mitigation across packet-switched infrastructure, typically operating at sub-50 millisecond response thresholds for real-time applications. These services orchestrate Quality of Service policies, deep packet inspection, and dynamic path selection to ensure predictable application performance across distributed architectures. Cloud-based deployment models are capturing accelerated enterprise migration as organizations abandon rigid on-premises appliance stacks. AI-powered optimization within the technology dimension is attracting disproportionate R&D allocation as vendors compete on predictive congestion avoidance and autonomous remediation capabilities.
The FCC governs spectrum allocation and broadband infrastructure standards in the United States, directly influencing carrier capex cycles that flow into optimization procurement. ETSI and the EU AI Act impose transparency and interoperability mandates on automated network management systems sold across European member states. India's TRAI enforces quality-of-service benchmarks that compel domestic operators to invest in performance analytics platforms. Stakeholders must weigh regulatory fragmentation against standardization momentum when selecting vendor partnerships and geographic expansion sequences.
Market Dynamics
AI-driven traffic orchestration is compressing carrier procurement cycles as operators abandon rule-based congestion management for predictive, autonomous systems. The FCC's net neutrality revisions and EU's Digital Networks Act are forcing simultaneous compliance investments across multi-jurisdictional deployments.
Growth Catalysts
- 5G Standalone Core Deployments:Telecommunications operators in Germany, India, and the United States are procuring intelligent traffic management platforms to support network slicing and ultra-reliable low-latency services.
- EU Digital Networks Act:Mandates for interoperability and transparency in automated network management are compelling European carriers to upgrade legacy optimization stacks.
- Cloud Migration:Enterprise abandonment of rigid on-premises appliance stacks is accelerating demand for cloud-native optimization services with elastic scaling capabilities.
Market Restraints
- Semiconductor Supply Concentration:Specialized ASIC and FPGA shortages from Taiwan-based foundries are extending lead times for high-performance optimization hardware.
- Geopolitical Export Controls:US restrictions on advanced networking equipment transfers to Chinese carriers are fragmenting vendor addressable markets.
- Legacy IPv4 Infrastructure:Persistent dependency on address translation and tunneling protocols degrades end-to-end optimization efficacy in hybrid cloud environments.
Strategic Opportunities
- Edge Computing Convergence:Integration of AI-powered optimization with distributed edge nodes creates new service tiers for industrial IoT and autonomous vehicle networks.
- India TRAI Quality Mandates:Compulsory quality-of-service benchmarks are driving domestic operator investment in performance analytics platforms.
- Private 5G Networks:Manufacturing campuses and logistics hubs in Germany and the United States represent underpenetrated demand for localized optimization services.
Industry Challenges
- AI/ML Talent Scarcity:Shortage of engineers skilled in reinforcement learning for network control plane automation is constraining vendor R&D velocity.
- Multi-Vendor Integration Complexity:Enterprise SD-WAN deployments require harmonizing optimization policies across Cisco, Nokia, and Huawei equipment stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Optimization Services Market |
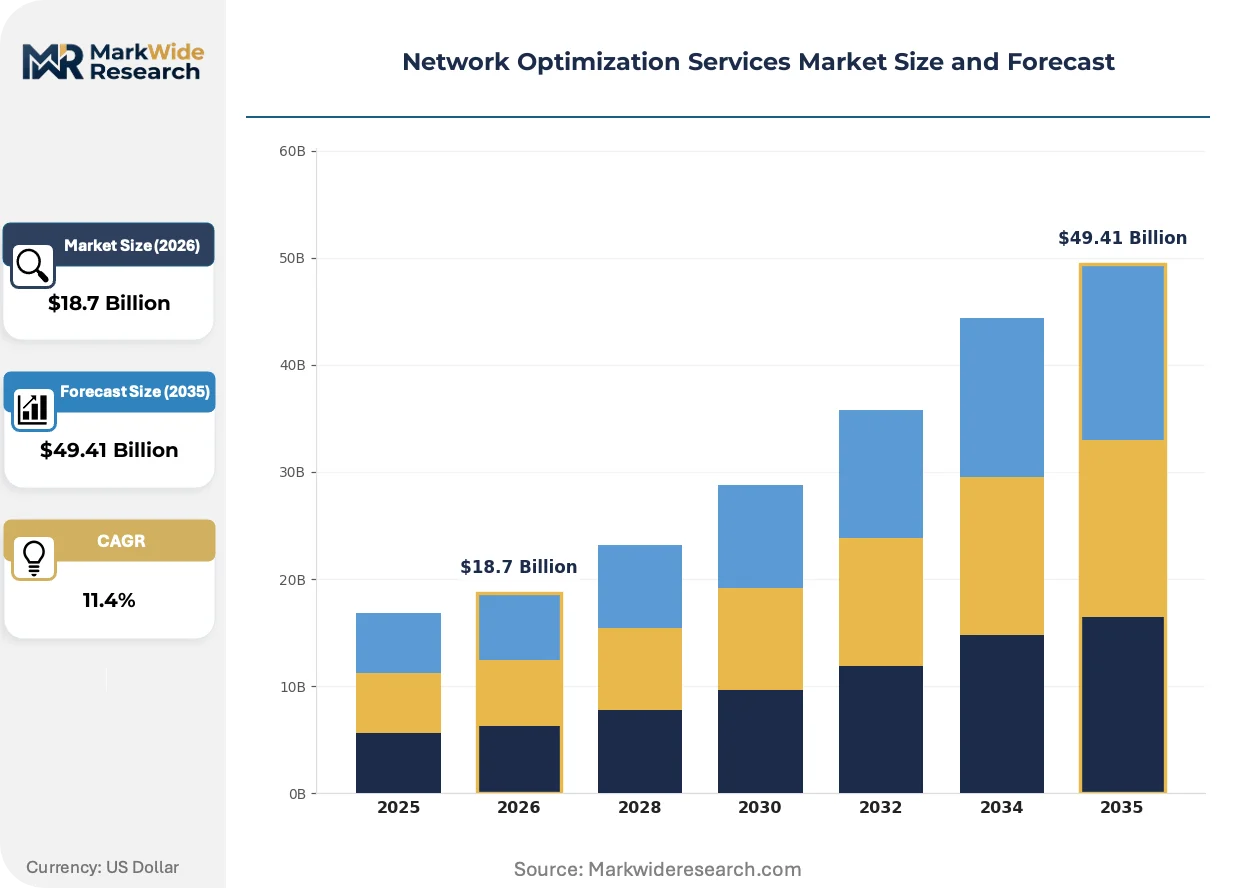
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Bandwidth Optimization, Traffic Management, Network Monitoring, Performance Analytics Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Telecommunications, Enterprises, Government, Educational Institutions Technology: SD-WAN, AI-Powered Optimization, Packet Shaping, MPLS |
| Companies Covered | Nokia Corporation, HPE, Cisco Systems, Alkira, Lumen Technologies, Solarwinds, Cloudflare, Flowmon Networks, Huawei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Optimization Services Market Strategic Shifts & Innovations
Embedded AI inference engines are migrating from centralized data centers to distributed network nodes, enabling sub-millisecond traffic decisions without cloud round-trips. This architectural shift demands new hardware-software co-design paradigms and reskilling of network operations teams.
Intent-based networking software is miniaturizing policy abstraction layers into switch ASICs and smartNICs. Financial services firms and high-frequency trading venues are deploying these capabilities to shave microseconds from cross-asset latency. The compression of decision logic to the silicon layer is collapsing traditional appliance vendor margins and forcing consolidation in the middle market.
ETSI's zero-touch network and service management standards are mandating autonomous remediation capabilities across European carrier procurements. Operators must demonstrate closed-loop fault detection and healing without human intervention to qualify for spectrum licenses. German and French telecommunications regulators are enforcing the strictest compliance timelines, accelerating vendor certification bottlenecks.
Enterprise buyers are unbundling managed optimization services from hardware procurement, preferring pure-software subscriptions with consumption-based pricing. Fortune 500 technology and retail sectors are driving this transition, forcing channel partners to rebuild compensation structures around recurring revenue. The United States exhibits the most advanced procurement sophistication, with India and Germany trailing by approximately eighteen months.
Network Optimization Services Market Segmentation
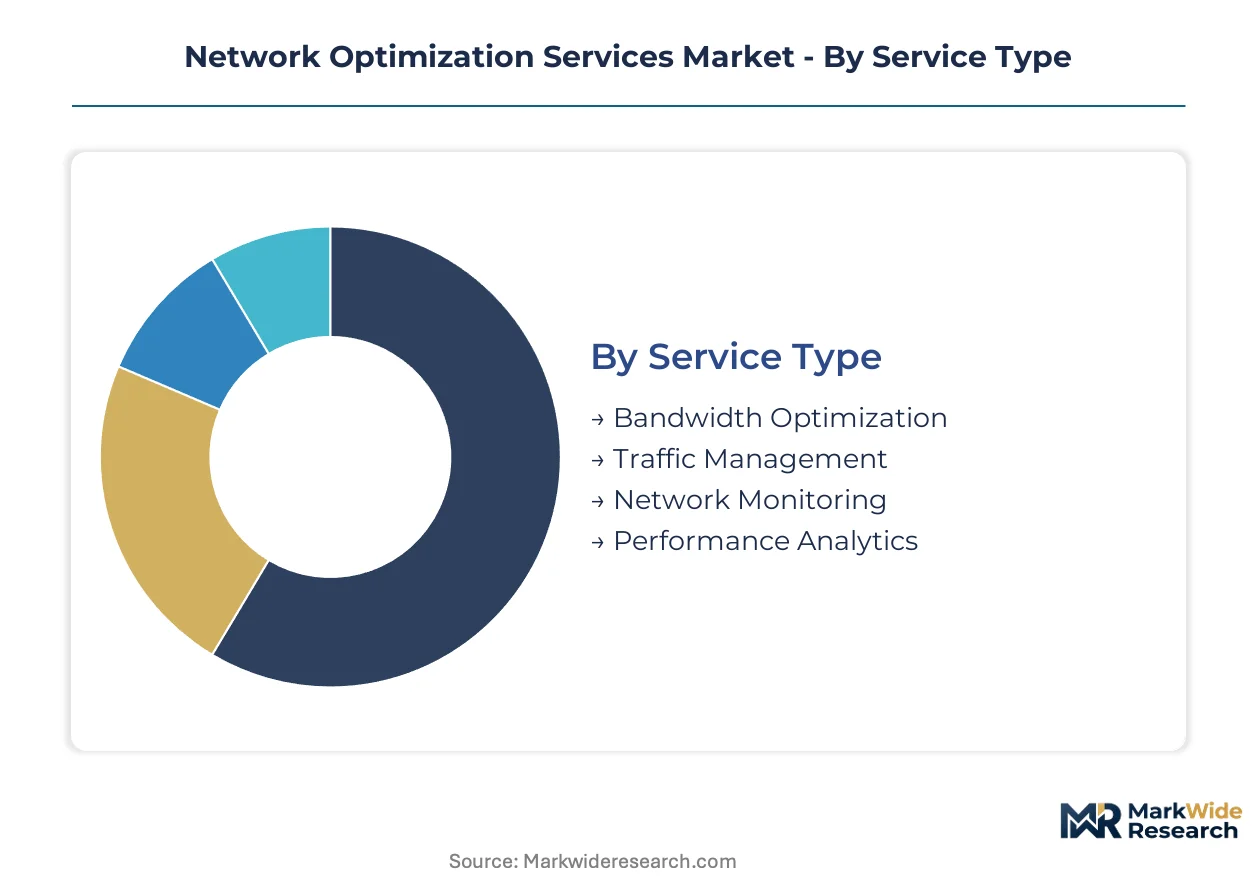
Network optimization services fragment across four structural dimensions that determine procurement patterns and vendor positioning. Service type and deployment model classifications reflect divergent regulatory compliance burdens across jurisdictions. Technology and end-user segmentation reveals where AI-driven automation is compressing traditional hardware replacement cycles.
Service Type:
Regulatory differentiation in quality-of-service mandates shapes procurement concentration across service categories. The FCC enforces broadband performance disclosure rules that elevate bandwidth optimization requirements for US carriers. TRAI benchmarks in India compel telecommunications operators toward performance analytics investments.
- Bandwidth Optimization:Compression and caching protocols reduce transit costs for content-heavy enterprise workloads. Demand concentrates among US streaming platforms and Indian over-the-top video distributors facing TRAI-mandated quality thresholds.
- Traffic Management:Intelligent routing and congestion control systems prioritize latency-sensitive applications. German automotive manufacturers and US financial exchanges deploy these capabilities to meet sub-50 millisecond SLA guarantees for autonomous vehicle coordination and high-frequency trading.
- Network Monitoring:Real-time telemetry platforms provide fault detection across distributed infrastructure.
- Performance Analytics:Predictive modeling engines forecast capacity requirements and anomaly patterns.
Established volume favors bandwidth optimization; emerging adoption favors traffic management.
Deployment Model:
Cost tier stratification separates capital-intensive appliance deployments from operational expenditure models favored by cloud-native enterprises. Fortune 500 technology and retail sectors in the United States exhibit the most advanced procurement sophistication, with India and Germany trailing by approximately eighteen months.
- Cloud-Based:Elastic scaling architectures eliminate hardware refresh cycles through software-defined consumption. US enterprise buyers unbundle managed services from hardware procurement, preferring pure-software subscriptions with consumption-based pricing.
- Managed Services:Outsourced operations transfer optimization complexity to specialized providers. European carriers under ETSI zero-touch mandates source autonomous remediation capabilities through managed service partnerships to qualify for spectrum licenses.
- On-Premises:Dedicated appliance stacks persist in regulated environments requiring air-gapped security.
- Hybrid:Split workloads across private infrastructure and public cloud orchestration layers.
Cloud-based deployments are climbing the fastest; hybrid architectures gain share among compliance-constrained verticals.
End User:
Customer type determines latency tolerance, security classification, and procurement authority centralization. Telecommunications operators command the largest contract values but extend sales cycles through multi-vendor certification requirements.
- Telecommunications:Carrier-grade infrastructure demands support millions of concurrent sessions with five-nines availability. 5G standalone core deployments in Germany, India, and the United States drive intelligent traffic management platform procurement for network slicing and ultra-reliable low-latency services.
- Enterprises:Corporate networks prioritize application-specific optimization for SaaS and cloud workloads. SD-WAN integration across Cisco, Nokia, and Huawei equipment stacks creates multi-vendor policy harmonization complexity for Fortune 500 accounts.
- Government:Sovereign networks require domestic data residency and certified encryption standards.
- Educational Institutions:Campus networks optimize for bursty video conferencing and research data transfer patterns.
Telecommunications anchors contract value; enterprises are expanding most quickly.
Technology:
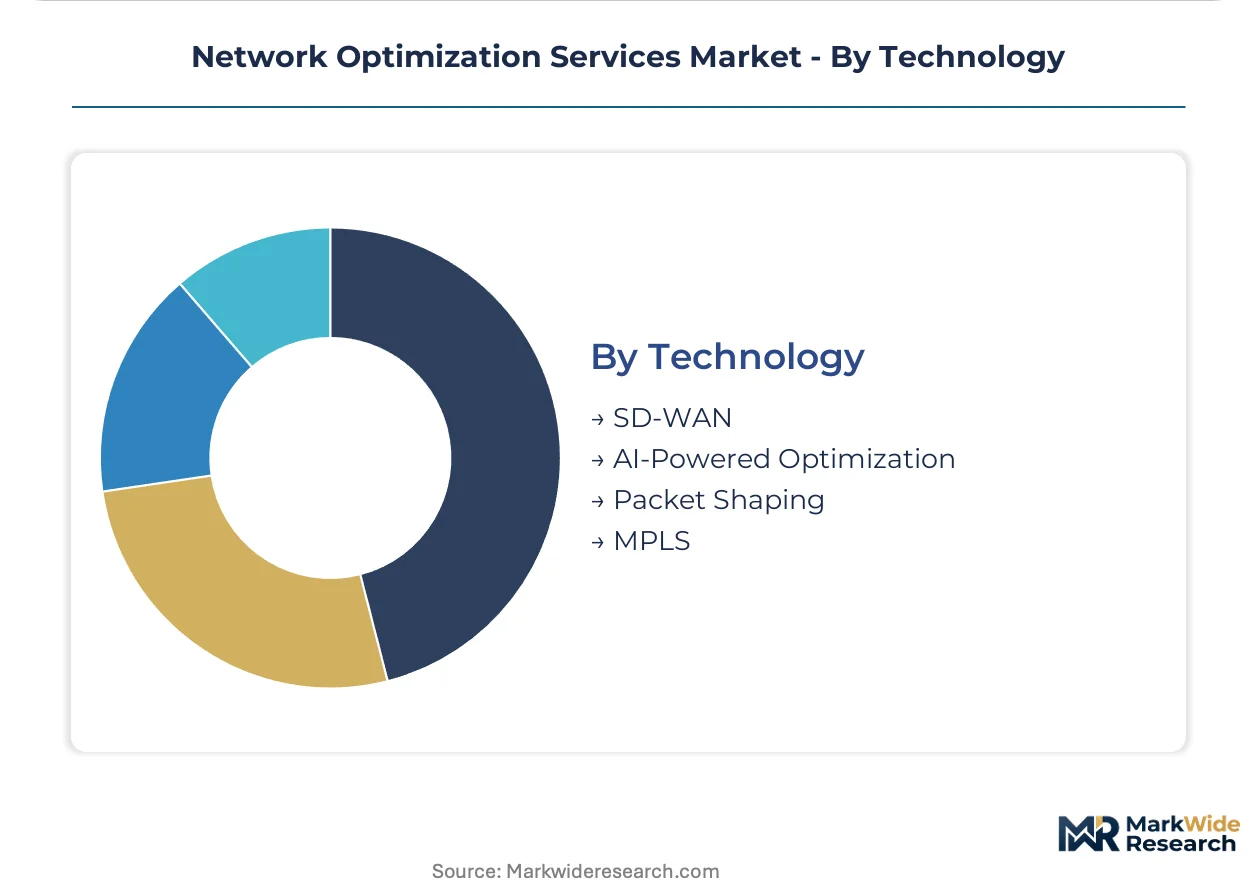
Technology maturity curves separate legacy protocol dependence from AI-native architectures. Packet shaping and MPLS represent installed base maintenance revenue; SD-WAN and AI-powered optimization capture disproportionate R&D allocation.
- AI-Powered Optimization:Reinforcement learning engines predict congestion and autonomously reroute traffic. The shortage of engineers skilled in network control plane automation constrains vendor R&D velocity and creates capability scarcity premiums.
- SD-WAN:Software-defined overlays abstract transport independence across MPLS, broadband, and LTE paths. Cisco dominates enterprise integration with deep channel control; Nokia leverages telco heritage for carrier-scale deployments.
- Packet Shaping:Deep packet inspection classifies and prioritizes traffic flows by application signature.
- MPLS:Label-switched paths provide deterministic routing for legacy enterprise VPN architectures.
SD-WAN commands established deployment share; AI-powered optimization shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in network optimization services reflect divergent regulatory compliance burdens and carrier investment cycles across major economies. The United States maintains net service exports through dominant cloud-native software vendors, while Germany and India import specialized hardware components for 5G infrastructure buildouts. Trade flows concentrate where telecommunications operators face the most stringent quality-of-service mandates.
United States
FCC net neutrality revisions and broadband infrastructure standards are accelerating carrier capex cycles into intelligent traffic management platforms. The regulator's spectrum allocation policies directly influence procurement timelines for optimization vendors serving AT&T, Verizon, and T-Mobile. Silicon Valley and Seattle host the dominant cloud-native software providers unbundling managed services from hardware procurement.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg demand sub-50 millisecond SLA guarantees for autonomous vehicle coordination networks. ETSI zero-touch network standards and the EU Digital Networks Act compel Deutsche Telekom and Vodafone to upgrade legacy optimization stacks. Berlin and Frankfurt anchor carrier procurement decisions for network slicing and ultra-reliable low-latency services.
India
TRAI quality-of-service benchmarks are driving Reliance Jio and Bharti Airtel toward performance analytics platform investments. The regulator's mandatory disclosure rules elevate bandwidth optimization requirements for over-the-top video distributors. Mumbai and Bengaluru concentrate domestic software development for cloud-native optimization services with elastic scaling capabilities.
China
MIIT 5G standalone core deployment timelines are shaping procurement patterns for intelligent traffic management systems. Domestic carriers China Mobile and China Telecom prioritize cost-engineered optimization solutions despite geopolitical export control pressures. Shenzhen and Beijing host the primary hardware-software co-design centers for AI-powered network control plane automation.
United Kingdom
Ofcom's broadband universal service obligations are extending optimization service requirements into rural infrastructure deployments. BT Group and Virgin Media O2 are procuring hybrid cloud orchestration layers to manage split workloads across private and public infrastructure. London's financial exchanges drive specialized demand for microsecond-latency optimization in high-frequency trading venues.
Network Optimization Services Market Key Industry Players
Concentration sits with telecommunications heritage vendors and cloud-native challengers competing on divergent capability vectors. The vendor base stratifies across three tiers: integrated infrastructure providers with carrier-scale certification, enterprise-focused SD-WAN specialists with channel depth, and AI-native entrants with reinforcement learning expertise. Strategic moves center on M&A for talent acquisition in network control plane automation and geographic expansion into private 5G network deployments.
Within the integrated infrastructure tier, Nokia Corporation and Cisco Systems anchor divergent market positions. Nokia leverages its Helsinki-based telecommunications heritage to secure European and Asian carrier certifications for large-scale deployments. Cisco exemplifies the enterprise-channel archetype through deep control over Fortune 500 SD-WAN integration accounts. Huawei occupies a cost-engineered positioning in emerging markets despite geopolitical headwinds constraining its addressable geography. Cloudflare and Alkira represent the cloud-native challenger segment, with San Francisco-based Cloudflare exemplifying the edge-computing convergence strategy and Santa Clara-based Alkira occupying the network-as-a-service abstraction layer.
| Leading Market Players |
|---|
| Nokia Corporation |
| HPE |
| Cisco Systems |
| Alkira |
| Lumen Technologies |
| Solarwinds |
| Cloudflare |
| Flowmon Networks |
| Huawei |
| Others |
Cost & Logistics Intelligence
Cloud-native software stacks displacing proprietary hardware appliances are redrawing procurement economics across carrier and enterprise segments. This substitution simultaneously concentrates supply leverage with Taiwan-based semiconductor foundries and compresses pricing power for traditional appliance vendors locked into ASIC refresh cycles.
Pricing Analysis
Telecommunications operators anchor three-tier pricing structure across premium, standard, and economy levels based on SLA stringency and geographic deployment scale. Price differentiation rests on certification grade for ETSI zero-touch compliance and after-sales service bundling for autonomous remediation capabilities. Pricing pressure stems from enterprise buyers unbundling managed services from hardware procurement in favor of consumption-based SaaS models. Fortune 500 technology buyers exhibit lowest price sensitivity for sub-50 millisecond latency guarantees; emerging market carriers face acute cost compression.
Supply Chain Analysis
Strategic stockpiling of specialized FPGAs and smartNICs dominates procurement behavior as lead time volatility from Taiwan-based foundries intensifies. Hardware-software co-design centers concentrate in the United States, Germany, and China for AI inference engine development. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and photonic interconnect substrates. Single-source vulnerability in advanced node semiconductor fabrication represents the critical structural risk. Distribution runs through carrier-certified systems integrators and cloud hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Network optimization services are approaching a platform-economics inflection as intent-based networking APIs enable third-party developer ecosystems. ETSI zero-touch standards and FCC net neutrality revisions are forcing interoperability investments that favor modular, API-first architectures over closed proprietary stacks.
For Market Incumbents: Fortify carrier certification moats through accelerated ETSI compliance investments ahead of German and French regulatory deadlines. Deepen backward integration into AI training infrastructure for network control plane automation to offset talent scarcity premiums. Lock in Fortune 500 enterprise accounts with consumption-based pricing transitions before cloud-native challengers achieve channel parity.
For New Entrants and Emerging Players: Anchor in private 5G network deployments for manufacturing campuses and logistics hubs in Germany and the United States where incumbent coverage remains thin. Target India TRAI-mandated quality analytics investments as the most penetrable regulatory-driven demand pocket. Pursue OEM partnerships with automotive Tier 1 suppliers for autonomous vehicle coordination networks requiring sub-50 millisecond SLAs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed SD-WAN specialists lacking AI-native optimization capabilities. Long-term viability hinges on reinforcement learning expertise for predictive congestion management rather than legacy MPLS maintenance revenue. Watch for inflection when ETSI zero-touch certification becomes mandatory for European spectrum license eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Platform Development | Reinforcement learning engines for predictive congestion avoidance differentiate vendor capabilities. |
| ETSI Zero-Touch Certification | Autonomous remediation capabilities become mandatory for European carrier spectrum licenses. |
| Edge Computing Convergence | Embedded inference engines at distributed nodes enable sub-millisecond traffic decisions. |
| Consumption-Based Pricing Transition | Enterprise buyers unbundle hardware procurement in favor of elastic software subscriptions. |
| Private 5G Network Specialization | Manufacturing campuses in Germany and the United States represent underpenetrated demand. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with carrier network architects, enterprise IT procurement officers, cloud platform engineers, and regulatory compliance leads; and secondary validation through FCC spectrum allocation records, ETSI standardization documents, TRAI quality-of-service mandates, SEC 10-K filings from listed vendors, and hyperscaler capex disclosures. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against carrier procurement cycle data anchored volume estimates.
Across the analysis window, the forecast framework modeled service type segmentation, deployment model migration patterns, end-user vertical concentration, and technology substitution dynamics including AI-powered optimization penetration. CAGRs derived from regression analysis of historical carrier capex cycles and enterprise cloud migration velocity. Industry-specific inputs included 5G standalone core deployment timelines and ETSI zero-touch compliance phase-in schedules.
Material uncertainties — semiconductor supply disruptions, export control expansion, and regulatory timeline slippage — sit outside the modeled envelope. Forecasts reflect assumptions regarding AI talent availability and carrier certification velocity. Revision becomes warranted when Taiwan-based foundry capacity constraints breach 18-month sustained duration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
Philippines Data Center Networking Market
Data Center and Networking
Content Delivery Network (CDN) Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Global Network Operating Systems Market
Data Center and Networking
Nosql Market
Data Center and Networking
Japan Data Center Server Market
Data Center and Networking
Global Heterogeneous Network Market
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
South Korea Data Center Server Market
Data Center and Networking
Converged Data Platform Market
Data Center and Networking
Network Virtualization Software Market
Data Center and Networking
Data Center Networks Market
Data Center and Networking
Mobile Data Market
Data Center and Networking
North America Subscriber Data Management Market
Data Center and Networking
MPLS-Based Core Network Market