
 Virtual Networking Market | 2026-2036
Virtual Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Networking Market Analysis
Software-defined perimeters and zero-trust architecture is reconfiguring how enterprises design network access and segmentation. Cisco Systems, Inc. leverages its installed base of routing hardware to push virtualized subscription services into existing accounts. VMware, Inc. anchors its strategy in multi-cloud network virtualization through its NSX platform, spanning private data centers and AWS or Azure endpoints. Huawei Technologies Co., Ltd. competes aggressively on price-performance for carrier-grade virtualized core networks in markets outside North America.
Virtual networking encompasses the abstraction of network functions from dedicated hardware into software layers that run on commodity servers, hypervisors, or cloud instances, typically employing encapsulation protocols such as VXLAN or Geneve to tunnel traffic across underlay networks. Its primary commercial purpose is to decouple network topology from physical infrastructure, enabling programmatic provisioning, elastic scaling, and policy-driven segmentation across distributed environments. Hybrid cloud deployment now captures the largest share of enterprise spending as organizations retain sensitive workloads on-premise while bursting to public infrastructure. Software-defined networking leads service-type growth because it collapses switching, routing, and firewall functions into centrally orchestrated control planes. Among customer types, large enterprises dominate current revenue, though service providers are expanding fastest as they build managed SD-WAN and SASE offerings for mid-market clients.
The Federal Communications Commission shapes US market access through spectrum and broadband infrastructure rules that indirectly determine where virtual network edges can be deployed with acceptable latency. The European Telecommunications Standards Institute and ETSI NFV specifications, alongside GDPR data-residency requirements, compel vendors to engineer region-specific instances with localized encryption and logging. China's Ministry of Industry and Information Technology enforces domestic certification for virtual network equipment through GB standards and MIIT testing protocols. Stakeholders must weigh regulatory fragmentation against the cost of maintaining parallel product certifications when selecting geographic expansion priorities.
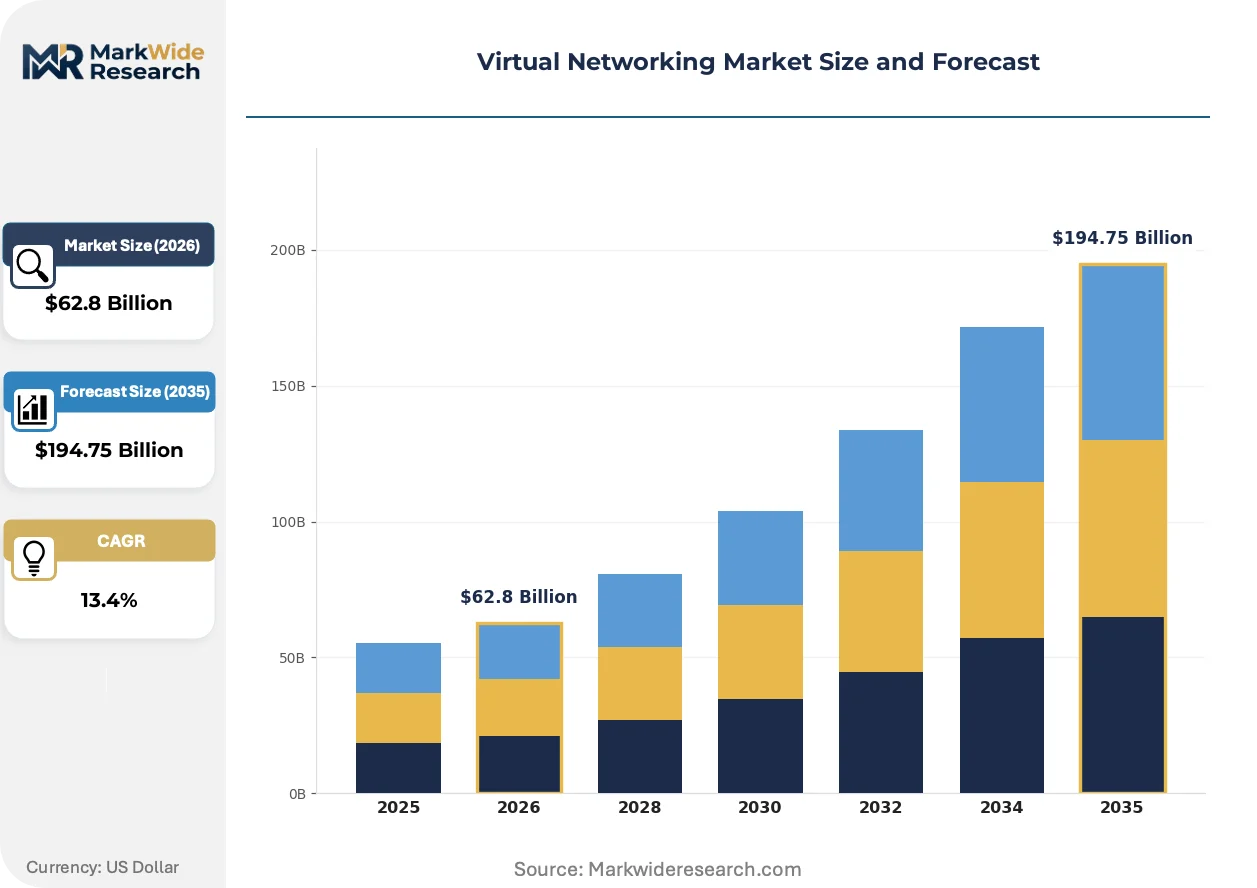
Market Dynamics
Enterprise migration from hardware-centric WANs to software-defined architectures is compressing procurement cycles and forcing incumbent vendors to restructure pricing models around subscription consumption rather than perpetual licensing.
Growth Catalysts
- Zero-trust mandates:US federal agencies now require microsegmentation capabilities that virtualized security stacks deliver more cost-effectively than physical appliances. Defense contractors and civilian departments are accelerating replacement timelines.
- Financial services network modernization:Banking infrastructure teams are collapsing branch routers into centralized SD-WAN controllers to reduce operational overhead and improve fraud detection latency.
- ETSI NFV specifications:European carriers are standardizing virtualized network function orchestration, creating procurement templates that accelerate vendor qualification across national markets.
Market Restraints
- Specialized engineering talent scarcity:Deployment of VXLAN-Geneve overlay networks requires skills combining datacenter virtualization with carrier routing protocols that few engineers possess.
- Silicon supply concentration:SmartNIC and DPU processors from a limited set of foundries create bottlenecks for high-throughput virtual switching appliances.
- Data residency enforcement:GDPR localization requirements fragment cloud network architectures, forcing redundant infrastructure investment that erodes the cost advantage of centralized virtualization.
Strategic Opportunities
- Managed SASE channels:Mid-market enterprises lacking internal networking expertise are outsourcing secure access service edge procurement to telecommunications carriers and MSPs.
- Edge computing convergence:5G network slicing and multi-access edge computing are creating demand for lightweight virtualized packet cores deployed at cell tower aggregation points.
- India's PLI scheme for telecom equipment:Domestic manufacturing incentives are attracting virtualized core network vendors to establish local engineering centers and certification labs.
Industry Challenges
- Multi-vendor orchestration complexity:Enterprises combining VMware NSX, Cisco ACI, and cloud-native CNI plugins face policy translation failures that extend deployment timelines.
- MIIT certification timelines:China's mandatory testing protocols for virtual network equipment add six to nine months to product launch schedules for foreign vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Networking Market |
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $194.75 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise Service Type: Virtual Private Network, Software-Defined Networking, Network Function Virtualization, Cloud Access Security Broker Customer Type: Small Enterprises, Medium Enterprises, Large Enterprises, Service Providers Technology: IPsec, SSL, MPLS, Ethernet |
| Companies Covered | Microsoft Corporation, Cisco Systems, Inc., VMware, Inc., Huawei Technologies Co., Ltd., Hewlett Packard Enterprise Development LP, IBM Corporation, Juniper Networks, Inc., Oracle Corporation, Verizon Communications Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Networking Market Emerging Trajectories
Virtual networking infrastructure is fragmenting into specialized layers as cloud-native control planes displace monolithic network operating systems, creating openings for vendors with narrow but deep capabilities.
Container network interfaces are hybridizing Kubernetes pod connectivity with traditional VLAN segmentation, allowing platform engineering teams to enforce zero-trust policies without reconfiguring physical switches. Financial services firms are deploying these overlays fastest, collapsing separate networking and security procurement into unified platform budgets. This convergence is compressing margins for standalone firewall vendors while rewarding integrated platform providers.
The EU Cybersecurity Act certification framework is mandating Common Criteria evaluation for virtual network appliances handling critical infrastructure traffic. Vendors must now submit source code for security analysis before achieving qualified trust service status. German energy utilities and French healthcare networks are delaying procurement until suppliers complete this process, creating temporary supply concentration among early certifiers.
Enterprise buyers are unbundling hardware procurement from software licensing, demanding separate pricing for white-box switches and controller subscriptions. This disintermediation is disrupting traditional channel relationships where distributors previously bundled both. US hyperscale cloud customers are driving this shift hardest, negotiating direct relationships with Taiwanese ODM manufacturers for programmable data plane hardware.
Virtual Networking Market Segmentation
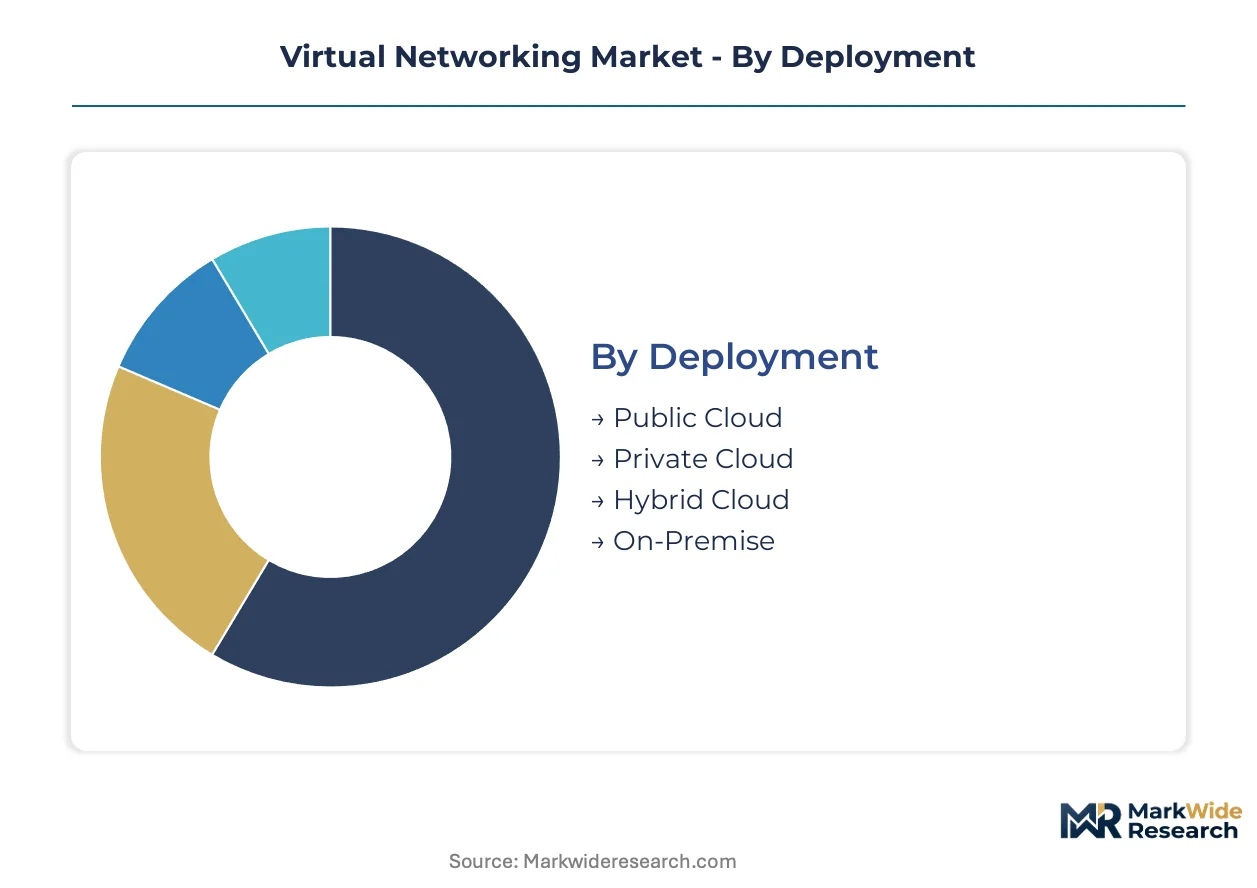
Segmentation in virtual networking reveals how infrastructure abstraction layers map to distinct procurement patterns. Deployment models and service architectures determine whether buyers prioritize capital efficiency, control sovereignty, or elastic scaling.
Deployment:
Mature on-premise installations coexist with emerging cloud-native topologies across the maturity spectrum.
- Public Cloud:Fully managed virtual networks run on hyperscale infrastructure with consumption-based billing. Financial services firms in the United States are migrating branch connectivity to these environments to satisfy federal zero-trust mandates without capital expenditure.
- Private Cloud:Dedicated virtualized infrastructure resides within enterprise-controlled facilities or hosted environments. German automotive manufacturers and French healthcare networks favor this model to maintain GDPR data residency compliance while gaining software-defined agility.
- Hybrid Cloud:Orchestrated workloads span on-premise and public endpoints through unified control planes. This architecture dominates enterprise spending as organizations retain sensitive processing locally while bursting non-critical traffic to public infrastructure.
- On-Premise:Traditional hardware-centric deployments persist in regulated environments requiring physical air-gapping. Defense contractors and civilian agencies with legacy certification requirements maintain these installations despite higher operational overhead.
Hybrid Cloud retains volume leadership; Public Cloud holds the steepest expansion curve.
Service Type:
Cost tier differentiation separates commodity connectivity from premium orchestrated security stacks.
- Software-Defined Networking:Centralized control planes programmatically manage switching, routing, and policy enforcement across distributed fabrics. ETSI NFV specifications are accelerating European carrier procurement of these orchestrated layers.
- Network Function Virtualization:Virtualized appliances replace dedicated hardware for firewalls, load balancers, and packet inspection. India's PLI scheme for telecom equipment is attracting vendors to establish local engineering centers for these functions.
- Virtual Private Network:Encrypted tunneling services extend secure connectivity across untrusted networks. Mid-market enterprises lacking internal expertise are outsourcing these capabilities to managed service providers.
- Cloud Access Security Broker:Policy enforcement gateways mediate between enterprise users and SaaS applications. Financial services procurement teams are collapsing separate networking and security budgets into unified platform spending for these integrated stacks.
Software-Defined Networking dominates current revenue concentration; Cloud Access Security Broker is climbing the fastest as SASE convergence accelerates.
Customer Type:
Volume scale separates mass-market service providers from high-touch enterprise engagements.
- Large Enterprises:IT infrastructure teams with specialized engineering talent deploy multi-vendor virtualized stacks across global footprints. These buyers negotiate direct relationships with hardware manufacturers and demand unbundled software licensing.
- Service Providers:Telecommunications carriers and managed service providers build multi-tenant platforms for downstream clients. This segment is expanding most quickly as mid-market enterprises outsource secure access service edge procurement.
- Medium Enterprises:Organizations with limited networking expertise rely on channel partners for deployment and ongoing management. These buyers prioritize pre-integrated solutions over best-of-breed component assembly.
- Small Enterprises:Minimal IT staffing drives preference for fully managed consumption models with predictable monthly expenditure. Cloud-native virtual networking services address this segment through simplified provisioning interfaces.
Large Enterprises retain the deepest penetration; Service Providers are gaining share fastest through managed SASE channels.
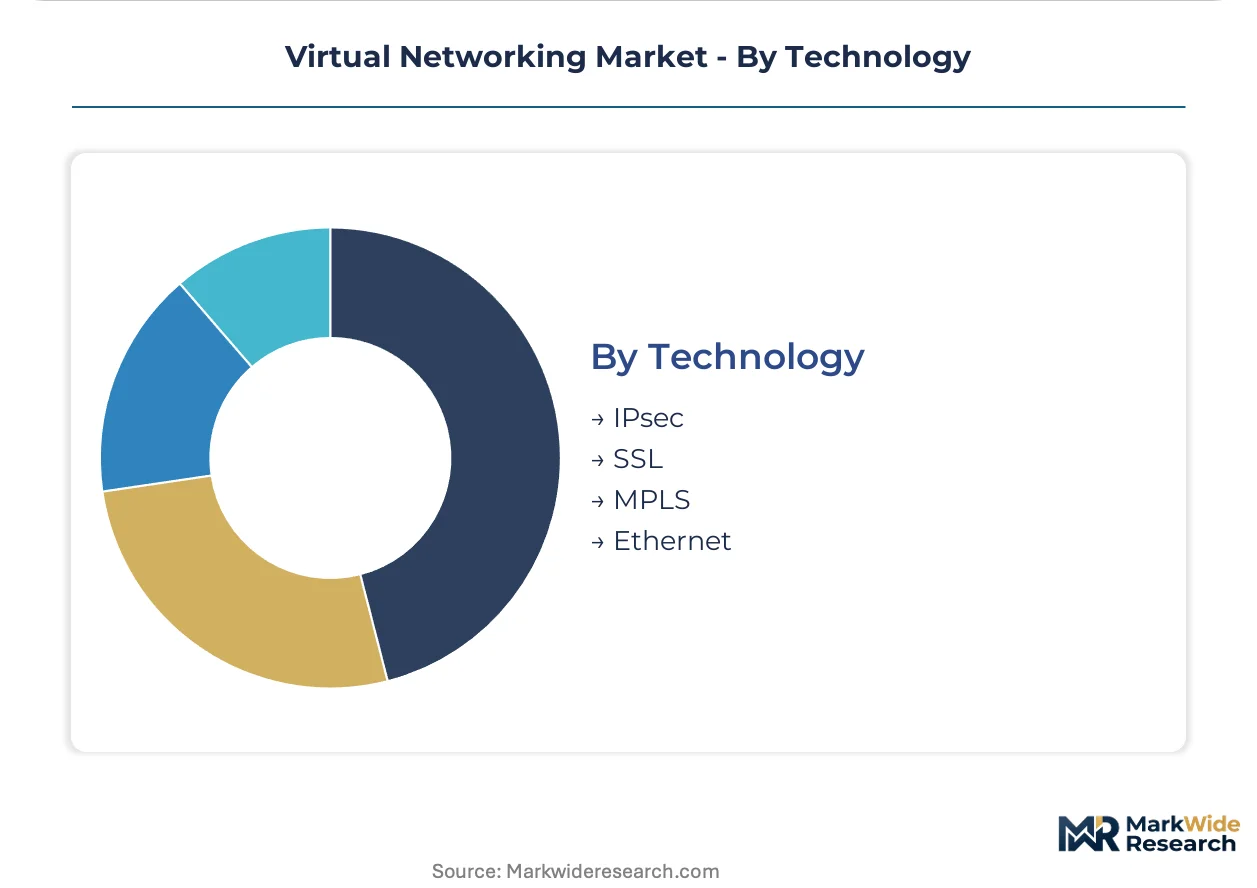
Technology:
Application context determines whether buyers prioritize cryptographic strength, transport efficiency, or legacy interoperability.
- IPsec:Standards-based encryption protocols secure site-to-site and remote access tunnels across heterogeneous environments. Federal agencies require these capabilities for microsegmentation under zero-trust architecture mandates.
- Ethernet:Layer 2 virtualization extends broadcast domains across data center fabrics and cloud regions. Hyperscale customers are driving unbundling of white-box switching hardware from controller subscriptions in this category.
- SSL:Transport layer security protects application-level communications without client-side configuration. Browser-based access patterns favor this technology for workforce mobility scenarios.
- MPLS:Label-switched paths continue serving latency-sensitive traffic in financial services and healthcare despite software-defined alternatives. Banking infrastructure teams maintain these circuits for fraud detection systems requiring deterministic performance.
IPsec commands the largest installed base; Ethernet is expanding most quickly as data center virtualization displaces proprietary fabrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German virtual networking vendors export orchestration platforms to United States hyperscale data centers, establishing a transatlantic trade corridor in software-defined infrastructure components.
United States
Federal zero-trust mandates and hyperscale cloud region expansion drive procurement of virtualized security stacks. The FCC shapes market access through spectrum and broadband infrastructure rules. Northern Virginia data center clusters concentrate demand for programmable network fabrics serving defense contractors and civilian agencies.
Germany
Automotive manufacturers and healthcare networks prioritize GDPR-compliant private cloud deployments. ETSI NFV specifications standardize virtualized network function orchestration across carrier procurement. Frankfurt and Munich host engineering centers where vendors localize encryption and logging capabilities for qualified trust service status.
China
Domestic certification requirements and 5G network slicing investments accelerate virtualized core network deployment. MIIT enforces GB standards and testing protocols that extend foreign vendor launch schedules. Beijing and Shanghai engineering clusters concentrate carrier-grade development for markets outside North America.
India
Telecom equipment manufacturing incentives attract virtualized core network vendors to establish local engineering centers. TRAI regulations shape spectrum allocation for 5G services requiring lightweight packet cores. Bangalore and Hyderabad certification labs process domestic compliance for export-oriented production.
United Kingdom
Financial services firms collapse separate networking and security budgets into unified platform spending. GDPR alignment post-Brexit maintains data residency requirements for cross-border traffic. London financial district procurement teams negotiate direct relationships with programmable hardware manufacturers.
Virtual Networking Market Vendor Landscape
Channel-controlling players compete with product-specialist players for procurement influence across enterprise and service provider segments. The vendor base organizes around three strategic archetypes: incumbent networking hardware vendors extending software subscriptions, cloud-native platform providers, and telecommunications carriers building managed service offerings. Dominant competitive moves include unbundling hardware from software licensing and establishing direct relationships with original design manufacturers for white-box switching.
Within the incumbent hardware tier, Cisco Systems, Inc. and VMware, Inc. occupy positions reflecting contrasting strategic anchors. Cisco leverages its installed base of routing equipment to push virtualized subscription services into existing enterprise accounts. VMware anchors its positioning in multi-cloud network virtualization spanning private data centers and public cloud endpoints. Huawei Technologies Co., Ltd. exemplifies the price-performance archetype for carrier-grade deployments in markets outside North America.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Cisco Systems, Inc. |
| VMware, Inc. |
| Huawei Technologies Co., Ltd. |
| Hewlett Packard Enterprise Development LP |
| IBM Corporation |
| Juniper Networks, Inc. |
| Oracle Corporation |
| Verizon Communications Inc. |
| Others |
Supply Flow & Price Mechanics
Taipei-based ODM clusters for programmable data plane hardware determine downstream pricing power for virtualized network controllers, as unbundling trends force vendors to compete on silicon efficiency rather than bundled appliance margins. White-box switch manufacturing concentration in Hsinchu Science Park feeds cost compression into enterprise procurement cycles, while subscription licensing models absorb volatility through recurring revenue structures.
Pricing Analysis
Current-generation SmartNIC-based virtual switching commands premium positioning against prior-generation software-only implementations and next-generation DPU-accelerated architectures still in qualification. Three-tier pricing structure across premium, standard, and economy levels separates carrier-grade certified appliances from enterprise SD-WAN bundles and open-source controller distributions. Pricing pressure stems from hyperscale cloud buyers negotiating direct foundry relationships that bypass traditional channel markups. Service providers exhibit lowest price sensitivity due to multi-tenant margin stacking, while mid-market enterprises drive hardest bargain through MSP consolidation.
Supply Chain Analysis
Foundry capacity at TSMC, Samsung, and Intel anchors contract-manufacturing concentration for high-throughput virtual switching silicon. SmartNIC and DPU processors draw from advanced node dependencies, while commodity server motherboards and optical transceivers rest on broader Asian electronics manufacturing networks. Single-source vulnerability concentrates in 7nm and 5nm foundry allocations for programmable data plane chips. Distribution runs through Taiwanese ODMs supplying hyperscale direct, tier-one server vendors for enterprise, and carrier-integrated systems houses for telecommunications procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zero-trust architecture mandates across federal and financial verticals create a high-growth disruption window, with regulatory compliance timelines compressing vendor qualification cycles and favoring early certifiers.
For Market Incumbents: Harden virtual appliance security postures through Common Criteria certification investment ahead of EU Cybersecurity Act enforcement waves. Defend installed-base relationships by embedding subscription controllers deeper into existing routing hardware footprints, neutralizing cloud-native platform substitution threats through hybrid orchestration capabilities. For New Entrants and Emerging Players: Establish a beachhead in managed SASE channels serving mid-market enterprises lacking internal networking expertise. India's PLI scheme for telecom equipment offers lowest barrier to localized engineering presence, while carrier-grade virtualized core networks outside North America present price-performance arbitrage opportunities against incumbent hardware vendors. For Investors and Strategic Acquirers: Carve-out targets emerge from networking hardware conglomerates divesting non-core software assets under shareholder pressure for recurring revenue transformation. Long-term viability centers on orchestration platform ownership rather than commodity virtual function appliances. Watch hyperscaler capex allocation shifts toward programmable networking silicon as inflection indicator for controller software valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Common Criteria Certification Investment | EU Cybersecurity Act compliance unlocks qualified trust service status for critical infrastructure procurement. |
| Direct ODM Relationship Establishment | Hyperscale cloud buyers bypass channel markups through Taipei-based programmable hardware negotiations. |
| Managed SASE Channel Partnership | Telecommunications carriers capture mid-market outsourcing demand lacking internal networking expertise. |
| Multi-Cloud Controller Integration | VMware NSX and cloud-native CNI hybridization addresses enterprise policy translation failure risks. |
| India PLI Scheme Localization | Domestic manufacturing incentives attract virtualized core network engineering center establishment. |
Methodological Framework
Initial hypotheses were tested against primary input from enterprise IT infrastructure directors, telecommunications carrier network architects, managed service provider technical leads, and hyperscale cloud procurement officers and refined through secondary validation across SEC 10-K filings, ETSI NFV specification releases, hyperscaler capex disclosures, and carrier procurement database tracking. Bottom-up deployment model sizing and top-down macroeconomic factor weighting were triangulated to converge estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning deployment model, service type, customer scale tier, and encryption protocol technology. CAGRs were derived from installed base migration curves and greenfield procurement elasticity modeling. Industry-specific forecast inputs incorporated federal zero-trust mandate implementation timelines and ETSI NFV standardization adoption rates across European carrier procurement cycles.
Stress conditions across silicon supply allocation, GDPR enforcement stringency, and MIIT certification timeline variability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding enterprise virtualization penetration curves and carrier managed service outsourcing velocity. Quarterly review of hyperscaler networking silicon capex, Common Criteria certification completion rates, and carrier SD-WAN RFP issuance volume is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
SDN Orchestration Market
Data Center and Networking
Fog Networking Market
Data Center and Networking
Global Scalable Software Defined Networking Market
Data Center and Networking
Network Optimization Services Market
Data Center and Networking
Chile Data Center Networking Market
Data Center and Networking
Ethernet Transceivers Market
Data Center and Networking
Global Data Warehouse As a Service (Dwaas) Market
Data Center and Networking
Dynamic Data Management System Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Brazil Data Center Networking Market
Data Center and Networking
Global Data Management Platform Market
Data Center and Networking
Global Managed SD-WAN Service Market
Data Center and Networking
South Africa Data Center Server Market
Data Center and Networking
Network Connectivity Tester Market
Data Center and Networking
Global Enterprise Networking Market