
 Software Defined Video Networking Market | 2026-2036
Software Defined Video Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Software Defined Video Networking Market Analytics
Platform licensing revenue is tilting from perpetual hardware-centric models toward recurring software subscriptions in video networking infrastructure. Cisco Systems leverages its installed base of routing hardware to extend SDN controller penetration across broadcast workflows. Juniper Networks anchors its position through specialized traffic management silicon optimized for low-latency video transport. Arista Networks differentiates via cloud-grade switching platforms that sustain sub-microsecond jitter performance for live production environments.
Software Defined Video Networking denotes an architecture where control plane intelligence for video traffic routing is decoupled from dedicated hardware and centralized through programmable SDN controllers, typically operating on standard x86 compute with OpenFlow or proprietary southbound protocols managing 10Gbps to 400Gbps fabric throughput. The primary purpose is enabling dynamic bandwidth allocation, multicast optimization, and session-based quality-of-service enforcement across geographically distributed video workflows. Cloud-based deployment models capture the fastest expansion as media enterprises abandon capital-intensive on-premises headends for elastic compute pools. Edge computing deployments are gaining traction where ultra-low latency requirements for live sports and interactive streaming cannot tolerate centralized cloud round-trips. Hybrid architectures presently occupy the dominant revenue position by balancing legacy satellite and terrestrial interconnects with emerging IP fabric overlays.
The FCC governs interstate video transport standards and net neutrality provisions affecting how carriers prioritize streaming traffic across American networks. ETSI and the European Commission's Digital Services Act shape interoperability mandates and cross-border content delivery frameworks within European markets. China's MIIT enforces GB standards for domestic video networking equipment while advancing dual carbon goals that pressure data center energy efficiency in streaming infrastructure. Stakeholders must monitor how divergent sovereignty requirements for video data residency are fragmenting previously unified architectural roadmaps.
Market Dynamics
The central structural force reshaping Software Defined Video Networking is the decoupling of control plane intelligence from dedicated broadcast hardware, a shift that compresses capital deployment cycles and redistributes value toward software licensing and cloud orchestration layers.
Growth Catalysts
- Live streaming infrastructure:Sports leagues and esports tournaments demand sub-50ms latency for interactive viewer experiences, forcing broadcasters to deploy edge-computing nodes with programmable SDN controllers.
- FCC net neutrality rulings:Carriers in the United States must disclose traffic management practices, creating transparency that accelerates software-defined traffic engineering adoption for video prioritization.
- Cloud migration:Media enterprises abandon satellite downlink facilities for elastic IP fabric, with AWS, Azure, and Google Cloud regions absorbing former headend workloads.
Market Restraints
- Silicon supply concentration:Specialized ASICs for 400Gbps video switching fabric depend on TSMC's advanced nodes, creating single-source vulnerability for low-latency packet processing.
- Skill scarcity:Broadcast engineers with hybrid IP-video expertise command premium compensation, constraining deployment velocity for mid-tier media groups.
- Interoperability friction:Proprietary southbound protocols from incumbent vendors fragment multi-vendor fabric management, delaying unified controller deployments.
Strategic Opportunities
- German industrial video:Manufacturing automation and remote inspection workflows in Bavaria and Baden-Württemberg remain underpenetrated by software-defined multicast, offering greenfield deployment potential.
- ETSI interoperability mandates:The European Commission's Digital Services Act pressures cross-border content delivery standardization, favoring vendors with open API architectures.
- AI-driven traffic prediction:Convergence of machine learning inference at the edge with SDN controllers enables predictive bandwidth allocation for live event spikes.
Industry Challenges
- Hybrid integration complexity:Media enterprises must bridge legacy SDI baseband infrastructure with IP fabric without disrupting 24/7 broadcast operations, requiring phased cutover strategies.
- Certification timeline compression:China's MIIT GB standards for video networking equipment demand extended testing cycles that delay product launches in the world's second-largest media market.
- Multivendor orchestration:Fragmented controller ecosystems force buyers to maintain parallel management planes, inflating operational overhead and training requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software Defined Video Networking Market |
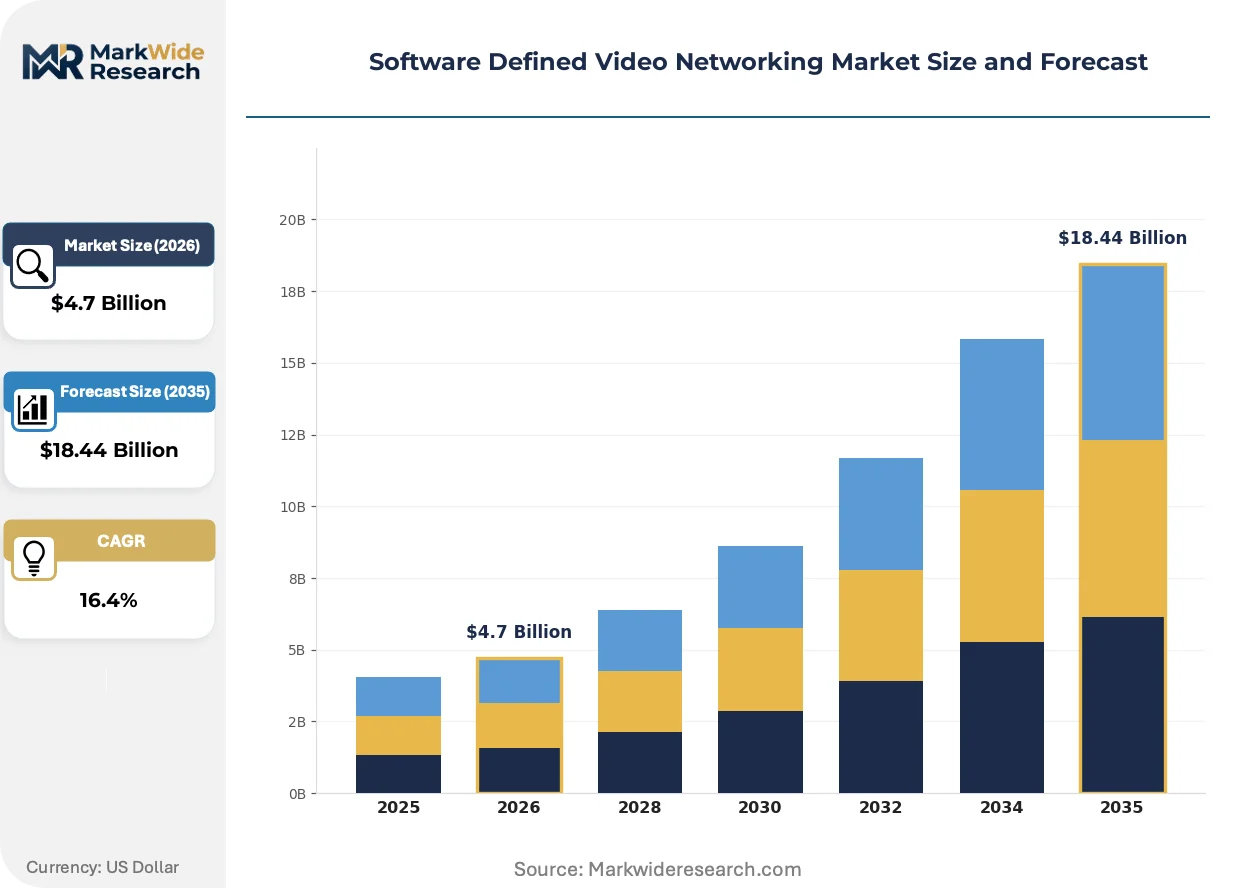
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $18.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Broadcasting, Surveillance, Content Delivery, Video Conferencing Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Media Enterprises, Telecommunications, Education Institutions, Government Agencies Technology: SDN Controllers, Network Virtualization, Protocols, Traffic Management |
| Companies Covered | Cisco Systems, Juniper Networks, Dell Technologies, Hewlett Packard Enterprise, IBM, Arista Networks, Palo Alto Networks, Broadcom, Fortinet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software Defined Video Networking Market Evolving Landscape
Software-defined control planes are absorbing functions once embedded in dedicated hardware, compressing equipment refresh cycles and shifting procurement toward subscription-based consumption models across broadcast infrastructure.
Intent-based networking is migrating from experimental deployments to production-grade live workflows. This technology abstracts low-level routing policies into declarative service definitions that operators specify rather than manually configure. Major sports broadcasters in the United States and Germany now deploy intent-based controllers for multi-venue event coverage, collapsing provisioning time from days to minutes while reducing misconfiguration incidents that previously caused on-air failures.
China's MIIT dual carbon goals are reshaping data center energy efficiency mandates for streaming infrastructure. The regulation imposes PUE ceilings on facilities exceeding specified power thresholds, forcing video networking deployments toward liquid-cooled switching fabric and renewable-powered edge locations. Domestic cloud providers and state media entities are responding by consolidating workloads into certified green facilities, displacing smaller colocation operators unable to meet efficiency benchmarks.
Buyer contracting patterns are fragmenting as media enterprises unbundle hardware procurement from software licensing and professional services. Large broadcast groups now negotiate controller subscriptions directly with software vendors while sourcing white-box switching hardware through separate commodity channels. This bifurcation is most visible in China, where CCTV and provincial broadcasters lead the separation of software control layers from underlying transport infrastructure.
Software Defined Video Networking Market Segmentation
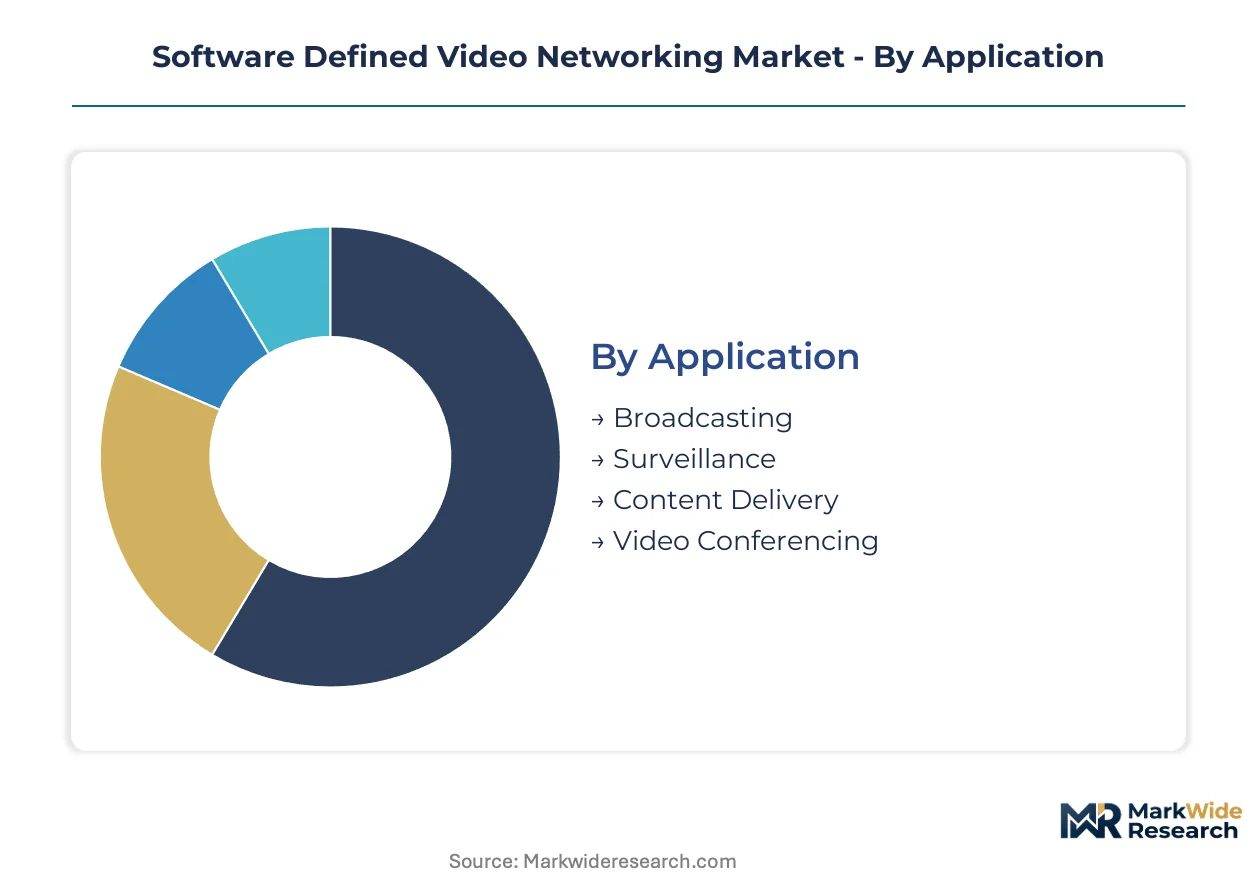
Software Defined Video Networking architectures serve heterogeneous workloads spanning live production, security, and enterprise collaboration. Segmentation reveals how control plane abstraction creates divergent value pools across deployment topologies and buyer types.
Application:
Application segmentation maps how video traffic engineering requirements vary by content type and latency sensitivity.
- Broadcasting:Live production workflows demand sub-microsecond jitter tolerance across multi-venue event coverage. Sports leagues in the United States and Germany drive edge node deployment for real-time camera synchronization.
- Surveillance:Municipal and enterprise security networks require deterministic multicast routing for thousands of concurrent camera streams. China's smart city initiatives concentrate demand for software-defined traffic isolation between public safety and civilian data.
- Content Delivery:CDN operators leverage programmable controllers for dynamic path optimization across peering exchanges.
- Video Conferencing:Enterprise IT departments prioritize session-based QoS enforcement for hybrid workforce connectivity.
Broadcasting commands the established base. The steepest expansion runs through Surveillance as municipal digitization accelerates.
Deployment Model:
Deployment topology determines capital intensity, operational control, and latency boundaries for video workloads.
- Cloud-Based:Elastic compute pools absorb headend transcoding and packaging functions previously anchored in satellite downlink facilities. Media enterprises in China and the United States migrate broadcast workloads to AWS, Azure, and domestic cloud regions.
- Edge Computing:Distributed nodes place SDN controllers within 10 kilometers of capture points for interactive streaming. Esports tournaments and live sports betting platforms in Germany drive sub-50ms latency requirements.
- On-Premises:National broadcasters maintain sovereign control over primary distribution infrastructure.
- Hybrid:Bridges legacy SDI baseband with IP fabric overlays during multi-year transition windows.
Hybrid architectures command the established base. Cloud-Based deployments are climbing the fastest as capital cycles compress.
End User:
Buyer type shapes procurement patterns, technical sophistication, and regulatory exposure for networking vendors.
- Media Enterprises:Broadcast groups and streaming platforms negotiate unbundled software subscriptions separate from commodity switching hardware. CCTV and provincial networks in China lead this procurement bifurcation.
- Telecommunications:Carriers deploy programmable controllers to manage video prioritization under FCC net neutrality disclosure requirements in the United States.
- Education Institutions:Universities require multicast optimization for campus-wide lecture capture and remote learning distribution.
- Government Agencies:Defense and civilian entities impose stringent data residency and encryption standards on transport infrastructure.
Media Enterprises command the established base. Telecommunications is gaining share fastest as 5G video transport scales.
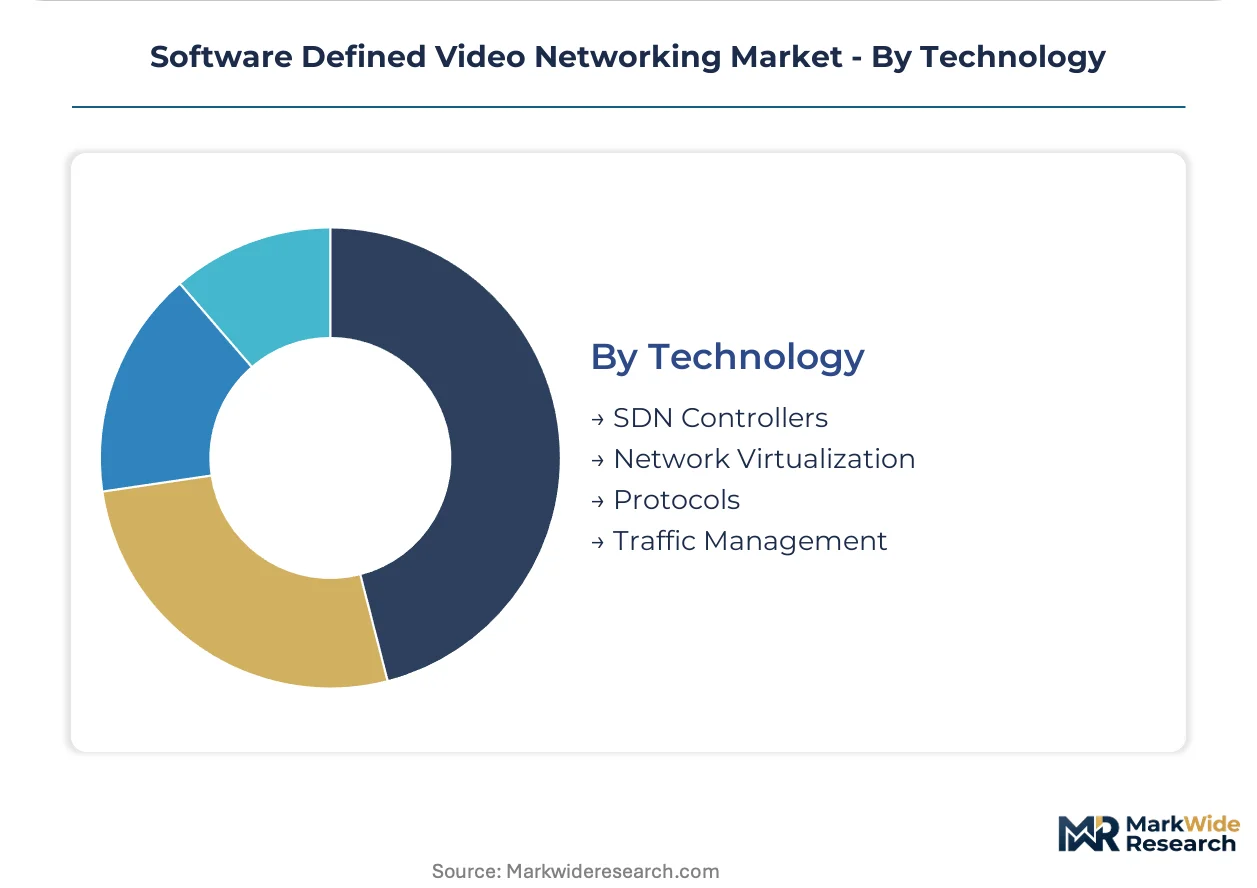
Technology:
Technology segmentation isolates where value concentrates within the decoupled control plane stack.
- SDN Controllers:Centralized intelligence platforms manage southbound protocols across 10Gbps to 400Gbps fabric. Intent-based networking capabilities now reach production-grade live workflows for major sports broadcasters.
- Traffic Management:Specialized silicon and algorithms enforce per-session QoS for uncompressed video transport. Low-latency packet processing depends on TSMC advanced node availability.
- Network Virtualization:Overlay networks abstract physical topology for multi-tenant broadcast facilities.
- Protocols:OpenFlow and proprietary southbound implementations compete for multi-vendor fabric management dominance.
SDN Controllers command the established base. Traffic Management is expanding most quickly as 400Gbps switching fabric proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes live sports edge computing for sub-50ms latency, while China concentrates cloud-based headend consolidation under MIIT efficiency mandates. Germany maintains hybrid architectures bridging legacy SDI with IP fabric overlays.
United States
Sports leagues and esports tournaments drive demand for interactive streaming infrastructure. FCC net neutrality rulings require carriers to disclose traffic management practices, accelerating software-defined traffic engineering adoption. Production clusters in Los Angeles and New York deploy edge nodes for real-time camera synchronization across multi-venue events.
China
State media entities and provincial broadcasters lead migration from satellite downlink facilities to elastic cloud regions. MIIT dual carbon goals impose PUE ceilings on data centers, forcing consolidation into certified green facilities. Beijing and Shanghai clusters displace smaller colocation operators unable to meet energy efficiency benchmarks.
Germany
Manufacturing automation and remote inspection workflows in industrial zones create greenfield demand for software-defined multicast. ETSI interoperability mandates under the European Commission's Digital Services Act pressure cross-border standardization. Bavaria and Baden-Württemberg host underpenetrated deployments in factory-floor video networking.
Japan
Broadcasters maintain stringent quality requirements for uncompressed video transport in live production environments. METI industrial policy supports domestic equipment certification timelines that delay foreign vendor entry. Tokyo and Osaka clusters prioritize sub-microsecond jitter tolerance for 4K and 8K content distribution.
United Kingdom
Media enterprises unbundle software licensing from hardware procurement, negotiating controller subscriptions separately from commodity switching. GDPR data residency requirements fragment architectural roadmaps for cross-border content delivery. London production houses lead hybrid deployment models balancing on-premises sovereignty with cloud elasticity.
Software Defined Video Networking Market Competitive Landscape
Capability concentration sits with specialized traffic management vendors; scale advantage sits with incumbent networking conglomerates. The vendor base spans three tiers: cloud-grade switching specialists, routing hardware incumbents extending SDN controllers, and security-focused platform integrators. Dominant competitive moves include portfolio diversification into adjacent orchestration layers and strategic partnerships with hyperscale cloud providers.
Within the routing hardware tier, Cisco Systems and Juniper Networks exemplify incumbents leveraging installed base penetration. Arista Networks occupies a position among cloud-grade switching specialists optimized for low-latency production environments. These three anchors represent divergent strategic postures: controller extension through hardware legacy, specialized silicon optimization, and cloud-native fabric performance respectively.
| Leading Market Players |
|---|
| Cisco Systems |
| Juniper Networks |
| Dell Technologies |
| Hewlett Packard Enterprise |
| IBM |
| Arista Networks |
| Palo Alto Networks |
| Broadcom |
| Fortinet |
| Others |
Value Network & Pricing Analysis
Trans-Pacific fiber routes connecting Shanghai and Los Angeles carry escalating bandwidth costs that concentrate pricing power among carriers operating proprietary SDN controller stacks. These corridor dynamics reward vertically integrated vendors while squeezing white-box hardware margins across media enterprise procurement.
Pricing Analysis
Long-term subscription contracts dominate controller licensing, with three-year enterprise agreements anchoring recurring revenue for incumbent networking vendors. Price differentiation rests on jitter performance certification and geographic support density, with premium tiers commanding substantial uplifts for sub-microsecond guarantees. Pricing pressure stems from hyperscaler cloud egress fee compression as AWS and Azure absorb former headend workloads. Mid-tier media groups exhibit acute price sensitivity, whereas national broadcasters prioritize sovereignty guarantees over per-port economics.
Supply Chain Analysis
Advanced switching silicon feeds from Taiwan, South Korea, and the United States, with TSMC's N5 and N3 nodes anchoring 400Gbps packet processing capabilities. Specialized ASICs, optical transceivers, and precision timing components constitute critical input dependencies. Single-source vulnerability at the foundry level exposes vendors to allocation constraints during capacity crunches. Distribution runs through direct enterprise sales teams for major accounts, supplemented by systems integrators serving provincial broadcasters and municipal surveillance networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controller ecosystem fragmentation creates entry niches as media enterprises unbundle software procurement from hardware sourcing. Intent-based networking adoption splinters purchasing authority between broadcast engineering and cloud infrastructure teams.
For Market Incumbents: Build switching fabric moats through captive silicon roadmaps that lock in performance differentiation against merchant chip alternatives. Deepen backward integration into precision timing components to secure supply continuity against TSMC allocation volatility. Extend professional services attach rates to offset controller commoditization pressure from open-source alternatives.
For New Entrants and Emerging Players: German industrial zones in Bavaria offer underpenetrated multicast demand from manufacturing automation and remote inspection workflows. Target municipal surveillance networks in secondary Chinese cities where provincial broadcasters seek alternatives to incumbent pricing. Lead with open API architectures that satisfy ETSI interoperability mandates without legacy protocol baggage.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors traffic management specialists with production-grade intent-based networking deployments. Five-to-ten year viability hinges on edge computing density expansion rather than centralized cloud consolidation. Monitor hyperscaler capex disaggregation signals for inflection timing on white-box switching demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Intent-Based Networking Deployment | Major sports broadcasters in the United States collapse provisioning time from days to minutes. |
| Edge Node Expansion | Esports platforms in Germany drive sub-50ms latency requirements for interactive streaming. |
| Open API Architecture Development | ETSI mandates under the Digital Services Act favor vendors with interoperable controller stacks. |
| Green Facility Certification | MIIT dual carbon goals force consolidation into liquid-cooled data centers displacing colocation operators. |
| Silicon Roadmap Vertical Integration | Specialized ASIC dependence on TSMC creates single-source vulnerability for 400Gbps fabric vendors. |
Research Methodology
Desk research of FCC rulings, ETSI standards documentation, and MIIT regulatory filings preceded structured interviews with broadcast engineering directors, cloud infrastructure architects, carrier network planners, and municipal surveillance procurement officers. Secondary triangulation drew from hyperscaler capex disclosures, semiconductor foundry utilization reports, and media enterprise RFP documentation. Bottom-up segmentation modeling cross-validated against top-down macroeconomic scenario analysis.
Assumption sets held regulatory enforcement timelines and foundry capacity expansion fixed while varying cloud migration velocity and edge computing adoption curves across the projection horizon. The analytical framework modeled deployment topology, application workload, and buyer sophistication as primary segmentation dimensions alongside regional regulatory cluster variations. CAGRs derived from S-curve technology diffusion patterns applied to infrastructure replacement cycles, with inputs including live sports rights expenditure trajectories and 5G transport network buildout schedules.
Practitioners should monitor foundry allocation announcements, hyperscaler egress pricing adjustments, and ETSI interoperability certification timelines for early signals of forecast revision triggers. Semiconductor supply constraints, net neutrality rulemaking shifts, and carbon efficiency mandate acceleration constitute specific risk factors warranting scenario contingency planning. Quarterly review of vendor backlog disclosures and provincial broadcaster procurement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
APAC Data Center Networking Market
Data Center and Networking
Global Data Management Platform Market
Data Center and Networking
Graph Database Market
Data Center and Networking
Nvme Over Fiber Channel Market
Data Center and Networking
MPLS-Based Core Network Market
Data Center and Networking
Nosql Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
Internet Protocol Version 6 (IPv6) Market
Data Center and Networking
France Data Center Networking Market
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
Vietnam Data Center Server Market
Data Center and Networking
Ethernet Transceivers Market
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
Global Network Configuration and Change Management Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
Global Data Warehouse Market