
 Dairy Snacks Market | 2026-2036
Dairy Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Snacks Market Intelligence
European dairy cooperative output is rebalancing toward higher-margin snack formats as fluid milk consumption softens across Germany and France. Arla Foods leverages its farmer-owned structure to sustain stable whey protein supplies for cheese snack lines. Nestlé anchors premium positioning through controlled chilled distribution networks in Western Europe. Fonterra competes on commodity cheddar volumes while navigating Oceania pasture volatility.
Dairy snacks encompass processed milk-derived foods formulated for between-meal consumption, typically containing 10-25% milk solids with adjusted moisture content below 50% for shelf stability through pasteurization or fermentation. These products serve commercial purposes ranging from child nutrition fortification to adult protein supplementation in portable formats. Cheese and yogurt segments dominate value capture due to established cold-chain infrastructure and repeat purchase frequency, while pudding remains a mature category with concentrated private-label manufacturing. Single-serve packaging commands margin premiums in convenience channels, though resealable formats gain traction among adult workplace consumers seeking portion control.
FDA nutrition labeling rules and USDA organic certification standards shape product formulation decisions for US market access, while EU EFSA health claim evaluations determine permissible marketing language across member states. The EU F-Gas Regulation and pending packaging waste directives further constrain refrigeration and material choices for cross-border suppliers. Stakeholders must monitor evolving front-of-pack warning label regimes in Latin America and Southeast Asia that threaten brand portability for standardized global recipes.
Market Dynamics
Clean-label regulations across the European Union and shelf-stable processing innovations are compressing formulation cycles while forcing simultaneous investment in cold-chain efficiency and ambient-stable alternatives.
Growth Catalysts
- EFSA Health Claim Evaluations:Permissible marketing language for protein fortification claims in cheese snacks drives premium positioning across EU member states, accelerating R&D investment in clinically validated formulations.
- Urban Protein Demand:Indian metropolitan households shifting toward convenience foods create pull-through for single-serve yogurt and fortified pudding formats in modern trade channels.
- Fermentation Advancement:Precision-controlled starter culture technologies reduce spoilage rates in ambient-stable cheese products, expanding distribution reach beyond refrigerated infrastructure.
Market Restraints
- Pasture Volatility:Oceania milk supply fluctuations concentrate input cost risk for commodity cheddar processors dependent on Fonterra auction pricing mechanisms.
- F-Gas Regulation Constraints:EU restrictions on hydrofluorocarbon refrigerants inflate cold-chain capex for cross-border cheese snack logistics, squeezing margin on temperature-sensitive formats.
- Plant-Based Substitution:Oat and almond protein isolates capture shelf space in convenience channels, threatening repeat purchase frequency for traditional dairy snacks among flexitarian demographics.
Strategic Opportunities
- Workplace Portion Control:Resealable multi-serve packaging formats address adult snacking occasions in German and French office environments, commanding margin premiums over single-serve alternatives.
- USDA Organic Certification:Federal organic standards create tiered pricing architecture for clean-label cheese snacks, enabling brand differentiation in saturated North American retail.
- Chilled Distribution Convergence:Integration of direct-to-consumer cold-chain logistics with existing pharmaceutical networks opens last-mile efficiency gains for probiotic yogurt subscriptions.
Industry Challenges
- Whey Protein Procurement:Arla Foods' farmer-owned cooperative structure limits third-party access to stable whey supplies, forcing competitors into spot-market volatility or backward integration investments.
- Front-of-Pack Labeling Divergence:Latin American warning label regimes and Southeast Asian nutrient profiling schemes fragment global recipe standardization, multiplying SKU complexity for multinational portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Snacks Market |
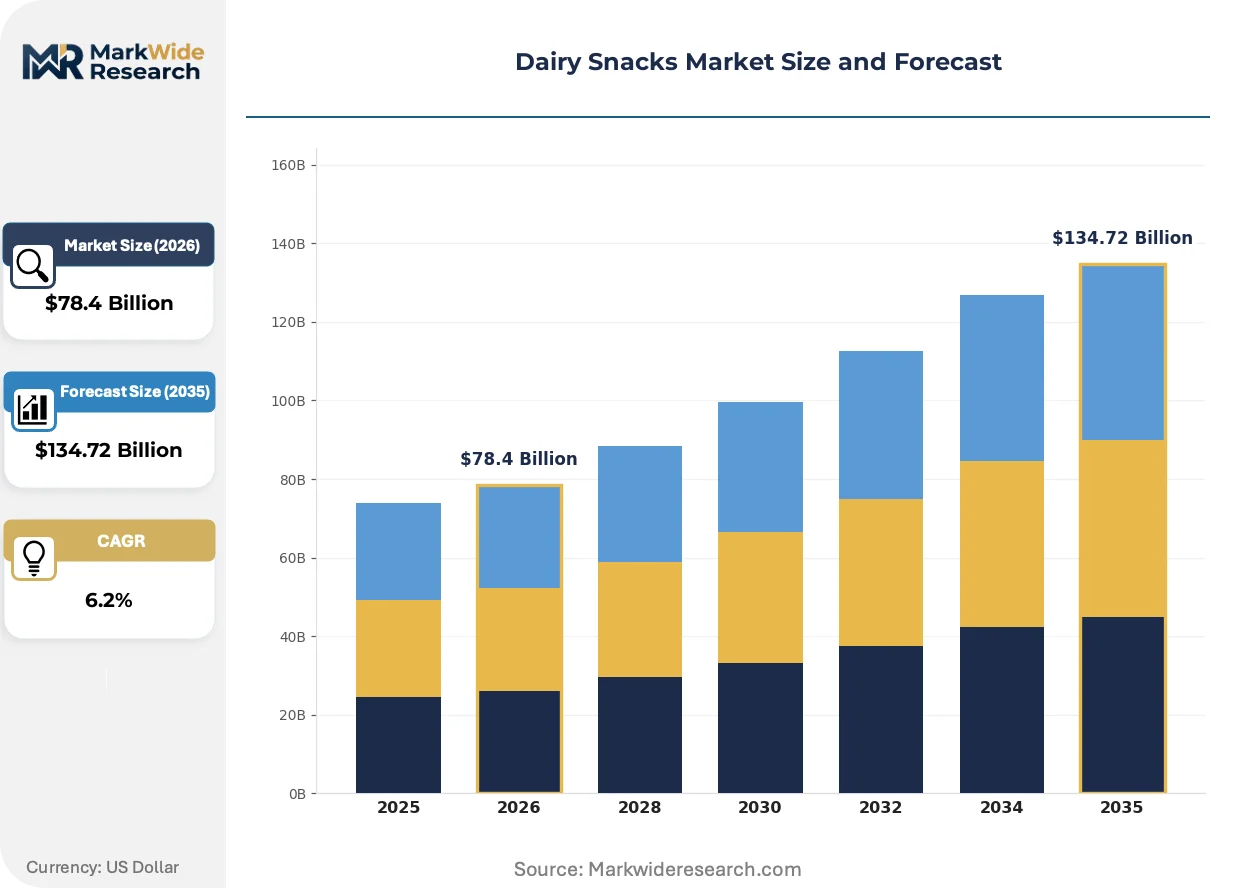
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheese, Yogurt, Cream Cheese, Pudding Packaging Type: Single-Serve, Multi-Pack, Bulk, Resealable End User: Children, Adults, Seniors, Health-Conscious Consumers Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops |
| Companies Covered | Dairy Farmers of America, Arla Foods, Nestlé, Saputo, Fonterra, Danone, General Mills, Yili Group, Lactalis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Snacks Market Strategic Shifts & Innovations
Active fermentation control and alternative protein integration are compressing traditional processing timelines while regulatory fragmentation multiplies compliance burdens across export markets.
High-pressure processing technology is rewriting shelf-life extension protocols for fresh cheese snacks. German retail chains are adopting HPP-treated mozzarella sticks at pace, enabling ambient distribution without sacrificing texture integrity. This compression of cold-chain dependency is unlocking convenience channel penetration previously blocked by refrigeration requirements.
EU packaging waste directives are mandating recycled content minimums for single-serve dairy formats. Industrial consequence includes accelerated shift toward paper-based barrier films and deposit-return scheme participation in France and Germany. Yogurt segments face highest compliance cost exposure due to multi-layer cup complexity, driving consolidation toward mono-material alternatives.
Subscription-based replenishment models are displacing impulse purchasing in adult protein snacking. Direct-to-consumer platforms capture recurring revenue from UK and US workplace consumers, replacing traditional convenience store restocking cycles. This channel rotation is most visible in metropolitan clusters where chilled last-mile infrastructure overlaps with existing meal-kit logistics networks.
Dairy Snacks Market Segmentation
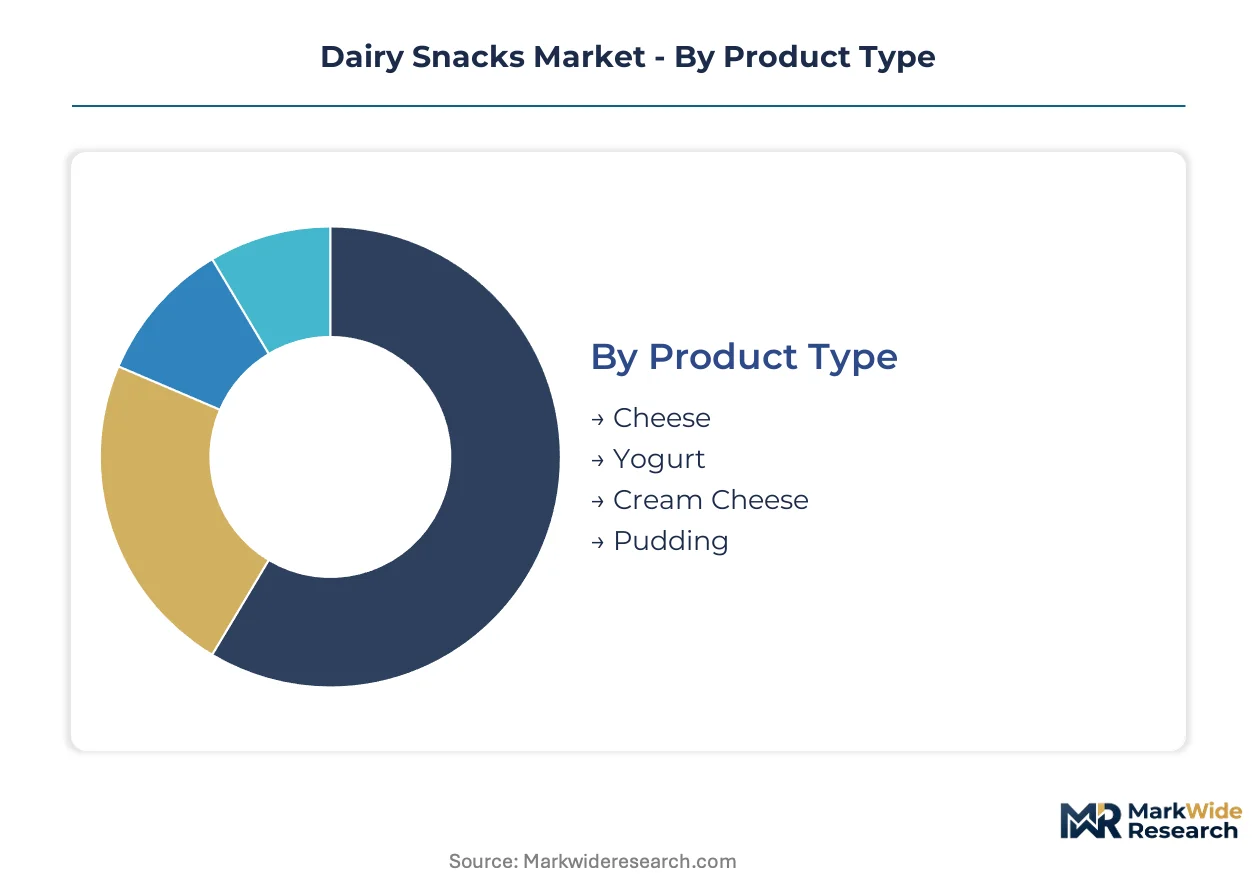
Segmentation in dairy snacks reveals how formulation, packaging, and channel choices determine margin capture and cold-chain investment requirements. Distinct consumption occasions across age cohorts and purchase settings force parallel product architectures rather than one-size-fits-all approaches.
Product Type:
Cheese and yogurt segments operate as standalone snacking formats with established chilled infrastructure, while pudding and cream cheese embed more deeply into meal occasions or recipe applications.
- Cheese:Processed milk solids ranging from 45% in fresh mozzarella formats to 60% in aged cheddar snacks, with moisture content engineered below 50% for shelf stability. German and French retail chains concentrate demand for portion-controlled cheese sticks, driven by workplace protein snacking and EFSA-permissible health claims around calcium fortification.
- Yogurt:Fermented milk products with live culture counts maintained above 10^6 CFU/g through cold-chain preservation, spanning drinkable, Greek-style, and layered fruit varieties. Indian metropolitan households generate fastest expansion for single-serve probiotic formats as urban convenience demand accelerates in modern trade channels.
- Cream Cheese:Spreadable fresh cheese with 33-55% milk fat content, primarily embedded in bagel and cracker pairing occasions rather than standalone consumption.
- Pudding:Heat-treated dairy desserts with starch or egg-based thickening, largely mature in Western markets with concentrated private-label manufacturing.
Volume placements concentrate in Cheese; the faster expansion belongs to Yogurt.
Packaging Type:
Packaging economics split between premium single-serve formats commanding impulse margins and efficiency-driven multi-unit configurations for household replenishment.
- Single-Serve:Individual portions from 30-100g in plastic cups, foil-lidded pots, or flow-wrapped bars, optimized for convenience channel velocity and portion-controlled consumption. UK and US workplace consumers drive recurring demand through grab-and-go refrigerated fixtures in urban transit hubs.
- Resealable:Zip-lock or screw-cap formats enabling multi-occasion consumption without spoilage, capturing adult consumers seeking portion flexibility. German office environments show strongest adoption for resealable cheese snack pouches as employers provision shared refrigeration.
- Multi-Pack:Bundled unit configurations reducing per-serve cost for household pantry stocking, common in yogurt and pudding categories.
- Bulk:Foodservice-scale packaging for institutional catering and ingredient applications, bypassing retail markup structures.
Margin concentration sits with Single-Serve; resealable formats are climbing the fastest as workplace consumption patterns mature.
End User:
Age-based segmentation maps directly onto nutritional positioning requirements and regulatory oversight intensity, from child-targeted fortification to senior-friendly texture modifications.
- Children:Products with controlled sugar ceilings and fortified calcium or vitamin D, subject to strict front-of-pack marketing restrictions in multiple jurisdictions. French and German retailers enforce placement protocols limiting child-targeted snacks to designated aisle sections.
- Health-Conscious Consumers:High-protein, low-lactose, or organic-certified formats with clean-label ingredient decks, commanding tiered pricing premiums. US organic certification through USDA standards enables brand differentiation in saturated retail environments.
- Adults:Convenience-optimized formats for between-meal protein supplementation without specific health condition targeting.
- Seniors:Texture-modified and nutrient-dense options addressing chewing difficulty and elevated protein requirements in aging populations.
Revenue capture skews toward Health-Conscious Consumers; children-targeted formats face steepest regulatory headwinds.
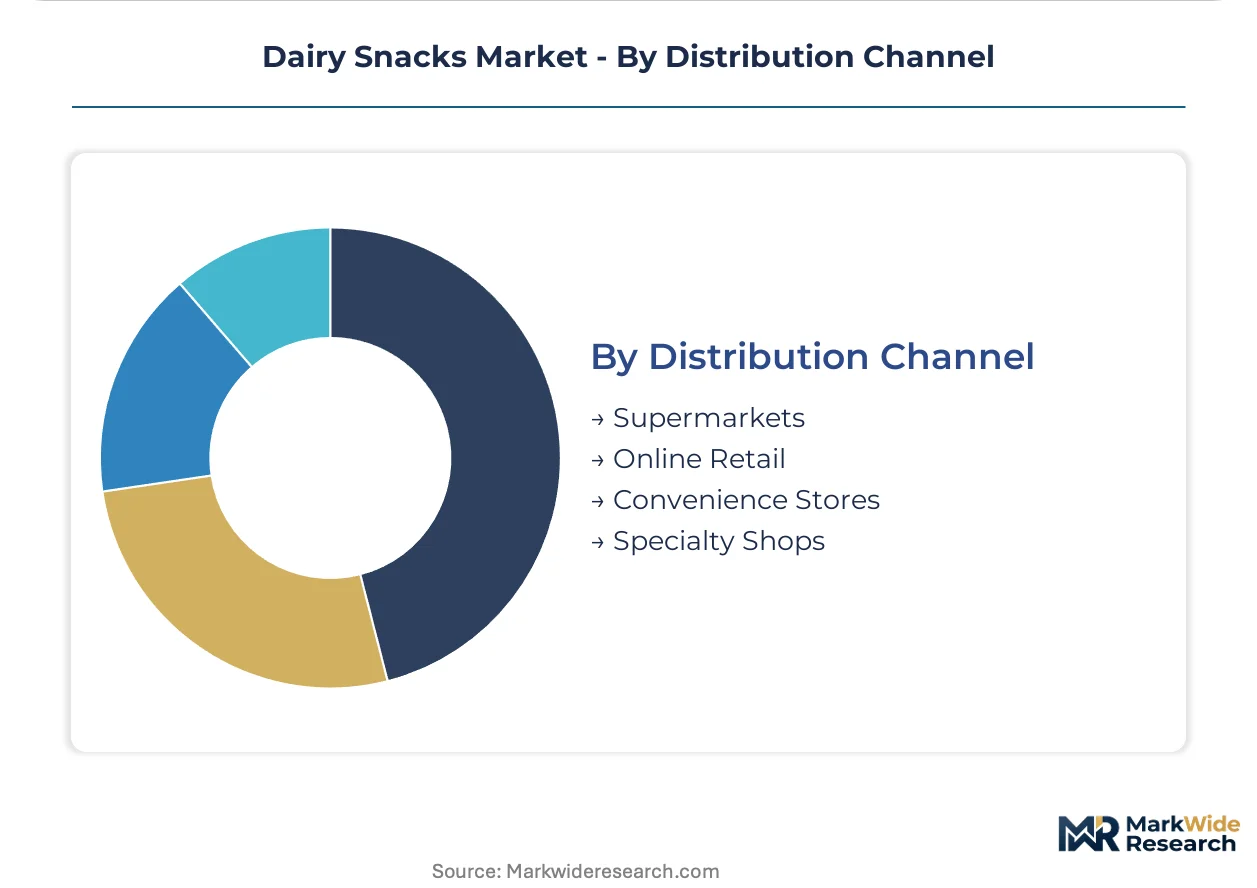
Distribution Channel:
Channel mix determines cold-chain capex recovery timelines, with direct-to-consumer platforms displacing traditional convenience store replenishment in protein snacking categories.
- Supermarkets:Full-category refrigerated sets with highest SKU breadth, absorbing fixed cold-chain costs across high-velocity traffic. French and German chains are adopting HPP-treated cheese formats to reduce refrigeration dependency in ambient aisle expansion.
- Online Retail:Subscription-based replenishment models capturing recurring revenue through chilled last-mile logistics overlapping with meal-kit distribution networks. UK metropolitan clusters show strongest penetration for yogurt subscription services.
- Convenience Stores:Impulse-oriented single-serve placement with premium pricing power, though losing share to planned online replenishment.
- Specialty Shops:Curated artisan and import cheese selections with educated staff, serving premium gifting and entertaining occasions.
Transaction volume concentrates in Supermarkets; Online Retail is gaining share fastest as subscription mechanics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pasture-rich regions in New Zealand and the Netherlands anchor raw milk supply for processed snack formats. Urban protein demand in Asian megacities and European workplace snacking patterns reshape finished goods distribution.
United States
Workplace protein snacking and child nutrition fortification drive single-serve yogurt and cheese stick demand. FDA nutrition labeling rules and USDA organic certification standards constrain formulation choices for national distribution. Wisconsin and California dairy cooperatives concentrate fluid milk processing capacity while shifting toward higher-margin snack formats.
Germany
Office-based portion control and EFSA-permissible health claims accelerate resealable cheese snack adoption. EU F-Gas Regulation inflates cold-chain capital expenditure for cross-border logistics. Bavarian and North Rhine-Westphalian retail chains lead HPP-treated mozzarella deployment to reduce refrigeration dependency.
India
Metropolitan convenience demand and urban household protein supplementation pull single-serve probiotic yogurt expansion. FSSAI fortification guidelines and front-of-pack labeling proposals reshape product positioning. Mumbai and Delhi modern trade channels concentrate fastest growth for fortified pudding formats.
France
Premium chilled distribution and clean-label ingredient preferences sustain margin capture in cheese snack segments. EU packaging waste directives mandate recycled content minimums for single-serve formats. Parisian retail headquarters coordinate deposit-return scheme participation for multi-layer yogurt cup alternatives.
China
Middle-class protein diversification and gift-oriented premium positioning drive imported cheese snack demand. SAMR food safety standards and GB labeling requirements complicate cross-border recipe standardization. Yangtze River Delta cold-chain infrastructure supports probiotic yogurt subscription growth in Shanghai and Hangzhou metropolitan clusters.
Dairy Snacks Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue ambient-stable processing and direct-to-consumer subscription mechanics. The vendor base clusters around dairy cooperative structures, multinational packaged food conglomerates, and regional chilled distribution specialists. Three archetypes dominate: farmer-owned cooperatives securing upstream milk supply, brand houses leveraging controlled cold-chain networks, and private-label manufacturers serving retail consolidation. Competitive moves concentrate on fermentation technology licensing and backward integration into whey protein processing.
Within the cooperative archetype, Fonterra and Arla Foods exemplify farmer-owned structures that anchor stable milk solids supply for commodity and premium snack lines. Nestlé and Danone occupy positions as multinational brand houses with established chilled distribution depth across Western European and North American retail networks. Yili Group represents the scale-driven regional specialist with concentrated domestic market penetration.
| Leading Market Players |
|---|
| Dairy Farmers of America |
| Arla Foods |
| Nestlé |
| Saputo |
| Fonterra |
| Danone |
| General Mills |
| Yili Group |
| Lactalis |
| Others |
Cost & Logistics Intelligence
Farmer-owned cooperative structures across Oceania and Northern Europe anchor raw milk procurement, translating pasture volatility directly into input cost pass-through mechanisms that discipline pricing across commodity cheddar and whey protein derivatives. This ownership concentration limits spot-market liquidity, forcing private-label manufacturers and multinational brand houses into long-term offtake negotiations that harden price floors even as retail competition intensifies.
Pricing Analysis
Warranty and freshness guarantees bundled into chilled distribution contracts command premium positioning against unbundled ambient-stable alternatives. Three-tier pricing structure across organic-certified, conventional chilled, and private-label economy levels segments buyer archetypes by cold-chain investment capacity. Pricing pressure stems from Fonterra's auction-based milk powder pricing transmitting Oceania pasture volatility into European processing margins. Private-label purchasers exhibit highest price sensitivity, while probiotic yogurt subscribers accept recurring premium pricing for guaranteed live culture counts.
Supply Chain Analysis
Refrigerated freight cost inflation across EU cross-border lanes concentrates margin pressure on temperature-sensitive cheese formats, accelerating HPP-treated product adoption. Raw milk supply concentrates in New Zealand, the Netherlands, and Germany, with whey protein processing anchored in Denmark and Wisconsin. Input dependencies span starter cultures from French and Italian specialist suppliers, barrier films complying with EU packaging waste directives, and pharmaceutical-grade cold-chain equipment facing F-Gas Regulation constraints. Single-source vulnerability sits with Fonterra's auction mechanism for commodity cheddar inputs. Distribution runs through supermarket refrigerated sets absorbing fixed capex, with direct-to-consumer platforms capturing subscription replenishment in UK and US metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Milk solids processing capacity constraints in pasture-dependent regions prop pricing discipline, as Fonterra's auction mechanism and EU F-Gas refrigeration restrictions limit rapid supply expansion. This supply-constrained structure favors incumbents with locked-in farmer relationships and stranded cold-chain assets.
For Market Incumbents: Acquire precision fermentation technology licenses to hedge against plant-based substitution threats from oat and almond protein isolates. Backward integration into whey protein processing reduces spot-market exposure from Arla Foods' cooperative supply dominance. Expand HPP-treated capacity in Germany and France to deflect F-Gas refrigeration capex inflation.
For New Entrants and Emerging Players: Begin with ambient-stable cheese formats targeting Indian metropolitan convenience channels where refrigerated infrastructure remains underdeveloped. Direct-to-consumer probiotic yogurt subscriptions in UK and US workplace clusters offer white-space penetration before supermarket slotting fee barriers harden. Partner with existing meal-kit logistics networks to bypass last-mile cold-chain buildout.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap private-label manufacturers with concentrated retailer relationships in France and Germany, where EU packaging waste compliance costs squeeze sub-scale competitors. Long-term viability hinges on mono-material packaging transition completion and HPP technology adoption. Monitor Fonterra auction price volatility as inflection signal for commodity cheddar margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| HPP Technology Licensing | German retail chains adopt ambient-stable mozzarella formats, reducing F-Gas refrigeration dependency. |
| Mono-Material Packaging Transition | EU packaging waste directives force yogurt cup redesign, consolidating supplier bases toward compliant film specialists. |
| Direct-to-Consumer Platform Launch | UK metropolitan subscription mechanics displace convenience store impulse cycles with recurring revenue capture. |
| Backward Integration into Whey Processing | Captive supply insulates against Arla Foods' cooperative supply restrictions and spot-market volatility. |
| Precision Fermentation Partnership | Alternative protein R&D hedges brand portfolios against flexitarian demographic shift in North American convenience channels. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated against primary interviews with dairy cooperative procurement directors, supermarket category buyers, cold-chain logistics operators, and FSSAI regulatory affairs specialists. Secondary sources included EU EFSA health claim submissions, USDA organic certification databases, Fonterra auction pricing archives, and Indian modern trade channel shipment records. Bottom-up volume modeling across product segments converged with top-down macroeconomic anchoring.
Granularity-level modeling operated at individual SKU configuration, capturing organic certification tier, packaging format, and distribution channel as distinct forecast dimensions. CAGRs derived from segment-level volume trajectories weighted against pasture supply elasticity and urban protein demand curves. Industry-specific inputs included EFSA-permissible health claim approval timelines and F-Gas refrigeration equipment replacement cycles.
Underlying measurement precision varies by segment; yogurt subscription volumes and HPP-treated cheese adoption carry tighter precision than emerging ambient-stable formats where infrastructure deployment remains uneven. Forecasts reflect assumptions around cold-chain capex recovery timelines and EU packaging directive enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Fried Potato Chips Market
Snacks
Specialty Snacks Market
Snacks
Low Fat Crackers Market
Snacks
Qatar Potato Chips Market
Snacks
North America Savory Snacks Market
Snacks
Granola Market
Snacks
North America Extruded Snack Food Market
Snacks
Savory Snacks Market
Snacks
Extruded Cereals Market
Snacks
Candy and Snack Food Pouches Market
Snacks
UAE Snack Bar Market
Snacks
South East Asia Snack Bar Market
Snacks
Energy Bar Market
Snacks
Allergy-Free Snacks Market
Snacks
Savory Snack Products Market
Snacks
No-Fat Peanut Butter Market