
 Candy and Snack Food Pouches Market | 2026-2036
Candy and Snack Food Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Candy and Snack Food Pouches Market Insights
India is reshaping competitive dynamics in flexible snack packaging through aggressive capacity additions in Gujarat and Maharashtra industrial corridors. Amcor Plc leverages its integrated film extrusion and converting footprint to supply multinational confectionery brands with high-barrier metallized structures. Huhtamaki Oyj anchors its position through specialized heat-seal coating technologies that extend shelf life for tropical climate distribution. Mondi Group differentiates via paper-based pouch solutions that navigate emerging single-use plastic restrictions across European retail channels.
Candy and snack food pouches are multi-layer flexible containers, typically comprising oriented polypropylene, polyethylene terephthalate, or aluminum oxide-coated films, engineered to provide moisture, oxygen, and light barriers while enabling vertical shelf presentation and consumer resealability; they serve primarily to preserve product freshness, reduce portion waste, and maximize retail space efficiency in impulse-buy environments. Stand-up pouches dominate value contribution due to premium shelf visibility and brand billboard surface area, while biodegradable film materials represent the fastest-evolving specification tier as retailers impose sustainability scorecards on suppliers. Resealable zip-lock closures command margin concentration because they command price premiums and drive repeat purchase loyalty in trail mix and granola segments where portion control matters.
The FDA governs food contact substance compliance under 21 CFR, while the EU F-Gas Regulation and REACH constrain fluorinated barrier chemistries that historically enabled ultra-high oxygen resistance. India's BIS certification requirements for food-grade plastics create market access friction for unqualified imports but protect domestic converters with certified laboratory infrastructure. Stakeholders must monitor how rapidly evolving extended producer responsibility frameworks in Europe and North America will redefine acceptable end-of-life pathways for multi-material laminate structures before committing to long-term capital equipment.
Market Dynamics
Multi-layer film recyclability mandates under the EU PPWR are forcing converters to reengineer barrier chemistries and extrusion processes ahead of enforcement timelines.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recycled content minimums and recyclability thresholds are accelerating investment in mono-material compatible barrier coatings across European converting operations.
- India modern trade expansion:Organized retail penetration in Gujarat and Maharashtra corridors is creating specification demand for humidity-resistant metallized pouches in snack food localization.
- High-barrier aluminum oxide deposition:Vacuum coating advances are replacing foil laminates in oxygen-sensitive confectionery while maintaining optical clarity and microwave compatibility.
Market Restraints
- Ethylene-vinyl alcohol resin cost volatility:EVOH pricing swings tied to ethylene feedstock markets compress margin predictability for oxygen barrier film converters.
- Fluorinated chemistry constraints:REACH and EU F-Gas Regulation phase-downs are eliminating ultra-high barrier per- and polyfluoroalkyl substances without drop-in replacements at equivalent performance.
- Multi-material laminate end-of-life complexity:Current mechanical recycling infrastructure cannot process PET/PE/EVOH combinations, forcing reliance on nascent chemical recycling capacity concentrated in Germany and Netherlands.
Strategic Opportunities
- India BIS certification gap:Domestic laboratory infrastructure scarcity creates protected market access for certified converters able to navigate food-grade plastic compliance timelines.
- Paper-based flexible packaging:Emerging single-use plastic restrictions across French and German retail channels are opening specification windows for fiber-dominant pouch structures with heat-seal coatings.
- Resealable closure integration:Zip-lock and slider technologies are penetrating trail mix and granola segments where portion control drives repeat purchase loyalty and price premium capture.
Industry Challenges
- Extended producer responsibility compliance:Rapidly evolving EPR frameworks in France, Germany, and Italy require real-time tracking of packaging material flows and fee structures without standardized data protocols.
- Heat-seal coating reformulation:Migrating from solvent-based to water-based adhesive systems demands capital-intensive drying equipment upgrades and validation cycles for tropical climate distribution performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Candy and Snack Food Pouches Market |
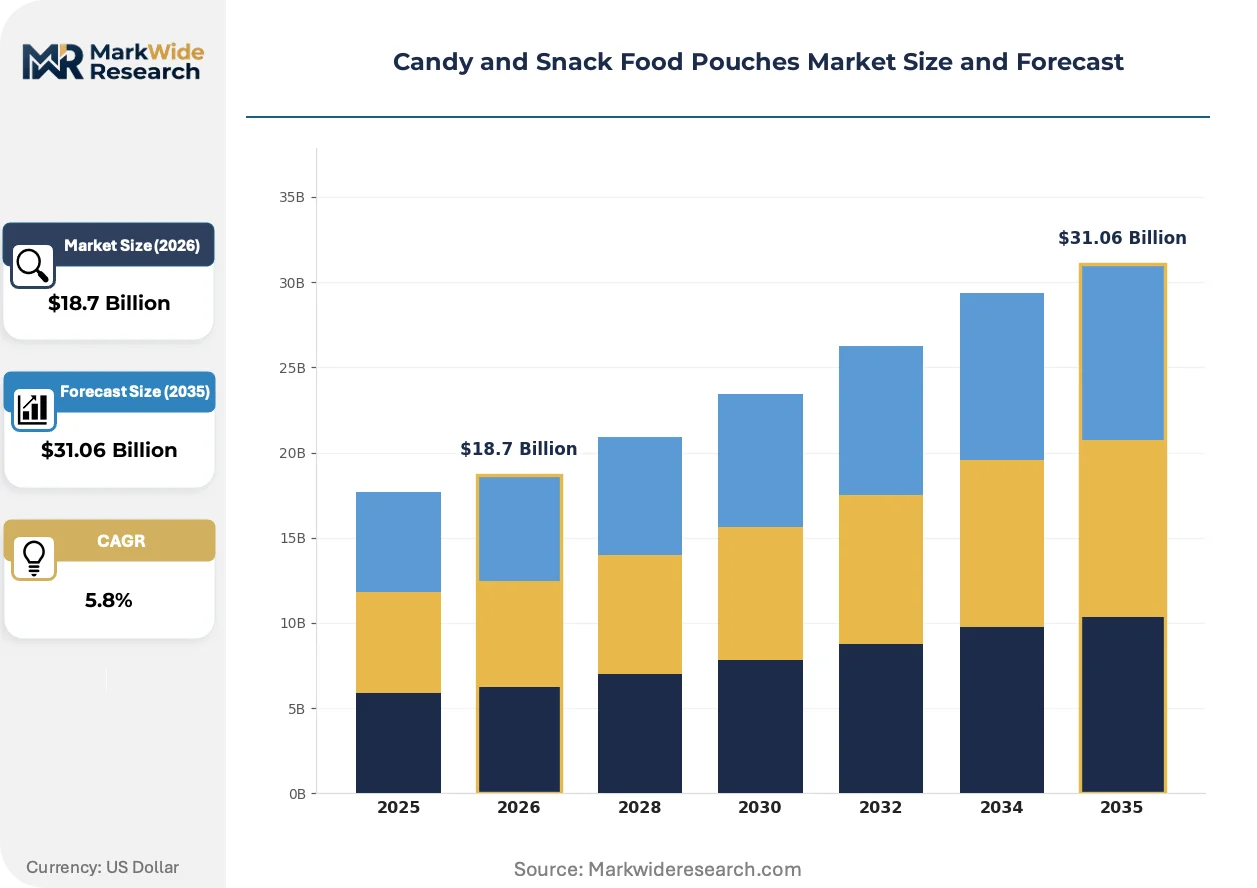
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Resealable Pouches, Stand-Up Pouches, Flat Pouches, Vacuum Pouches Material: Plastic, Paper, Metallized Film, Biodegradable Film Closure Type: Zip Lock, Press Seal, Heat Seal, Taping End Use: Candies, Nuts, Granola, Trail Mix |
| Companies Covered | Amcor Plc, Huhtamaki Oyj, Berry Global, Mondi Group, Toppan Inc., Sonoco, Sealed Air, Printpack, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Candy and Snack Food Pouches Market Trends and Innovations
Digital printing and smart packaging integration are compressing batch minimums and enabling mass customization while regulatory chemistry bans force material science pivots.
Digital flexographic and inkjet printing systems are digitizing short-run brand versioning for seasonal confectionery launches. Regional snack food manufacturers in India and Southeast Asia are adopting these systems to bypass plate costs and reduce lead times from weeks to days. This capability is digitizing the economics of limited-edition packaging, collapsing the volume threshold for economically viable customization.
REACH authorization restrictions on perfluorinated compounds are eliminating legacy ultra-high barrier chemistries from European food contact applications. Converters must validate aluminum oxide and silicon oxide vacuum-deposited alternatives that match oxygen transmission rates without fluorinated polymer additives. High-fat nut and chocolate applications in Germany and Benelux markets face the steepest reformulation timelines.
Urban millennial and Gen Z consumption patterns are fragmenting pack size demand toward single-serve and sharing formats. Convenience store and e-commerce direct-to-consumer channels in Indian metropolitan areas are displacing traditional multi-pack warehouse club specifications. This rotation is most visible in Mumbai and Bangalore, where on-the-go snacking occasions now dominate new product development briefs.
Candy and Snack Food Pouches Market Segmentation
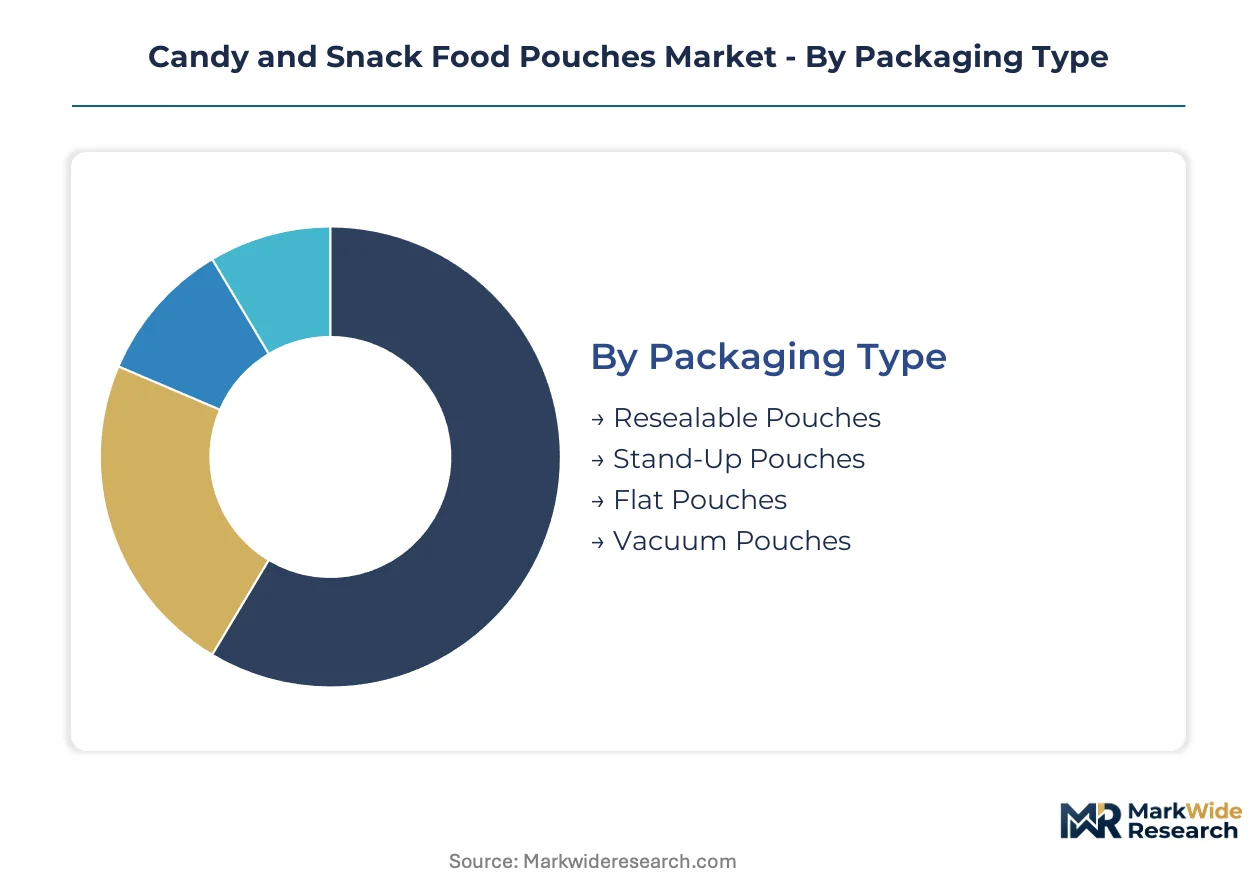
Candy and snack food pouch specifications fragment across four structural dimensions that determine barrier performance, shelf presence, and regulatory compliance. Material chemistry and closure mechanics now dominate procurement decisions as sustainability mandates and convenience expectations reshape converter priorities.
Packaging Type:
Mature formats dominate volume while emerging configurations capture specification shifts driven by retail channel evolution.
- Resealable Pouches:Multi-layer laminates incorporating zip-lock or slider mechanisms enable repeated access while maintaining moisture barriers for humidity-sensitive confections. Indian metropolitan convenience stores and direct-to-consumer e-commerce channels in Mumbai and Bangalore are specifying these for single-serve trail mix and granola portions where portion control drives repeat purchase behavior.
- Stand-Up Pouches:Gusseted bottom structures provide vertical shelf stability and maximum brand-facing surface area for impulse-buy environments. European retail chains in Germany and France are mandating these for premium chocolate and nut assortments where shelf visibility determines placement economics.
- Flat Pouches:Two-seal configurations minimize material usage for cost-sensitive bulk confectionery distribution.
- Vacuum Pouches:High-barrier structures with oxygen scavenging layers extend shelf life for oxidation-prone nut applications.
Stand-up pouches handle the majority of throughput; resealable pouches are the fastest mover on share.
Material:
Cost tier stratification separates commodity substrates from premium specifications as regulatory chemistry bans force material pivots.
- Plastic:Oriented polypropylene and polyethylene terephthalate laminates remain the baseline for moisture and oxygen barrier performance in high-volume confectionery. REACH and EU F-Gas Regulation constraints on fluorinated additives are forcing converters toward aluminum oxide-coated alternatives for equivalent barrier properties without per- and polyfluoroalkyl substances.
- Paper:Fiber-dominant structures with heat-seal coatings are gaining specification in French and German retail channels where single-use plastic restrictions are tightening. Mondi Group and similar converters are scaling capacity for these structures as supermarket sustainability scorecards penalize petroleum-derived substrates.
- Metallized Film:Vacuum-deposited aluminum layers provide light and oxygen barriers for tropical climate distribution in India.
- Biodegradable Film:Polylactic acid and starch-based alternatives are emerging for compostable certification requirements in select European markets.
Plastic substrates handle the majority of throughput; paper-based structures are climbing the fastest on share.
Closure Type:
Application requirements determine sealing mechanism selection, with premium positioning correlating to reseal functionality.
- Zip Lock:Interlocking plastic tracks enable consumer-controlled resealability for multi-occasion consumption patterns. Trail mix and granola segments in organized Indian retail are specifying these for price premium capture and brand loyalty reinforcement.
- Press Seal:Adhesive-based reclosure provides lower-cost resealability for mid-tier confectionery specifications.
- Heat Seal:Permanent fusion bonding remains standard for single-serve portions and tamper-evident requirements.
- Taping:Pressure-sensitive adhesive strips offer limited reclosure for economy-tier bulk formats.
Heat seal handles the majority of throughput; zip lock is gaining share fastest.
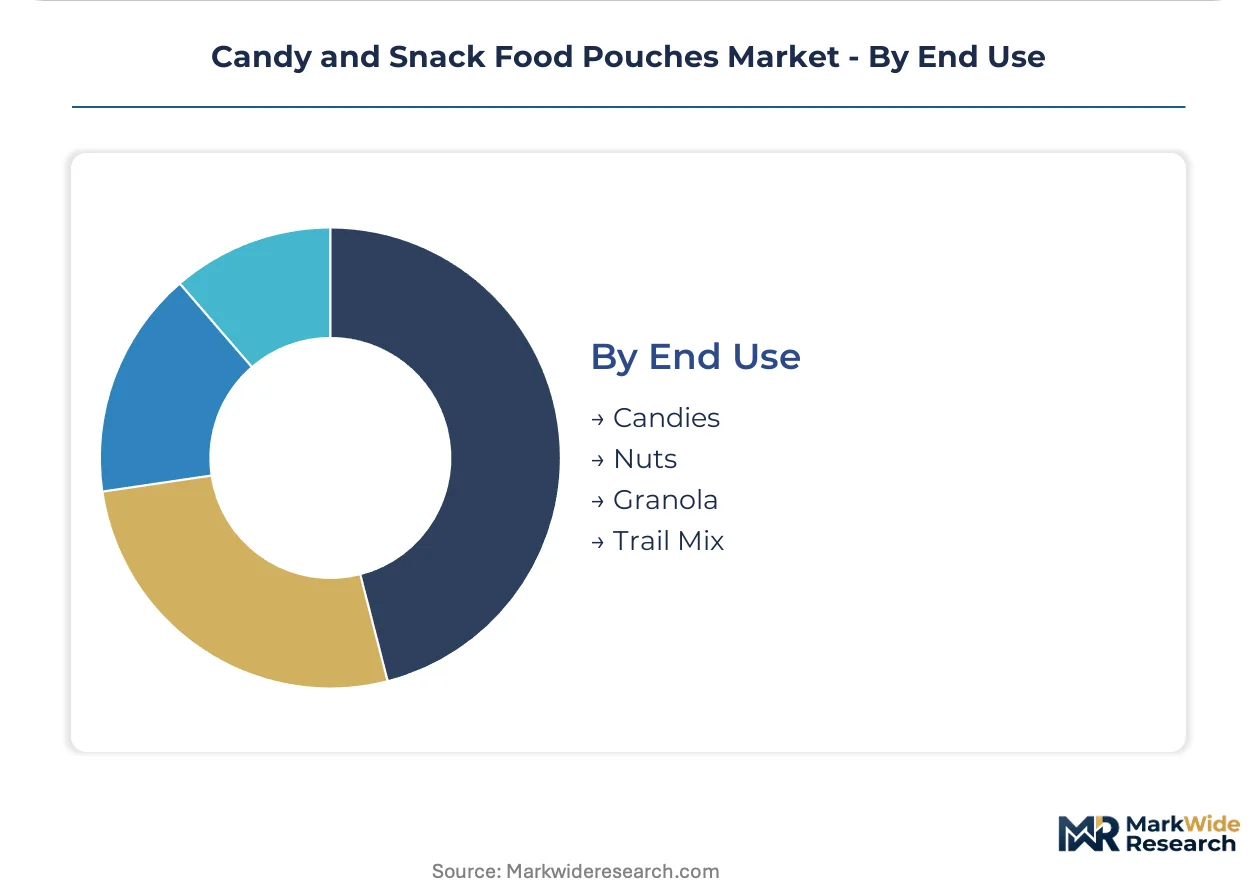
End Use:
Customer type fragmentation separates impulse confectionery from health-positioned snacking segments with distinct barrier requirements.
- Candies:Sugar-based and chocolate confectionery demand high moisture barriers and fat migration resistance. German and Benelux markets are driving specification for aluminum oxide-coated films as REACH eliminates legacy fluorinated barrier chemistries from high-fat chocolate applications.
- Nuts:Oil-rich substrates require ultra-low oxygen transmission rates to prevent rancidity in extended distribution cycles.
- Granola:Clustered cereal formats with dried fruit inclusions need humidity control and crispness preservation.
- Trail Mix:Heterogeneous ingredient mixes with varying moisture and fat content present complex barrier engineering challenges for multi-component shelf stability.
Candies handle the majority of throughput; trail mix is expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS certification framework for food-grade plastics anchors the dominant geography, creating protected market access for certified converters while the EU PPWR and REACH reshape European specification requirements ahead of enforcement deadlines.
India
Modern trade expansion in Gujarat and Maharashtra corridors drives specification demand for humidity-resistant metallized pouches as snack food localization accelerates. BIS certification requirements create market access friction for unqualified imports while protecting domestic converters with certified laboratory infrastructure. The Mumbai-Pune industrial belt concentrates capacity additions for barrier film extrusion serving organized retail penetration.
Germany
REACH authorization restrictions on perfluorinated compounds eliminate legacy ultra-high barrier chemistries from chocolate and nut applications in German and Benelux markets. The EU F-Gas Regulation phase-down forces converters toward aluminum oxide vacuum-deposited alternatives without drop-in replacements at equivalent performance. The Ruhr industrial region hosts chemical recycling infrastructure development for multi-material laminate processing.
United States
FDA 21 CFR compliance requirements govern food contact substance migration limits for confectionery packaging specifications across impulse-buy retail channels. Urban millennial and Gen Z consumption patterns fragment pack size demand toward single-serve and sharing formats in convenience store and e-commerce direct-to-consumer channels. The Chicago-Milwaukee corridor maintains converting capacity for high-barrier metallized structures.
France
Single-use plastic restrictions across French retail channels open specification windows for fiber-dominant pouch structures with heat-seal coatings as supermarket sustainability scorecards penalize petroleum-derived substrates. Extended producer responsibility frameworks require real-time tracking of packaging material flows without standardized data protocols. The Lyon-Grenoble cluster advances paper-based flexible packaging capacity for premium chocolate assortments.
Japan
METI standards and JIS certification requirements shape barrier film specifications for oxidation-prone nut applications in extended distribution cycles. High-fat confectionery demand drives specification for ultra-low oxygen transmission rate structures. The Kanto region around Tokyo concentrates converting operations for seasonal confectionery launches with digital printing integration.
Candy and Snack Food Pouches Market Competitive Landscape
Capability concentration sits with integrated film extrusion and converting specialists; scale advantage sits with diversified packaging conglomerates with multinational manufacturing footprints. The market structure tiers between premium barrier technology developers and volume-driven commodity converters. Three archetypes dominate: integrated film-to-pouch converters, specialized coating technology providers, and paper-based sustainable packaging innovators. Competitive moves concentrate on mono-material compatible barrier coating investments and paper-based capacity scaling for plastic-restricted retail channels.
Within the integrated converter tier, Amcor Plc and Huhtamaki Oyj exemplify archetypes of multinational packaging conglomerates with film extrusion and converting footprints spanning multiple geographies. Amcor Plc represents the scale-driven integrated model with metallized barrier supply capabilities. Huhtamaki Oyj occupies a position emphasizing specialized heat-seal coating technologies. Mondi Group anchors the paper-based sustainable packaging vector with fiber-dominant pouch solutions navigating European single-use plastic restrictions.
| Leading Market Players |
|---|
| Amcor Plc |
| Huhtamaki Oyj |
| Berry Global |
| Mondi Group |
| Toppan Inc. |
| Sonoco |
| Sealed Air |
| Printpack |
| ProAmpac |
| Others |
Pricing and Supply Chain Analysis
The Mumbai-Pune industrial belt anchors capacity additions for barrier film extrusion, concentrating supply-side leverage among certified converters who command premium positioning in organized retail channels. This geographic concentration feeds downstream pricing power dynamics as BIS compliance requirements filter out unqualified imports and protect domestic laboratory infrastructure investments.
Pricing Analysis
Indian metropolitan markets trade at 15-25% premiums to European contract benchmarks due to humidity-resistant metallized specifications and tropical climate distribution requirements. Pricing stratifies across premium, standard, and economy tiers where resealable zip-lock closures capture margin concentration through repeat purchase loyalty mechanics. Cost compression in standard-tier polyethylene laminates is intensifying because EVOH feedstock volatility compresses converter predictability. Commodity flat pouch buyers in bulk confectionery distribution exhibit highest price sensitivity, while premium chocolate brands in German retail channels absorb barrier coating premiums for aluminum oxide deposition clarity.
Supply Chain Analysis
Extended payment terms from multinational confectionery brands now stretch to 90-120 days, forcing mid-tier converters toward supply-chain finance facilities anchored by integrated film extrusion players. Raw material dependencies center on ethylene feedstock markets, oriented polypropylene resin, and vacuum-deposited aluminum oxide coatings sourced from Germany and Japan. Single-source vulnerability concentrates in EVOH barrier resin supply where ethylene-vinyl alcohol pricing swings tether margin stability to petrochemical commodity cycles. Distribution runs through organized retail procurement offices in Gujarat and Maharashtra corridors, with direct-to-consumer e-commerce channels in Bangalore and Mumbai fragmenting traditional warehouse club specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU PPWR recyclability mandates constitute a regulatory inflection that will eliminate multi-material laminate structures from European food contact applications, compressing the window for mono-material compatible barrier coating investments. This disruption accelerates competitive sorting between integrated converters with capital deployment capacity and commodity players trapped in legacy chemistries.
For Market Incumbents: Build certification moats around BIS laboratory infrastructure and EU PPWR-compliant mono-material coating validation to defend against Asian import competition and European specialty coating entrants. Prioritize backward integration into aluminum oxide vacuum deposition capacity in the Mumbai-Pune corridor to capture snack food localization demand. Channel control through direct procurement relationships with modern trade expansion in Gujarat anchors volume commitments against price erosion.
For New Entrants and Emerging Players: Maharashtra and Gujarat industrial corridors present underpenetrated specification demand for humidity-resistant metallized pouches as domestic snack food localization accelerates. Paper-based flexible packaging for French and German retail channels offers the most penetrable white-space given supermarket sustainability scorecard enforcement. A go-to-market angle targeting mid-tier Indian granola brands with digital printing-enabled short-run customization bypasses plate cost barriers that protect incumbent scale advantages.
For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-driven consolidation play because regulatory chemistry bans and EPR framework expansion will structurally disadvantage non-integrated converters without captive coating technology. Acquisition targets should screen for certified laboratory infrastructure and heat-seal coating reformulation capabilities in water-based adhesive systems. The signal to watch is EU chemical recycling capacity buildout in Germany and the Netherlands, which would unlock end-of-life value recovery for multi-material laminates and reshape acceptable film structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier Coating Investment | EU PPWR compliance eliminates legacy multi-layer laminates from European retail channels by enforcement deadlines. |
| Aluminum Oxide Vacuum Deposition Scale-Up | REACH restrictions on fluorinated chemistries force substitution for high-fat chocolate and nut applications. |
| BIS Certification Laboratory Acquisition | Domestic infrastructure scarcity creates protected market access for certified converters in Indian organized retail. |
| Paper-Based Flexible Packaging Capacity | French and German single-use plastic restrictions open specification windows for fiber-dominant heat-seal structures. |
| Resealable Closure Technology Integration | Zip-lock and slider mechanisms capture price premiums in trail mix and granola segments where portion control matters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association capacity reports to anchor supply-side assessments. Primary interviews engaged film extrusion plant managers, confectionery brand procurement leads, retail category buyers, and flexible packaging R&D directors across India, Germany, and the United States. Secondary validation drew from BIS certification databases, ECHA REACH authorization lists, EU PPWR implementation guidance, and SEC 10-K disclosures from listed packaging conglomerates. Bottom-up capacity modeling triangulated against top-down demand segmentation to constrain variance bounds.
Forecast inputs incorporate packaging type evolution, material chemistry substitution rates, closure mechanism adoption curves, and end-use fragmentation across impulse confectionery and health-positioned snacking segments. Segmentation dimensions span packaging configuration, substrate composition, sealing technology, and customer application requirements across the projection horizon. CAGRs derive from installed capacity trajectories, regulatory enforcement timelines, and channel shift elasticity parameters specific to organized retail penetration and e-commerce direct-to-consumer growth.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian integrated converters or European paper-based packaging specialists would shift outcomes beyond modeled bounds. Macroeconomic deviation in ethylene feedstock markets, accelerated EU PPWR enforcement, or breakthroughs in chemical recycling economics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
North America Extruded Snack Food Market
Snacks
Premium Snacks Market
Snacks
South Korea Snack Bar Market
Snacks
Snack Subscription Market
Snacks
North America Snack Food Market
Snacks
Jerky Snacks Market
Snacks
Protein Crisps Market
Snacks
Global Vegetable Chips Market
Snacks
North America Potato Chips Market
Snacks
South East Asia Snack Bar Market
Snacks
Refrigerated Snacks Market
Snacks
Vegan Protein Balls Market
Snacks
Specialty Snacks Market
Snacks
Spicy Sticks (Chinese Snack) Market
Snacks
Duck Neck (Chinese Snack) Market
Snacks
South America Protein Bar Market