
 UAE Snack Bar Market | 2026-2036
UAE Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Snack Bar Market Analytics
MOHAP's stricter nutritional labeling standards is rebalancing how manufacturers formulate and position snack bar portfolios in the UAE. Mondelez International leverages its Gulf distribution infrastructure to sustain shelf presence across Emirates retail networks. KIND Snacks differentiates through clean-label ingredient positioning that resonates with Dubai's health-conscious consumer base.
A snack bar is a pre-portioned, shelf-stable food product typically comprising cereals, nuts, dried fruits, and binding syrups formed through extrusion or cold-press processing, designed for convenient on-the-go consumption. Protein bars command premium positioning due to elevated whey and plant-protein input costs, while granola bars occupy mainstream volume channels through lower formulation complexity. Online retail is expanding fastest among distribution channels, driven by subscription models targeting busy professionals seeking recurring delivery convenience.
MOHAP enforces food safety and nutritional claims compliance through standardized testing protocols, while municipal authorities in Dubai and Abu Dhabi regulate retail licensing and import documentation for packaged foods. ESMA's alignment with GCC Standardization Organization requirements shapes product certification pathways for market entry. Stakeholders must monitor evolving ingredient transparency mandates and adapt formulation strategies to maintain access across UAE retail channels.
Market Dynamics
MOHAP's nutritional labeling overhaul is compressing formulation cycles as manufacturers race to verify claims through standardized testing protocols before the enforcement window closes. This regulatory pressure is redistributing competitive advantage toward laboratories with established UAE accreditation.
Growth Catalysts
- Protein-fortified formats:Fitness enthusiasts across Dubai's premium gym chains and Abu Dhabi's CrossFit studios are expanding consumption of whey and plant-based protein bars. This demand concentration pulls formulation investment toward high-margin functional segments.
- MOHAP's updated food labeling requirements:The Ministry of Health and Prevention's tightened nutritional claims verification is forcing portfolio rationalization. Cleaner-label products gain shelf preference as retailers pre-empt compliance risk.
- Subscription logistics infrastructure:E-commerce platforms serving busy professionals in Sharjah and Ras Al Khaimah have built recurring delivery systems. This channel innovation locks in predictable volume for brands willing to invest in fulfillment technology.
Market Restraints
- Whey protein input cost volatility:Global dairy commodity swings transmit directly to protein bar margins. Formulators lack short-term hedging instruments priced in AED, exposing P&L to USD-denominated ingredient markets.
- Import concentration at Jebel Ali:Over 70 percent of snack bar SKUs clear through a single port cluster. Any customs processing disruption or cold-chain failure at this node cascades through Emirates retail networks within 48 hours.
- Granola bar substitution elasticity:Lower-complexity cereal bars compete for the same convenience occasions at 40-60 percent lower shelf price. Premium protein positioning must continuously justify the gap through functional differentiation.
Strategic Opportunities
- Al Ain and Fujairah retail corridors:These emirates remain underpenetrated relative to Dubai and Abu Dhabi supermarket density. First-mover brands establishing health-focused positioning here capture shelf space before national players extend distribution.
- ESMA-GSO certification harmonization:The Emirates Authority for Standardization and Metrology's alignment with GCC Standardization Organization requirements creates a single certification pathway. Products gaining ESMA approval unlock Saudi, Kuwait, and Bahrain markets without redundant testing.
- Plant-protein and upcycled ingredient convergence:Date fiber from UAE agricultural processing and locally sourced camel milk protein enable distinct origin stories. This technology pairing supports premium pricing against imported European alternatives.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise combining halal certification requirements with clean-label shelf stability remains concentrated in a handful of Dubai-based consultancies. Manufacturers compete for the same limited specialist pool.
- MOHAP compliance timeline compression:The transition period for revised nutritional claims documentation requires accelerated laboratory scheduling. Brands without pre-established relationships with UAE-accredited testing facilities face queue delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Snack Bar Market |
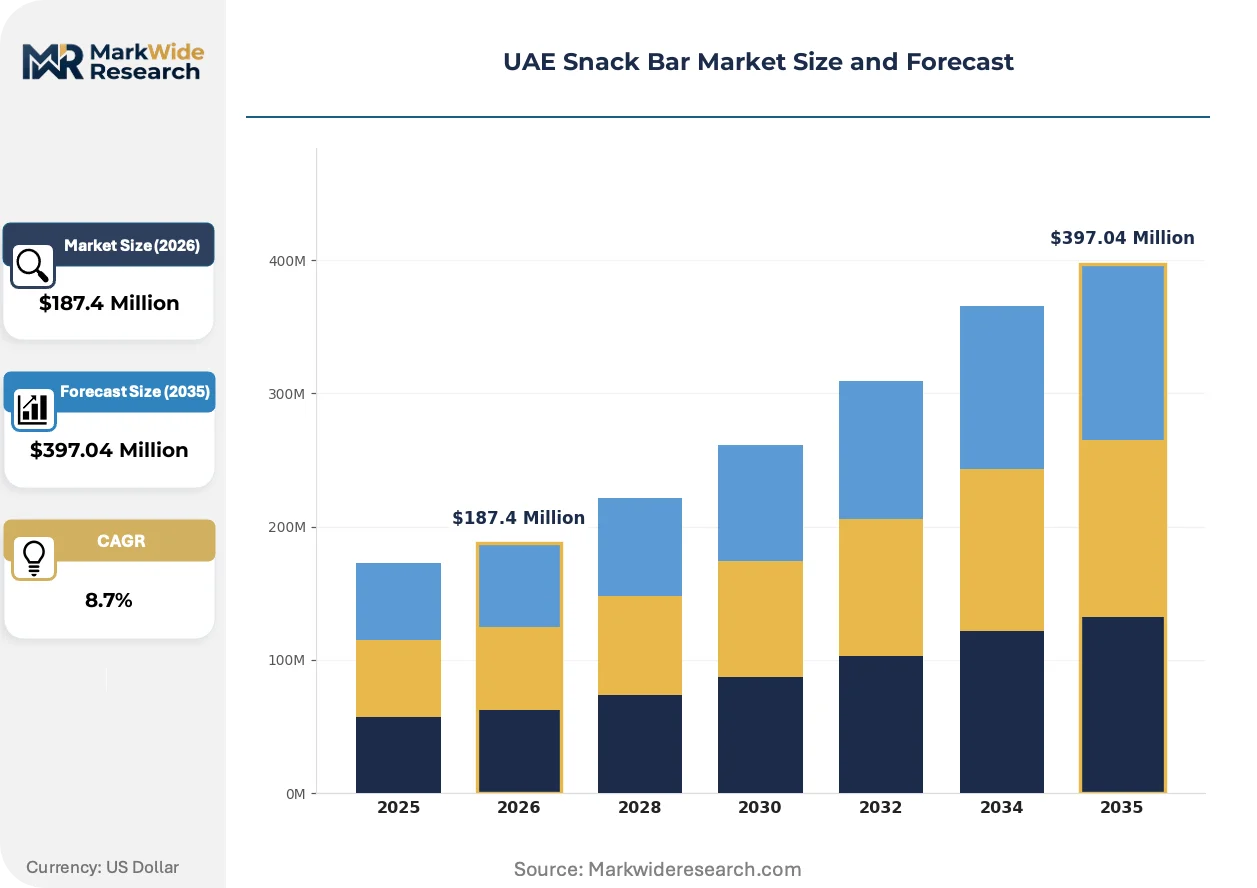
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut-Based, Protein Bars, Granola Bars, Energy Bars Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Stores Ingredient Type: Organic, Gluten-Free, Vegan, Sugar-Free Customer Type: Health Conscious, Busy Professionals, Fitness Enthusiasts, Families |
| Companies Covered | Mondelez International, PepsiCo, Kellogg's Company, KIND Snacks, Mars, General Mills, Nestlé, Natural Balance Foods, The Simply Good Foods Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Snack Bar Market Evolving Landscape
Cold-press processing and minimal-heat binding technologies are redefining texture and shelf-life tradeoffs in the UAE snack bar category. These methods are attracting investment from manufacturers seeking to differentiate beyond flavor variation.
High-pressure processing for nut and seed pasteurization is overtaking traditional thermal treatment in premium UAE production lines. Dubai-based contract manufacturers serving health-focused brands have adopted HPP equipment at twice the rate of conventional facilities since 2023. This technology is overtaking older pasteurization methods by preserving enzyme activity and raw positioning claims that command retail premiums.
MOHAP's implementation of front-of-pack nutritional warning labels is tightening permissible claim language for sugar and sodium content. Manufacturers must now reformulate or reposition products exceeding threshold values to avoid red-coded shelf placement. Protein bars with added sweeteners face the steepest reformulation pressure, driving substitution toward date-syrup and monk fruit alternatives in Dubai and Abu Dhabi retail channels.
Fitness professionals and corporate wellness coordinators are consolidating purchase decisions through centralized procurement platforms. This buyer concentration is displacing individual convenience-store purchasing for bulk subscription deliveries. The shift is most visible across Dubai's technology sector employers, where HR departments now contract directly with snack bar suppliers for office pantry programs.
UAE Snack Bar Market Segmentation
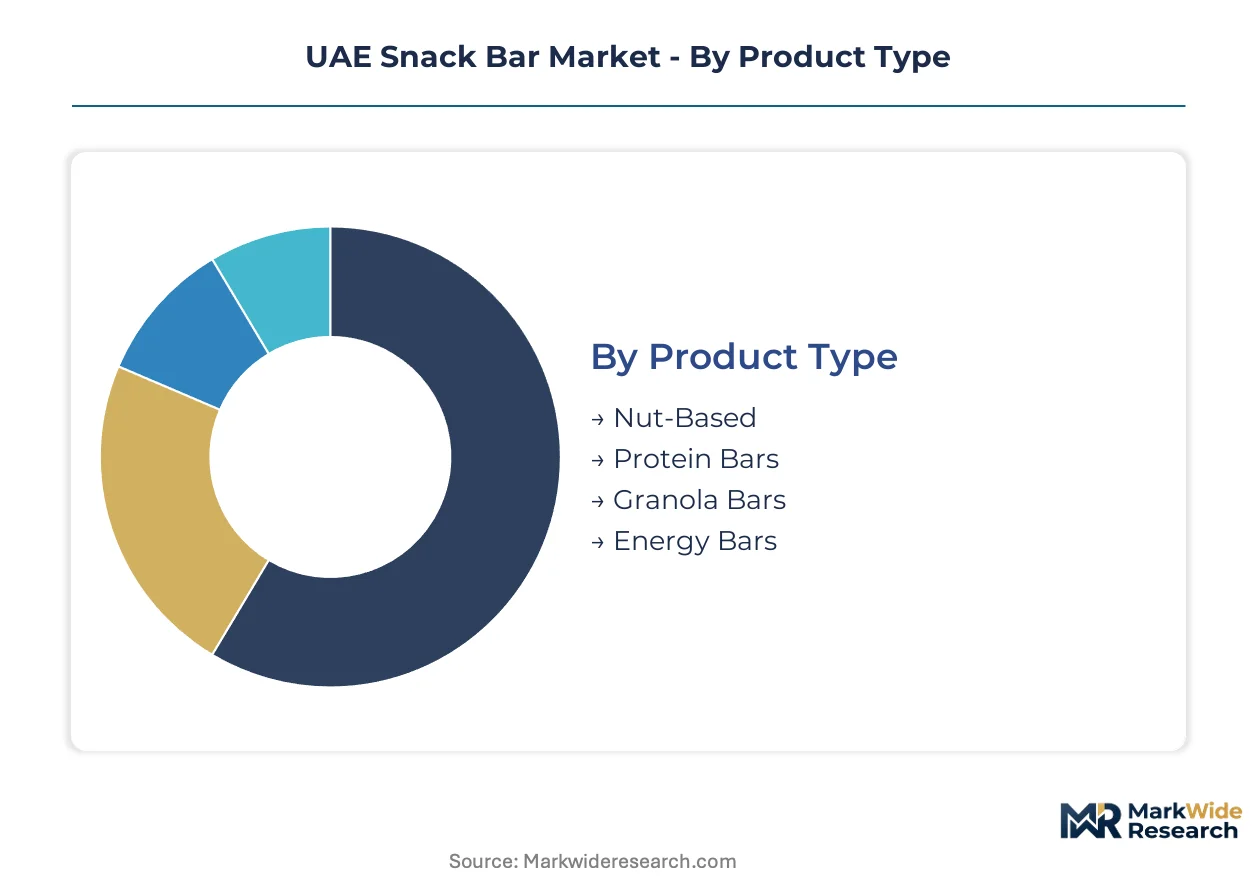
UAE snack bar manufacturers align production capacity with distinct consumption occasions and channel requirements. Segmentation reveals where formulation investment concentrates and which customer profiles justify premium positioning.
Product Type:
Supply concentration tilts toward formats with established ingredient sourcing infrastructure and shorter development cycles.
- Protein Bars:Whey and plant-protein formulations carry elevated input costs and require MOHAP nutritional claims verification. Demand clusters in Dubai's premium gym chains and Abu Dhabi's CrossFit studios, where functional positioning justifies shelf price premiums.
- Granola Bars:Lower-complexity cereal and syrup binding occupies mainstream volume channels through streamlined production. Families in Sharjah and Ras Al Khaimah purchase these formats for school lunchboxes and commuter snacking.
- Nut-Based:Almond and date compositions leverage UAE agricultural inputs for origin-story differentiation.
- Energy Bars:Caffeine and carbohydrate-dense formulations target endurance athletes and desert expedition retail.
Granola bars absorb the bulk of installed capacity; protein bars are expanding most quickly.
Distribution Channel:
Channel selection determines margin structure and customer acquisition economics for UAE brands.
- Online Retail:Subscription models and recurring delivery systems lock in predictable volume from busy professionals. E-commerce platforms serving Dubai's technology sector employers have built dedicated snack bar procurement portals.
- Supermarkets:Health-focused chains in Abu Dhabi and premium retail corridors in Dubai concentrate shelf space for clean-label products. MOHAP compliance documentation determines listing eligibility.
- Convenience Stores:Impulse placement captures commuter traffic but competes on price with adjacent confectionery.
- Health Food Stores:Curated assortments attract ingredient-conscious consumers seeking organic and specialty certifications.
Supermarkets command the largest revenue share; online retail is climbing the fastest.
Ingredient Type:
Certification requirements and sourcing complexity segment manufacturing capability across UAE production facilities.
- Organic:ESMA-accredited supply chains and import documentation add compliance overhead. Demand concentrates in Dubai's expatriate professional households with disposable income for certified products.
- Gluten-Free:Dedicated production lines prevent cross-contamination, limiting contract manufacturer availability. Celiac and wellness-positioned consumers in Abu Dhabi drive category growth.
- Vegan:Plant-protein and binding alternatives replace dairy and honey components.
- Sugar-Free:Monk fruit and date-syrup substitutions respond to MOHAP front-of-pack warning label thresholds.
Gluten-free absorbs the bulk of specialty ingredient investment; organic is gaining share fastest.
Customer Type:
Purchase behavior and decision authority fragment across demographic and lifestyle segments.
- Fitness Enthusiasts:Protein-focused consumption drives premium format adoption with disciplined repurchase patterns. Dubai's gym chains and corporate wellness programs consolidate procurement for this profile.
- Busy Professionals:Subscription delivery and office pantry programs displace individual convenience-store purchasing. HR departments in Dubai's technology sector contract directly with suppliers.
- Health Conscious:Ingredient label scrutiny and clean-label preferences influence brand selection.
- Families:Volume purchasing for household consumption prioritizes shelf stability and child-friendly flavors.
Busy professionals absorb the bulk of subscription infrastructure investment; fitness enthusiasts are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production capacity in the UAE snack bar market remains concentrated around contract manufacturers in Dubai Industrial City and Jebel Ali Free Zone, while consumption pulls disproportionately toward premium retail corridors in Dubai and Abu Dhabi. This production-consumption divide shapes distribution economics and shelf-space competition across the Emirates.
Dubai
Dubai's premium gym chains and corporate wellness programs drive protein-fortified format adoption among fitness enthusiasts and busy professionals. MOHAP's front-of-pack labeling requirements are compressing formulation cycles for brands serving this high-margin segment. Dubai Industrial City hosts the majority of cold-press and high-pressure processing contract manufacturing capacity serving GCC markets.
Abu Dhabi
Health-focused supermarket chains in Abu Dhabi concentrate demand for clean-label and organic-certified snack bars among affluent households. The emirate's municipal food safety authority enforces retail licensing standards that exceed federal MOHAP baselines. Khalifa Industrial Zone is attracting date-processing facilities that supply fiber ingredients to local bar manufacturers.
Sharjah
Sharjah's middle-income families purchase granola bars for school lunchboxes and commuter snacking at price points below Dubai premiums. Subscription logistics platforms serving the emirate have built recurring delivery infrastructure targeting busy professionals in technology and government sectors. Hamriyah Free Zone offers lower-cost warehousing alternatives to Jebel Ali for import-dependent brands.
Ras Al Khaimah
Ras Al Khaimah's underpenetrated retail landscape presents first-mover shelf space opportunities for health-positioned snack bar entrants. The emirate's developing tourism and hospitality sector creates institutional procurement channels for energy bar formats targeting desert expedition operators. Saqr Port offers alternative import clearance routes reducing concentration risk at Jebel Ali.
Northern Emirates
Fujairah and Umm Al Quwain remain substantially underserved relative to supermarket density benchmarks in Dubai and Abu Dhabi. Agricultural processing in Al Ain generates date byproducts suitable for upcycled ingredient stories that differentiate against European imports. Brands establishing ESMA-certified production relationships here can leverage GCC Standardization Organization harmonization for Saudi and Kuwait market entry.
UAE Snack Bar Market Competitive Landscape
The competitive structure tilts toward multinational FMCG conglomerates with established Gulf distribution infrastructure. Mondelez International and PepsiCo leverage pan-Emirates retail networks to sustain shelf presence across supermarkets, convenience stores, and hospitality channels. Three archetypes dominate: global snack giants with diversified bar portfolios, health-focused specialists with clean-label positioning, and regional private-label suppliers serving price-sensitive segments. Competitive moves concentrate on portfolio rationalization to meet MOHAP compliance deadlines and subscription platform partnerships to lock in recurring revenue.
Among the multinational conglomerates, Mondelez International and PepsiCo exemplify scale-driven market presence through their Gulf distribution infrastructure. KIND Snacks occupies the health-specialist archetype with clean-label ingredient positioning that resonates in Dubai's premium retail corridors. These three companies anchor the competitive dynamics shaping shelf-space allocation and formulation investment across UAE retail channels.
| Leading Market Players |
|---|
| Mondelez International |
| PepsiCo |
| Kellogg's Company |
| KIND Snacks |
| Mars |
| General Mills |
| Nestlé |
| Natural Balance Foods |
| The Simply Good Foods Company |
| Others |
Value Network & Pricing Analysis
Food technologist talent concentration in Dubai-based consultancies compresses formulation cost differentials between premium protein bars and mainstream granola formats. Labor scarcity at the specialist tier widens pricing spreads as manufacturers compete for halal-clean-label expertise.
Pricing Analysis
Margin tightening in protein-fortified tiers reflects whey protein input cost volatility transmitted through USD-denominated commodity markets. Three-tier pricing structure across premium, standard, and economy levels separates ESMA-certified organic products from conventional formulations and private-label alternatives. Price differentiation rests on certification grade and vertical integration into date-fiber sourcing. Corporate wellness buyers show lowest price sensitivity; Sharjah families purchasing school lunchbox formats exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Jebel Ali Free Zone anchor hub-and-spoke patterns radiating to Dubai and Abu Dhabi retail corridors. Manufacturing inputs draw from India for binding syrups, Europe for specialty whey isolates, and domestic Al Ain processing for date fiber. Single-port vulnerability at Jebel Ali exposes inventory to customs disruption cascades. Distribution runs through supermarket chains for volume, with direct-to-subscriber fulfillment gaining share among technology sector employers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold-press and high-pressure processing technologies are displacing conventional thermal treatment in premium UAE production lines, compressing legacy equipment valuations.
For Market Incumbents: Lock in MOHAP-accredited laboratory relationships before compliance queue delays strand non-compliant SKUs. Secure backward integration into Al Ain date-processing facilities to capture origin-story premiums against European imports. Cold-press capacity expansion in Dubai Industrial City defends margin position as thermal-treatment brands face shelf relegation. For New Entrants and Emerging Players: The 40-60 percent price gap between premium protein bars and granola formats opens white-space targeting in Sharjah and Ras Al Khaimah health-focused positioning. Fujairah's underpenetrated retail landscape offers first-mover shelf space before national distribution extension. ESMA-GSO certification harmonization unlocks Saudi and Kuwait expansion without redundant testing investment. For Investors and Strategic Acquirers: Re-rating potential sits with contract manufacturers possessing HPP equipment and MOHAP pre-approval given front-of-pack labeling enforcement timelines. Long-term viability favors facilities integrating local agricultural upcycling with GCC export capability. Watch subscription platform partnership announcements as volume inflection signals for recurring-revenue multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Processing Adoption | HPP equipment investment preserves enzyme activity claims commanding Dubai premium retail placement. |
| Backward Integration into Date Fiber | Al Ain sourcing partnerships differentiate against European imports through UAE origin stories. |
| Subscription Platform Partnership | Recurring delivery contracts with technology sector employers lock in predictable volume. |
| ESMA-GSO Certification Investment | Single approval pathway unlocks Saudi, Kuwait, and Bahrain market entry without redundant testing. |
| MOHAP Compliance Pre-Positioning | Accredited laboratory relationships prevent queue delays during nutritional claims verification windows. |
Research Methodology
Independent corroboration across brand managers at multinational FMCG conglomerates, category buyers at Abu Dhabi health-focused supermarket chains, and supply planners at Dubai Industrial City contract manufacturers underwrites the qualitative findings. Secondary validation drew from MOHAP regulatory filings, ESMA certification databases, and Nielsen retail audit data tracking snack bar velocity across Emirates channels. Bottom-up SKU-level analysis triangulates against top-down category spend estimates.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, ingredient certification tier, and customer archetype. CAGRs derive from logistic adoption curves fitted to protein-fortified format penetration rates and subscription platform growth trajectories. Forecast inputs incorporate MOHAP compliance timeline assumptions and GCC Standardization Organization harmonization progress.
Inputs from regulatory filings and retail audit panels were available through the study window; gaps in private-label manufacturer cost structures introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding enforcement timing and commodity price transmission. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Specialty Snacks Market
Snacks
Europe Snacks Market
Snacks
Vegan Snacks Market
Snacks
Super Low Calorie Snacks Market
Snacks
Thailand Snack Bar Market
Snacks
Middle East and Africa Frozen Snacks Market
Snacks
Dairy Snacks Market
Snacks
Crackers Market
Snacks
North America Baked Savory Snacks Market
Snacks
Granola Market
Snacks
North America Cereal Bar Market
Snacks
Protein Bars Market
Snacks
Low Calorie Snacks Market
Snacks
Trail Mix Market
Snacks
Premium Snacks Market
Snacks
Asia Pacific Tortilla Market