
 Granola Market | 2026-2036
Granola Market Size, Share, and Industry Trends Forecast 2026-2036
Granola Market Outlook
The gap between premium artisanal granola and commodity bulk offerings is expanding as ingredient transparency and provenance claims split consumer willingness to pay. General Mills leverages its cereal manufacturing infrastructure to sustain volume leadership in mainstream retail channels. Purely Elizabeth differentiates through organic certification and superfood ingredient positioning that commands shelf space in specialty grocers.
Granola denotes a baked mixture of rolled oats, sweeteners, and binding agents, typically combined with nuts, seeds, or dried fruits and toasted at controlled temperatures to achieve a crunchy, shelf-stable texture intended for breakfast or snacking applications. The product type dimension shows fruit and nut formulations anchoring current revenue while gluten-free variants capture the fastest expansion as celiac awareness and wheat-avoidance diets proliferate. Among distribution channels, online retailers are displacing traditional supermarket dominance as subscription models and direct-to-consumer brands reshape replenishment behavior.
FDA nutrition labeling requirements and EFSA health claims regulations constrain how manufacturers communicate functional benefits, while USDA organic certification creates a parallel compliance pathway that unlocks premium pricing tiers. Stakeholders must monitor evolving sugar taxation proposals and front-of-pack labeling mandates that threaten reformulation cycles and margin structures.
Market Dynamics
The granola market is undergoing a structural bifurcation between clean-label premium positioning and cost-optimized commodity production, with ingredient transparency requirements from FDA and EFSA compliance frameworks forcing simultaneous reformulation across both tiers.
Growth Catalysts
- Protein fortification technology:Microencapsulation and plant-protein blending advances allow manufacturers to hit 10g+ protein claims without texture degradation. Specialty grocers in the United States are prioritizing these SKUs for shelf placement.
- USDA Organic certification pathway:The parallel compliance track unlocks pricing premiums 20-40% above conventional equivalents. EFSA health claims regulations simultaneously constrain competitor messaging, reinforcing certified organic positioning.
- Celiac disease diagnostic expansion:Wheat-avoidance diets proliferate as testing accessibility improves in Germany, Australia, and Canada. Gluten-free oat sourcing networks are scaling to meet this demand pull.
Market Restraints
- Honey and maple syrup input volatility:Climate stress on pollinator populations and maple tapping regions creates 12-18 month price forecasting uncertainty for natural sweetener-dependent formulations.
- Almond supply concentration:California's Central Valley supplies 80% of global almond volume. Drought-driven water allocation disputes threaten binding agent and mix-in cost stability.
- Sugar taxation proposals:Front-of-pack labeling mandates under consideration in the United Kingdom and Mexico threaten margin compression for legacy recipes.
Strategic Opportunities
- Direct-to-consumer subscription models:Replenishment automation bypasses slotting fee structures at traditional supermarkets. Brands capturing household pantry data can optimize flavor rotation algorithms.
- India urban breakfast modernization:Packaged food penetration accelerates in Mumbai, Bangalore, and Delhi NCR as dual-income households abandon traditional morning preparation routines.
- Upcycled ingredient valorization:Spent grain from craft brewing and fruit pulp from juice processing create circular economy narratives that satisfy ESG screening criteria for institutional foodservice procurement.
Industry Challenges
- Clean-label R&D talent scarcity:Formulation chemists capable of replacing modified food starches with functional alternatives command premium compensation in competitive hiring markets.
- Co-manufacturer certification lag:Third-party bakery capacity with simultaneous organic, gluten-free, and allergen-free qualifications remains bottlenecked, extending new product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Granola Market |
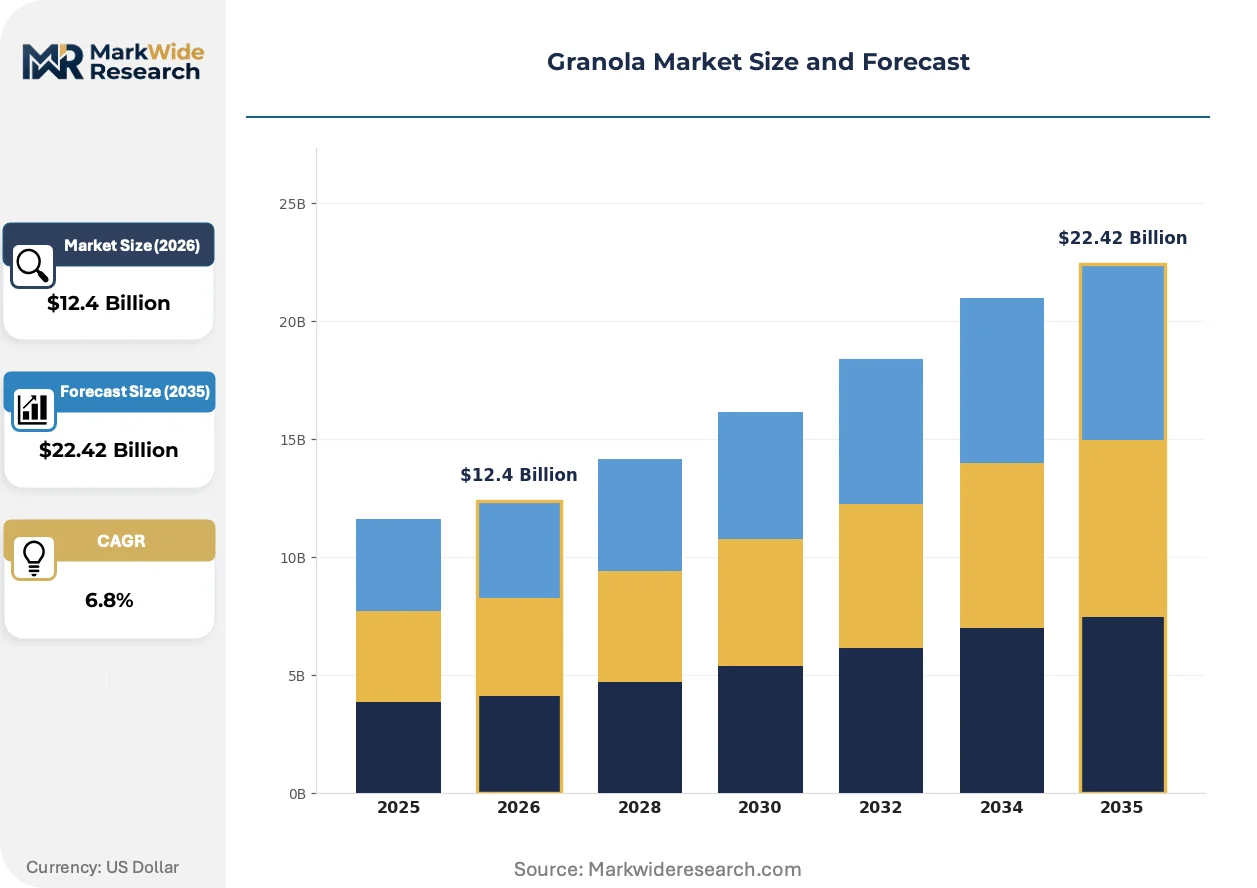
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Chip, Nut & Seed, Fruit & Nut, Gluten-Free End User: Health-Conscious Consumers, Athletes, Busy Professionals, Students Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Convenience Stores Pack Size: Single Serve, Family Size, Bulk, Snack Packs |
| Companies Covered | Nature Valley, Purely Elizabeth, General Mills, Cascadian Farm, Bob's Red Mill, Kellogg Company, Bear Naked, KIND, Quaker Oats Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Granola Market Strategic Shifts
Active reformulation cycles are compressing product development timelines as manufacturers simultaneously pursue sugar reduction targets, protein enhancement, and clean-label ingredient substitution to meet divergent consumer expectations.
Precision fermentation-derived sweeteners are integrating into granola binding systems as manufacturers seek to maintain glycemic response claims without relying on sugar alcohols that trigger digestive sensitivity complaints. Early adopters in the sports nutrition and diabetic-friendly segments are validating sensory acceptance at pilot scale. This technology is integrating upstream into ingredient supplier portfolios, forcing traditional sweetener vendors to defend volume positions through price concessions.
EFSA's evolving guidance on nutrient profiles and health claims is restricting how manufacturers communicate functional benefits on European packaging. The industrial consequence is a shift toward implied wellness positioning through ingredient storytelling rather than explicit physiological claims. Gluten-free and low-sugar variants in France, Germany, and the Netherlands are most affected, with reformulation teams prioritizing visual appetite appeal and texture innovation over label messaging.
Pantry replenishment automation through subscription platforms is displacing impulse-driven supermarket purchases for core granola SKUs. Direct-to-consumer brands capture household consumption data that enables predictive flavor rotation and personalized nutrition bundling. This behavioral shift concentrates most visibly in the United States, where specialty grocer penetration and logistics infrastructure support reliable cold-chain-adjacent delivery for superfood-enhanced formulations.
Granola Market Segmentation
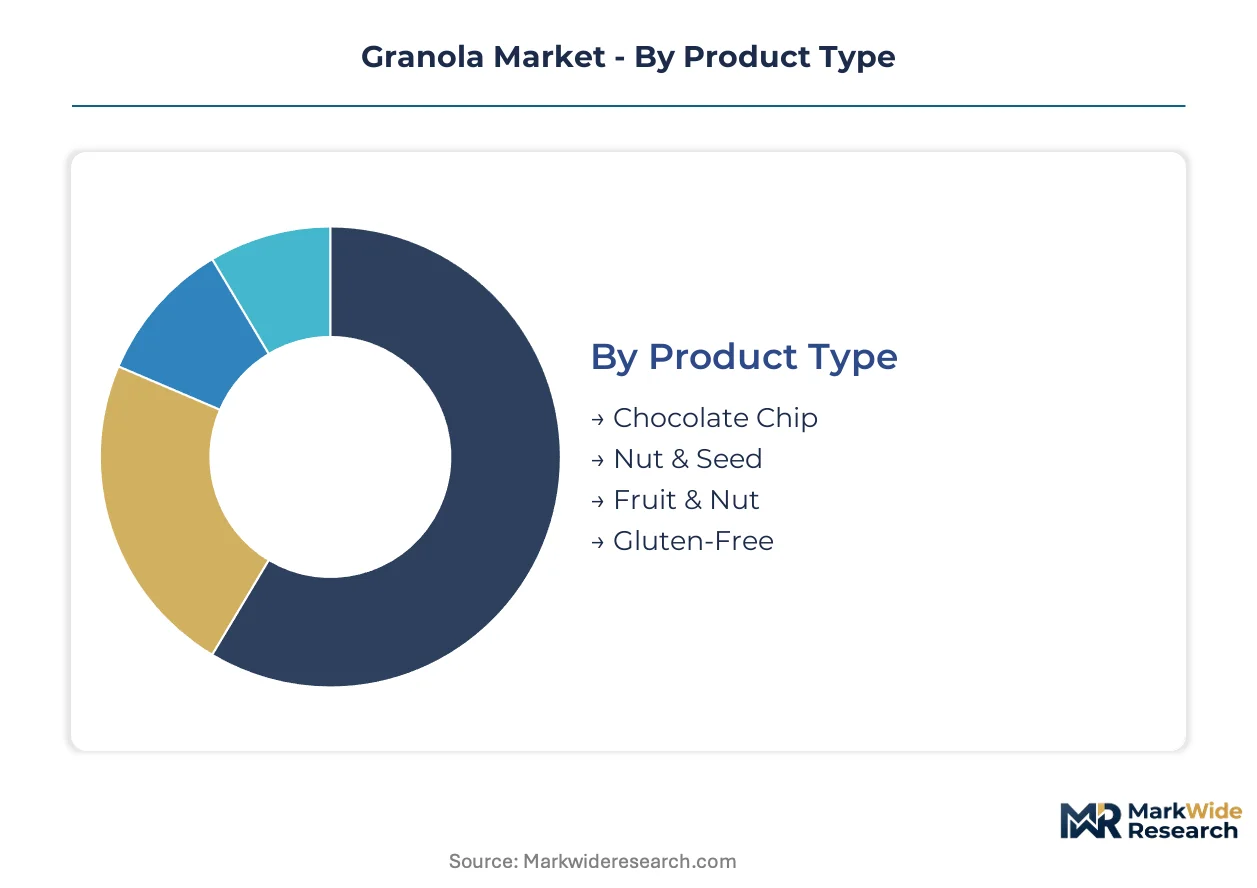
Granola manufacturers configure production lines and ingredient sourcing around four distinct segmentation axes. Each dimension carries different margin implications and requires separate compliance pathways for FDA nutrition labeling and USDA organic certification.
Product Type:
Ingredient concentration in California almond orchards and Canadian maple syrup regions dictates which formulations achieve cost-competitive scale.
- Fruit & Nut:Combines dried cranberries, raisins, or apricots with almonds, walnuts, or pecans bound by honey or maple syrup. Demand concentrates in United States specialty grocers where provenance storytelling commands shelf placement premiums.
- Gluten-Free:Uses certified gluten-free oats sourced from dedicated fields with PCR testing protocols. Celiac awareness expansion in Germany, Australia, and Canada is accelerating demand fastest among wheat-avoidance diet adherents.
- Nut & Seed:Pumpkin seeds, sunflower seeds, and chia replace or supplement tree nuts for cost flexibility and allergen management.
- Chocolate Chip:Cocoa mass and chocolate inclusions target younger demographics and dessert-positioned snacking occasions.
Today's leader: Fruit & Nut. Tomorrow's challenger: Gluten-Free.
End User:
Customer lifetime value varies dramatically across usage occasions, with protein-seeking athletes generating repeat purchase rates double those of occasional breakfast buyers.
- Health-Conscious Consumers:Prioritizes low-sugar, high-fiber, and clean-label ingredient decks. United States direct-to-consumer subscription models capture this cohort through pantry data-driven flavor rotation.
- Athletes:Requires 10g+ protein per serving with optimized carbohydrate-to-protein ratios for recovery. Microencapsulation technology enables these claims without texture degradation.
- Busy Professionals:Values single-serve portability and minimal preparation time for office consumption.
- Students:Price-sensitive segment favoring bulk formats and promotional multipacks for dormitory storage.
Athletes and health-conscious consumers together anchor premium pricing tiers.
Distribution Channel:
Channel selection determines compliance burden intensity, with health food stores requiring the most extensive certification documentation.
- Online Retailers:Subscription automation and direct-to-consumer data capture enable predictive replenishment. This channel is climbing the fastest as specialty brands bypass supermarket slotting fees.
- Supermarkets:Volume concentration in mainstream retail requires trade promotion investment and facing competition from private-label alternatives.
- Health Food Stores:Organic certification and non-GMO verification are table stakes for shelf placement.
- Convenience Stores:Single-serve and snack pack formats dominate with impulse-driven purchase behavior.
Supermarkets still move the most tonnage. Online retailers are gaining share fastest.
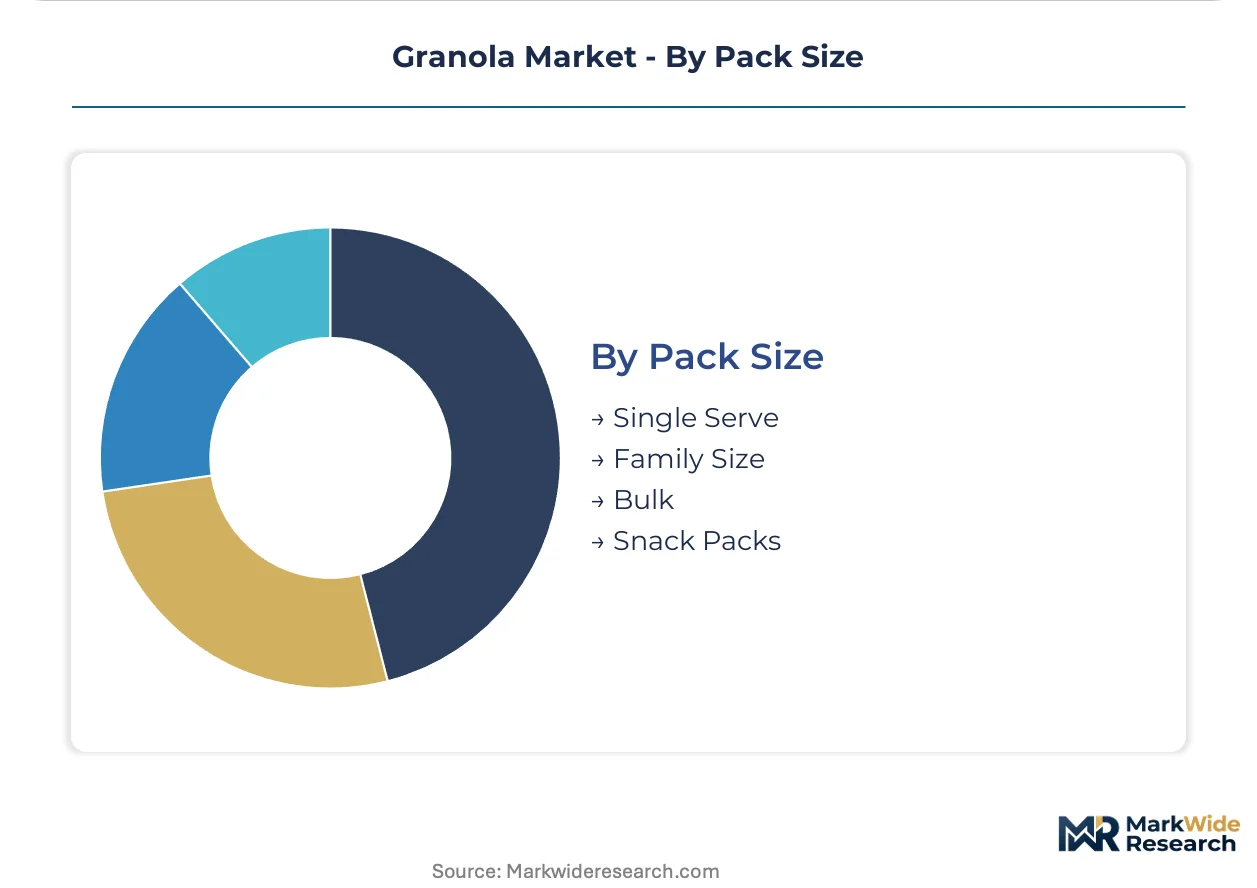
Pack Size:
Packaging line configuration and warehouse cube efficiency create divergent margin structures across size tiers.
- Family Size:24-32 ounce bags target household pantry stocking with lowest per-ounce pricing.
- Single Serve:1.5-2 ounce portions for on-the-go consumption in travel and foodservice channels.
- Snack Packs:4-6 ounce multi-packs balance portability with value perception.
- Bulk:Foodservice and institutional formats with minimal packaging for cafeteria and hospitality procurement.
Family Size dominates household penetration. Single Serve is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food scientists and supply chain specialists cluster in regions with established oat processing infrastructure and organic certification expertise. Talent concentration in the Upper Midwest and Pacific Northwest anchors North American formulation leadership, while European regulatory affairs professionals concentrate around Brussels and Frankfurt.
United States
Protein-seeking athletes and clean-label adherents in Austin, Boulder, and Portland drive demand for microencapsulated formulations. FDA nutrition labeling requirements and USDA organic certification pathways create dual compliance tracks that advantage established players. Minneapolis-St. Paul hosts General Mills' cereal manufacturing infrastructure, sustaining volume leadership through co-located oat milling and packaging operations.
Germany
Celiac awareness expansion and wheat-avoidance diet adherence accelerate gluten-free oat sourcing from dedicated Bavarian and Lower Saxon fields. EFSA health claims regulations constrain explicit functional messaging, pushing reformulation teams toward implied wellness positioning through ingredient storytelling. Hamburg and Berlin specialty grocers prioritize SKUs with PCR-tested gluten-free certification and superfood inclusions.
Australia
Diagnostic accessibility improvements for celiac disease expand the addressable market for certified gluten-free formulations in Sydney and Melbourne. Food Standards Australia New Zealand (FSANZ) labeling requirements govern nutritional claims and allergen declarations. Queensland and Victoria oat-growing regions are developing dedicated gluten-free supply chains with identity preservation protocols from field to mill.
Canada
Health Canada front-of-pack labeling proposals and sugar taxation discussions threaten margin compression for legacy recipes in Toronto and Vancouver markets. Prairie provinces anchor oat production volume, while Montreal and Calgary distribution hubs service direct-to-consumer subscription brands bypassing supermarket slotting fees. Organic certification penetration exceeds North American averages in British Columbia and Ontario.
India
Dual-income households in Mumbai, Bangalore, and Delhi NCR abandon traditional morning preparation routines, accelerating packaged breakfast penetration. FSSAI labeling regulations and organic certification frameworks remain less stringent than FDA or EFSA equivalents, creating regulatory arbitrage opportunities for imported premium brands. Maharashtra and Karnataka urban clusters show strongest uptake of protein-fortified and low-sugar Western formulations.
Granola Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the granola category. Consolidated cereal conglomerates leverage existing manufacturing infrastructure against nimble direct-to-consumer entrants. Three archetypes dominate: diversified packaged food giants with co-located oat milling capacity, organic-certified specialty brands commanding specialty grocer shelf premiums, and subscription-native digital-first players capturing pantry data. Competitive moves concentrate on co-manufacturer certification acquisition and direct-to-consumer channel expansion.
Among diversified packaged food conglomerates, General Mills and Kellogg Company exemplify scale-driven archetypes with integrated cereal manufacturing footprints. Within the organic-certified specialty tier, Purely Elizabeth occupies a position defined by superfood ingredient positioning and non-GMO verification. Nature Valley and Bear Naked sit within the mass-market natural segment, bridging conventional supermarket distribution with clean-label ingredient decks.
| Leading Market Players |
|---|
| Nature Valley |
| Purely Elizabeth |
| General Mills |
| Cascadian Farm |
| Bob's Red Mill |
| Kellogg Company |
| Bear Naked |
| KIND |
| Quaker Oats Company |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap granola specialists in California's Central Valley and the Pacific Northwest anchor oat milling and almond processing capacity, their conservative balance sheets enabling patient pricing discipline during honey and maple syrup volatility that squeezes leveraged commodity traders.
Pricing Analysis
Subscription bundling separates pantry-automation subscribers from transactional supermarket buyers, with three-tier pricing structure across premium, standard, and economy levels. USDA organic certification and gluten-free PCR testing drive 20-40% premiums over conventional equivalents. Pricing pressure stems from front-of-pack labeling mandates in the United Kingdom and Mexico threatening legacy recipe margins. Students and bulk-format buyers exhibit highest price sensitivity; athletes seeking 10g+ protein claims show lowest.
Supply Chain Analysis
Almond supply rests on California's Central Valley orchards facing drought-driven water allocation disputes, while Canadian maple syrup regions and Argentine buckwheat fields provide alternative binding agents. Honey harvests draw from pollinator-dependent apiaries in North Dakota and Florida. Single-source vulnerability concentrates in California's 80% global almond share. Distribution runs through direct-to-consumer subscription platforms displacing traditional supermarket slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The granola market reads as a late-cycle quality story, with health-conscious consumers in Austin, Boulder, and Portland accelerating demand for microencapsulated protein fortification and superfood inclusions that command shelf placement premiums.
For Market Incumbents: Cement co-manufacturer certification acquisition in organic, gluten-free, and allergen-free qualifications to bottleneck competitor launch timelines. Deepen backward integration into certified gluten-free oat milling in Minnesota and Saskatchewan to defend against drought-driven almond cost spikes. Prioritize direct-to-consumer channel control to capture household pantry data for predictive flavor rotation.
For New Entrants and Emerging Players: Enter via India's Mumbai, Bangalore, and Delhi NCR urban clusters where dual-income households abandon traditional morning preparation routines and FSSAI regulations create regulatory arbitrage for imported premium brands. Target protein-fortified and low-sugar Western formulations with localized taste adaptation. Pursue foodservice partnerships with institutional procurement seeking ESG-compliant upcycled ingredient narratives.
For Investors and Strategic Acquirers: Valuations sit cheapest among co-manufacturers with simultaneous organic, gluten-free, and allergen-free qualifications bottlenecking new product launches. Five-to-ten-year viability hinges on subscription-native digital-first players capturing pantry replenishment automation. Watch EFSA health claims guidance evolution as inflection indicator for implied wellness positioning versus explicit functional messaging.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees while capturing household consumption data in Austin and Portland. |
| USDA Organic Certification Investment | Unlocks 20-40% pricing premiums at specialty grocers requiring non-GMO verification. |
| Gluten-Free Supply Chain Integration | Establishes dedicated oat sourcing with PCR testing protocols for celiac-aware consumers in Germany. |
| Precision Fermentation Sweetener Adoption | Maintains glycemic response claims without sugar alcohols triggering digestive complaints. |
| Upcycled Ingredient Sourcing Partnership | Satisfies ESG screening criteria for institutional foodservice procurement from craft brewing spent grain. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at specialty grocers, supply planners, and co-manufacturer operations heads with secondary validation from Nielsen retail audit data, USDA organic certification records, FDA nutrition labeling filings, and customs import records. Bottom-up SKU-level volume aggregation and top-down category spend analysis provided triangulation checks.
Comparable-period anchoring linked historical consumption patterns to forward projection assumptions across the modeling period. Segmentation dimensions included product type, end user archetype, distribution channel, and pack size tier. CAGRs were derived from trend extrapolation adjusted for protein fortification technology diffusion and celiac diagnostic expansion rates. Forecast inputs incorporated honey and maple syrup price volatility bands and co-manufacturer capacity utilization assumptions.
Inputs from Nielsen retail audit and USDA certification databases were available through the study window; gaps in direct-to-consumer subscription transaction data introduce uncertainty bands around channel share estimates. Forecasts reflect documented assumptions about EFSA health claims evolution and sugar taxation proposal timelines. Regulatory guidance shifts and pollinator population stress warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
North America Snack Food Market
Snacks
Germany Snack Bar Market
Snacks
Austria Snack Bar Market
Snacks
Fruit Jerky Market
Snacks
Crispy Fruit Chips Market
Snacks
Trail Mix Market
Snacks
Organic Chips Market
Snacks
Fat Free Meals and Snacks Market
Snacks
Poland Snack Bar Market
Snacks
Spain Snack Bar Market
Snacks
Better for You Snacks Market
Snacks
India Energy Bar Market
Snacks
Snack Products Market
Snacks
North America Frozen Snacks Market
Snacks
Veggie Chips Market
Snacks
United States Popcorn Market