
 No-Fat Peanut Butter Market | 2026-2036
No-Fat Peanut Butter Market Size, Share, and Industry Trends Forecast 2026-2036
No-Fat Peanut Butter Market Foresight
Subscription-based replenishment models for pantry staples is realigning how no-fat peanut butter reaches repeat buyers. The J.M. Smucker Company leverages its direct-to-consumer infrastructure to capture recurring revenue streams. Kraft Heinz Company anchors shelf presence through dominant retail partnerships with mass-market grocers. Hormel Foods Corporation differentiates via specialized nutrition positioning within its broader protein portfolio.
No-fat peanut butter is a spreadable food product manufactured through mechanical defatting or hydraulic pressing of roasted peanuts to reduce lipid content below standard peanut butter thresholds, typically yielding a protein-dense paste with altered viscosity and mouthfeel properties. The product serves commercial and retail buyers seeking reduced-calorie protein sources for dietary management and athletic nutrition programs. Creamy textures lead volume sales due to broader acceptance in baking and smoothie applications, while flavored variants capture faster growth through novelty positioning in specialty retail. Health Food Stores channel distribution commands premium positioning, whereas supermarket placements sustain baseline volume through family-oriented Customer Type segments.
The FDA governs peanut butter identity standards under 21 CFR 164.150, which defines composition thresholds and labeling requirements that directly constrain product formulation and marketing claims. USDA oversees agricultural sourcing protocols for domestic peanut supply chains, influencing input cost structures and origin certification requirements. State-level health departments supplement federal oversight through retail inspection regimes that affect shelf placement and inventory turnover. Stakeholders must monitor evolving clean-label enforcement patterns and plant-based protein classification debates that could recategorize competitive positioning in nutrition aisles.
Market Dynamics
FDA's updated Nutrition Facts labeling requirements for added sugars are compressing formulation timelines and forcing manufacturers toward cleaner label architectures across the no-fat peanut butter category. This regulatory pressure intersects with fitness-driven protein demand to reshape competitive positioning.
Growth Catalysts
- Protein-focused meal planning:Fitness enthusiasts and athletes drive repeat purchase velocity through structured dietary programs that prioritize protein density per serving.
- 21 CFR 164.150:FDA identity standards create definitional clarity that reduces regulatory friction for compliant manufacturers expanding distribution.
- Mechanical defatting:Hydraulic pressing technology improvements yield superior viscosity control, enabling broader baking and smoothie applications.
Market Restraints
- Domestic peanut supply concentration:USDA-supervised agricultural sourcing ties input costs to domestic crop yields and weather volatility.
- Altered mouthfeel properties:Lipid reduction creates sensory limitations that constrain acceptance among traditional peanut butter consumers.
- Standard peanut butter substitution:Full-fat alternatives retain price advantage and broader palate familiarity in family-oriented segments.
Strategic Opportunities
- Subscription-based replenishment:Direct-to-consumer infrastructure enables recurring revenue capture from pantry staple buyers.
- Flavored variant expansion:Novelty positioning in specialty retail channels accelerates growth beyond baseline creamy textures.
- Health Food Stores channel:Premium positioning in dedicated wellness retail commands margin expansion unavailable in mass-market grocery.
Industry Challenges
- Clean-label enforcement patterns:Evolving FDA interpretation of marketing claims requires continuous compliance monitoring and label revision cycles.
- Plant-based protein classification debates:Regulatory uncertainty around peanut butter categorization threatens shelf placement in nutrition aisles.
- State-level retail inspection regimes:Fragmented health department oversight creates inventory turnover variability across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | No-Fat Peanut Butter Market |
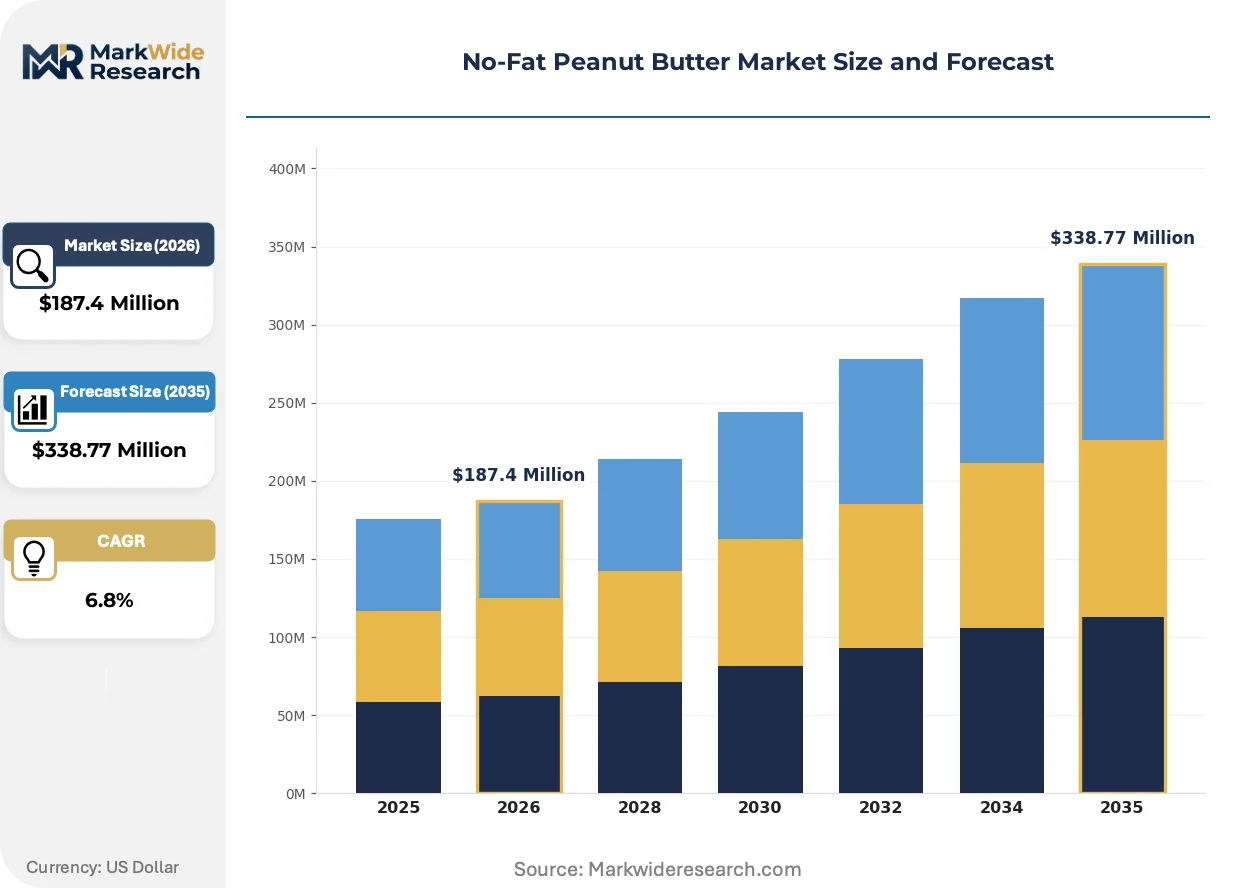
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creamy, Crunchy, Natural, Flavored Packaging Type: Tubs, Jars, Sachets, Pouches Distribution Channel: Online, Supermarkets, Convenience Stores, Health Food Stores Customer Type: Health Conscious Consumers, Athletes, Families, Fitness Enthusiasts |
| Companies Covered | The J.M. Smucker Company, Hormel Foods Corporation, Kraft Heinz Company, Conagra Brands, Inc., Once Again Nut Butter, PBfit, Justin's, Crazy Richard's, MaraNatha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
No-Fat Peanut Butter Market Shifts & Advancements
Mechanical defatting processes are converging with digital quality control systems to reshape how no-fat peanut butter achieves batch consistency. Three developments are compressing competitive timelines.
Enzymatic lipid modification is converging with precision roasting control to enable protein retention above traditional hydraulic pressing yields. Mid-size manufacturers in the athletic nutrition segment adopt these hybrid systems fastest. The technology is converging with automated viscosity monitoring to reduce reformulation cycles from months to weeks.
EU Green Deal nutritional profiling criteria are pressuring exporters to reformulate sodium and sugar content for continental shelf access. Manufacturers targeting European health food channels face reformulation costs or market exclusion. German and Dutch buyers now demand third-party certification beyond baseline FDA compliance.
Pantry replenishment automation is displacing traditional grocery restocking for core buyers. Health-conscious households in metropolitan US markets subscribe to direct delivery, bypassing conventional retail inventory management. This channel compression concentrates fulfillment capability among operators with captive logistics infrastructure.
No-Fat Peanut Butter Market Segmentation
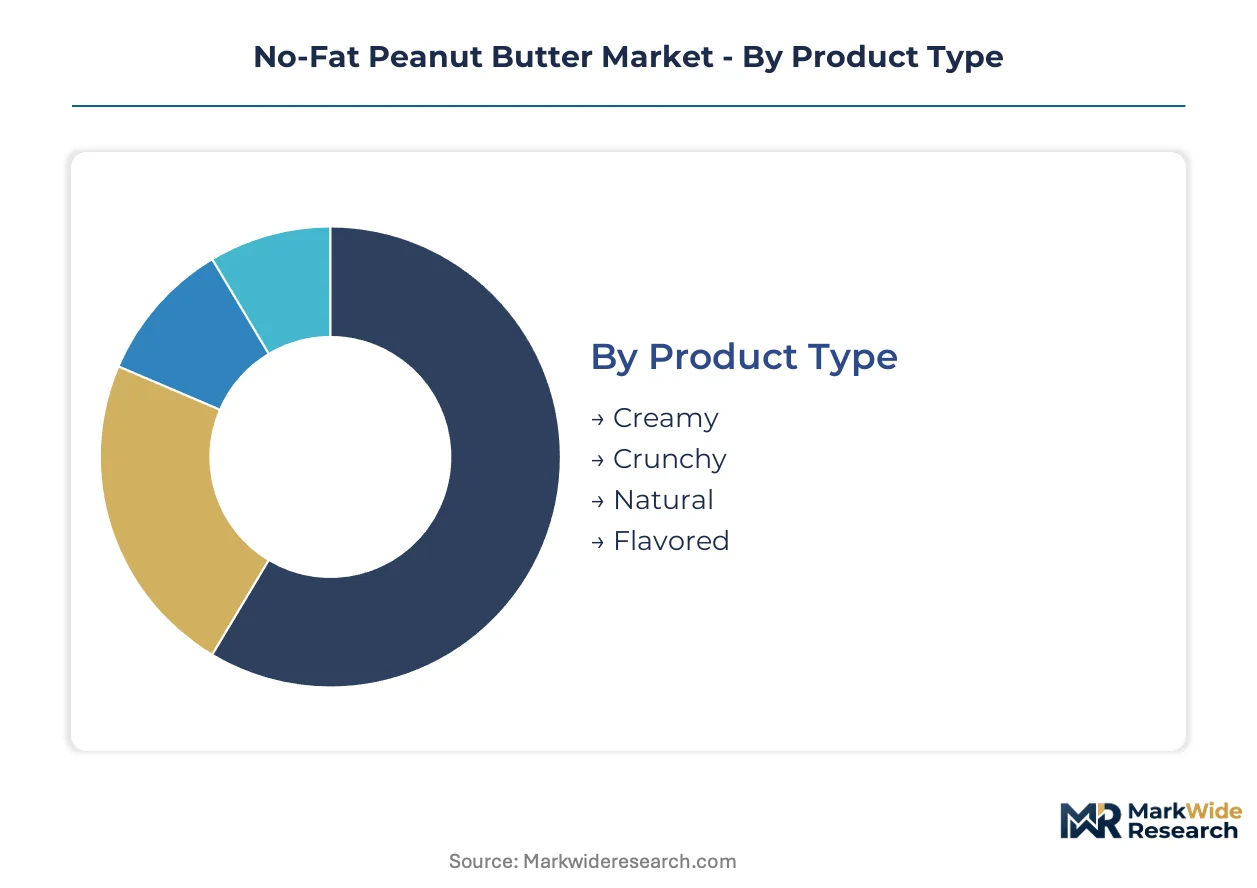
Segmentation in no-fat peanut butter reveals how formulation choices, packaging economics, and channel access determine which buyers manufacturers can profitably serve. Each dimension carries distinct margin profiles and regulatory exposure that shape competitive strategy.
Product Type:
Supply concentration in mechanical defatting capacity favors producers with scale to optimize protein retention across texture variants.
- Creamy:Achieved through extended grinding of defatted peanut paste with controlled particle size below 50 microns for uniform spreadability. Demand concentrates in baking and smoothie applications across United States metropolitan markets where protein fortification drives household penetration. The FDA's 21 CFR 164.150 identity standard provides definitional clarity that reduces formulation risk for compliant manufacturers.
- Flavored:Incorporates cocoa, honey, or cinnamon additions post-defatting to mask altered mouthfeel properties. Specialty retail channels in health-conscious urban clusters drive fastest expansion as novelty positioning commands premium pricing unavailable in baseline formulations.
- Crunchy:Blends partially defatted paste with intact peanut fragments for textural contrast. Athletic nutrition programs favor this variant for satiety signaling in structured meal plans.
- Natural:Excludes stabilizers and hydrogenated oils, shortening shelf life but satisfying clean-label requirements. Health Food Stores channel placement sustains margin despite higher spoilage rates.
Today's leader: Creamy. Tomorrow's challenger: Flavored.
Packaging Type:
Cost tier differentiation separates institutional buyers from household replenishment patterns through unit economics and shelf-life engineering.
- Jars:Glass or PET containers with tamper-evident closures dominate family-oriented supermarket placements. United States mass-market grocers anchor volume through multi-unit promotional pricing.
- Tubs:Wide-mouth polypropylene containers optimize scoopability for commercial kitchen and foodservice applications. Fitness facilities and athletic training centers drive institutional demand.
- Sachets:Single-serve foil laminates enable portion-controlled distribution in travel and workplace settings. Convenience Stores channel placement captures impulse purchase behavior.
- Pouches:Flexible stand-up bags with resealable spouts reduce shipping cube for direct-to-consumer fulfillment. Subscription-based replenishment models favor this format for last-mile efficiency.
Volume concentrates in jars. Margin expansion sits with pouches.
Distribution Channel:
Customer type alignment determines which channels warrant dedicated inventory investment versus third-party placement.
- Supermarkets:Dominant shelf space allocation for family-oriented segments through end-cap promotions and loyalty program integration. Kraft Heinz Company and J.M. Smucker Company compete for linear footage in this channel.
- Health Food Stores:Curated placement with nutritionist consultation drives premium positioning. Clean-label enforcement patterns from state health departments create compliance variability across jurisdictions.
- Online:Direct-to-consumer infrastructure enables subscription-based replenishment with personalized flavor profiling. Pantry automation displaces traditional grocery restocking in metropolitan markets.
- Convenience Stores:Limited SKU count favors portable formats and impulse pricing. Sachet and small-jar configurations dominate this channel.
Supermarkets sustain baseline volume. Online captures recurring revenue.
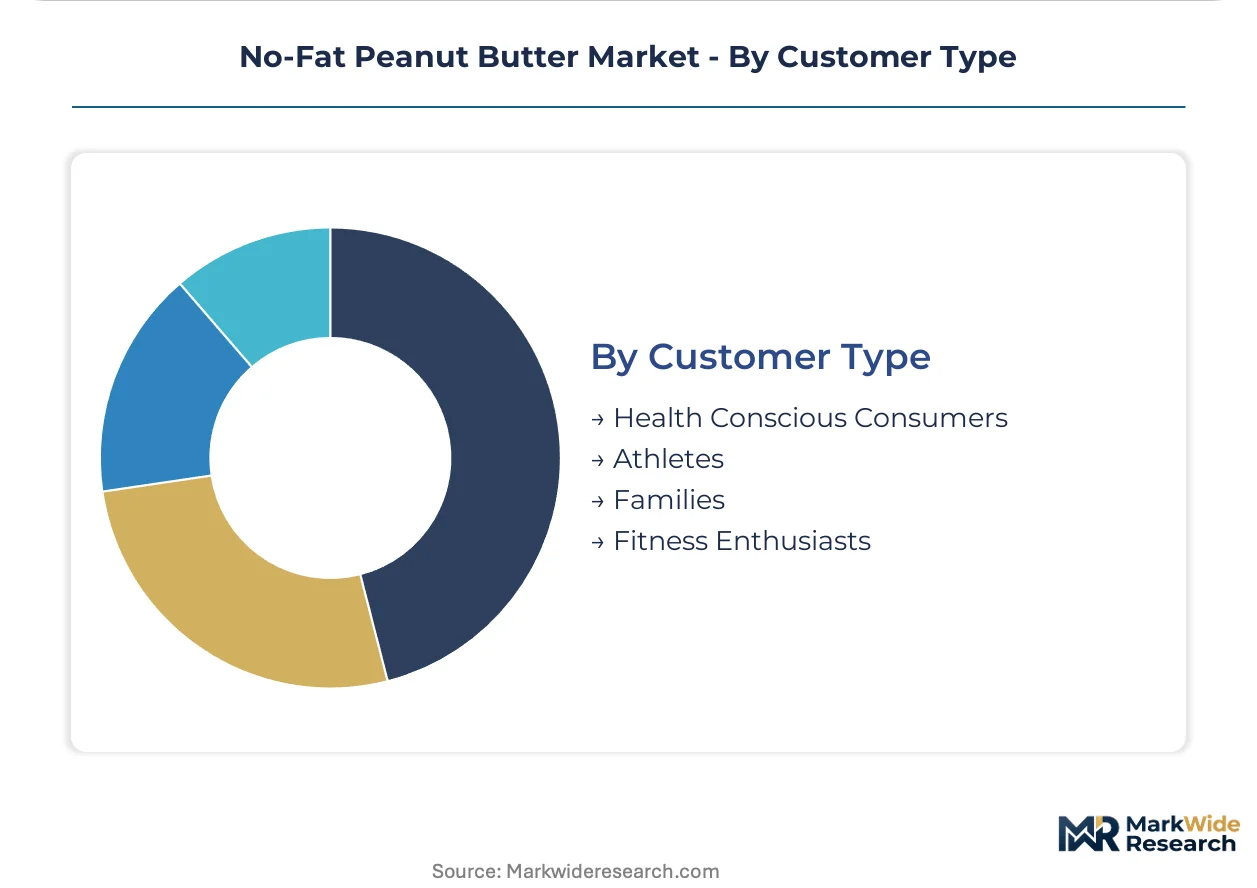
Customer Type:
Application intensity separates programmatic buyers with structured consumption from discretionary purchasers with sporadic demand.
- Fitness Enthusiasts:Systematic protein-focused meal planning drives repeat purchase velocity through direct-to-consumer subscription. Hormel Foods Corporation targets this segment via specialized nutrition positioning.
- Athletes:Competitive and recreational performers with quantified macronutrient targets. Sports nutrition programs at collegiate and professional levels institutionalize demand.
- Health Conscious Consumers:Wellness-oriented shoppers prioritizing reduced-calorie density over traditional taste profiles. FDA's updated Nutrition Facts labeling for added sugars influences purchase decisions.
- Families:Price-sensitive household purchasers balancing nutritional claims with palate acceptance across age groups. Standard peanut butter substitution risk concentrates here.
Fitness enthusiasts anchor premium pricing. Families constrain margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for no-fat peanut butter outpaces Canadian adoption by roughly three to one, reflecting deeper penetration of protein-focused dietary culture. Germany and the Netherlands anchor European uptake through health food retail networks. Japan shows emerging interest among athletic nutrition programs.
United States
Fitness enthusiasts and health-conscious grocery shoppers drive volume through subscription replenishment and supermarket loyalty programs. FDA's 21 CFR 164.150 identity standards provide regulatory clarity that reduces formulation friction for domestic manufacturers. Metropolitan clusters in California and Texas concentrate demand through direct-to-consumer fulfillment infrastructure.
Germany
EU Green Deal nutritional profiling criteria pressure exporters to reformulate sodium and sugar content for continental shelf access. EFSA oversight of health claims creates compliance thresholds that favor established suppliers with dedicated regulatory affairs capacity. Berlin and Hamburg anchor health food retail expansion where clean-label positioning commands premium pricing.
Netherlands
German and Dutch buyers demand third-party certification beyond baseline FDA compliance for imported no-fat peanut butter. REACH chemical safety protocols influence packaging material selection for continental distribution. Rotterdam logistics clusters facilitate re-export throughout northwestern European health food channels.
Canada
Health Canada and PMRA oversight of food safety and agricultural inputs shapes domestic peanut supply chain protocols. Provincial health departments in Ontario and Quebec supplement federal inspection regimes affecting retail placement. Toronto and Vancouver metropolitan markets concentrate demand through specialty grocers and online replenishment models.
Japan
Collegiate and professional sports nutrition programs institutionalize demand for protein-dense spreads among athletic populations. METI standards for processed foods influence labeling and import documentation requirements. Tokyo and Osaka urban clusters drive trial adoption through curated health food retail and fitness facility distribution.
No-Fat Peanut Butter Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pantry staple recognition dominating mass retail while private label gains traction in subscription channels. The vendor base concentrates among three to five national brands with legacy peanut butter heritage, supplemented by emerging athletic nutrition specialists. Strategic archetypes include diversified food conglomerates with defatting technology access, pure-play nut butter specialists with clean-label credibility, and sports nutrition formulators with protein positioning expertise. Capacity expansion and direct-to-consumer infrastructure buildout represent the dominant competitive moves as manufacturers bypass traditional grocery intermediaries.
Among diversified food conglomerates, The J.M. Smucker Company and Kraft Heinz Company occupy positions anchored by legacy peanut butter portfolios and dominant retail shelf presence. Hormel Foods Corporation exemplifies the protein-specialist archetype through nutrition-focused positioning within broader meat and nut butter holdings. These three represent the scale-driven tier where mechanical defatting technology access and supermarket linear footage competition determine baseline market presence.
| Leading Market Players |
|---|
| The J.M. Smucker Company |
| Hormel Foods Corporation |
| Kraft Heinz Company |
| Conagra Brands, Inc. |
| Once Again Nut Butter |
| PBfit |
| Justin's |
| Crazy Richard's |
| MaraNatha |
| Others |
Supply & Pricing Matrix
Fitness enthusiasts and athletes anchor premium pricing tiers through subscription-based replenishment models that compress price elasticity for compliant manufacturers. Their programmatic demand patterns enable direct-to-consumer operators to bypass traditional grocery margin stacking while mass-market family segments retain acute price sensitivity.
Pricing Analysis
Capacity additions in Georgia and Texas defatting facilities are reshaping price floors for mid-tier creamy variants. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and channel access. Cost compression in economy tiers intensifies because standard peanut butter substitutes retain shelf-space advantages. Families exhibit highest price sensitivity, while athletic nutrition programs demonstrate lowest elasticity due to protein-density requirements.
Supply Chain Analysis
Peanut supply rests on domestic agricultural output concentrated in Georgia, Alabama, and Texas growing regions. Mechanical defatting equipment and hydraulic pressing systems draw from specialized food processing machinery producers in Germany and Italy. Single-source vulnerability in domestic peanut crop yields creates exposure to weather volatility and USDA-supervised acreage shifts. Distribution runs through supermarket retail partnerships for baseline volume, with direct-to-consumer fulfillment capturing premium subscription tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
No-fat peanut butter functions as a stable compounder anchored by persistent protein-focused dietary trends among fitness populations. FDA's 21 CFR 164.150 identity standards provide regulatory clarity that sustains formulation investment confidence.
For Market Incumbents: Cement shelf-space dominance through exclusive retail partnership renewals with mass-market grocers. Deepen backward integration into mechanical defatting capacity to capture margin from equipment suppliers. Counter private-label subscription entrants by deploying personalized flavor profiling through captive direct-to-consumer infrastructure.
For New Entrants and Emerging Players: Enter via flavored variant white space in specialty health food channels where novelty positioning commands premium pricing unavailable to legacy creamy formulations. Target collegiate athletic nutrition programs with institutional tub configurations. Pursue third-party certification beyond FDA compliance to unlock German and Dutch export channels.
For Investors and Strategic Acquirers: Diversified food conglomerates with defatting technology access are the most active acquirer in this space. Five-to-ten-year viability hinges on subscription infrastructure scalability and clean-label enforcement adaptation. Monitor plant-based protein classification debates as inflection indicator for shelf-placement risk in nutrition aisles.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Launch | Subscription replenishment captures recurring revenue from fitness enthusiasts bypassing retail intermediaries. |
| Backward Integration | In-house mechanical defatting capacity reduces dependency on third-party processing and stabilizes input costs. |
| Flavored Variant Expansion | Novelty positioning in specialty retail accelerates growth beyond baseline creamy texture saturation. |
| Third-Party Certification | EFSA-compliant health claims unlock German and Dutch health food channels demanding standards beyond FDA. |
| Sustainability Repositioning | EU Green Deal nutritional profiling compliance enables continental shelf access for reformulated low-sodium variants. |
Research Methodology
Direct dialogue with brand managers at peanut butter manufacturers, category buyers at mass-market retailers, supply planners at foodservice distributors, and regulatory affairs specialists at FDA consulting firms grounded qualitative findings. Secondary validation drew from FDA 21 CFR filings, USDA crop production reports, Nielsen retail audit data, and SEC 10-K disclosures from diversified food conglomerates. Bottom-up segment sizing triangulated against top-down category value estimates.
Market value and volume trajectories across the analysis window reflect econometric modeling of protein demand elasticity, regulatory compliance cost pass-through, and channel shift dynamics. Segmentation dimensions included product texture, packaging format, distribution channel, and customer application intensity. CAGRs derived from regression analysis of historical protein-focused food category growth rates calibrated against mechanical defatting capacity expansion schedules and subscription adoption curves.
The model holds under stable FDA identity standard interpretation and consistent fitness-driven protein demand; deviation in plant-based protein reclassification or domestic peanut supply disruption would shift trajectory. Forecasts embed assumptions regarding clean-label enforcement patterns and direct-to-consumer logistics scaling. A small set of named triggers—regulatory recategorization debates, defatting technology cost curves, and European import certification evolution—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Peanut Butter Keto Snacks Market
Snacks
Australia Snack Bar Market
Snacks
Organic Snack Food Market
Snacks
Sweet Potato Chips Market
Snacks
Low Fat Crackers Market
Snacks
Low Calorie Cookies Market
Snacks
Europe Extruded Snack Food Market
Snacks
Kids Snacks Market
Snacks
Middle East and Africa Snack Pellets Market
Snacks
Super Low Calorie Snacks Market
Snacks
Spicy Sticks (Chinese Snack) Market
Snacks
Snack Pellets Market
Snacks
Spain Energy Bar Market
Snacks
South Africa Snack Bar Market
Snacks
Global Snack Food Market
Snacks
Kale Chips Market