
 North America Extruded Snack Food Market | 2026-2036
North America Extruded Snack Food Market Size, Share, and Industry Trends Forecast 2026-2036
North America Extruded Snack Food Market Intelligence
Convenience store and club-channel buyer consolidation is expanding as regional retail banners merge procurement functions and demand volume commitments from extruded snack suppliers. PepsiCo leverages its direct-store-delivery infrastructure to sustain shelf-space dominance in these consolidated accounts. General Mills anchors its position through R&D intensity in whole-grain extrusion formulations. Mondelez International competes via specialized savory snack portfolios that navigate shifting retailer category management priorities.
Extruded snack food refers to products manufactured by forcing cereal or vegetable-based dough through a die under heat and pressure, typically achieving bulk densities of 50–150 g/L and moisture contents below 4% for shelf-stable crispness. The process creates porous cellular structures that deliver uniform texture and extended shelf life for commercial retail distribution. Corn snacks occupy the largest volume share within product type segmentation due to established supply chains and favorable input costs, while mixed grain snacks lead growth as brands respond to clean-label and fiber-content positioning. Pouch packaging dominates unit economics through lighter shipping weights and material efficiency, though tub formats command margin premiums in club and convenience channels where resealability drives repeat purchase.
The FDA enforces Nutrition Facts labeling and sodium reduction guidance that shapes reformulation roadmaps across U.S. manufacturing facilities, while Health Canada implements parallel front-of-package nutrition symbol requirements affecting cross-border product standardization. USDA organic certification and non-GMO verification frameworks create tiered market access thresholds that influence ingredient sourcing and extrusion plant capital allocation. Stakeholders must monitor evolving sodium and added-sugar thresholds across both federal regimes to determine whether unified North American formulations or market-specific product lines deliver superior returns.
Market Dynamics
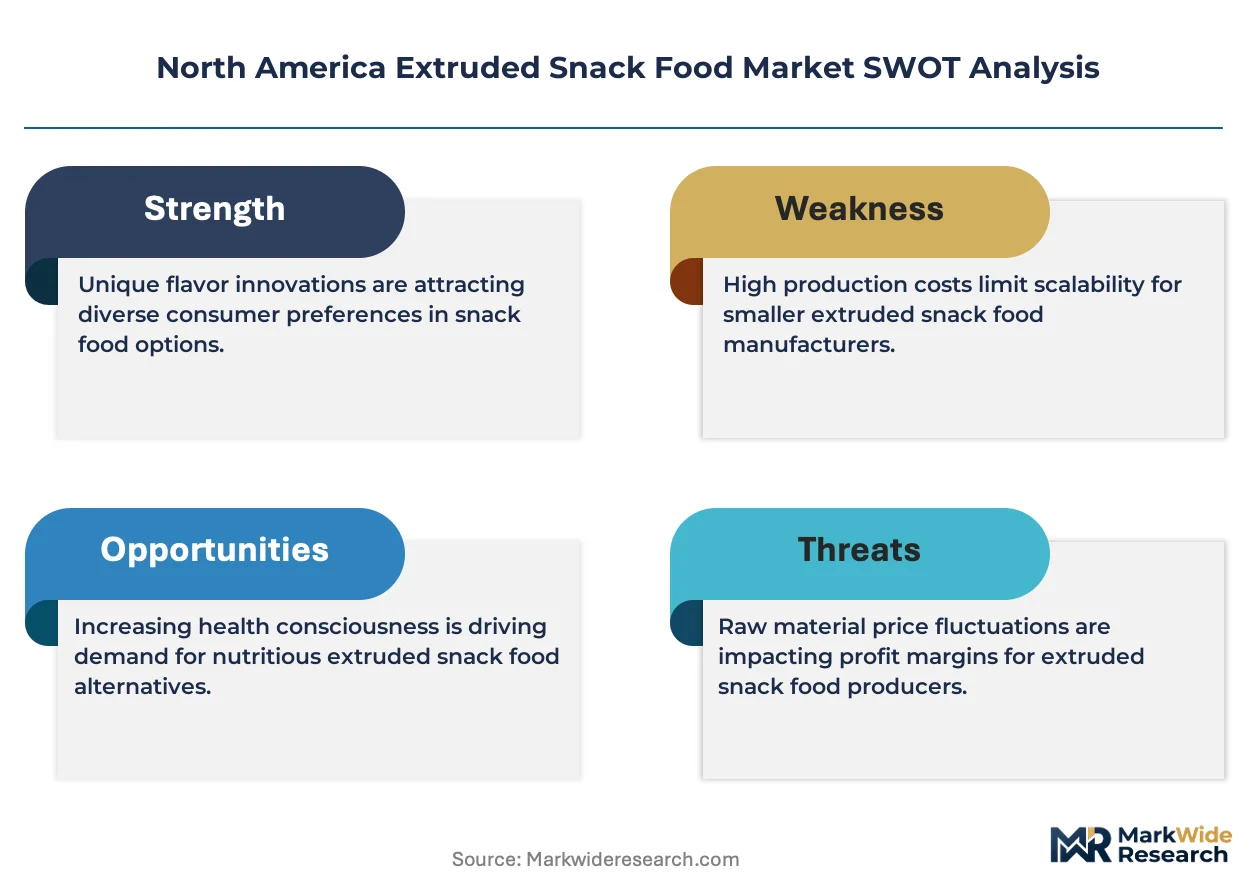
Direct-store-delivery consolidation among convenience store chains is compressing supplier margins while demanding reformulation commitments aligned with FDA sodium reduction timelines.
Growth Catalysts
- Front-of-Package Labeling Mandates:Health Canada's nutrition symbol requirements accelerate clean-label innovation cycles across Canadian manufacturing facilities. Reformulation investments unlock shelf access in cross-border retail banners.
- Co-Manufacturing Cluster Density:Southeastern United States distribution hubs concentrate extrusion capacity within 500-mile radius of major population centers. Proximity to corn belt supply chains reduces inbound freight costs for regional brands.
- Whole-Grain Extrusion Advances:Modified screw configurations and lower-shear processing preserve fiber integrity in mixed-grain formulations. Equipment upgrades enable texture parity with traditional corn-based products.
Market Restraints
- Corn Price Volatility:Drought cycles in Midwest growing regions create input cost spikes that squeeze margin structures for commodity-positioned products. Hedging strategies require working capital reserves many mid-tier producers lack.
- Single-Source Equipment Dependency:Extruder screw and barrel fabrication concentrates among German and Italian specialized suppliers. Lead times extending beyond 18 months constrain capacity expansion timelines.
- FDA Sodium Reduction Guidance:Draft targets for savory snacks force flavor system rebuilds that risk consumer rejection. Reformulation costs compound without guaranteed retail price recovery mechanisms.
Strategic Opportunities
- Club-Channel Resealable Formats:Tub packaging with moisture-lock closures commands repeat purchase premiums in Costco and Sam's Club locations. Format migration from pouches supports margin expansion in consolidated accounts.
- USDA Organic Certification Pathways:Certified organic extruded snacks access dedicated shelf sets and promotional calendars in Whole Foods and Sprouts banners. Supply chain traceability investments create defensible positioning.
- Hot-and-Spicy Flavor Platforms:Chile-lime and Nashville hot profiles attract younger demographic cohorts in Texas and Florida convenience stores. Regional taste preferences support price premiums against national benchmarks.
Industry Challenges
- Extrusion Process Engineer Scarcity:Specialized knowledge of twin-screw configurations and die design for specific expansion ratios commands compensation premiums. Talent competition from pharmaceutical and pet food extrusion sectors intensifies recruitment.
- Legacy ERP Integration with Track-and-Trace:Lot-level ingredient sourcing documentation requirements strain paper-based quality systems. Software migration timelines conflict with audit deadlines for major retail supplier qualifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Extruded Snack Food Market |
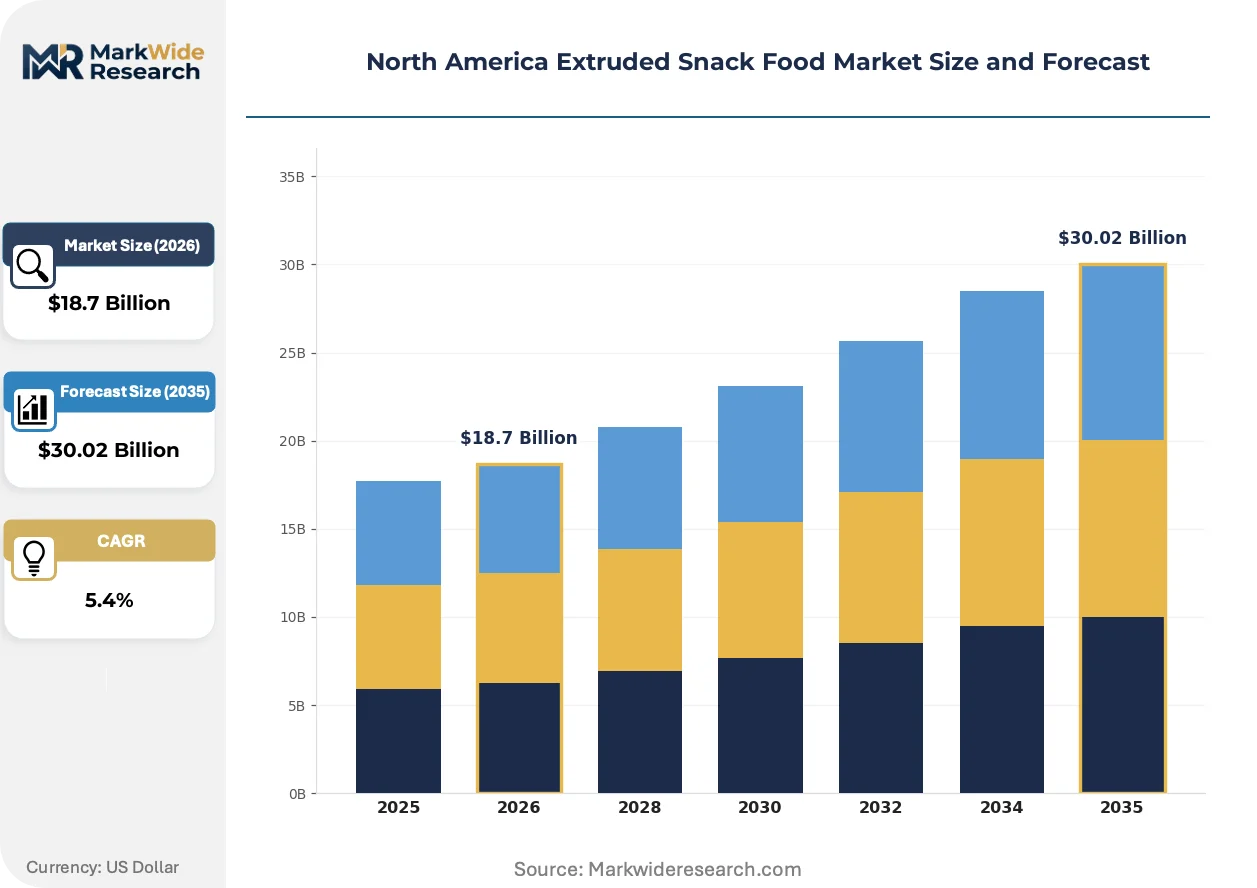
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potato Snacks, Corn Snacks, Rice Snacks, Mixed Grain Snacks Flavor Profile: Salty, Sweet, Spicy, Savory Packaging Type: Bags, Boxes, Tubs, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores |
| Companies Covered | PepsiCo, General Mills, Mondelez International, Kellogg Company, Conagra Brands, Calbee, Campbell Soup Company, Utz Brands, ITC Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Extruded Snack Food Market Strategic Shifts & Innovations
Pulse-protein extrusion and modified atmosphere packaging are converging to reshape product development roadmaps, while regulatory labeling mandates accelerate transparency investments across the value chain.
High-moisture extrusion of pea and lentil proteins is integrating into mainstream savory snack production lines previously dedicated to corn and potato formulations. Mid-sized regional brands in the Pacific Northwest and Upper Midwest are piloting these systems at 30-40% capacity substitution rates. The technology is integrating clean-label protein claims into conventional snack price tiers without requiring separate processing facilities.
FDA updated Nutrition Facts regulations and parallel Health Canada front-of-package symbol requirements are forcing synchronized reformulation across North American product portfolios. Dual-compliance strategies favor unified sodium and added-sugar targets rather than market-specific recipes. Small-format convenience store SKUs face disproportionate compliance burden due to shorter production runs and label changeover costs.
Consolidated procurement functions at merged convenience store banners are displacing fragmented regional buying with centralized category management. Volume commitments and exclusive flavor development agreements now dominate supplier negotiations. This concentration is most visible in the southeastern United States, where RaceTrac, QuikTrip, and Circle K procurement desks have unified under shared analytics platforms.
North America Extruded Snack Food Market Segmentation
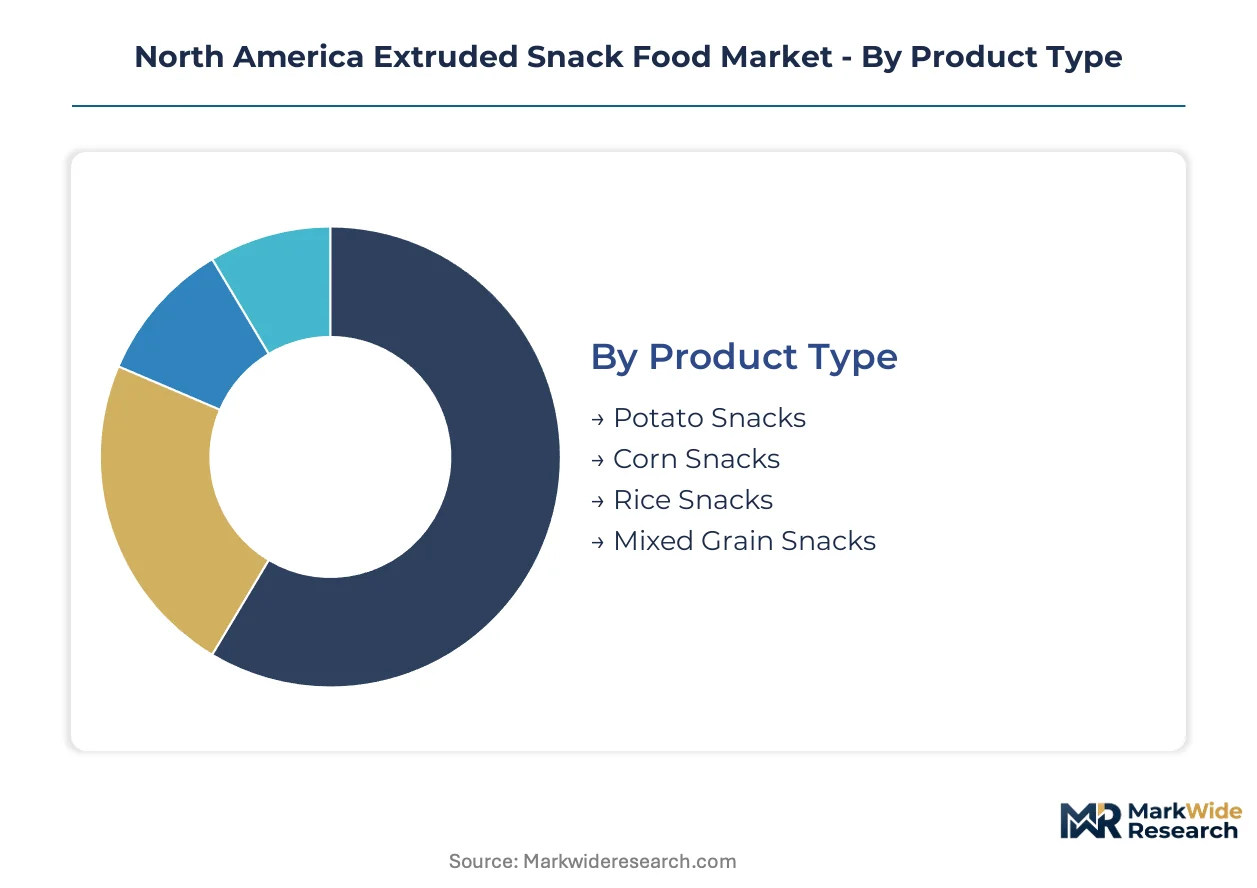
Extruded snack manufacturers configure production lines around specific expansion ratios and die geometries that lock in texture profiles for each product category. Segmentation choices determine capital allocation between high-volume commodity runs and specialized equipment for premium formats. Procurement desks at consolidated retail banners now demand segment-specific compliance documentation that favors suppliers with dedicated manufacturing assets.
Product Type:
Standardization dominates corn and potato platforms where ingredient sourcing and extrusion parameters remain consistent across production batches, while mixed grain formulations require customized screw configurations and temperature profiling that elevate technical complexity.
- Corn Snacks:Yellow and white corn meal extrusions achieve bulk densities of 50–80 g/L through high-shear processing with single-screw configurations. Demand concentrates in the southeastern United States, where regional distribution hubs serve RaceTrac and QuikTrip convenience store banners with private-label volume commitments. FDA sodium reduction timelines are forcing flavor system rebuilds that risk texture degradation in low-salt formulations.
- Mixed Grain Snacks:Blends incorporating quinoa, sorghum, and ancient wheat varieties utilize lower-shear twin-screw extrusion to preserve fiber integrity and protein structure. The Pacific Northwest and Upper Midwest anchor pilot production capacity, where mid-sized brands target Whole Foods and Sprouts promotional calendars with clean-label positioning. Health Canada front-of-package nutrition symbol requirements accelerate reformulation investments across cross-border manufacturing facilities.
- Potato Snacks:Dehydrated potato flake extrusions with pre-gelatinized starch matrices deliver uniform cell structure and extended shelf stability below 4% moisture content.
- Rice Snacks:Milled rice flour formulations with modified amylopectin ratios achieve lighter expansion ratios suited to Asian-inspired flavor platforms in California and British Columbia retail channels.
Most installed capacity flows through Corn Snacks. Expansion is steepest in Mixed Grain Snacks.
Flavor Profile:
Cost tier stratification separates commodity salt applications from premium spice blends that command ingredient premiums and specialized coating equipment investments.
- Spicy:Chile-lime, Nashville hot, and ghost pepper oil encapsulation systems require dedicated seasoning drums and oil application lines that increase changeover complexity. Texas and Florida convenience stores drive regional concentration, where younger demographic cohorts support price premiums against national flavor benchmarks. Supply constraints on authentic chile sourcing from Hatch Valley and Oaxaca create procurement volatility for premium positioning.
- Savory:Cheese powder, yeast extract, and hydrolyzed vegetable protein blends dominate club-channel formats where umami intensity drives repeat purchase in Costco and Sam's Club locations. The southeastern United States concentrates manufacturing capacity within 500-mile radius of major population centers, reducing outbound freight costs for bulk tub shipments.
- Salty:Sodium chloride and potassium chloride blends face FDA draft reduction targets that force complete flavor system rebuilds without guaranteed retail price recovery mechanisms.
- Sweet:Maltodextrin and sugar-based coatings compete with clean-label honey and maple formulations that require modified atmosphere packaging to prevent moisture migration and stickiness.
Volume concentration sits with Savory applications. Climbing the fastest is Spicy, supported by regional taste differentiation in Sun Belt convenience stores.
Packaging Type:
Margin structure varies dramatically between lightweight flexible formats optimized for freight economics and rigid containers that capture resealability premiums in consolidated retail accounts.
- Pouches:Multi-layer metallized films with nitrogen flush achieve 12–18 month shelf stability at material weights below 5 grams per unit. Unit economics favor e-commerce and supermarket channels where shipping cost absorption determines supplier selection. USDA organic certification requirements for lot-level traceability strain legacy ERP integration timelines for mid-tier producers.
- Tubs:Polypropylene containers with moisture-lock closures command repeat purchase premiums in club and convenience channels where portion control and resealability drive consumption frequency. Format migration from pouches supports margin expansion in consolidated procurement negotiations with unified RaceTrac, QuikTrip, and Circle K analytics platforms.
- Bags:Pillow and gusseted configurations with resealable zippers balance material efficiency with shelf presence for mid-tier supermarket placement.
- Boxes:Paperboard secondary packaging with primary film liners serves gift and variety pack applications in specialty store channels with higher promotional calendar dependence.
Freight-optimized capacity concentrates in Pouches. Steepest expansion trajectory belongs to Tubs, reflecting club-channel format migration and convenience store resealability requirements.
Distribution Channel:
Customer type fragmentation separates high-frequency impulse purchase environments from planned shopping occasions that demand different packaging formats and promotional investment levels.
- Convenience Stores:Single-serve and small-format SKUs face disproportionate regulatory compliance burden due to shorter production runs and label changeover costs for FDA and Health Canada dual-compliance strategies. Consolidated procurement functions at merged southeastern banners displace fragmented regional buying with centralized category management and volume commitment requirements.
- Supermarkets:Multi-pack and family-size configurations dominate shelf-space negotiations where direct-store-delivery infrastructure determines supplier access to planogram positioning. PepsiCo leverages its distribution network to sustain shelf-space dominance in these consolidated accounts.
- Online Retail:Ship-ready packaging with burst strength and drop-test certification requirements adds material cost layers that compress margins in price-transparent digital channels.
- Specialty Stores:Whole Foods and Sprouts dedicated shelf sets for certified organic extruded snacks reward supply chain traceability investments with promotional calendar access.
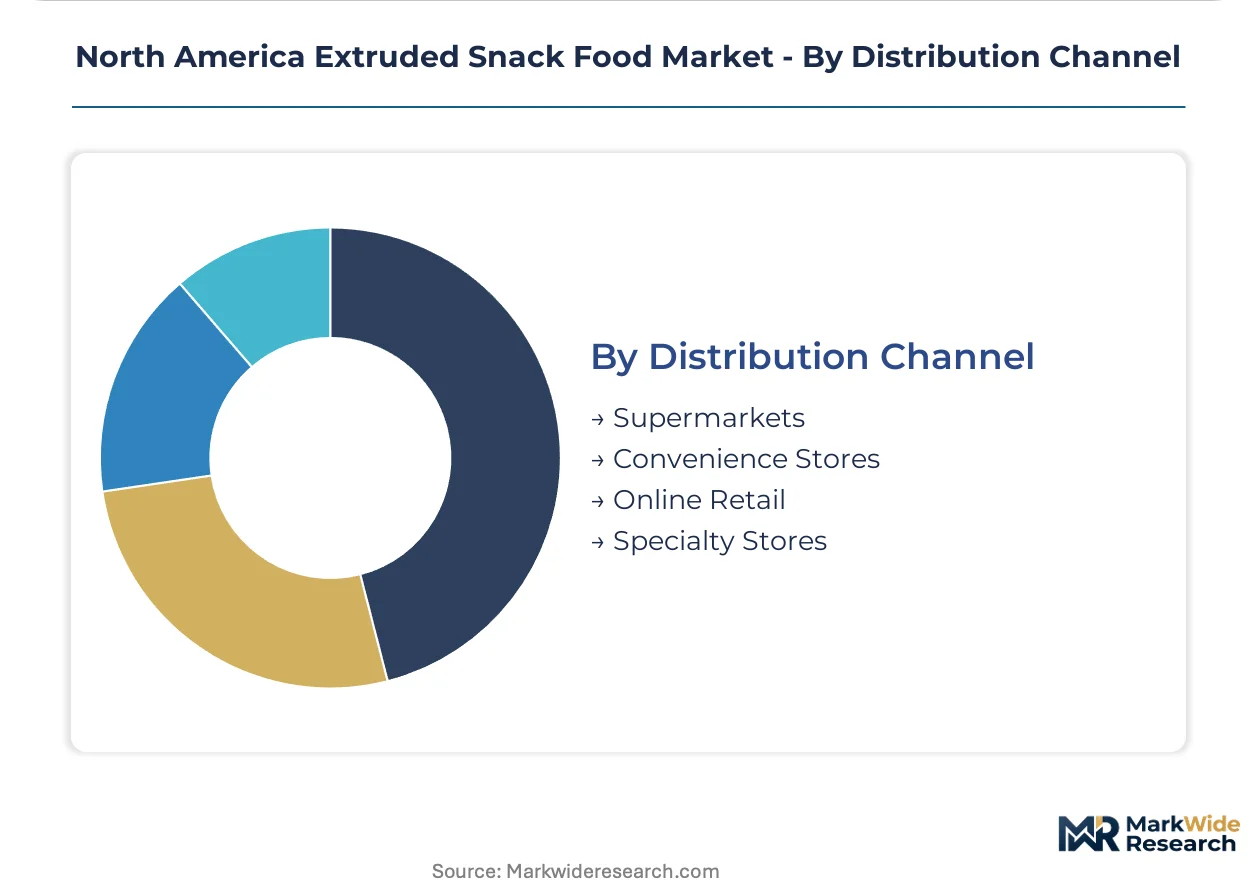
Transaction volume concentrates in Supermarkets. Gaining share fastest is Convenience Stores, driven by southeastern procurement consolidation and private-label expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates substantially higher extruded snack volume than Canada, though both markets face synchronized regulatory pressure from FDA and Health Canada labeling mandates. Mexico's manufacturing base is expanding as brands seek tariff-advantaged production for North American distribution.
United States
Southeastern distribution hubs in Georgia and Florida concentrate extrusion capacity within 500-mile radius of major population centers. The FDA's sodium reduction guidance forces flavor system rebuilds across savory snack portfolios. RaceTrac and QuikTrip procurement consolidation in Atlanta creates centralized category management with volume commitment requirements.
Canada
Health Canada's front-of-package nutrition symbol requirements accelerate clean-label reformulation investments in Ontario and Quebec manufacturing facilities. Cross-border retail banners demand unified North American product specifications. Toronto-area co-manufacturing clusters serve private-label expansion in convenience and club channels.
Mexico
Querétaro and Guanajuato industrial corridors attract extrusion capacity investment seeking USMCA tariff advantages for corn-based snack exports. Domestic demand concentrates in Mexico City and Monterrey metropolitan areas. The country's national food safety regulator enforces labeling standards that align with US and Canadian technical regulations.
California
Asian-inspired flavor platforms drive rice snack innovation in Los Angeles and San Francisco Bay Area retail channels. Modified atmosphere packaging adoption rates exceed national averages due to clean-label positioning requirements. Sacramento Valley distribution infrastructure supports Pacific Northwest market penetration.
Texas
Chile-lime and Nashville hot flavor profiles command price premiums in Houston and Dallas-Fort Worth convenience store networks. Younger demographic cohorts support regional taste differentiation against national benchmarks. Interstate 35 corridor logistics clusters reduce outbound freight costs for spicy segment distribution.
North America Extruded Snack Food Market Key Industry Players
United States producers anchor the scale-driven tier; Canadian and Mexican specialists hold regional positioning through tariff-advantaged production and cross-border compliance expertise. Market structure concentrates around three to four national brand portfolios with direct-store-delivery infrastructure, while mid-tier regional players compete on flavor innovation and private-label execution. Strategic archetypes separate DSD-integrated multinationals, co-manufacturing-dependent regional brands, and organic-certified specialty operators. Dominant competitive moves include procurement consolidation responses and sodium-compliant reformulation pipelines.
Within the multinational tier, PepsiCo, General Mills, and Mondelez International exemplify divergent strategic positioning. PepsiCo occupies a position anchored in direct-store-delivery infrastructure dominance. General Mills represents R&D-intensive whole-grain formulation capabilities. Mondelez International sits within specialized savory snack portfolio development, navigating retailer category management shifts without DSD network dependency.
| Leading Market Players |
|---|
| PepsiCo |
| General Mills |
| Mondelez International |
| Kellogg Company |
| Conagra Brands |
| Calbee |
| Campbell Soup Company |
| Utz Brands |
| ITC Limited |
| Others |
Cost & Logistics Intelligence
Corn futures price volatility from Midwest drought cycles cascades through extrusion manufacturing into three-tier pricing structure across premium, standard, and economy levels. Input cost spikes compress margin structures for commodity-positioned products while reformulation investments for FDA sodium compliance elevate pricing floors for clean-label segments.
Pricing Analysis
Capacity additions in Mexico's Querétaro corridor are reshaping price floors for corn-based snack exports under USMCA tariff advantages. Pricing stratifies across premium, standard, and economy tiers driven by USDA organic certification level and volume scale commitments from consolidated convenience store procurement. Cost compression in standard-tier segments is intensifying because of single-source equipment dependency from German and Italian suppliers. Club-channel buyers exhibit least price sensitivity due to resealable tub premiums, while small-format convenience SKUs face acute margin pressure from label changeover costs.
Supply Chain Analysis
Dual-sourcing qualification requirements from RaceTrac and QuikTrip procurement desks mandate redundant extrusion capacity within 500-mile radius of southeastern distribution hubs. Geographic supply concentrates in the United States, Canada, and Mexico, with raw material dependencies on yellow corn meal from the Corn Belt, specialized extruder screws from German fabricators, and nitrogen-flush packaging films. Single-source vulnerability in twin-screw equipment creates 18-month lead time exposure for capacity expansion. Distribution runs through direct-store-delivery networks for supermarket dominance and co-manufacturing clusters for private-label flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America extruded snack food market reads as a late-cycle quality story. Demand is shifting toward whole-grain and pulse-protein formulations that command shelf-space premiums in Whole Foods and Sprouts promotional calendars.
For Market Incumbents: Deploy backward integration into Corn Belt grain handling to secure input cost stability against drought-cycle volatility. Incumbents must accelerate sodium-compliant reformulation pipelines before FDA draft targets finalize, while consolidating co-manufacturing relationships in Georgia and Florida to defend against procurement centralization at merged convenience store banners. Channel control through direct-store-delivery infrastructure remains the critical lever for shelf-space dominance against Mondelez International's savory snack specialization. For New Entrants and Emerging Players: Pulse-protein extrusion technology at 30-40% capacity substitution rates offers white-space entry into clean-label segments without dedicated facility investment. New entrants should target the Pacific Northwest and Upper Midwest pilot production zones where mid-sized brands access Sprouts and Whole Foods promotional calendars with ancient grain positioning. A co-manufacturing-first go-to-market angle bypasses capital-intensive extruder equipment lead times while building USDA organic certification track records. For Investors and Strategic Acquirers: Asymmetric upside sits with regional co-manufacturing specialists holding Health Canada cross-border compliance expertise and Toronto-area cluster proximity. Long-term viability over the 5-10 year window favors assets with dual FDA-Health Canada formulation capabilities and resealable tub format migration readiness. The signal to watch is procurement consolidation velocity at southeastern convenience store banners as volume commitment thresholds displace fragmented regional suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Whole-Grain Formulation Pipeline | General Mills' R&D intensity preserves fiber integrity through lower-shear twin-screw configurations. |
| Resealable Tub Format Migration | Moisture-lock closures command repeat purchase premiums in Costco and Sam's Club consolidated accounts. |
| USDA Organic Certification Pathway | Supply chain traceability investments unlock dedicated shelf sets at Sprouts and Whole Foods banners. |
| Sodium-Compliant Flavor System Rebuild | FDA draft targets force complete savory snack reformulation without guaranteed retail price recovery. |
| Southeastern Co-Manufacturing Cluster Expansion | Proximity to corn belt supply chains reduces inbound freight costs for RaceTrac and QuikTrip private-label volume. |
Research Approach
Bottom-up convenience store and club-channel modeling reconciled against top-down extrusion capacity tracking forms the analytical core of this study. Primary interviews with category buyers at consolidated retail banners, extrusion process engineers, plant managers at co-manufacturing facilities, and procurement leads at ingredient suppliers combined with secondary validation from FDA labeling guidance documents, Health Canada front-of-package symbol regulations, USDA organic certification databases, and Nielsen retail audit data. Triangulation across stakeholder inputs and regulatory filings ensures segmentation integrity.
Input-output matrices mapped corn meal input costs, extrusion throughput parameters, and packaging format economics against distribution channel pricing power across the projection horizon. Segmentation dimensions modeled include product type, flavor profile, packaging configuration, and distribution channel, with additional granularity on USDA organic certification tier and sodium content compliance status. CAGRs were derived from capacity utilization trends and reformulation investment cycles. Forecast inputs incorporated FDA sodium reduction timeline scenarios and Health Canada symbol implementation pace.
The model holds under stable corn belt growing conditions and sustained USMCA tariff treatment; deviation in Midwest drought frequency or trade policy shifts would shift volume and value trajectories materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Meat Protein Chips Market
Snacks
Low Calorie Snack Foods Market
Snacks
UAE Cereal Bar Market
Snacks
Cheese Snacks Market
Snacks
Fruit Jerky Market
Snacks
UAE Snack Bar Market
Snacks
Protein Crisps Market
Snacks
Germany Energy Bar Market
Snacks
Europe Snack Pellets Market
Snacks
Low Calorie Biscuits Market
Snacks
North America Potato Chips Market
Snacks
Low-Calorie Savoury Snacks Market
Snacks
Nutritional Bar Market
Snacks
Protein Bars Market
Snacks
Healthy Fruit and Vegetable Chips Market
Snacks
Vegan Snacks Market