
 Savory Snack Products Market | 2026-2036
Savory Snack Products Market Size, Share, and Industry Trends Forecast 2026-2036
Savory Snack Products Market Insights
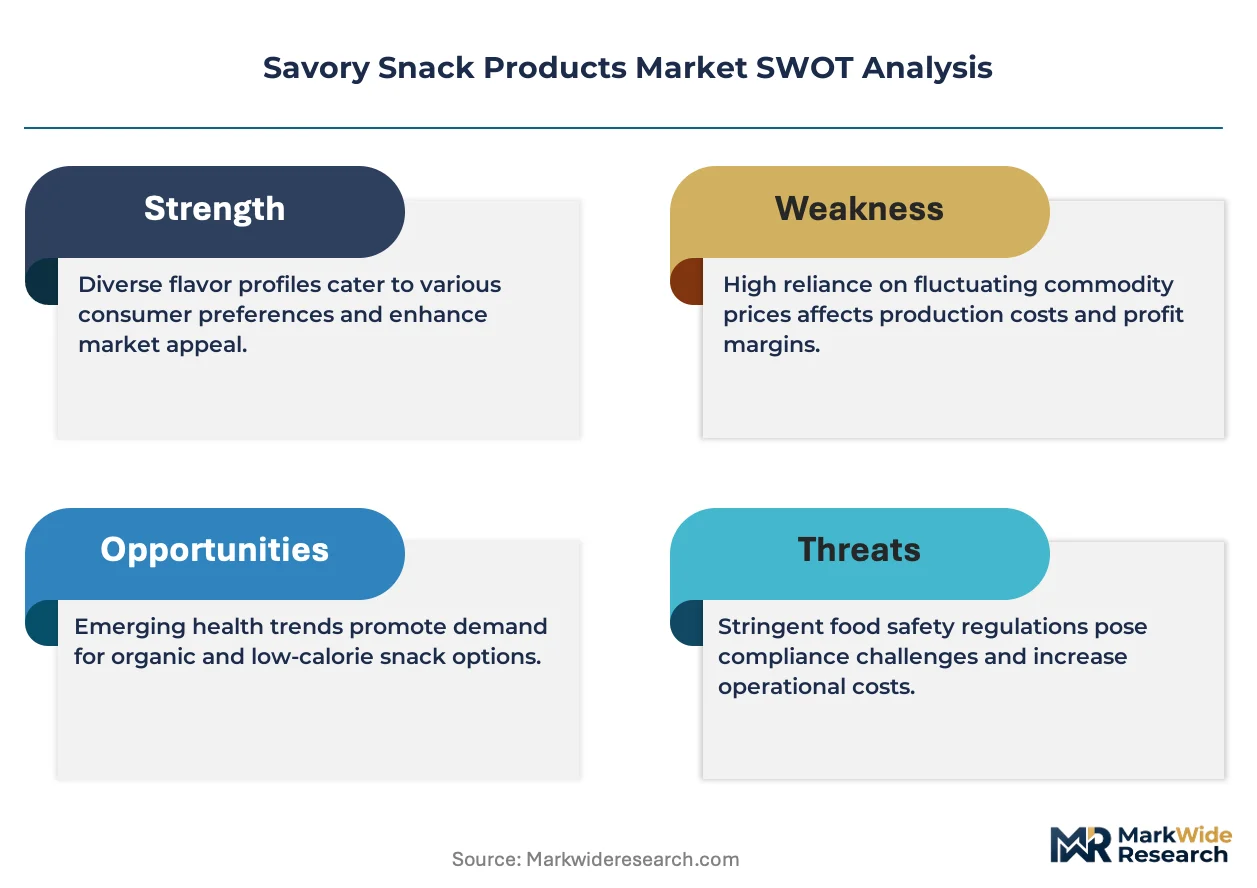
Buyer fragmentation across convenience stores and online retailers is repositioning procurement power away from traditional supermarkets. PepsiCo Inc leverages its direct-store-delivery network to sustain shelf dominance in North American convenience channels. Mondelez International, Inc. competes through premium positioning in European specialty shops. Calbee anchors its growth in Asian markets with localized flavor portfolios.
Savory snack products comprise seasoned, shelf-stable foods designed for immediate consumption, typically manufactured through extrusion, frying, baking, or air-popping processes with moisture content below 10% to ensure crispness and microbial stability. Grain-based chips occupy the largest volume share while legume-based alternatives capture the fastest margin expansion as protein fortification commands price premiums. Online retailers represent the fastest-growing distribution channel, though supermarkets still control the majority of value throughput due to impulse-buy placement economics.
FDA nutrition labeling rules and EU salt-reduction frameworks under EFSA guidance are tightening formulation constraints across major export markets. BIS standards in India and China's SAMR food safety protocols add compliance layers for multinational manufacturers entering Asia-Pacific growth corridors. Stakeholders must monitor regulatory divergence between sodium caps, front-of-pack warning labels, and novel ingredient approvals when allocating R&D budgets across geographies.
Market Dynamics
Clean-label mandates from EFSA and FDA are compressing formulation timelines while fragmenting ingredient sourcing across multiple supplier tiers. Manufacturers must reformulate legacy portfolios without sacrificing shelf stability or sensory performance.
Growth Catalysts
- EFSA salt-reduction frameworks:European reformulation mandates accelerate demand for potassium-based salt replacers and umami-enhancing yeast extracts. Reformulated products command shelf placement premiums in German and French retail.
- Air-popping technology:Reduced-oil processing methods cut saturated fat content by half while preserving texture integrity. Equipment adoption spreads through contract manufacturers serving private-label brands.
- Urban India:Convenience store penetration in Mumbai, Delhi, and Bangalore creates impulse-purchase infrastructure for single-serve formats. Young professionals drive trial rates for international flavor profiles.
Market Restraints
- Palm oil price volatility:Southeast Asian supply disruptions and EU deforestation regulations squeeze frying oil procurement budgets. Alternative oils require capital-intensive process revalidation.
- Extrusion equipment oligopoly:Three European and Japanese equipment suppliers control critical high-capacity extruder technology. Lead times extend to fourteen months for new capacity.
- Acrylamide formation limits:Binding EU benchmark levels for Maillard reaction byproducts restrict browning intensity in baked chip categories. Sensorial trade-offs reduce consumer acceptance in Mediterranean markets.
Strategic Opportunities
- Brazilian ANVISA novel ingredient pathway:Simplified approval procedures for plant proteins and fiber isolates open formulation space for local brands. First-movers capture shelf space ahead of multinational entry.
- Direct-to-pantry subscription models:Curated snack boxes bypass retail slotting fees while capturing consumption data. Urban Chinese households show highest subscription retention rates.
- Fermentation-derived flavor precursors:Precision fermentation produces clean-label savory notes without synthetic additives. Early partnerships with biotech suppliers lock in exclusive taste profiles.
Industry Challenges
- Legacy ERP integration:Real-time ingredient traceability requirements clash with decades-old manufacturing execution systems. SAP and Oracle migrations stall at mid-tier producers.
- Sensory scientist scarcity:Cross-trained professionals combining food chemistry with consumer psychology command premium compensation. Recruitment pipelines fail in secondary US and European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Savory Snack Products Market |
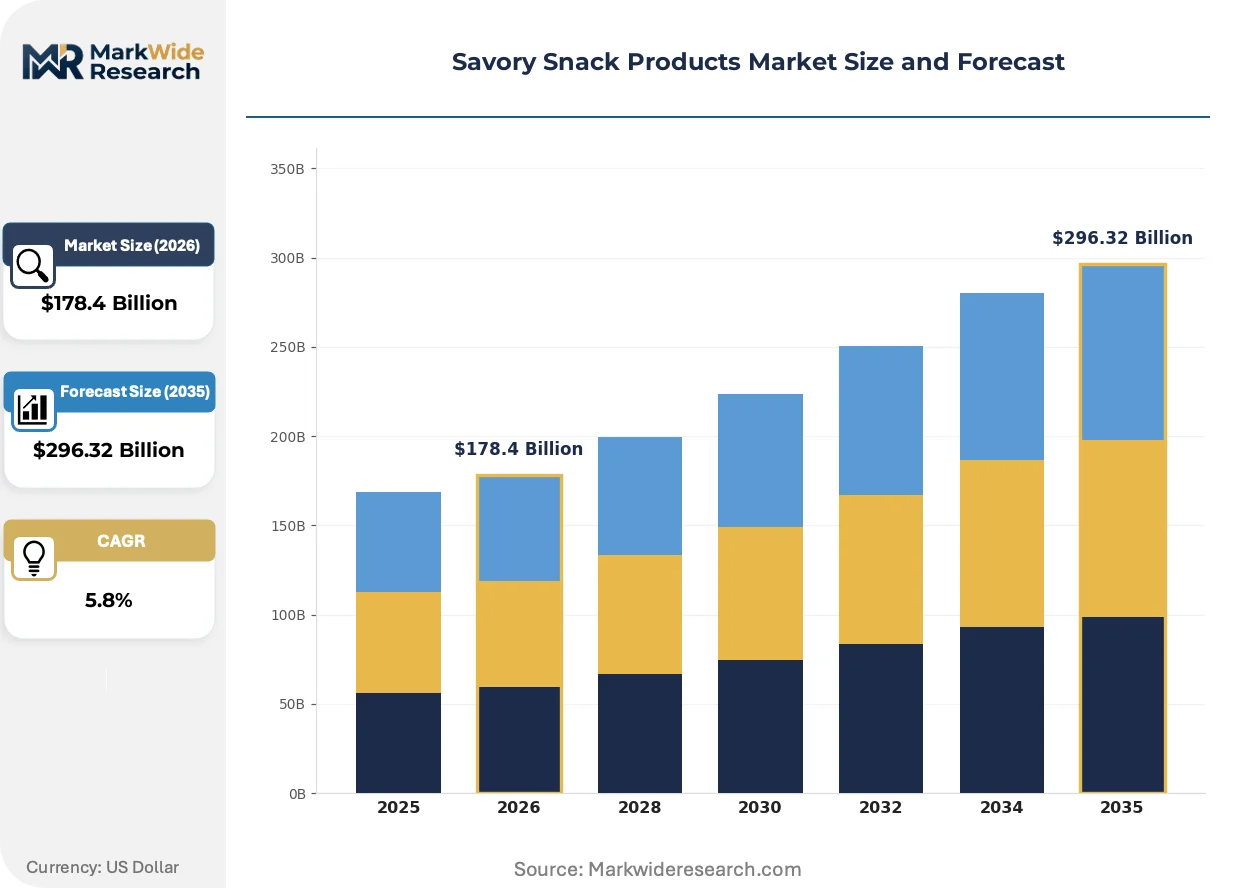
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $296.32 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Pretzels, Popcorn, Nuts Ingredient Type: Grain-based, Legume-based, Vegetable-based, Meat-based Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Shops End User: Children, Adults, Elderly, Health-conscious Consumers |
| Companies Covered | PepsiCo Inc, Mondelez International, Inc., Kellogg Company, The Kraft Heinz Company, General Mills Inc., Conagra Brands, Inc., Calbee, Intersnack Group, ITC Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Savory Snack Products Market Trends and Innovations
Processing technologies and disclosure requirements are rewriting competitive advantage in savory snacks. Winners separate through speed of reformulation and transparency architecture.
Pulse protein extrusion is expanding into mainstream chip formats beyond niche health positioning. Pea and lentil flour blends now achieve expansion ratios matching potato starch benchmarks. Major retailers in the United Kingdom and Netherlands are expanding shelf space for these formats ahead of planned front-of-pack labeling mandates.
EU Green Deal agricultural sourcing rules now require deforestation-free supply chain documentation for soy and palm derivatives. Manufacturers must implement satellite-verified traceability systems by 2025. Brazilian and Indonesian supply bases face the steepest compliance costs, pushing reformulation toward sunflower and rapeseed alternatives in European production.
Convenience store distributors are consolidating category management authority previously held by supermarket buyers. Mondelez and PepsiCo now negotiate directly with 7-Eleven and Lawson procurement teams for planogram positioning. This channel shift concentrates volume forecasts in fewer decision-makers, compressing forecast accuracy for regional brands in Japan and the United States.
Savory Snack Products Market Segmentation
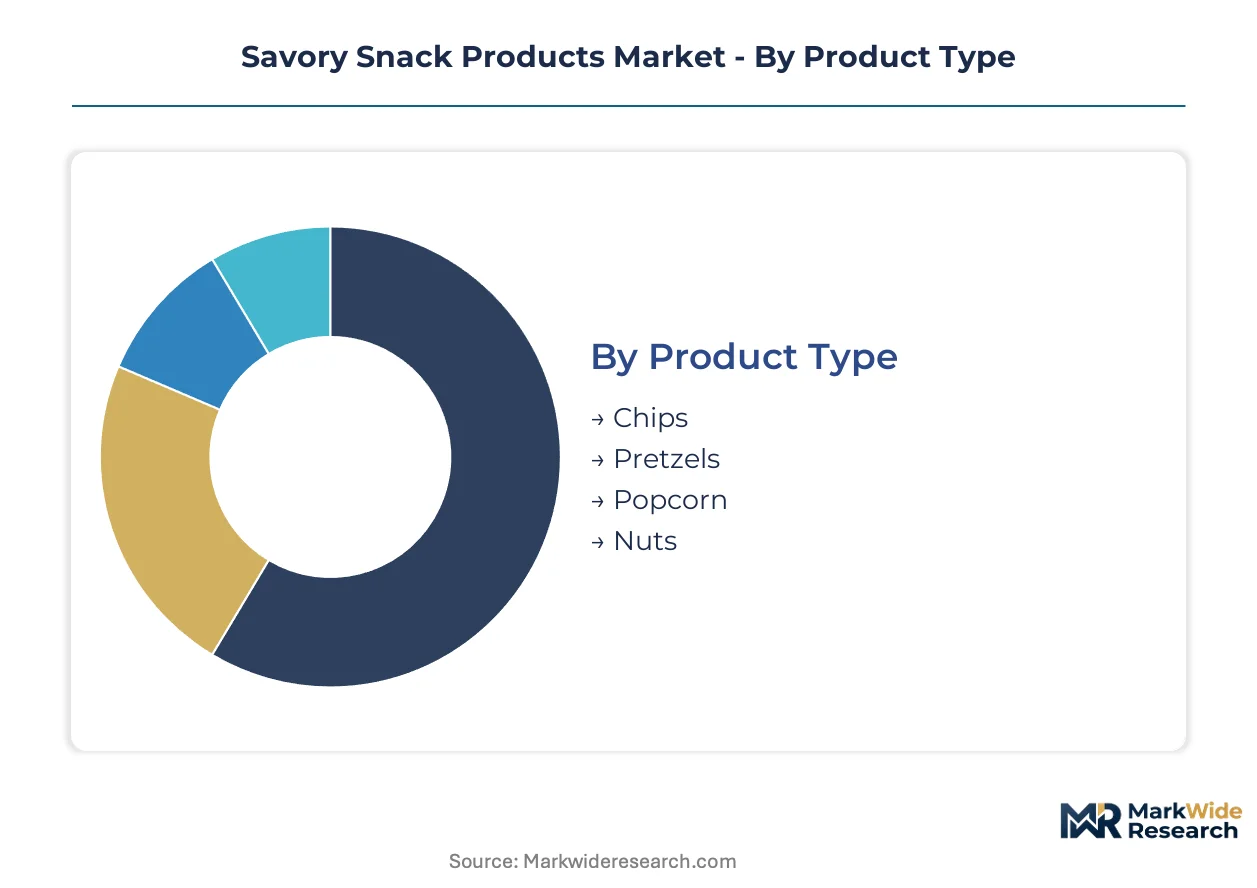
Segmentation in savory snacks reveals how formulation choices and channel strategies create distinct margin profiles. Manufacturers must align R&D investment with the specific technical and regulatory demands of each segment cluster.
Product Type:
Standalone snack formats dominate impulse purchasing, while embedded or bundled formats require different shelf-life engineering and packaging economics.
- Chips:Thin-sliced or extruded substrates fried or baked to sub-10% moisture, with flavor deposition via oil-based slurry or electrostatic powder coating. Demand concentrates in United States convenience stores where single-serve bags drive highest velocity; sodium reduction mandates from FDA and EFSA force continuous reformulation cycles.
- Popcorn:Air-popped or oil-popped whole grain with expansion ratios determining texture grade. Health-conscious consumers in United Kingdom and Germany expand purchases as air-popping technology eliminates half the saturated fat content; clean-label positioning commands price premiums in specialty retail.
- Pretzels:Wheat flour dough subjected to alkaline bath before baking, creating distinctive Maillard crust. German and Austrian heritage markets sustain volume leadership.
- Nuts:Dry-roasted or oil-roasted tree nuts and legumes with moisture barriers critical to rancidity prevention. Chinese and Indian urban households drive premium salted and flavored varieties.
Chips lead volumes today; popcorn is gaining share fastest.
Ingredient Type:
Raw material sourcing depth varies dramatically, with some categories requiring captive agricultural relationships while others rely on spot commodity markets.
- Grain-based:Corn, wheat, and rice flour extrusions forming the structural backbone of conventional snacks. United States Corn Belt proximity shapes procurement economics for North American manufacturers; EU Green Deal deforestation documentation requirements now extend to supply chain verification.
- Legume-based:Pea, lentil, and chickpea flours achieving expansion parity with potato starch through twin-screw extrusion optimization. United Kingdom and Netherlands retailers expand shelf space ahead of mandatory front-of-pack labeling; protein fortification justifies 15-30% price premiums over grain equivalents.
- Vegetable-based:Root vegetable slices and dehydrated greens marketed as micronutrient-dense alternatives. Japanese and South Korean consumers show highest trial rates for seaweed and taro variants.
- Meat-based:Jerky, cracklings, and puffed collagen snacks requiring distinct USDA or EFSA processing oversight. Brazilian and Argentinian beef supply bases serve Latin American demand clusters.
Grain-based formulations retain volume dominance; legume-based alternatives show steepest expansion trajectory.
Distribution Channel:
Channel selection determines packaging format, case count, and trade spend allocation, with direct-store-delivery versus warehouse distribution creating divergent cost structures.
- Supermarkets:Full-line retailers controlling planogram authority through category captain arrangements. Impulse-buy placement at aisle endcaps sustains volume throughput in France and Germany despite share erosion.
- Convenience Stores:Limited-assortment formats emphasizing immediate consumption and single-serve price points. 7-Eleven and Lawson procurement teams in Japan and United States now negotiate directly with manufacturers, consolidating forecasting power.
- Online Retailers:E-commerce platforms enabling subscription bundling and direct-to-pantry fulfillment. Urban Chinese households demonstrate highest retention rates for curated snack boxes.
- Specialty Shops:Premium and ethnic-focused retailers emphasizing provenance and artisan positioning. Mondelez leverages this channel for European premium placement.
Supermarkets maintain volume leadership; online retailers expand most quickly.
End User:
Demographic targeting shapes sodium levels, portion sizing, and nutritional claim architecture, with regulatory scrutiny intensifying for vulnerable populations.
- Children:Portion-controlled formats with school-compliant sodium thresholds and allergen-free positioning. FSSAI and FDA school nutrition guidelines restrict permissible ingredients in India and United States.
- Adults:Broad-spectrum positioning balancing indulgence with permissible snacking occasions. Workforce on-the-go consumption in Mumbai, Delhi, and Bangalore drives Indian growth.
- Elderly:Soft-texture and reduced-sodium variants addressing chewing difficulty and hypertension prevalence. Japanese aging demographics sustain specialized product development.
- Health-conscious Consumers:Segment demanding clean-label disclosure, protein fortification, and functional ingredient inclusion. EFSA and FDA front-of-pack labeling mandates accelerate migration toward this positioning in Europe and North America.
Adult targeting captures largest volume base; health-conscious positioning climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's convenience store penetration outpaces India's urban infrastructure buildout, though both markets show converging snacking frequency among young professionals. Regulatory divergence between EFSA sodium caps and FDA labeling rules fragments formulation strategies across export corridors.
United States
Single-serve bag velocity in convenience stores drives impulse purchasing, with 7-Eleven procurement teams consolidating planogram authority. FDA nutrition labeling rules force continuous sodium reduction cycles. Chicago and Dallas metropolitan clusters host contract manufacturing capacity serving private-label brands.
Germany
EFSA salt-reduction frameworks accelerate demand for potassium-based replacers and umami-enhancing yeast extracts. EU Green Deal deforestation documentation requirements extend to soy and palm supply chains. Munich and Hamburg retail clusters command shelf placement premiums for reformulated products.
China
SAMR food safety protocols add compliance layers for multinational manufacturers entering growth corridors. Urban households in Shanghai and Beijing demonstrate highest retention rates for curated snack box subscriptions. Yangtze River Delta manufacturing bases serve domestic and export demand.
India
FSSAI school nutrition guidelines restrict permissible ingredients in children-targeted formats. Mumbai, Delhi, and Bangalore convenience store penetration creates impulse-purchase infrastructure for single-serve formats. Young professionals in these metros drive trial rates for international flavor profiles.
United Kingdom
Front-of-pack labeling mandates accelerate migration toward health-conscious positioning. Retailers in London and Manchester expand shelf space for legume-based alternatives ahead of mandatory disclosure rules. Air-popped popcorn commands price premiums in specialty retail channels.
Savory Snack Products Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented channel structures. The vendor base spans multinational CPG holding companies, regional snack specialists, and private-label contract manufacturers. Three archetypes dominate: scale-driven portfolio conglomerates, geography-anchored flavor specialists, and agile private-label suppliers. Competitive moves concentrate on direct-store-delivery network expansion and clean-label reformulation partnerships.
Among diversified CPG conglomerates, PepsiCo Inc and Mondelez International, Inc. occupy positions representing scale-driven distribution archetypes. Calbee exemplifies the geography-anchored specialist model with localized flavor portfolios.
| Leading Market Players |
|---|
| PepsiCo Inc |
| Mondelez International, Inc. |
| Kellogg Company |
| The Kraft Heinz Company |
| General Mills Inc. |
| Conagra Brands, Inc. |
| Calbee |
| Intersnack Group |
| ITC Limited |
| Others |
Pricing and Supply Chain Analysis
Palm oil futures volatility cascades through frying oil procurement budgets, forcing manufacturers to stratify pricing across premium reformulated tiers and economy legacy lines as EU deforestation regulations tighten compliance costs.
Pricing Analysis
Capacity additions in Southeast Asian oleochemical processing are reshaping price floors for alternative frying oils, though equipment revalidation costs sustain premiums for early reformulators. Three-tier pricing structure across premium clean-label, standard mass-market, and economy private-label levels reflects certification grade and sodium-reduction investment. Pricing pressure stems from potassium-based salt replacer sourcing constraints as EFSA mandates accelerate. Private-label buyers exhibit highest price sensitivity; premium health-positioned segments absorb cost pass-through with minimal volume elasticity.
Supply Chain Analysis
Dual-sourcing requirements from European retailers now mandate satellite-verified traceability for palm and soy derivatives alongside qualified secondary oil suppliers. Manufacturing draws from Indonesian, Malaysian, and Brazilian agricultural bases for oil inputs, with pea and lentil protein concentrates increasingly sourced from Canadian and Ukrainian processors. Single-source vulnerability concentrates in high-capacity extrusion equipment where three European and Japanese suppliers control critical technology. Distribution runs through direct-store-delivery networks for convenience channel dominance and warehouse consolidation for supermarket volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The savory snack products market functions as a stable compounder anchored by persistent urbanization-driven snacking frequency among young professionals across emerging Asian metros.
For Market Incumbents: Extend direct-store-delivery network density in Mumbai, Delhi, and Bangalore to preempt convenience store consolidation by 7-Eleven and Lawson procurement teams. Deepen backward integration into pea and lentil protein processing to secure margin position against legume-based entrant pressure. Lock exclusive fermentation-derived flavor precursor partnerships before biotech supplier capacity saturates.
For New Entrants and Emerging Players: Enter via Brazilian ANVISA novel ingredient pathway for plant protein and fiber isolate formulations ahead of multinational shelf saturation. Target urban Chinese subscription snack box retention through curated direct-to-pantry fulfillment models. Exploit sensory scientist scarcity in secondary US and European markets by recruiting cross-trained food chemistry professionals at premium compensation.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier private-label contract manufacturers possessing air-popping technology capabilities and SAP migration completion. Long-term viability favors producers with deforestation-free supply chain documentation systems operational ahead of EU Green Deal enforcement. Monitor extrusion equipment order backlogs as inflection indicator for capacity-constrained pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Partnership | EFSA sodium caps and FDA labeling rules force continuous R&D cycles without sensory trade-offs. |
| Direct-Store-Delivery Expansion | PepsiCo's convenience channel dominance demonstrates shelf placement premiums from route density. |
| Pulse Protein Backward Integration | Captive pea and lentil processing secures margin expansion as protein fortification commands price premiums. |
| Fermentation-Derived Flavor Lock-In | Exclusive biotech supplier partnerships create defensible taste differentiation without synthetic additives. |
| Satellite-Verified Traceability Implementation | EU Green Deal documentation requirements become table stakes for European retail access. |
Research Methodology
Multiple input streams — category buyer interviews, procurement lead discussions, manufacturing executive consultations, and regulatory affairs dialogues — were reconciled against Nielsen retail audit data, customs trade records, SEC 10-K filings, and EFSA guidance documents. Primary fieldwork with brand managers, supply planners, and channel sales heads at diversified CPG conglomerates and regional specialists informed demand-side assumptions. Secondary validation drew from BIS standards filings, SAMR protocol documentation, and FSSAI school nutrition guideline releases. Bottom-up volume builds and top-down macroeconomic reconciliation anchored triangulation integrity.
Data-stream reconciliation across product type, ingredient sourcing, distribution channel, and end-user demographic dimensions shaped the analytical framework throughout the projection horizon. CAGRs emerged from segment-level growth rate synthesis rather than single-point extrapolation. Modeled inputs included urbanization velocity in Indian metros, convenience store penetration rates in Chinese tier-one cities, and front-of-pack labeling mandate implementation phasing across European markets.
Inputs from retail procurement databases and equipment supplier order books were available through the study window; gaps in real-time commodity price index granularity introduce uncertainty bands around input cost assumptions. Deviation in palm oil supply disruption severity or extrusion equipment lead time extension would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Spain Snack Bar Market
Snacks
North America Baked Chips Market
Snacks
UAE Cereal Bar Market
Snacks
South Africa Snack Bar Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
North America Snack Pellets Market
Snacks
Nutritional Bar Market
Snacks
High Carb Low Fat Snack Market
Snacks
Organic Snack Food Market
Snacks
Spain Energy Bar Market
Snacks
Fat Free Meals and Snacks Market
Snacks
Plant-Based Snacks Market
Snacks
Low Calorie Biscuits Market
Snacks
Thailand Snack Bar Market
Snacks
Italy Snack Bar Market