
 Allergy-Free Snacks Market | 2026-2036
Allergy-Free Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Allergy-Free Snacks Market Insights
The EU Green Deal's farm-to-fork sustainability targets is consolidating demand for cleaner-label, allergen-controlled supply chains. General Mills leverages its cereal and snack manufacturing scale to secure ingredient traceability across North American production networks. Enjoy Life Foods anchors its competitive position through dedicated allergen-free facilities that eliminate cross-contact risks entirely. Made Good specializes in organic, school-safe formats that dominate the children's lunchbox segment in Canada and the United States.
Allergy-free snacks are formulated products manufactured without specified allergens—peanuts, tree nuts, dairy, gluten, eggs, soy, or sesame—using segregated equipment, validated cleaning protocols, and ingredient certificates of analysis to ensure safety thresholds below detectable limits. Their primary purpose is to provide safe consumption options for individuals with immunoglobulin E-mediated food allergies or celiac disease while serving the broader clean-label preference population. Gluten-free product lines capture the largest volume share due to celiac diagnosis expansion and self-directed wheat avoidance, though dairy-free alternatives represent the fastest-growing margin pool as oat, pea, and coconut milk formulations displace traditional dairy inclusions. Nut-free formats maintain premium positioning in school and childcare channels where zero-tolerance policies restrict packaged foods containing or processed near peanuts and tree nuts.
The FDA enforces Food Allergen Labeling and Consumer Protection Act requirements with sesame added as the ninth major allergen, while the USDA governs allergen-free claims in school meal programs through its National School Lunch Program specifications. Health Canada and the European Food Safety Authority coordinate on precautionary allergen labeling thresholds that determine whether "may contain" statements trigger reformulation or market withdrawal. Stakeholders must monitor evolving regulatory harmonization between the FDA and Codex Alimentarius Commission, as divergent allergen lists and threshold definitions complicate multinational product registration and inventory management.
Market Dynamics
Segregated allergen-free manufacturing capacity is tightening faster than ingredient supply, forcing brands to secure dedicated production lines through multi-year facility partnerships or captive build-outs.
Growth Catalysts
- FDA Food Allergen Labeling and Consumer Protection Act:The sesame addition as the ninth major allergen mandates label reformulation across US distribution, expanding the addressable population for certified sesame-free products.
- School nutrition procurement:Zero-tolerance nut policies in North American K-12 meal programs are converting institutional volume toward validated nut-free supply chains with documented cleaning protocols.
- Pea protein extraction:Advances in flavor-masking technology for legume bases are unlocking dairy-free formulations that match mouthfeel benchmarks previously exclusive to milk powders.
Market Restraints
- Oat milk input volatility:Scandinavian oat harvest fluctuations and malting-grade competition are compressing margins for dairy-alternative snack coatings and inclusions.
- Single-source sunflower lecithin dependence:Eastern European processing concentration creates vulnerability for emulsifier supply in chocolate-based allergen-free products.
- Validated allergen testing throughput:Third-party laboratory capacity constraints for ELISA and PCR verification are extending batch-release timelines beyond retail shelf-life requirements.
Strategic Opportunities
- Brazil ANVISA harmonization:Alignment with Codex Alimentarius precautionary labeling thresholds would streamline multinational registration for brands entering Mercosur markets.
- Direct-to-school subscription channels:Curated lunchbox delivery bypasses retail slotting fees while capturing recurring revenue from time-constrained parents.
- Blockchain-enabled ingredient traceability:Integration with EU Green Deal farm-to-fork data standards differentiates supply chain transparency for premium-positioned clean-label lines.
Industry Challenges
- Sanitation validation specialist scarcity:Food safety engineers with expertise in allergen-specific cleaning verification command premium compensation, constraining facility expansion timelines.
- Co-manufacturer audit backlogs:BRCGS and SQF certification queues for dedicated allergen-free lines are delaying product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allergy-Free Snacks Market |
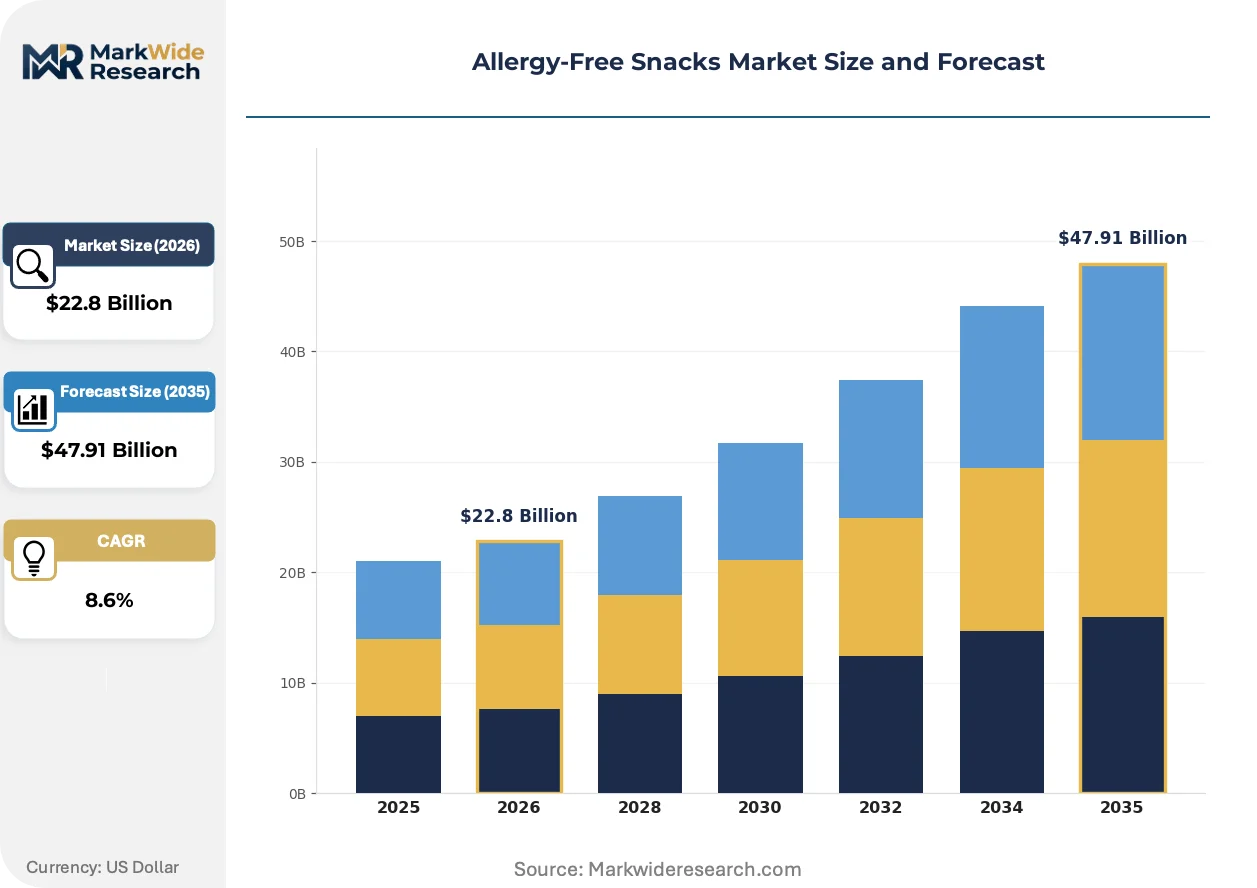
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut-Free, Dairy-Free, Gluten-Free, Vegan End User: Children, Adults, Athletes, Seniors Distribution Channel: Online Retailers, Supermarkets, Health Food Stores, Specialty Shops Packaging Type: Flexible Packaging, Rigid Containers, Pouches, Bulk Bins |
| Companies Covered | General Mills, Enjoy Life Foods, Nestlé, Free2b Foods, Made Good, Danone, Mondelēz International, Partake Foods, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allergy-Free Snacks Market Trends and Innovations
Formulation science and supply chain digitization are converging to compress development cycles while hardening safety guarantees for immunocompromised consumers.
Pulse-based protein isolates are overtaking soy and dairy derivatives in bar and bite applications. Pediatric allergist-recommended brands are adopting pea and lentil bases at the fastest pace. This protein rotation is compressing R&D timelines by eliminating flavor-masking iterations previously required for bitter off-notes.
EU Food Information for Consumers Regulation enforcement on precautionary labeling thresholds is forcing reformulation-or-withdrawal decisions. Manufacturers serving multiple member states face inventory fragmentation where identical SKUs require country-specific label variants. Free-from specialists are responding with single-formulation pan-European recipes that eliminate threshold ambiguity.
Subscription-based school lunch curation is displacing retail impulse purchasing for core allergen-free categories. Parents of children with multiple allergies are consolidating weekly procurement through verified-safe direct delivery. This channel pivot concentrates demand in Canada and the United States where childcare licensing mandates documented ingredient safety.
Allergy-Free Snacks Market Segmentation
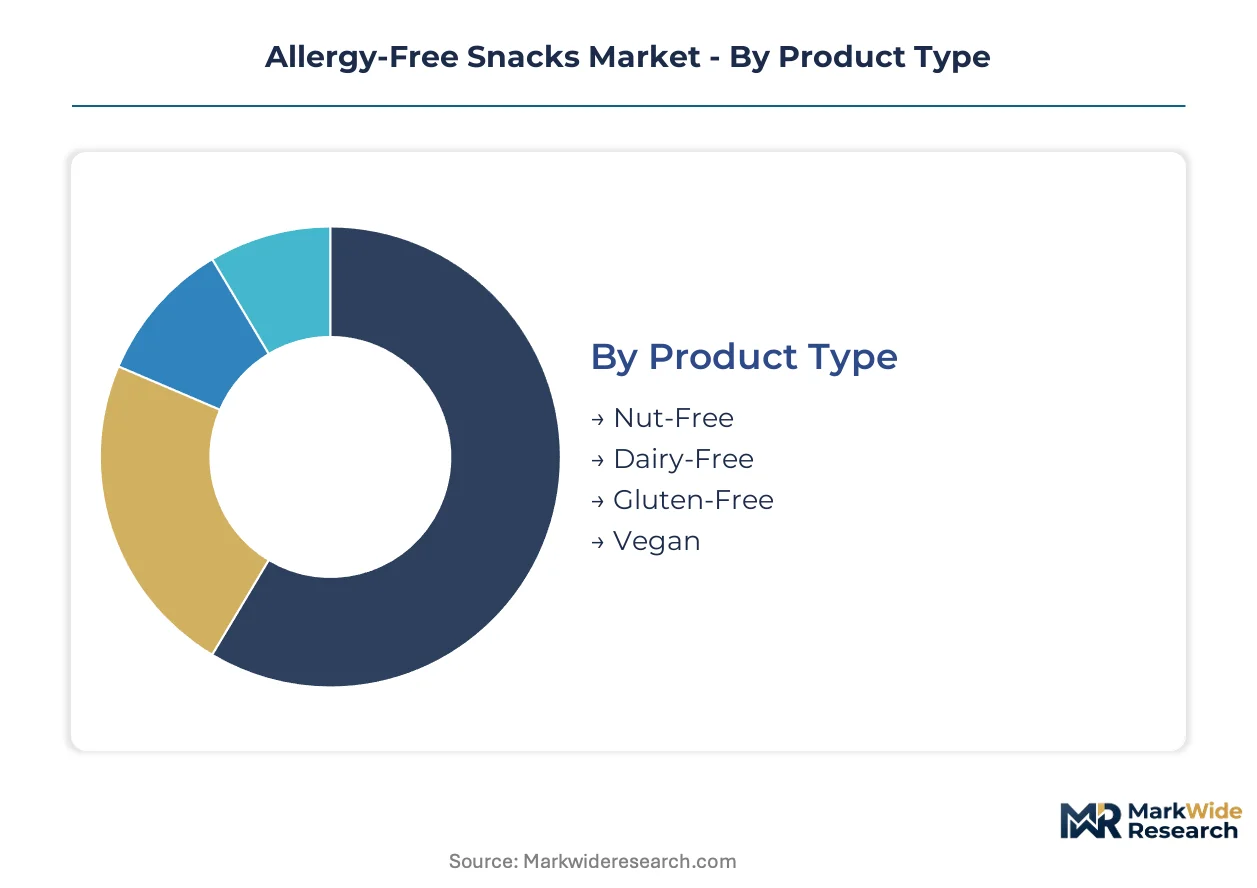
Segmentation in allergy-free snacks reflects divergent safety protocols, procurement channels, and consumption contexts. Manufacturers must align formulation rigor, packaging integrity, and distribution certification with distinct immunological risk profiles and purchasing behaviors across consumer life stages.
Product Type:
Standalone allergen elimination dominates premium positioning, while multi-allergen-free formulations embed across broader clean-label portfolios.
- Gluten-Free:Formulations exclude wheat, barley, and rye proteins through certified oat, rice, or legume bases. Celiac diagnosis expansion in the United States and self-directed wheat avoidance concentrate retail shelf space and institutional procurement in this segment.
- Dairy-Free:Oat, pea, and coconut milk derivatives displace milk powders in coatings and inclusions. This segment climbs fastest as flavor-masking technology resolves mouthfeel benchmarks previously exclusive to dairy bases.
- Nut-Free:Segregated manufacturing eliminates peanut and tree nut cross-contact risks entirely. Zero-tolerance policies in North American K-12 nutrition programs validate supply chains with documented cleaning protocols for this segment.
- Vegan:Excludes all animal derivatives including honey, gelatin, and dairy. Ethical consumption preferences in Western Europe expand addressable demand beyond strict allergen avoidance.
Gluten-free leads volumes today; dairy-free is gaining share fastest.
End User:
Procurement authority and consumption risk tolerance separate institutional buyers from individual decision-makers across life stages.
- Children:Pediatric allergist referrals and school nutrition mandates drive validated nut-free and multi-allergen-free procurement. Parents prioritize certified safety over price sensitivity in this segment.
- Adults:Self-directed elimination diets and diagnosed allergies sustain repeat purchase in retail and direct-to-consumer channels. Clean-label preference broadens addressable demand beyond clinical necessity.
- Athletes:Performance nutrition requirements intersect with allergen avoidance in protein bar and energy bite formats. Pea and lentil protein isolates dominate formulation for this segment.
- Seniors:Swallowing-safe textures and polypharmacy-related dietary restrictions shape product development. Soft-baked formats and single-serve portions concentrate demand here.
Children segment anchors institutional revenue; adults drive margin expansion through premium retail.
Distribution Channel:
Channel certification requirements and traceability standards fragment inventory management across verified and conventional retail pathways.
- Supermarkets:Dedicated free-from aisle placement and chain-level allergen protocols validate mass-market penetration. Slotting fees and planogram compliance constrain smaller manufacturers.
- Online Retailers:Subscription curation and direct-to-school delivery bypass retail intermediaries. Blockchain-enabled ingredient traceability differentiates premium-positioned lines in this channel.
- Health Food Stores:Staff-trained allergen counseling and local brand curation sustain premium positioning. Regional chain consolidation compresses independent store count.
- Specialty Shops:Allergist-recommended brands and pediatric nutrition focus dominate this channel. Limited geographic reach concentrates in urban clusters with elevated allergy prevalence.
Supermarkets capture volume concentration; online retailers expand most quickly through subscription models.
Packaging Type:
Barrier properties and portion control specifications align with consumption occasion and shelf-life requirements across channels.
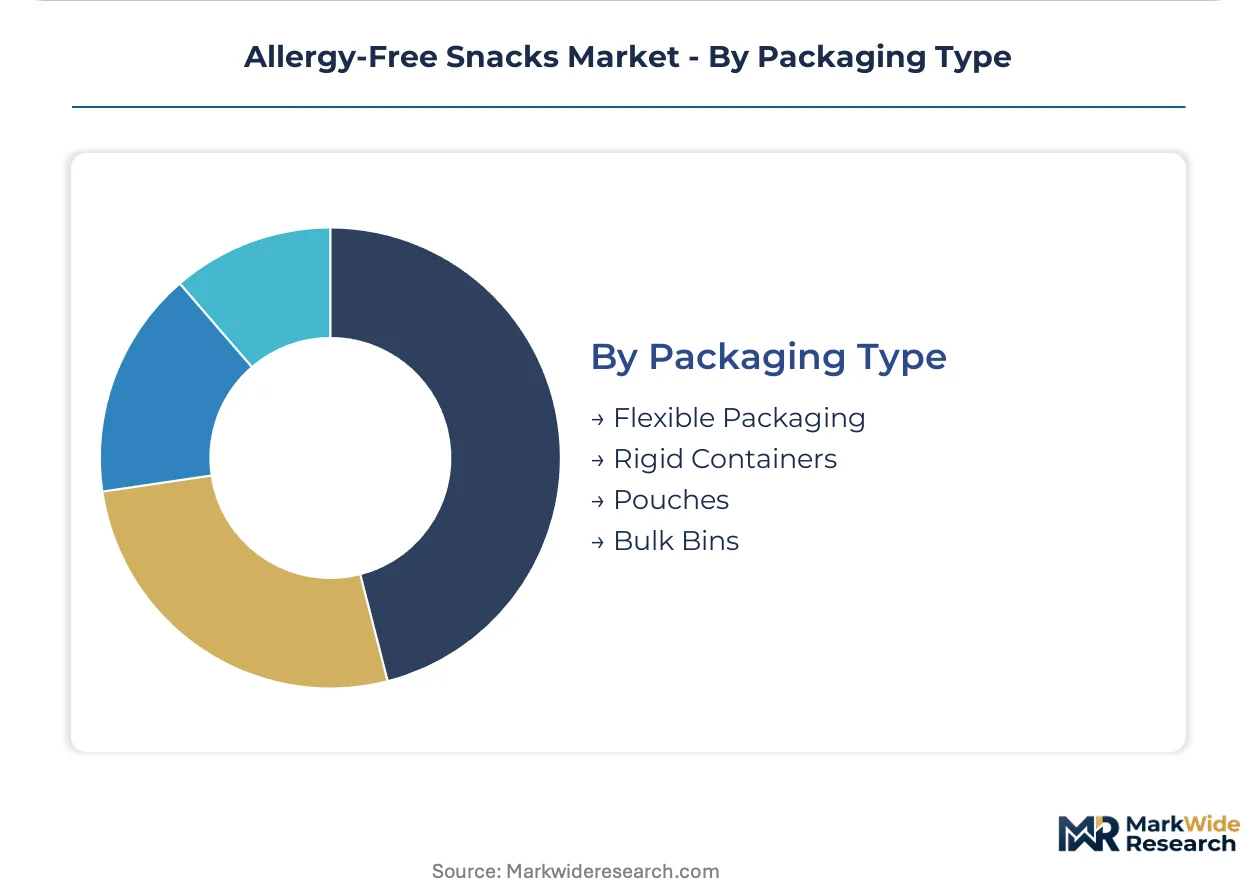
- Flexible Packaging:Multi-layer films with oxygen and moisture barriers extend shelf stability for baked and extruded snacks. Cost efficiency sustains dominance in mass-market distribution.
- Pouches:Resealable formats and portion-controlled servings align with school lunchbox and on-the-go consumption. Stand-up pouch adoption accelerates in premium children's segments.
- Rigid Containers:Crush protection and tamper-evident seals serve delicate formats and institutional bulk procurement. Higher material costs limit penetration in price-sensitive channels.
- Bulk Bins:Zero-waste retail and foodservice applications require validated allergen-free dispensing protocols. Cross-contamination risk constrains expansion in multi-allergen retail environments.
Flexible packaging leads unit volumes today; pouches show steepest expansion trajectory through school and childcare channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The allergy-free snacks industry traces its commercial origins to North American specialty bakeries that pioneered dedicated allergen-free manufacturing in the early 2000s, with Canadian and US firms establishing the segregated production protocols now standard across developed markets.
United States
Pediatric allergist referrals and school nutrition mandates drive validated nut-free procurement across K-12 districts. The FDA Food Allergen Labeling and Consumer Protection Act mandates sesame labeling reformulation, expanding certified sesame-free product lines. Chicago and Minneapolis anchor major dedicated allergen-free manufacturing clusters where multi-year facility partnerships secure production capacity.
Canada
Childcare licensing mandates documented ingredient safety, concentrating demand in Ontario and Quebec. Health Canada coordinates precautionary allergen labeling thresholds with EFSA, streamlining cross-border product registration. Toronto hosts the densest concentration of organic school-safe snack specialists serving North American lunchbox subscription channels.
Germany
Clean-label preference and celiac diagnosis expansion sustain gluten-free retail shelf space growth. The EU Food Information for Consumers Regulation enforces precautionary labeling thresholds that force reformulation-or-withdrawal decisions. Munich and Hamburg industrial zones concentrate dairy-alternative formulation expertise for oat and pea protein derivatives.
United Kingdom
Self-directed elimination diets and diagnosed allergies sustain repeat purchase in premium retail channels. The UK Food Standards Agency enforces Natasha's Law on prepacked for direct sale allergen labeling. London anchors specialist allergist-recommended brand distribution networks serving urban clusters with elevated allergy prevalence.
Australia
High pediatric food allergy rates and stringent school nut bans validate supply chains with documented cleaning protocols. Food Standards Australia New Zealand governs mandatory allergen declaration requirements for packaged foods. Melbourne and Sydney concentrate health food store networks with staff-trained allergen counseling capabilities.
Allergy-Free Snacks Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification rigor and dedicated facility investment, with validated allergen-free manufacturing capacity commanding 40-60% price premiums over conventional co-manufactured alternatives. The vendor base stratifies into three tiers: multinational CPG conglomerates with free-from portfolio extensions, dedicated allergen-free specialists with captive production assets, and emerging direct-to-consumer brands bypassing retail intermediaries. Dominant competitive moves include multi-year exclusive facility partnerships to lock segregated capacity and blockchain-enabled ingredient traceability integration to differentiate clean-label positioning.
Within the dedicated specialist tier, Enjoy Life Foods and Made Good exemplify archetypes of facility-based competitive moats, with the former representing North American dedicated allergen-free manufacturing scale and the latter anchoring organic school-safe format specialization. General Mills occupies a position bridging multinational CPG infrastructure with free-from portfolio diversification. These three firms collectively illustrate the strategic tension between scale economies and segregated production purity that defines competitive positioning in this category.
| Leading Market Players |
|---|
| General Mills |
| Enjoy Life Foods |
| Nestlé |
| Free2b Foods |
| Made Good |
| Danone |
| Mondelēz International |
| Partake Foods |
| Unilever |
| Others |
Pricing and Supply Chain Analysis
School nutrition procurement mandates across North American K-12 districts are compressing supplier qualification timelines, forcing manufacturers to absorb upfront certification costs that recast pricing structures across institutional and retail tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates dedicated allergen-free specialists from conventional co-manufactured alternatives. Price differentiation hinges on BRCGS/SQF certification grade and documented cleaning protocol rigor. Pricing pressure stems from oat milk input volatility and Scandinavian harvest fluctuations. Institutional buyers exhibit highest price sensitivity; pediatric allergist-recommended brands command lowest elasticity.
Supply Chain Analysis
Reverse-logistics flows for recalled allergen-contaminated batches require validated destruction protocols that extend supply chain cycle times. Ingredient sourcing concentrates in Canada, the United States, and Germany where segregated manufacturing clusters anchor production. Sunflower lecithin and pea protein isolates constitute critical input dependencies. Single-source Eastern European emulsifier processing creates tariff-exposure vulnerability. Distribution runs through direct-to-school subscription channels and verified retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal farm-to-fork compliance costs in Western Europe diverge from North American institutional procurement premiums.
For Market Incumbents: Extend dedicated facility partnerships to lock segregated capacity against emerging direct-to-consumer entrants. Deepen backward integration into oat and pea protein processing to offset Scandinavian harvest volatility. Certify additional production lines under BRCGS Allergen-Free standards before SQF audit queues lengthen further. For New Entrants and Emerging Players: Begin with curated lunchbox subscription channels in Ontario and Quebec where childcare licensing mandates documented ingredient safety. Target white-space in soft-baked senior formats where swallowing-safe textures remain underdeveloped. Pursue pediatric allergist endorsement as primary go-to-market credential. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing captive allergen-free production assets and established school nutrition procurement relationships. Five-to-ten year viability favors brands with blockchain-enabled traceability integration aligned to EU data standards. Monitor Health Canada-EFSA precautionary labeling threshold harmonization as regulatory convergence signal.| Strategic Initiative | Industry Significance |
|---|---|
| Dedicated Facility Partnership | Multi-year exclusive agreements secure scarce segregated production capacity ahead of competitor expansion. |
| Blockchain Traceability Integration | EU Green Deal farm-to-fork data compliance differentiates premium clean-label positioning for institutional buyers. |
| Direct-to-School Channel Launch | Subscription curation bypasses retail slotting fees while capturing recurring revenue from mandated procurement. |
| Pea Protein Backward Integration | In-house extraction capability insulates margin compression from legume base commodity volatility. |
| BRCGS Allergen-Free Certification | Third-party validation accelerates co-manufacturer qualification for zero-tolerance school nutrition programs. |
Research Methodology
Bottom-up institutional procurement modeling reconciled against top-down ingredient supply tracking forms the analytical core of this study. Primary interviews with school nutrition directors, co-manufacturer facility managers, pediatric allergists, retail category buyers, and third-party certification auditors combined with secondary validation from FDA enforcement reports, USDA National School Lunch Program specifications, Health Canada guidance documents, and EFSA scientific opinions. Triangulation across stakeholder perspectives and regulatory filings ensures data integrity.
Historical trendline analysis of dedicated allergen-free manufacturing capacity expansion and pediatric allergy diagnosis rates informed projection parameters across the analysis window. Segmentation dimensions modeled include product type, end-user life stage, distribution channel certification tier, and packaging format. CAGRs derived from facility partnership announcement tracking and school district procurement database analysis. Forecast inputs incorporated ELISA testing capacity constraints and oat harvest yield variability.
Several conditions sit outside the modeled scope, including unforeseen regulatory threshold revisions and catastrophic single-source ingredient supply disruptions. Forecasts reflect assumptions regarding sustained K-12 zero-tolerance policy enforcement and stable EU-US regulatory harmonization trajectory. Practitioners should monitor ANVISA-Codex alignment negotiations and sunflower lecithin processing concentration shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Roasted Snacks Market
Snacks
United States Snack Bar Market
Snacks
Dairy Protein Crisps Market
Snacks
Snack Food Packaging Market
Snacks
South America Cereal Bar Market
Snacks
Extruded Snacks Market
Snacks
Indonesia Snack Bar Market
Snacks
North America Fruit Snacks Market
Snacks
Tortilla Mix Market
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
Low Fat Granola Market
Snacks
Legume-Based Snacks Market
Snacks
Snack Pellets Market
Snacks
Protein Bars Market
Snacks
United Kingdom Snack Bar Market
Snacks
Energy Bar Market