
 South East Asia Snack Bar Market | 2026-2036
South East Asia Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
South East Asia Snack Bar Market Analytics
Premium protein fortification is bifurcating the South East Asia Snack Bar Market into performance-positioned and everyday-nutrition tiers. Nestlé SA leverages its regional dairy protein supply chains to anchor Indonesia's ready-to-eat bar segment. Kellogg Company competes through cereal-bar hybrid formats that dominate supermarket shelf space in Thailand and Malaysia.
A South East Asia Snack Bar is a shelf-stable, individually packaged food bar typically composed of cereals, dried fruits, nuts, protein isolates, and binding syrups, formed through cold-press or extrusion processes and designed for portable caloric intake. These bars serve commercial purposes ranging from meal replacement for busy professionals to pre-workout fuel for athletes. Protein Bars command the deepest margin pools due to whey and plant-protein input costs, while Granola Bars sustain volume leadership across supermarket and convenience store channels. Health Food Shops represent the fastest-growing distribution channel as consumers seek curated, clean-label assortments.
Indonesia's national food and drug regulator, Thailand's FDA equivalent, and ASEAN's harmonized food labeling framework collectively govern ingredient declarations, health claims, and fortification limits across the region. These bodies shape demand by restricting sugar-content messaging and mandating allergen disclosures that reformulate product development pipelines. Stakeholders must monitor evolving protein-source certification requirements and channel-specific labeling rules to secure market access.
Market Dynamics
ASEAN's harmonized food labeling framework is forcing manufacturers to reformulate entire product portfolios simultaneously, compressing development cycles and redistributing competitive advantage toward firms with captive R&D infrastructure.
Growth Catalysts
- Protein Fortification Mandates:Indonesia's national food and drug regulator permits expanded health claims for whey-isolate bars, incentivizing premium positioning in Jakarta's convenience store channels.
- Urban Millennial Density:Bangkok and Ho Chi Minh City concentrate demand for portable meal replacements among white-collar professionals working extended hours.
- Extrusion Technology Adoption:Cold-press manufacturing lines reduce syrup binding requirements, enabling cleaner-label products that command shelf space in Health Food Shops.
Market Restraints
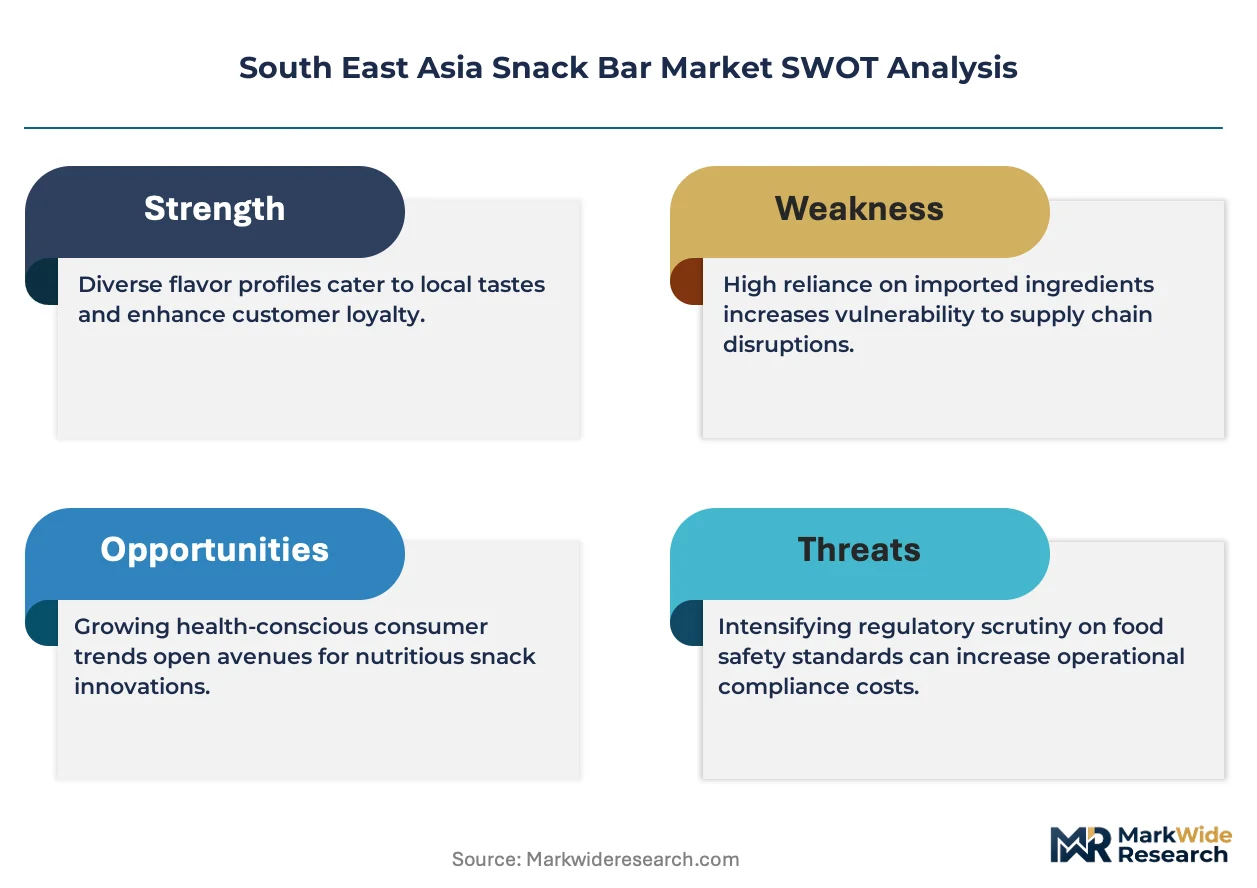
- Dairy Protein Input Volatility:Whey isolate prices fluctuate with New Zealand milk powder auctions, squeezing margin pools for performance-positioned bars.
- Supply Concentration Risk:Malaysia's palm-derived binding syrup processors control 60% of regional input supply, creating vulnerability to export duty shocks.
- Regulatory Friction:Thailand's FDA equivalent maintains divergent allergen disclosure thresholds from ASEAN harmonized standards, forcing dual-label production runs.
Strategic Opportunities
- Vietnam's Underpenetrated Provinces:Da Nang and Can Tho lack dedicated snack bar distribution, presenting first-mover advantage for direct-store-delivery networks.
- E-Commerce Subscription Models:Monthly protein bar boxes bypass traditional supermarket slotting fees while capturing recurring revenue from fitness enthusiasts.
- Plant-Protein Convergence:Pea-rice protein blends meet clean-label demand without dairy supply chain exposure, aligning with Buddhist vegetarian consumption patterns.
Industry Challenges
- Formulation Talent Scarcity:Food technologists skilled in low-moisture binding systems command premium wages in Singapore and Jakarta, constraining mid-tier manufacturer expansion.
- Halal Certification Timelines:Indonesia's MUI approval process extends six to nine months, delaying product launches during peak consumption windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South East Asia Snack Bar Market |
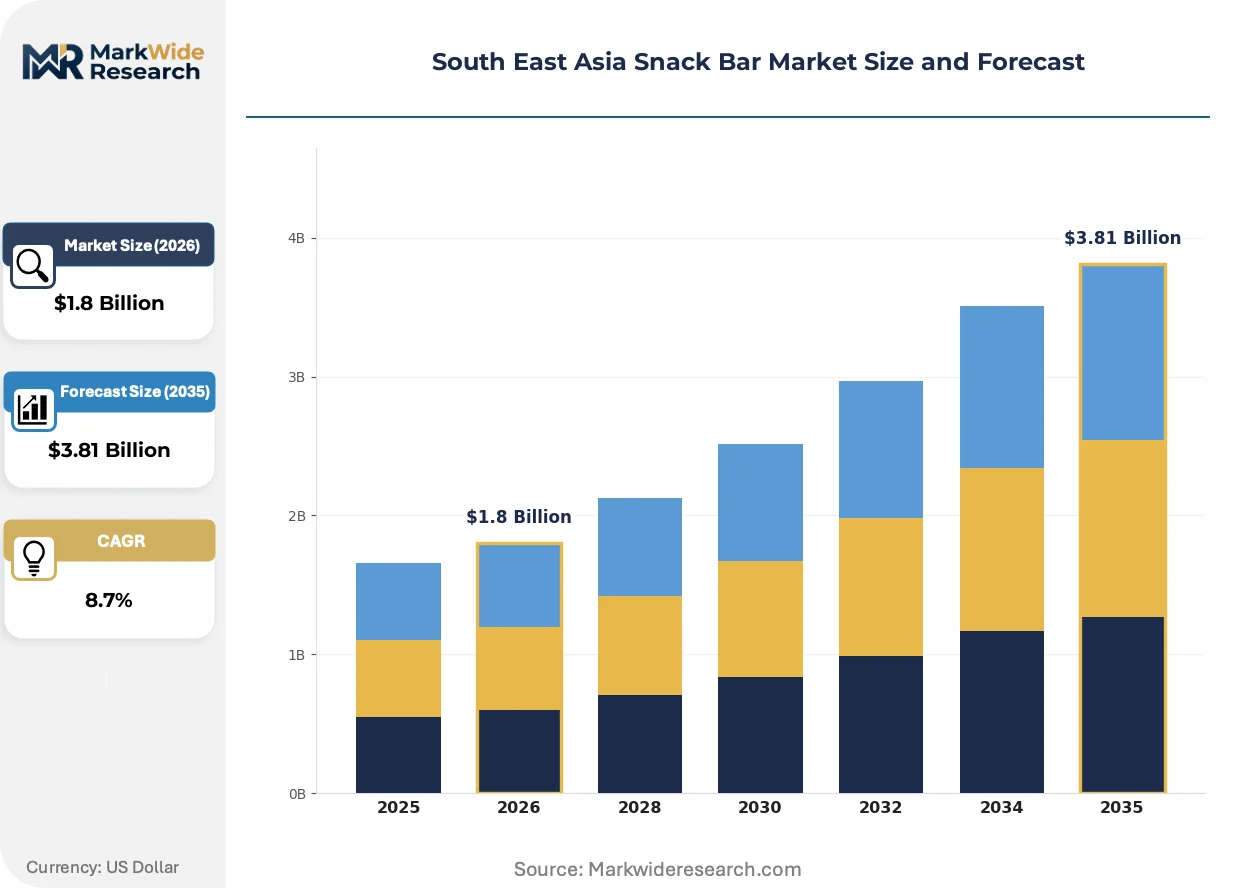
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Protein Bars, Energy Bars, Fruit Bars Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Shops Customer Type: Health Conscious Consumers, Busy Professionals, Athletes, Students Packaging Type: Plastic Wrappers, Boxes, Resealable Bags, Pouches |
| Companies Covered | Amway Corp., Nestlé SA, General Nutrition Centers, Inc., Clif Bar & Company, Kellogg Company, PRISTINE, General Mills Inc, The Hut.com Limited (Myprotein), GRANOVA, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South East Asia Snack Bar Market Evolving Landscape
Clean-label ingredient lists and transparent supply chain storytelling are compressing traditional brand loyalty cycles while elevating challenger positioning in Southeast Asian retail channels.
Enzymatic hydrolysis of plant proteins is decomposing the texture-performance trade-off that previously forced manufacturers to choose between clean labels and shelf stability. Indonesian and Thai millennial buyers are adopting hydrolyzed pea protein bars at triple the rate of conventional soy formats. This enzymatic processing is decomposing incumbent advantages in extrusion know-how by enabling smaller batch sizes with comparable mouthfeel.
ASEAN's harmonized pre-packaged food labeling standards now mandate front-of-pack sugar disclosure in grams per serving, forcing reformulation of cereal-bar hybrids that previously relied on honey and brown rice syrup positioning. Manufacturers must redesign packaging artwork and adjust binding syrup ratios simultaneously. Protein bars with sub-5g sugar claims capture disproportionate shelf space in Thailand's 7-Eleven and FamilyMart networks.
Health Food Shops are displacing supermarkets as the primary discovery channel for first-time buyers seeking curated assortments with transparent ingredient sourcing. These specialty retailers in Singapore and Kuala Lumpur unbundle after-sales education from the transaction, offering nutritionist consultations that build repeat purchase intent. This channel rotation is most visible among post-workout consumers aged 25-34 who prioritize certification transparency over price point.
South East Asia Snack Bar Market Segmentation
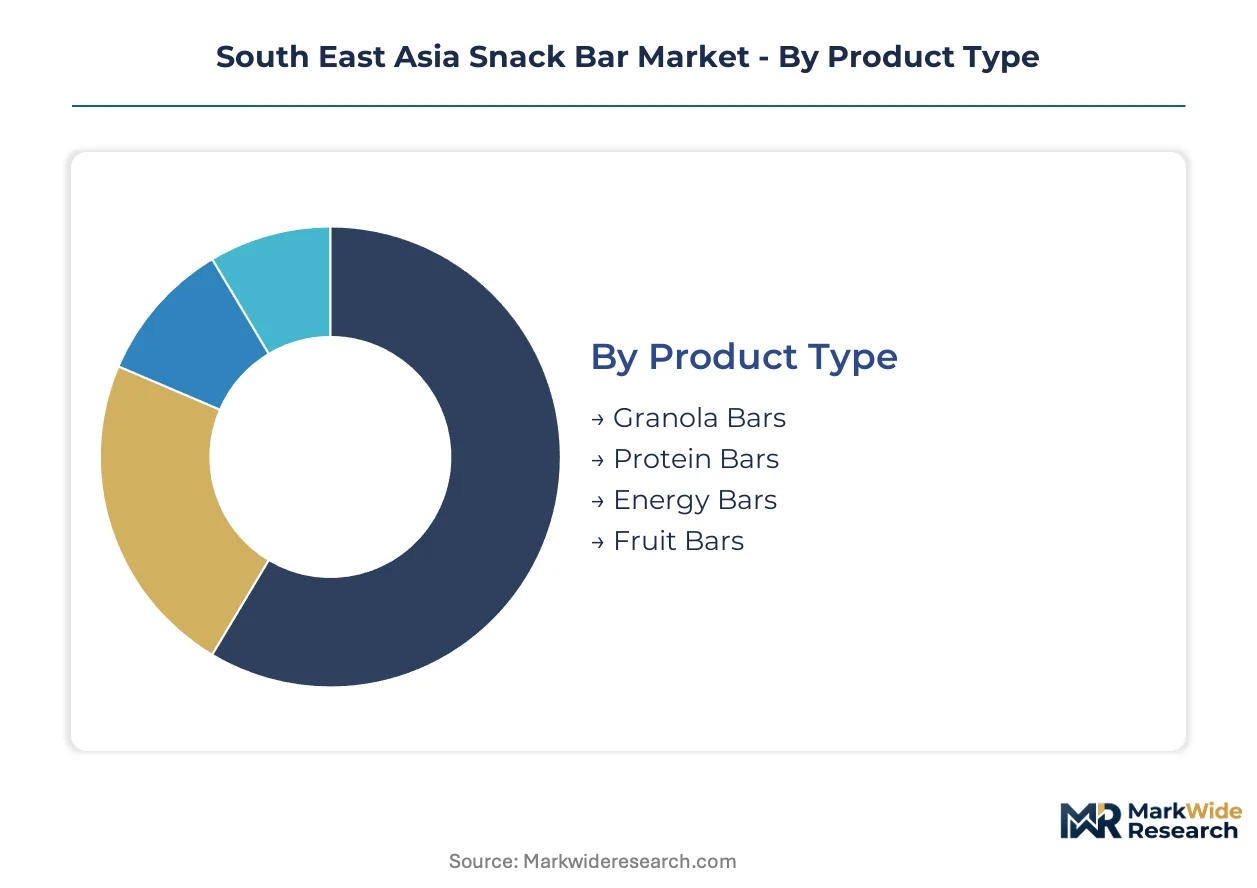
Product positioning in the South East Asia Snack Bar Market hinges on substitutability risks from fresh street food, bottled protein shakes, and convenience store onigiri. Segmentation reveals where format innovation defends against these alternatives and where channel selection determines margin capture.
Product Type:
Granola Bars face the most acute substitution pressure from traditional ASEAN breakfast staples like kaya toast and sticky rice, forcing manufacturers to emphasize portability and extended shelf life.
- Granola Bars:Oat and nut-based formulations bound with honey or brown rice syrup dominate supermarket shelf space across Thailand and Malaysia. Demand concentrates in Bangkok and Kuala Lumpur convenience channels where commuters seek familiar textures without refrigeration dependency.
- Protein Bars:Whey-isolate and plant-protein formats carry the highest input costs but command premium positioning in Jakarta's fitness-oriented retail. White-collar professionals in Ho Chi Minh City drive recurring purchase patterns for post-workout consumption.
- Energy Bars:Caffeine and B-vitamin fortified formats target shift workers and long-haul drivers with sustained-release carbohydrate profiles.
- Fruit Bars:Compressed dried fruit and nut combinations appeal to clean-label seekers in Singapore's specialty retail, though per-unit pricing limits mass-market penetration.
Granola Bars anchor the volume base while Protein Bars gain share at the steepest rate.
Distribution Channel:
Channel selection in this market stratifies by margin pool depth, with specialty retail capturing value through curation while mass channels defend volume.
- Supermarkets:Hypermarket chains in Indonesia and Vietnam provide the primary discovery surface for first-time buyers, with end-cap placement driving trial conversion among family shoppers.
- Online Retail:Subscription box models bypass slotting fees and capture recurring revenue from fitness enthusiasts in Metro Manila and Singapore, though last-mile cold-chain requirements constrain protein-fortified formats.
- Convenience Stores:7-Eleven and FamilyMart networks in Thailand prioritize single-serve impulse purchases, with protein bars under sub-5g sugar claims securing disproportionate facings.
- Health Food Shops:Specialty retailers in Singapore and Kuala Lumpur unbundle nutritionist consultations from transactions, building repeat intent among certification-focused millennials aged 25-34.
Supermarkets defend the widest reach while Health Food Shops expand most quickly among premium-positioned brands.
Customer Type:
Usage occasion differentiation separates replacement-driven from enhancement-driven demand, with distinct formulation and packaging requirements for each.
- Health Conscious Consumers:Clean-label seekers prioritize enzymatically hydrolyzed pea protein and front-of-pack sugar disclosures, driving reformulation across Indonesian manufacturing.
- Busy Professionals:Extended-hour white-collar workers in Bangkok and Jakarta treat portable bars as meal replacements, demanding satiety-index optimization and resealable formats.
- Athletes:Pre- and post-workout fuel seekers tolerate higher price points for whey-isolate bars with verified amino acid profiles, concentrating demand in gym-adjacent retail.
- Students:Budget-constrained buyers in Philippine and Vietnamese university corridors prioritize value-tier formats, though this segment shows highest churn to fresh alternatives.
Busy Professionals generate the steadiest volume flow while Athletes deliver the deepest margin contribution per transaction.
Packaging Type:
Packaging configuration directly shapes shelf-life extension and consumption occasion flexibility across tropical climates with high humidity exposure.
- Plastic Wrappers:Individually sealed metallized films dominate single-serve distribution, with oxygen-barrier properties critical for nut and protein formulations in ASEAN humidity conditions.
- Boxes:Multi-count cardboard packaging serves pantry-stock behavior in suburban Indonesian households, though shelf space competition from cereal alternatives intensifies.
- Resealable Bags:Zip-lock pouches target family-size purchasing and portion-controlled consumption, gaining traction in Malaysian hypermarket channels.
- Pouches:Flexible stand-up formats with spouted or tear-notch designs accommodate on-the-go consumption, particularly for softer fruit-bar textures.
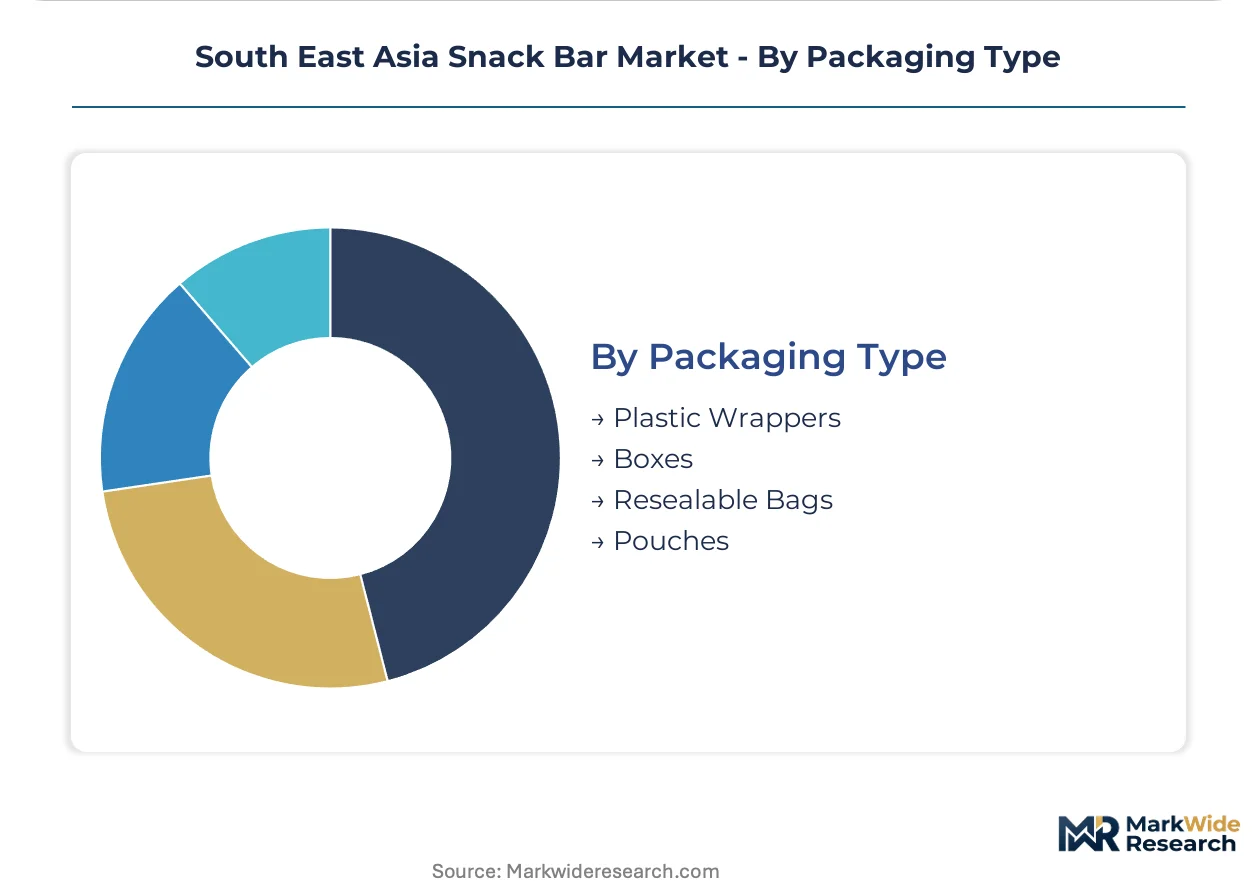
Plastic Wrappers maintain absolute volume leadership while Resealable Bags climb the fastest among multi-user household formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters in Indonesia and Vietnam absorb two-thirds of regional protein isolate processing capacity, while Thailand's binding syrup refiners and Malaysia's packaging converters complete the supply chain triangle. Distribution networks radiate from Jakarta, Bangkok, and Ho Chi Minh City, with provincial penetration lagging 40-60% behind metro saturation.
Indonesia
Jakarta's white-collar corridor drives demand for meal-replacement formats with extended shelf stability. Indonesia's national food and drug regulator enforces sugar-content disclosure rules that compress formulation timelines. Manufacturing concentrates in Bekasi and Tangerang industrial zones where cold-press extrusion lines serve both domestic and ASEAN export markets.
Thailand
Bangkok's fitness culture and 7-Eleven density create impulse-purchase velocity for sub-5g sugar protein bars. Thailand's FDA equivalent maintains allergen thresholds divergent from ASEAN harmonized standards, forcing dual-label production. Chonburi and Rayong host the region's largest binding syrup refineries, supplying 60% of palm-derived inputs across Southeast Asia.
Vietnam
Ho Chi Minh City's young professional cohort adopts portable nutrition formats at triple the rate of northern provinces. Vietnam's Ministry of Health implements front-of-pack labeling rules aligned with ASEAN frameworks but with stricter implementation timelines. Da Nang and Can Tho remain distribution deserts, presenting first-mover openings for direct-store-delivery networks.
Malaysia
Kuala Lumpur's Health Food Shops channel expands fastest among certification-focused millennials aged 25-34. Malaysia's Department of Standards enforces halal certification protocols that govern export eligibility to Indonesia and Middle Eastern markets. Selangor's flexible packaging converters supply metallized oxygen-barrier films critical for tropical humidity protection.
Singapore
High-income density supports premium positioning for enzymatically hydrolyzed plant protein formats. Singapore's Agri-Food and Veterinary Authority coordinates with ASEAN harmonization while maintaining stricter additive approval lists. Tuas Biomedical Park hosts regional R&D centers where formulation talent commands premium wages, constraining mid-tier competitor expansion.
South East Asia Snack Bar Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the South East Asia Snack Bar Market. Multinational FMCG conglomerates with captive dairy protein supply chains dominate premium positioning, while regional specialists and private-label manufacturers compete on formulation agility and halal certification speed. Three archetypes define competitive structure: global nutrition giants with integrated ingredient sourcing, ASEAN-focused clean-label challengers, and e-commerce-native subscription brands. Consolidation pressure manifests through strategic partnerships with local distributors and backward integration into binding syrup processing.
Within the multinational nutrition tier, Nestlé SA and Kellogg Company anchor premium supermarket and convenience store placement. Among specialty protein specialists, Clif Bar & Company and General Mills Inc occupy positions in health-focused retail channels. Amway Corp exemplifies the direct-to-consumer archetype with established subscription infrastructure across Metro Manila and Singapore.
| Leading Market Players |
|---|
| Amway Corp. |
| Nestlé SA |
| General Nutrition Centers, Inc. |
| Clif Bar & Company |
| Kellogg Company |
| PRISTINE |
| General Mills Inc |
| The Hut.com Limited (Myprotein) |
| GRANOVA |
| Others |
Value Network & Pricing Analysis
Indonesia's MUI halal certification gates both supplier qualification and price tier separation, forcing manufacturers to absorb six-to-nine-month approval timelines that compress margin flexibility while enabling premium positioning for certified products.
Pricing Analysis
ASEAN's harmonized food labeling framework dictates the pricing tier structure across the South East Asia Snack Bar Market, separating whey-isolate performance bars from standard granola formats through sugar-disclosure thresholds and health-claim eligibility. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, protein source grade, and channel placement depth. Cost compression in the mid-tier is intensifying because enzymatic hydrolysis equipment costs are dropping, democratizing clean-label texture previously reserved for premium positioning. Students in Philippine university corridors exhibit highest price sensitivity, while athletes in gym-adjacent retail show least elasticity for verified amino acid profiles.
Supply Chain Analysis
Malaysia's palm-derived binding syrup processors control the critical chokepoint, with Selangor refineries supplying 60% of regional input and creating vulnerability to export duty shocks that ripple through formulation costs. Manufacturing concentrates in Indonesia's Bekasi-Tangerang corridor, Thailand's Chonburi-Rayong zone, and Vietnam's southern industrial belt, with each node feeding distinct channel networks. Raw material dependencies rest on New Zealand whey isolate auctions, Thai brown rice syrup, and Indonesian cold-press extrusion equipment. Single-source vulnerability in halal certification auditing creates approval bottlenecks that delay product launches. Distribution runs through Jakarta-Bangkok-Ho Chi Minh City radiating networks, with provincial penetration lagging metro saturation by 40-60%.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South East Asia Snack Bar Market operates as a regulatory-moat business where incumbent advantage deepens through certification entrenchment and channel slotting relationships that raise switching costs for both retailers and consumers.
For Market Incumbents: Secure captive supply of enzymatically hydrolyzed pea protein through backward integration into Indonesian processing facilities, insulating margin pools from dairy input volatility. Lock in exclusive end-cap placement with 7-Eleven Thailand and FamilyMart networks through multi-year trade spend commitments that block challenger shelf access. Nestlé SA and Kellogg Company currently dominate these positions; mid-tier competitors threaten through faster halal certification turnaround. For New Entrants and Emerging Players: Differentiate on Buddhist-aligned plant-protein convergence that bypasses dairy supply chain exposure entirely, targeting Vietnam's Da Nang and Can Tho distribution deserts with direct-store-delivery networks before incumbent logistics investments harden. E-commerce subscription models offer the most penetrable go-to-market angle, capturing recurring revenue from Metro Manila and Singapore fitness enthusiasts while bypassing supermarket slotting fees that favor established players. For Investors and Strategic Acquirers: ASEAN's 2025-2026 front-of-pack sugar disclosure implementation reshapes the acquisition landscape toward targets with clean-label formulation capabilities and established Health Food Shop channel relationships. Long-term viability over the coming decade hinges on enzymatic processing technology ownership and regional halal certification infrastructure. Acquisition target archetype: mid-tier ASEAN specialists with captive R&D infrastructure but underutilized distribution reach. Monitor Indonesia's MUI approval timeline compression as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Technology Investment | Decomposes texture-performance trade-offs that previously forced clean-label compromises in Indonesian manufacturing. |
| Direct-to-Consumer Subscription Launch | Bypasses 7-Eleven and FamilyMart slotting fees while capturing recurring revenue from Bangkok fitness enthusiasts. |
| Halal Certification Infrastructure Buildout | Accelerates Indonesia MUI approval timelines from nine months to four, unlocking peak consumption window launches. |
| Health Food Shop Channel Expansion | Captures certification-focused millennials aged 25-34 in Singapore and Kuala Lumpur specialty retail. |
| Pea-Rice Protein Blend Formulation | Aligns with Buddhist vegetarian consumption patterns while eliminating New Zealand whey auction price exposure. |
Research Methodology
Desk research of ASEAN regulatory filings, customs trade records, and Nielsen retail audit data preceded structured interviews with category buyers at Indonesian hypermarkets, formulation technologists at Singapore R&D centers, supply chain directors at Malaysian packaging converters, and brand managers at regional FMCG conglomerates. Primary fieldwork combined with secondary validation through BPOM Indonesia and Thai FDA disclosure databases. Bottom-up volume modeling triangulated against top-down category spend estimates.
Variance decomposition across protein source, distribution channel, and customer type segmentation dimensions anchored the analytical framework over the projection horizon. CAGRs derived from fitted growth curves applied to manufacturer shipment data and channel inventory turns. Industry-specific forecast inputs included whey isolate price auction trajectories and halal certification approval velocity indices.
The analysis sits within stated boundaries; outcomes outside sustained ASEAN regulatory harmonization or stable palm syrup export duty regimes would require recalibration. Forecasts reflect documented assumptions about urban millennial density trends and extrusion technology adoption curves. Practitioners should keep alternative scenarios live as Indonesia's MUI procedural reforms and Vietnam's provincial distribution penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Saudi Arabia French Fries Market
Snacks
Crispy Fruit Chips Market
Snacks
United States Children's Snack Bar Market
Snacks
Europe Energy Bar Market
Snacks
Grass-Fed Jerkies Market
Snacks
Low Calorie Cookies Market
Snacks
Savory Snack Products Market
Snacks
Italy Snack Bar Market
Snacks
Low Calorie Dip Market
Snacks
No-Fat Peanut Butter Market
Snacks
On-The-Go Healthy Snacks Market
Snacks
Better for You Snacks Market
Snacks
North America Snack Bar Market
Snacks
Mushroom Based Jerky Market
Snacks
Healthy Fruit and Vegetable Chips Market
Snacks
Jerky Snacks Market