
 Plant-Based Bars Market | 2026-2036
Plant-Based Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Bars Market Intelligence
Capital-intensity divergence between co-manufacturing-dependent entrants and in-house production veterans is collapsing as ingredient costs and certification requirements escalate. Barebells leverages its European manufacturing footprint to sustain margin control across protein bar formulations. Orgain differentiates through R&D intensity in organic plant protein sourcing, while General Mills Inc anchors its position via brand strength and supermarket channel control.
Plant-based bars are shelf-stable food products formulated with protein isolates, nut butters, or grain bases, typically containing 10-20 grams of protein per serving and manufactured through cold-press or extrusion processes to preserve nutritional integrity; they serve commercial purposes as meal replacements, post-workout recovery tools, and portable nutrition for active consumers. Protein bars lead the product type landscape due to entrenched gym and athletic channel penetration, while gluten-free ingredient formulations command premium shelf positioning as allergen sensitivity reshapes purchasing criteria. Online retailers represent the fastest-growing distribution channel as direct-to-consumer subscription models capture recurring revenue from fitness enthusiasts and health-conscious consumers.
The FDA governs nutrition labeling and health claims for plant-based bars sold in the United States, while the EU Green Deal and REACH framework in Europe impose stringent requirements on sustainable ingredient sourcing and chemical transparency across supply chains. EFSA standards further shape product formulation decisions by defining acceptable protein quality metrics and additive thresholds for bars marketed with nutritional claims. Stakeholders must monitor evolving clean-label certification demands and regional divergence in protein fortification rules to align portfolio investments with compliance trajectories.
Market Dynamics
Ingredient certification requirements under the EU Green Deal and F-Gas Regulation are compressing margins for co-manufacturing-dependent entrants while rewarding in-house production veterans with captive supply chains and established clean-label credentials.
Growth Catalysts
- Fitness channel penetration:Gym and athletic retail networks in Germany are expanding shelf space for high-protein formulations as post-workout recovery snacking becomes routine among amateur athletes.
- REACH framework compliance:Chemical transparency mandates across Europe are accelerating reformulation investments that favor established players with dedicated regulatory affairs teams and documented supply chain audits.
- Cold-press manufacturing:This nutrient-preservation process is enabling premium positioning for bars targeting consumers seeking minimally processed alternatives to extruded competitors.
Market Restraints
- Organic pea protein cost volatility:Sourcing concentration in Canadian and Ukrainian growing regions exposes formulators to weather-driven input price swings and contract renegotiation cycles.
- EFSA additive thresholds:Strict caps on emulsifiers and texture agents limit product development flexibility for brands seeking texture parity with dairy-based protein bars.
- Almond butter supply risk:California drought patterns and water allocation disputes are constraining reliable access to this core binding ingredient for allergen-free formulations.
Strategic Opportunities
- Direct-to-consumer subscription models:Recurring revenue capture through personalized nutrition algorithms is opening defensible positions against supermarket channel commoditization.
- CSRD-aligned carbon labeling:Early adoption of scope-three emissions disclosure creates differentiation among climate-conscious buyers in Nordic retail channels.
- Senior nutrition applications:Texture-softened, high-protein formats for sarcopenia prevention represent an underserved demographic with distinct formulation and packaging requirements.
Industry Challenges
- Clean-label certification timelines:Organic and non-GMO verification processes stretch 12-18 months, delaying product launches and freezing capital in inventory.
- Extrusion technician scarcity:Specialized knowledge of low-moisture protein processing commands premium wages and constrains capacity expansion for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Bars Market |
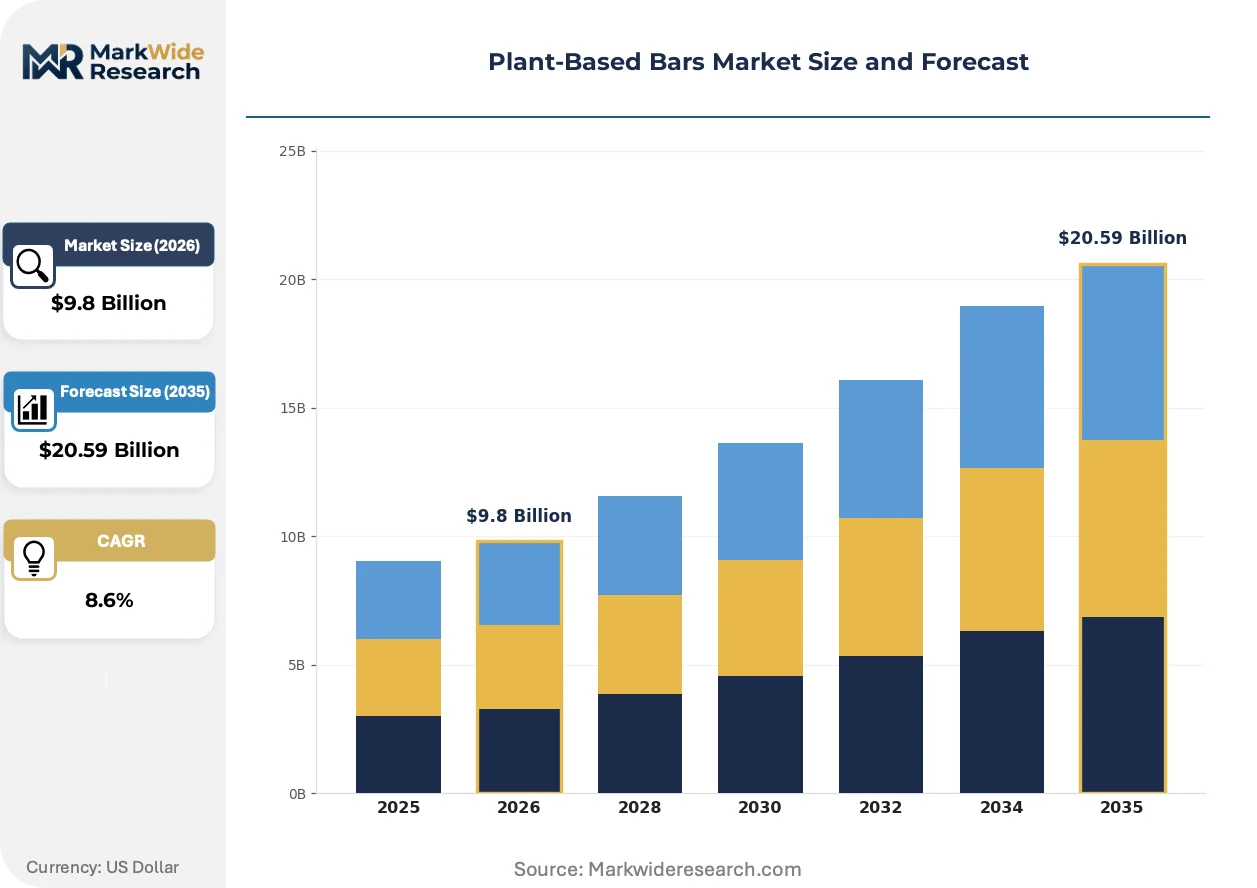
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.59 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut Bars, Protein Bars, Snack Bars, Energy Bars Ingredient Type: Protein Sources, Fiber Rich, Nut-Free, Gluten-Free Distribution Channel: Online Retailers, Health Stores, Supermarkets, Specialty Shops Consumer Category: Vegans, Fitness Enthusiasts, Health-Conscious Consumers, Athletes |
| Companies Covered | Barebells, Orgain, General Mills Inc, Rise Bar, No Cow, GoMacro, Simply Protein, NuGo Nutrition, PROBAR, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Bars Market Strategic Shifts & Innovations
Reformulation priorities are converging on texture optimization and carbon footprint reduction as regulatory disclosure requirements harden and athletic consumers reject chalky mouthfeel compromises.
Fermented protein isolates from fungal biomass are fragmenting traditional soy and pea dominance by delivering complete amino acid profiles with lower agricultural land intensity. Boutique fitness studios and CrossFit affiliates are piloting these ingredients in limited-edition releases. The technology is fragmenting procurement patterns as brands diversify supplier bases away from commodity legume markets.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in industrial refrigeration, forcing cold-chain logistics providers serving plant-based bar warehouses to retrofit equipment or switch to CO2-based systems. This imposes capital burdens on regional distributors with thin margins. German cold-storage operators are responding fastest through pooled equipment upgrade programs subsidized by federal efficiency grants.
Subscription-based replenishment is displacing impulse grocery purchases among committed fitness enthusiasts who prioritize convenience and flavor consistency over in-store discovery. Athletic wear retailers with existing membership ecosystems are bundling nutrition boxes with apparel purchases. This shift concentrates most visibly in urban UK and German markets where gym density supports same-day delivery economics.
Plant-Based Bars Market Segmentation
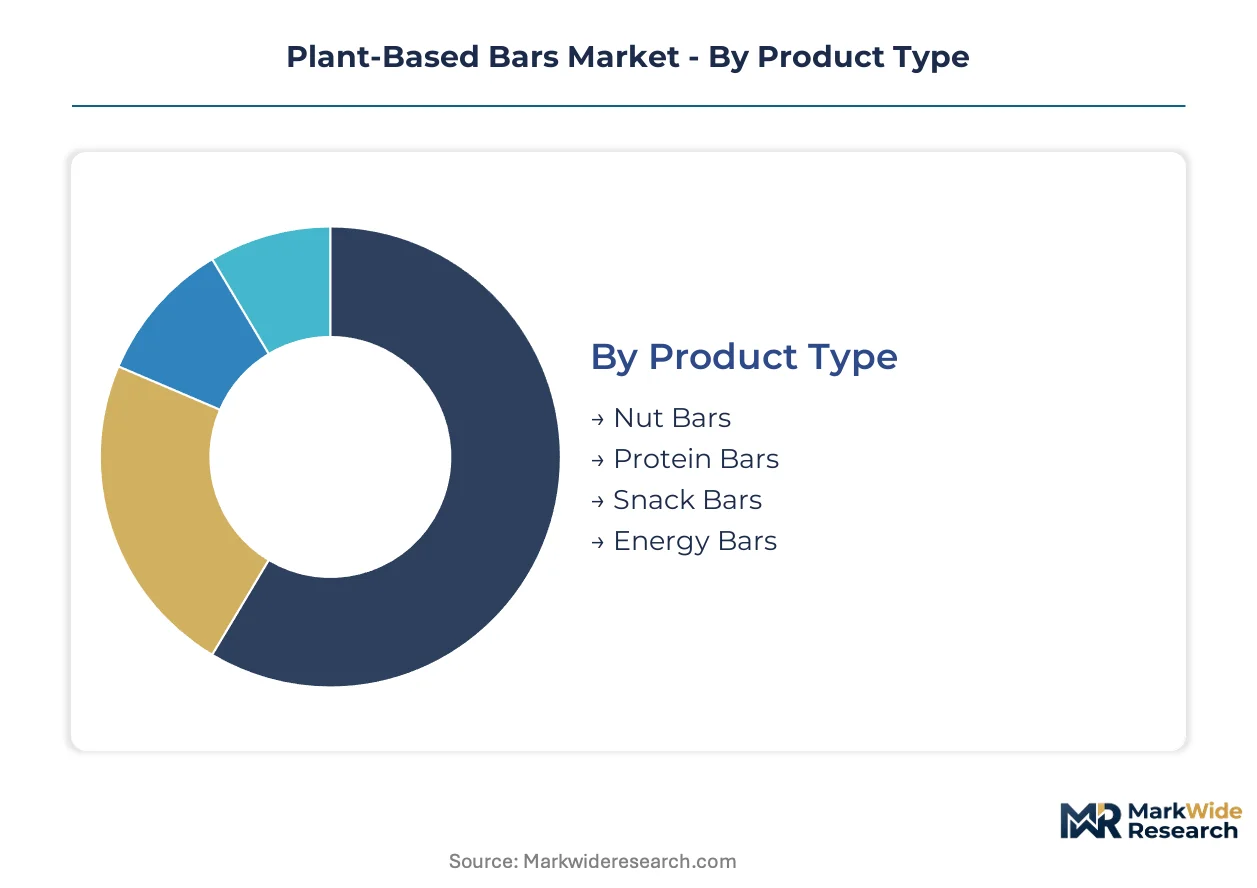
Segmentation in plant-based bars reveals where formulation investments concentrate and which buyer profiles command premium shelf positioning. Understanding these divides exposes where substitute threats from conventional dairy bars and whole-food alternatives exert the strongest pressure.
Product Type:
Protein bars face the most intense substitution pressure from dairy-based alternatives, forcing plant-based variants to differentiate through texture innovation and clean-label positioning.
- Protein Bars:Formulations deliver 10-20 grams of protein per serving through pea, soy, or rice isolates, manufactured via cold-press or extrusion processes. Demand concentrates in German gym networks where post-workout recovery snacking has become routine among amateur athletes, though EFSA additive thresholds constrain texture parity with dairy competitors.
- Energy Bars:These products emphasize rapid glycogen replenishment through date, oat, and syrup bases rather than protein density. UK boutique fitness studios and CrossFit affiliates are piloting limited-edition releases with fermented fungal biomass to diversify beyond commodity legume inputs.
- Nut Bars:Almond, cashew, and peanut butter formulations serve as binding agents in minimally processed formats.
- Snack Bars:Lower-protein options targeting casual consumption occasions with grain and fruit bases.
Protein bars retain volume leadership; energy bars hold the steepest expansion curve through athletic channel penetration.
Ingredient Type:
Cost tier stratification separates premium-positioned allergen-free formulations from commodity protein concentrates competing on price per gram.
- Gluten-Free:Oat, rice, and pseudocereal bases command premium shelf positioning as celiac sensitivity and wheat avoidance reshape purchasing criteria across European supermarkets. German retailers allocate dedicated planogram space, though organic certification timelines stretch 12-18 months and freeze working capital.
- Protein Sources:Pea and soy isolates dominate commodity supply, with sourcing concentration in Canadian and Ukrainian growing regions exposing formulators to weather-driven price volatility. Fermented fungal proteins are fragmenting procurement patterns as brands seek lower agricultural land intensity.
- Nut-Free:Sunflower seed and pumpkin seed butter alternatives serve school-safe and allergen-sensitive segments.
- Fiber Rich:Chicory root, inulin, and resistant starch additions target digestive health positioning.
Gluten-free formulations capture the highest margin tier; protein sources maintain the broadest volume base.
Distribution Channel:
Volume concentration in supermarket chains is accelerating channel commoditization, forcing brands to defend margin through direct-to-consumer subscription economics.
- Online Retailers:Direct-to-consumer subscription models with personalized nutrition algorithms are displacing impulse grocery purchases among committed fitness enthusiasts. Urban UK and German markets support same-day delivery economics where gym density enables efficient route consolidation.
- Supermarkets:General Mills and legacy CPG players anchor shelf presence through slotting fee advantages and promotional scale, compressing margins for emerging brands dependent on co-manufacturing.
- Health Stores:Independent retailers with educated staff drive trial for premium and novel formulations.
- Specialty Shops:Athletic wear retailers bundle nutrition boxes with apparel purchases through existing membership ecosystems.
Supermarkets retain volume leadership; online retailers are gaining share fastest through recurring revenue capture.
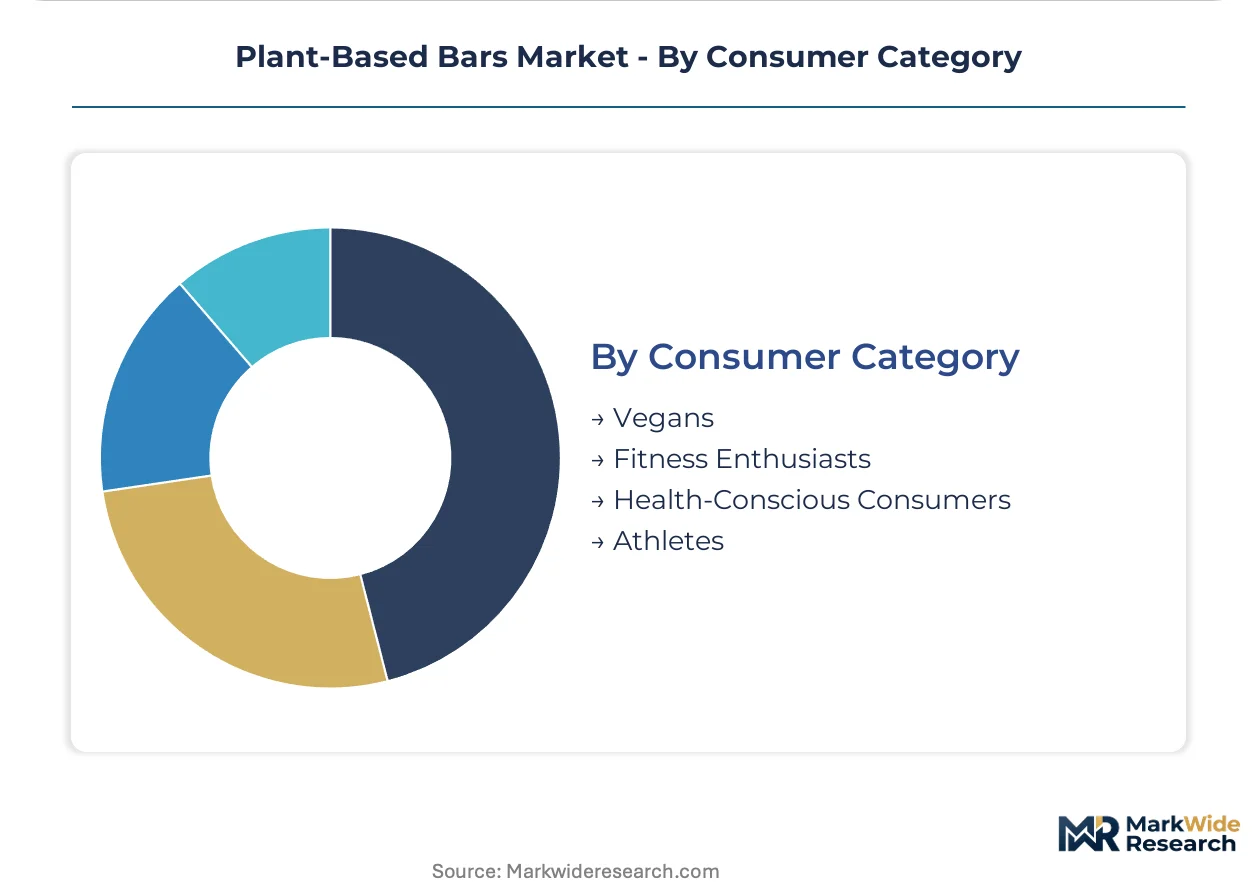
Consumer Category:
Application intensity separates performance-driven users with high purchase frequency from occasional buyers with elastic brand loyalty.
- Fitness Enthusiasts:Amateur athletes with structured training regimens generate the highest purchase frequency and lowest price elasticity, prioritizing flavor consistency and macronutrient reliability over in-store discovery. This segment drives cold-press manufacturing adoption as chalky mouthfeel rejection constrains extruded alternatives.
- Athletes:Competitive and professional users demand batch-tested formulations with documented protein quality metrics under EFSA standards, creating certification barriers for smaller entrants.
- Health-Conscious Consumers:Broad wellness-oriented buyers with moderate protein requirements and higher brand switching rates.
- Vegans:Ethical positioning drives acceptance of texture trade-offs and premium pricing for verified animal-free supply chains.
Fitness enthusiasts retain volume leadership; athletes command the steepest premium tier through certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German supermarket channels where clean-label certification commands shelf space, while UK online retailers compress margins through subscription-driven volume aggregation. This asymmetry reshapes where manufacturers allocate formulation investments and regulatory compliance resources.
Germany
Fitness enthusiasts in Bavaria and North Rhine-Westphalia drive concentrated demand for high-protein, allergen-free formulations through gym network expansion. The EU Green Deal and F-Gas Regulation enforce stringent sustainable sourcing and refrigeration standards across supply chains. Berlin-Brandenburg hosts the fastest-adapting cold-storage operators utilizing federal efficiency grants for CO2-based system retrofits.
United Kingdom
Urban gym density in London and Manchester enables same-day delivery economics for direct-to-consumer subscription models displacing impulse purchases. REACH framework compliance mandates chemical transparency documentation from all ingredient suppliers. CrossFit affiliates and boutique fitness studios in the Southeast pilot limited-edition fermented protein releases.
United States
Health-conscious consumers in California and New York Metro sustain volume leadership for protein bars through established athletic retail networks. FDA nutrition labeling and health claim regulations govern formulation decisions and packaging disclosures. The Pacific Northwest clusters R&D activity for organic plant protein sourcing innovations.
Canada
Organic pea protein sourcing concentration in Prairie Provinces exposes formulators to weather-driven input volatility and contract renegotiation cycles. Health Canada and PMRA standards regulate additive thresholds and organic certification timelines stretching 12-18 months. Ontario's manufacturing base processes Canadian-grown legume inputs for North American distribution.
Sweden
Climate-conscious buyers in Nordic retail channels prioritize CSRD-aligned carbon labeling and scope-three emissions disclosure for purchasing decisions. EFSA protein quality metrics and additive thresholds constrain texture parity with dairy-based competitors. Stockholm's food-tech cluster advances fermented fungal biomass processing for lower agricultural land intensity.
Plant-Based Bars Market Key Industry Players
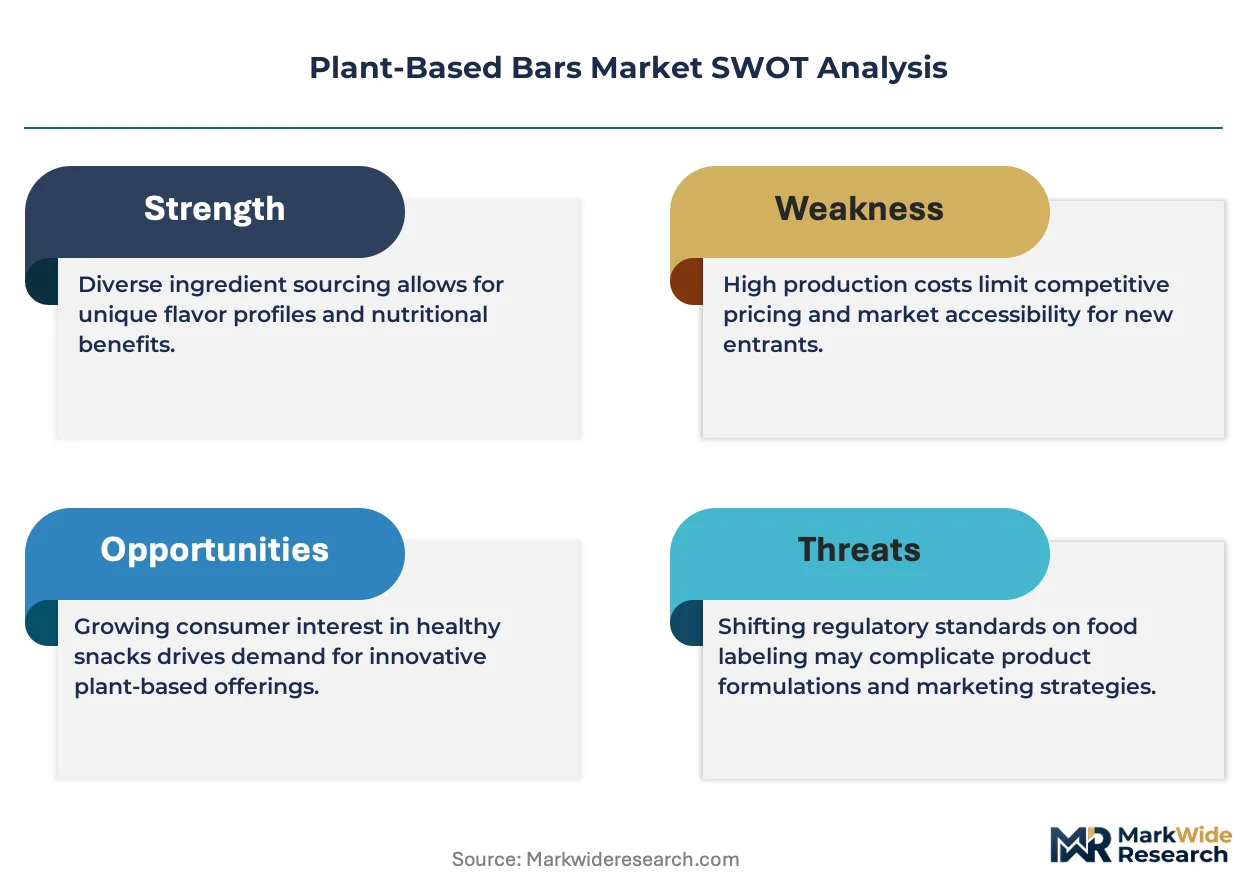
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where in-house production veterans with captive supply chains sustain margin control against co-manufacturing-dependent entrants facing compressed economics. The vendor base stratifies across three strategic archetypes: European manufacturing footprint holders leveraging regulatory proximity, R&D-intensive organic sourcing specialists, and legacy CPG players anchoring supermarket channel control through promotional scale. Dominant competitive moves include backward integration into ingredient supply and direct-to-consumer subscription infrastructure buildout.
Within the European manufacturing tier, Barebells represents footprint-based margin control, while Orgain exemplifies R&D intensity in organic plant protein sourcing. General Mills Inc anchors the legacy CPG position through established supermarket channel relationships. These three occupy distinct competitive vectors without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Barebells |
| Orgain |
| General Mills Inc |
| Rise Bar |
| No Cow |
| GoMacro |
| Simply Protein |
| NuGo Nutrition |
| PROBAR, Inc |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts for organic pea protein lock in supply access for in-house production veterans while exposing co-manufacturing-dependent entrants to spot market volatility and margin compression. These contract structures simultaneously secure price visibility across the EU Green Deal compliance window and freeze working capital in inventory cycles stretching 12-18 months for clean-label certification.
Pricing Analysis
The customization-premium spread separates configured-to-order subscription pricing from standard supermarket shelf pricing. A three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale. Pricing pressure stems from slotting fee advantages that General Mills and legacy CPG players deploy to compress emerging brand margins. Fitness enthusiasts exhibit the lowest price sensitivity due to flavor consistency requirements, while health-conscious consumers with elastic brand loyalty drive commoditization in impulse grocery channels.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain margin recovery for cold-chain-dependent formulations requiring CO2-based refrigeration retrofits under the EU F-Gas Regulation. Supply concentrates in Canada and Ukraine for organic pea protein, with California anchoring almond butter sourcing. Raw material dependencies rest on fermented fungal biomass, chicory root fiber, and resistant starch additions. Single-source vulnerability in Canadian Prairie Provinces exposes formulators to weather-driven input volatility. Distribution runs through direct-to-consumer subscription platforms displacing supermarket channel concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plant-based bars market represents an early-cycle expansion story where post-workout recovery snacking adoption among amateur athletes creates durable demand tailwinds. Fitness channel penetration in German gym networks signals penetration runway before saturation dynamics emerge.
For Market Incumbents: Fortify backward integration into organic plant protein sourcing to offset commodity legume price volatility and EFSA additive threshold constraints. Prioritize captive cold-press manufacturing capacity to defend margin control against co-manufacturing-dependent entrants facing extrusion technician scarcity and certification timeline delays. For New Entrants and Emerging Players: Anchor in senior nutrition applications for sarcopenia prevention, an underserved demographic with distinct texture-softened formulation requirements and limited incumbent presence. Target Nordic retail channels where CSRD-aligned carbon labeling creates differentiation headroom against legacy players with undocumented scope-three emissions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription operators with personalized nutrition algorithms, indicating superior cash-flow quality versus supermarket-dependent brands. Acquisition targets should exhibit in-house production footprints and established clean-label credentials. The signal to watch is federal efficiency grant uptake rates for CO2-based cold-storage retrofits, indicating regulatory adaptation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Protein Sourcing | Captive supply chains insulate margin control from Canadian and Ukrainian weather-driven price volatility. |
| Direct-to-Consumer Subscription Launch | Recurring revenue capture defends position against supermarket channel commoditization and slotting fee compression. |
| Cold-Press Manufacturing Scale-Up | Nutrient-preservation processes enable premium positioning against extruded competitors in German gym networks. |
| CSRD-Aligned Carbon Labeling Program | Scope-three emissions disclosure creates differentiation among climate-conscious buyers in Nordic retail channels. |
| Senior Nutrition Format Development | Texture-softened high-protein bars address sarcopenia prevention with limited incumbent competition. |
Research Approach
Cross-validation between regulatory filing analysis and supply chain documentation anchors the qualitative findings in this study. Primary interviews with brand managers, category buyers at German and UK retailers, supply planners, and cold-storage operators combined with secondary validation from EFSA guidance documents, EU Green Deal implementation texts, REACH compliance databases, and customs trade records. Bottom-up segmentation sizing and top-down market triangulation reconcile volume estimates across the analysis window.
Sensitivity analysis testing across protein source substitution scenarios and certification timeline variations informs the forecast framework. Segmentation dimensions modeled include product type, ingredient certification tier, distribution channel, and consumer application intensity. CAGRs derive from regression analysis against fitness channel penetration rates and organic protein input cost trajectories. Forecast inputs incorporate EFSA additive threshold evolution and federal efficiency grant disbursement patterns for cold-chain retrofits.
Material uncertainties — regulatory acceleration in F-Gas phase-down schedules, drought-induced almond butter supply disruption, and extrusion technician wage inflation — sit outside the modeled envelope. Forecasts reflect assumptions about adoption velocity among amateur athletes and clean-label certification completion rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Sausages Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
Vegan Pasta Market
Plant Based Food
Vegan Diet Market
Plant Based Food
Global Plant Based Milk Market
Plant Based Food
Pea Protein Isolate Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Africa Pea Protein Market
Plant Based Food
Burdock Root Extract Market
Plant Based Food
Vegan Pizza Crust Market
Plant Based Food
Brazil Soy Beverages Market