
 Extruded Cereals Market | 2026-2036
Extruded Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
Extruded Cereals Market Foresight
Whole grain flour is rebalancing cost structures across extruded cereal portfolios as manufacturers reduce dependence on refined corn inputs. General Mills leverages its North American milling infrastructure to secure consistent supply of blended grain formulations. Kellogg Company anchors its innovation pipeline in high-fiber extrusion technology for expanded product lines. Post Holdings competes through private-label manufacturing scale that serves multiple retail banners simultaneously.
Extruded cereals are grain-based products manufactured by forcing moistened starch dough through a die under high temperature and pressure, then expanding upon exit to create porous, shelf-stable structures with bulk densities typically below 0.3 g/cm³. This process enables precise control of texture, shape, and nutrient retention for breakfast and snack applications. Wheat-based puffs and flakes hold established volume positions in mature markets, while granola formats command higher margins through premium positioning in health food stores. Corn and rice segments sustain volume leadership in emerging economies where price sensitivity shapes purchasing decisions.
The FDA governs nutrient-content claims and fortification limits for cereals sold in the United States, while EFSA mandates strict health-claim substantiation across European markets. Both frameworks elevate R&D costs but create barriers against unverified product positioning. ISO 22000 and HACCP protocols further constrain process variability for exporters targeting multiple regulatory jurisdictions. Stakeholders must monitor evolving whole-grain definition standards and sugar threshold regulations that threaten reformulation requirements across core product lines.
Market Dynamics
Whole grain flour substitution is compressing input cost volatility while forcing capital retooling across extruded cereal manufacturing lines. This structural shift from refined corn dependence to blended grain portfolios is redrawing competitive economics and supplier relationships simultaneously.
Growth Catalysts
- Clean-label mandates:FDA and EFSA fortification standard tightening is accelerating reformulation investment toward natural preservative systems and reduced sugar thresholds.
- Extrusion precision technology:High-fiber extrusion process advances are expanding texture control capabilities for expanded snack and breakfast applications.
- Urban retail density:United States and German metropolitan markets are concentrating premium shelf space allocation for health-positioned extruded cereal formats.
Market Restraints
- Grain input cost volatility:Wheat and oat futures price swings are destabilizing blended flour cost structures for manufacturers with limited backward integration into milling.
- Supply concentration risk:North American corn processing capacity consolidation creates geographic dependency for starch supply security.
- Technical limitation:High-fiber dough rheology constraints restrict extrusion throughput speeds below refined grain baselines.
Strategic Opportunities
- Underpenetrated geography:Japanese convenience retail channels remain underserved by textured vegetable protein-fortified extruded snack formats.
- Regulatory tailwind:EU Green Deal sustainable packaging mandates are creating first-mover advantage for biodegradable film-wrapped cereal products.
- Technology convergence:Twin-screw extrusion combined with in-line mass spectrometry is enabling real-time nutrient retention optimization.
Industry Challenges
- Skill gap:Food engineering talent scarcity in extrusion die design is extending new product development timelines.
- Capex intensity:Continuous extruder replacement cycles demand substantial capital allocation for manufacturers upgrading from batch systems.
- Compliance timeline:ISO 22000 certification renewal complexity is creating bottlenecks for exporters serving multiple regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extruded Cereals Market |
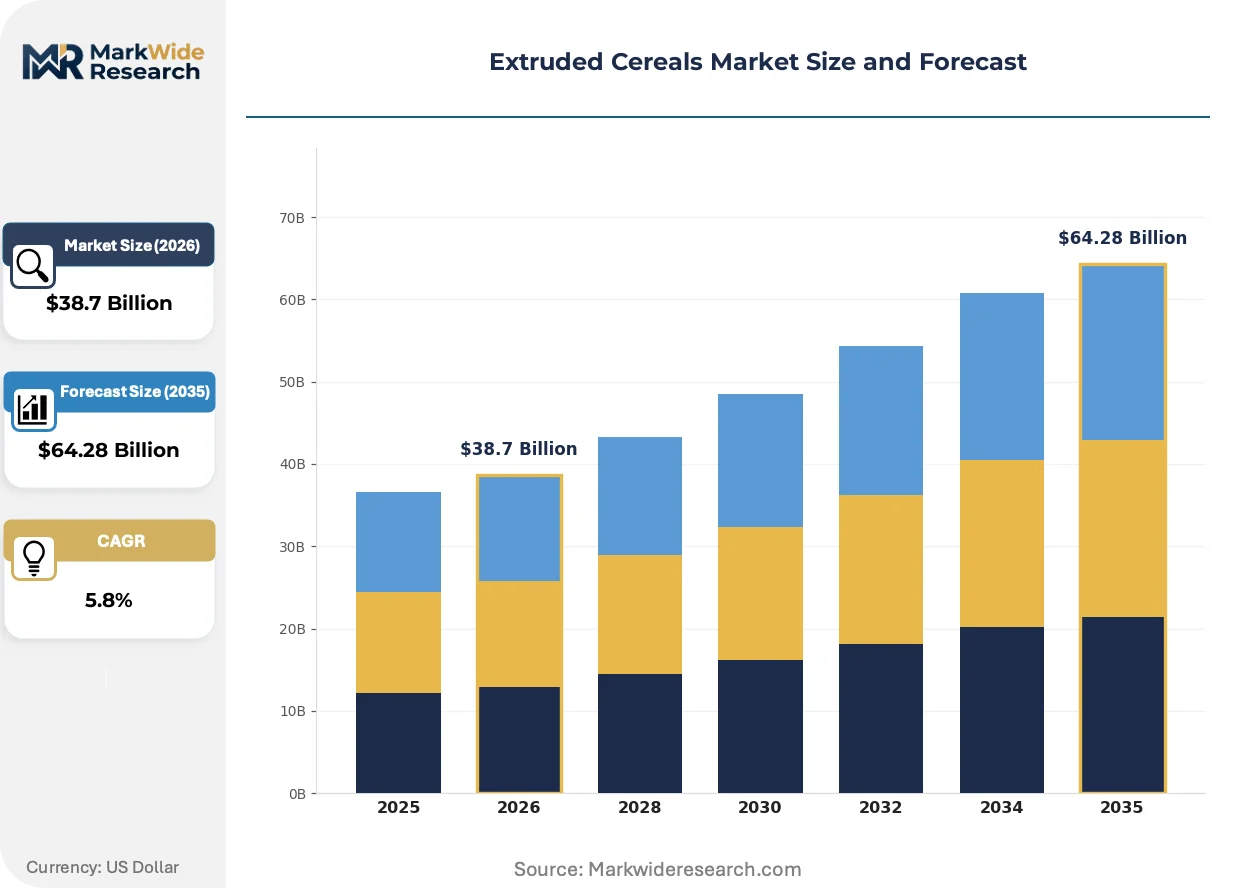
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn, Rice, Wheat, Oats Form: Flakes, Puffs, Bars, Granola End User: Retail Consumers, Food Service, Health Food Stores, Manufacturers Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores |
| Companies Covered | Conagra Brands, Grupo Bimbo, PepsiCo, B&G Foods, Mondelēz International, Kellogg Company, Post Holdings, Calbee, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extruded Cereals Market Shifts & Advancements
Extruded cereal manufacturing is experiencing simultaneous pressure from precision processing technology, tightening nutrient-content frameworks, and channel-specific format requirements. These intersecting forces are compressing product development cycles while expanding technical capability requirements.
Twin-screw extrusion systems with modular barrel configurations are decentralizing production scale economics across mid-cap manufacturers. Regional processors in Germany and Japan are adopting these systems to capture local formulation flexibility without centralized plant investment. This technology diffusion is compressing minimum efficient scale thresholds and fragmenting volume concentration.
EFSA health-claim substantiation protocols are elevating clinical trial requirements for fiber and whole-grain positioning statements. European manufacturers now face documentation burdens that delay label approval by 12-18 months for novel nutrient claims. Breakfast cereal segments with established EFSA-approved claims are consolidating shelf access advantage over challenger brands.
Direct-to-consumer subscription channels are capturing trial-oriented buyers who previously purchased through conventional grocery retail. United States health-conscious households are shifting initial product discovery online, with repeat volume migrating to club and mass retail formats. This bifurcation is forcing parallel packaging and pricing architectures from identical manufacturing lines.
Extruded Cereals Market Segmentation
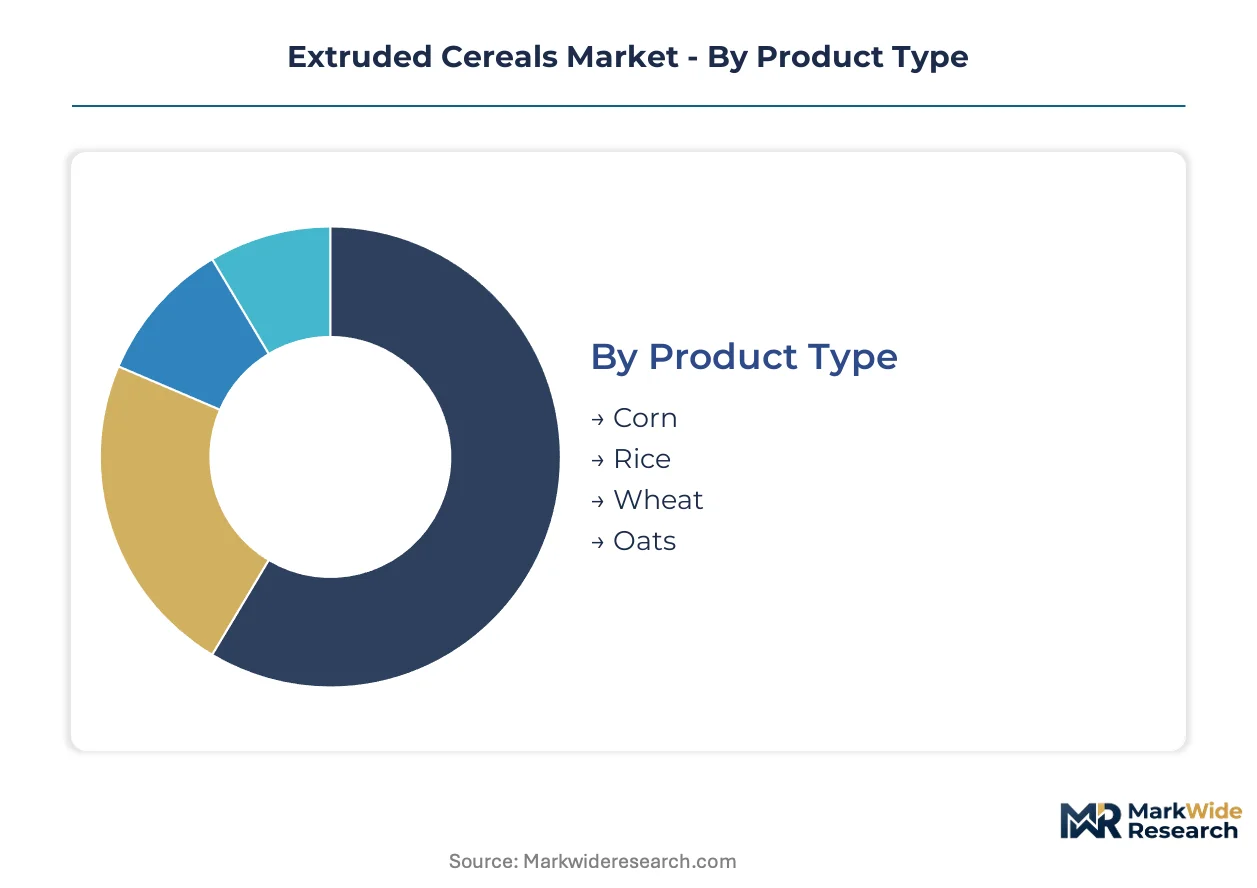
Extruded cereals fragment across four distinct segmentation axes. Product type and form determine manufacturing equipment and margin structure. End user and channel specifications dictate packaging formats, shelf-life requirements, and pricing architectures.
Product Type:
Cost tier separates buyers in this category, with commodity grain inputs at the base and premium whole-grain blends commanding formulation premiums.
- Corn:Yellow and white corn grits provide the lowest-cost starch base for high-volume extrusion. Demand concentrates in emerging economies where price sensitivity dominates purchasing decisions, though input cost volatility from North American corn processing consolidation threatens margin stability.
- Wheat:Hard red winter and durum wheat flours enable higher-protein extrusion with superior texture retention. German and Japanese manufacturers favor wheat-based puffs for premium breakfast positioning, driven by EFSA-approved whole-grain health claims that justify shelf price premiums.
- Rice:White and brown rice flours offer hypoallergenic formulations for clean-label portfolios. Asian markets sustain volume leadership for rice-based extruded snacks.
- Oats:Rolled and steel-cut oat inputs deliver soluble fiber content for heart-health positioning. Health food stores in the United States drive oat segment expansion.
Volume sits with corn; growth tilts toward oats.
Form:
Application determines extrusion die complexity and downstream processing requirements.
- Flakes:Flattened extruded sheets require precision roller mills and toasting ovens for final texture. United States breakfast table consumption sustains flake dominance, though high-fiber dough rheology constraints limit extrusion throughput speeds below refined grain baselines.
- Puffs:Direct-expanded spheres and shapes achieve lowest bulk density through high-pressure die expansion. Japanese convenience retail channels capture growing puff demand for on-the-go snacking, supported by textured vegetable protein fortification trends.
- Bars:Cold-formed extrusion with binding syrups creates portable meal-replacement formats. German consumers favor bar formats for workplace consumption.
- Granola:Clustered baked extrusions command highest margins through premium health store positioning. Clusters require extended drying cycles that compress line utilization rates.
Volume sits with flakes; growth tilts toward bars.
End User:
Customer type dictates order scale, specification tolerance, and contract structure.
- Retail Consumers:Household purchasers drive brand loyalty and repeat volume through familiar flavor profiles. United States supermarket channels dominate this segment, with direct-to-consumer subscription models capturing trial-oriented buyers who migrate to mass retail for repeat purchases.
- Food Service:Hotels, cafeterias, and institutional kitchens purchase bulk formats with extended shelf-life requirements. German contract catering operators specify clean-label formulations for public sector compliance.
- Health Food Stores:Independent retailers demand certified organic and non-GMO verification with minimal processing claims. EFSA health-claim substantiation protocols create 12-18 month approval delays for novel positioning statements in European health channels.
- Manufacturers:Industrial buyers source intermediate extruded ingredients for further processing into composite products. Japanese confectionery manufacturers import extruded cereal bases for chocolate coating operations.
Volume sits with retail consumers; growth tilts toward health food stores.
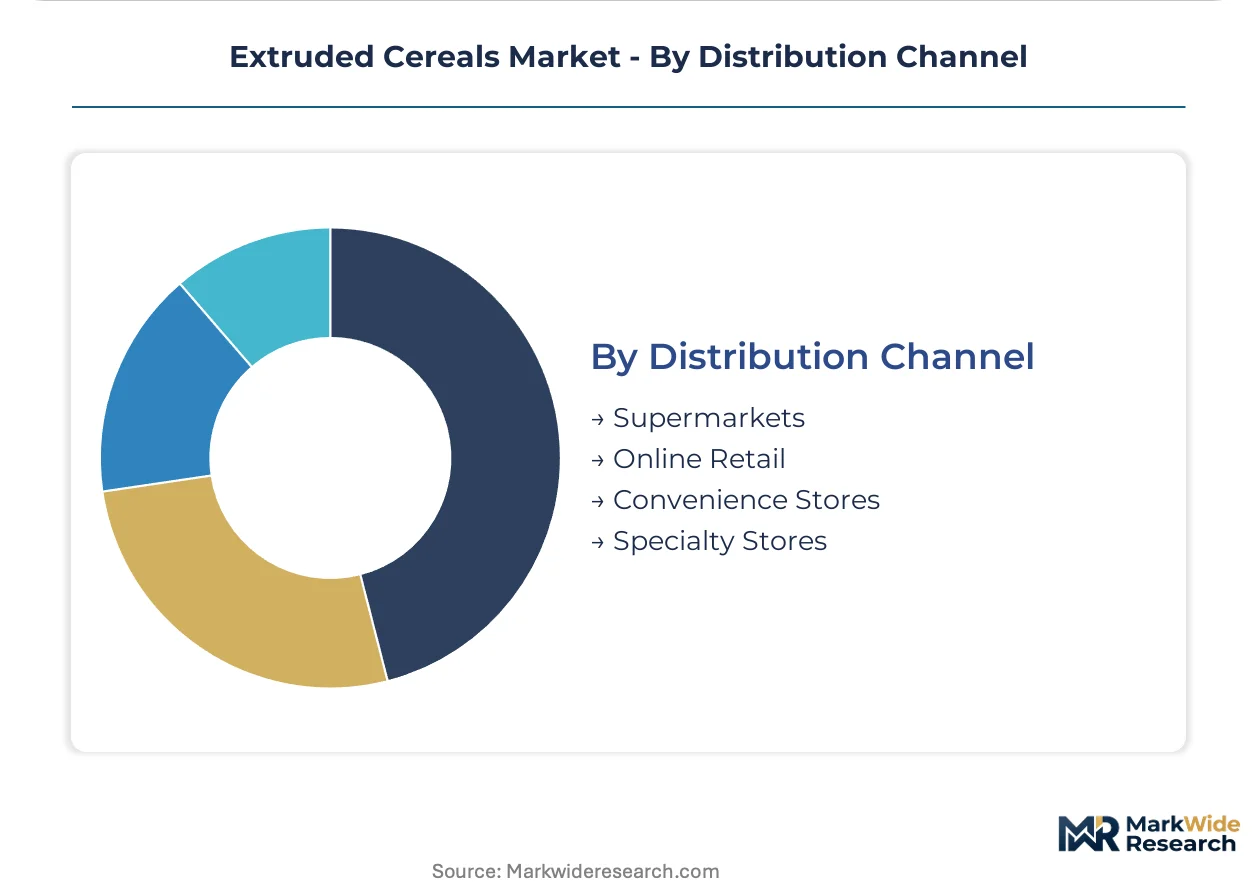
Distribution Channel:
Channel concentration shapes packaging investment and trade promotion spend.
- Supermarkets:Mass merchandisers command slotting fees and promotional calendar adherence for shelf access. United States retail banners allocate premium space to health-positioned extruded cereals with established EFSA or FDA-compliant claims.
- Online Retail:E-commerce platforms enable subscription replenishment and flavor variety bundling. Direct-to-consumer discovery channels in the United States compress new product trial costs versus conventional grocery launch.
- Convenience Stores:Small-format urban retailers prioritize single-serve packaging and immediate consumption positioning. Japanese convenience retail remains underserved by protein-fortified extruded snack formats.
- Specialty Stores:Organic and natural product retailers enforce supplier certification standards that exceed mass-market requirements. EU Green Deal sustainable packaging mandates create first-mover advantage for biodegradable film-wrapped products in European specialty channels.
Volume sits with supermarkets; growth tilts toward online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the United Arab Emirates concentrate regional distribution infrastructure for extruded cereal exporters targeting Middle Eastern markets. These zones offer zero-duty warehousing and simplified customs procedures that reduce landed costs for manufacturers shipping from European and Asian production bases.
United States
Health-conscious retail consumers in metropolitan areas drive clean-label breakfast cereal demand. FDA fortification standard tightening accelerates reformulation investment toward natural preservative systems. Minneapolis-St. Paul anchors North American extruded cereal production with integrated milling and extrusion infrastructure serving national retail banners.
Germany
EFSA health-claim substantiation protocols elevate clinical documentation requirements for whole-grain positioning statements. EU Green Deal sustainable packaging mandates create first-mover advantage for biodegradable film-wrapped products in specialty channels. Bavaria concentrates precision extrusion equipment manufacturing and food engineering talent pools.
Japan
Convenience retail channels capture growing demand for on-the-go extruded snack formats. METI standards govern food additive approvals and labeling requirements for fortified cereal products. Kanto region manufacturers supply textured vegetable protein-fortified puffs to dense urban convenience store networks.
Brazil
Price-sensitive consumer segments sustain volume leadership for corn-based extruded cereals in emerging economy contexts. ANVISA regulates nutrient-content claims and fortification limits for breakfast products sold domestically. São Paulo state anchors South American production capacity with integrated grain processing and extrusion operations.
India
Rising urban middle-class households expand breakfast cereal penetration beyond traditional consumption patterns. FSSAI mandates strict labeling standards for health and nutrition claims on packaged food products. Maharashtra and Gujarat concentrate contract manufacturing capacity serving both domestic retail and export markets.
Extruded Cereals Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with portfolio-scale conglomerates commanding supermarket shelf access while private-label fabricators capture volume through retail banner relationships. The vendor base organizes around three archetypes: diversified food conglomerates with extruded cereal divisions, pure-play breakfast cereal specialists, and co-manufacturing service providers. Consolidation pressure intensifies as input cost volatility favors backward-integrated milling operations. Geographic expansion and strategic partnerships represent dominant competitive moves for mid-cap challengers seeking scale.
Within the diversified conglomerate tier, General Mills and Kellogg Company exemplify portfolio-scale positioning across multiple grain-based categories. Post Holdings occupies a distinct position as a publicly traded pure-play with significant private-label manufacturing exposure. These three entities represent contrasting strategic postures: integrated brand ownership, hybrid branded-contract manufacturing, and scale-driven co-production services.
| Leading Market Players |
|---|
| Conagra Brands |
| Grupo Bimbo |
| PepsiCo |
| B&G Foods |
| Mondelēz International |
| Kellogg Company |
| Post Holdings |
| Calbee |
| General Mills |
| Others |
Supply & Pricing Matrix
Twin-screw extrusion technology diffusion is compressing minimum efficient scale thresholds while fragmenting volume concentration across regional processors, simultaneously redrawing cost economics and supplier power dynamics as mid-cap manufacturers capture local formulation flexibility without centralized plant investment.
Pricing Analysis
Volume sits with corn-based commodity tiers while margins concentrate in oat and granola premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-approved whole-grain health claims from refined grain baselines and private-label contract manufacturing. Cost compression in commodity corn tiers is intensifying because North American processing consolidation limits backward-integrated sourcing alternatives. Emerging economy buyers exhibit highest price sensitivity, while health food store purchasers accept formulation premiums for certified organic verification.
Supply Chain Analysis
ISO 22000 and HACCP certification gating constrains exporter access to multiple regulatory jurisdictions, elevating compliance costs for challengers while protecting incumbent positions. Raw material flows draw from United States corn processing, German wheat milling, and Japanese rice flour refining as dominant input sources. Supply chain risk centers on single-source vulnerability for textured vegetable protein fortification inputs. Distribution runs through supermarket slotting-fee structures in mature markets and direct-to-consumer subscription channels for trial-oriented buyer acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive milling capacity and extrusion equipment manufacturing control determine cost position and formulation speed.
For Market Incumbents: Deepen backward integration into North American grain processing to secure blended flour supply security against futures price volatility. Acquire precision extrusion die design capabilities to compress new product development timelines threatened by food engineering talent scarcity. Defend shelf access through EFSA and FDA pre-approved health claim portfolios that create 12-18 month approval barriers for challenger brands. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer lowest customer acquisition cost for trial-oriented buyers who subsequently migrate to mass retail repeat purchase. Japanese convenience retail remains underserved by protein-fortified extruded snack formats, presenting white-space penetration opportunity. Capture initial volume through biodegradable film-wrapped products aligned with EU Green Deal sustainable packaging mandates. For Investors and Strategic Acquirers: Exit pathways concentrate in co-manufacturing service provider acquisitions by branded conglomerates seeking private-label scale. Long-term viability favors entities with integrated milling infrastructure and multi-jurisdictional ISO 22000 certification. Watch for FDA sugar threshold regulation tightening as inflection indicator forcing reformulation capex cycles that favor capital-rich incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Milling | Captive grain processing secures blended flour supply against North American corn consolidation. |
| High-Fiber Extrusion Technology Investment | Twin-screw precision expands texture control for EFSA-approved whole-grain positioning claims. |
| Direct-to-Consumer Channel Launch | Subscription models capture trial-oriented buyers before mass retail repeat volume migration. |
| Sustainable Packaging Transition | Biodegradable film-wrapped products align with EU Green Deal mandates for specialty channel access. |
| Private-Label Manufacturing Scale-Up | Co-production services capture retail banner relationships across multiple supermarket banners simultaneously. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with extrusion equipment engineers, cereal brand managers, retail category buyers, and grain procurement directors. FDA fortification standard documents, EFSA health-claim substantiation protocols, and ISO 22000 certification databases provided regulatory boundary conditions. Bottom-up volume modeling across product type, form, end user, and distribution channel segments triangulated against top-down market sizing from milling industry production statistics.
Granularity-level modeling captured corn, wheat, rice, and oat input cost structures at the ingredient tier; flake, puff, bar, and granola form factors at the manufacturing equipment tier; and retail consumer, food service, health food store, and manufacturer end-user archetypes at the demand tier. CAGRs derived from historical volume trajectories adjusted for twin-screw extrusion technology adoption curves and clean-label reformulation investment cycles across the analysis window. Forecast inputs incorporated wheat futures price volatility assumptions and EFSA approval timeline distributions for novel nutrient claims.
Caveats apply where FDA sugar threshold regulation tightening or EFSA whole-grain definition standard revision could materially shift the outlook for reformulation requirements and shelf-access economics. A model refresh is warranted upon material change in North American corn processing consolidation patterns or Japanese convenience retail protein-fortification adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Allergy-Free Snacks Market
Snacks
Snacks Market
Snacks
Middle East and Africa Snack Food Market
Snacks
Corn Chips Market
Snacks
Asia Pacific Tortilla Market
Snacks
Sweet Potato Fries Market
Snacks
China Snack Bar Market
Snacks
Low-Fat Tortillas Market
Snacks
UAE Snack Bar Market
Snacks
Mediterranean Lentil Crisps and Inclusion Bases Market
Snacks
Spain Snack Bar Market
Snacks
Europe Extruded Snack Food Market
Snacks
North America Extruded Snack Food Market
Snacks
Premium Snacks Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
Granola Bars Market