
 Low Fat Crackers Market | 2026-2036
Low Fat Crackers Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Crackers Market Analytics
Non-GMO Project verification is collapsing as a baseline qualifier for shelf placement in mainstream low fat cracker assortments. Mondelez International leverages its global procurement infrastructure to secure identity-preserved grain contracts at scale. Simple Mills sustains premium positioning through almond-flour formulations that exclude refined starches entirely. Mary's Gone Crackers anchors the organic seeded segment with certified gluten-free production lines that command dedicated retail space.
Low fat crackers are baked snack products formulated with reduced lipid content, typically achieving fat levels below 3 grams per serving through modified dough systems, steam-injection baking, or alternative lipid sources such as oleogels. These products serve weight-management consumers, cardiac-health dietary protocols, and institutional feeding programs with mandated nutritional ceilings. Whole wheat crackers lead volume contribution due to fiber-adjacent health claims, while seed crackers represent the fastest-expanding margin pool as chia, flax, and hemp ingredients justify price premiums. Rice crackers occupy mature shelf-stable positions in Asian-American retail corridors, though their growth rate lags newer multigrain formats.
The FDA governs nutrient content claims including "low fat" thresholds and serving-size standardization under 21 CFR 101.62, while the USDA Organic seal and Non-GMO Project verification operate as parallel gatekeepers for premium distribution access. State-level sugar warning labels in California and New York exert secondary pressure on adjacent sweet-flavor formulations. Stakeholders must monitor evolving front-of-pack scoring systems from the FDA and private retail consortiums, as these will determine which formulations retain shelf visibility without reformulation investment.
Market Dynamics
FDA's updated Nutrition Facts label requirements and front-of-pack labeling initiatives are forcing reformulation across conventional retail channels, compressing development timelines and redistributing shelf visibility toward clean-label compliant products.
Growth Catalysts
- Clean-label mandates:FDA's 21 CFR 101.62 serving-size standardization pressures legacy brands toward simplified ingredient decks, accelerating private-label innovation cycles.
- Corporate wellness programs:Fortune 500 cafeteria contracts now specify sub-3g fat thresholds per serving, institutionalizing volume demand for compliant cracker formats.
- Steam-injection baking:This modified atmospheric process achieves lipid reduction without textural compromise, enabling whole-wheat formulations to retain mouthfeel parity with full-fat alternatives.
Market Restraints
- Identity-preserved grain scarcity:Non-GMO Project verified corn and wheat supplies concentrate in the US Midwest, exposing procurement to weather-driven price volatility.
- Oleogel functional limits:Ethylcellulose-stabilized lipid systems fail to replicate Maillard browning intensity of conventional fats, constraining flavor development in premium positioned lines.
- California sugar warning labels:State-level mandates on sweet-flavor adjacent categories create formulation complexity for honey-glazed or fruit-infused cracker extensions.
Strategic Opportunities
- Direct-to-institutional channels:K-12 feeding programs and hospital systems represent underpenetrated volume pools with mandated nutritional ceilings and long-term contract structures.
- Almond-flour premium tier:Grain-free positioning captures paleo and keto-adjacent consumers willing to absorb 40-60% price premiums over conventional multigrain formats.
- EU Green Deal alignment:EFSA-approved health claims for chia and hemp ingredients unlock distribution in German and Dutch retail consortiums prioritizing sustainability credentials.
Industry Challenges
- Gluten-free certification timelines:GFCO audit protocols require 6-9 month validation cycles, delaying line extensions in the fastest-expanding seeded cracker segment.
- Retrofitting legacy ovens:Steam-injection hardware installation demands $2-4M per facility, stranding mid-cap bakeries without captive capital access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Crackers Market |
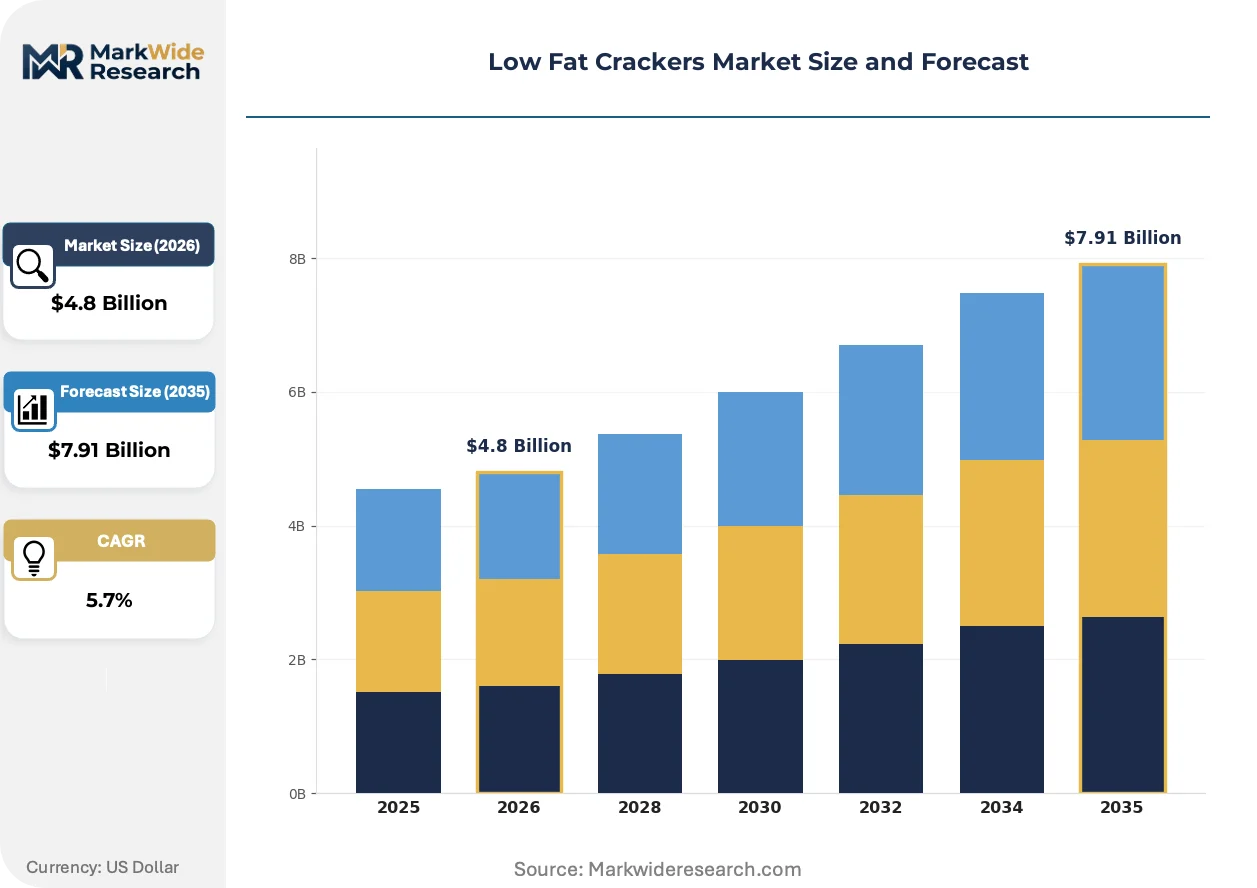
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rice Crackers, Whole Wheat Crackers, Corn Crackers, Seed Crackers Flavor: Herb, Cheese, Spicy, Sweet Packaging Type: Pouches, Boxes, Tubs, Bags Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores |
| Companies Covered | Mondelez International, Kellogg Company, PepsiCo, Mary's Gone Crackers, Campbell Soup Company, Simple Mills, Crunchmaster, Kellanova, Snyder's-Lance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Crackers Market Evolving Landscape
Reformulation science is compressing the trade-off between fat reduction and sensory performance, while regulatory labeling convergence and procurement centralization reshape how products reach end consumers.
Oleogel technology is miniaturizing the functional gap between reduced-fat and conventional baked goods. Ethylcellulose-structured oleogels from high-oleic sunflower oil now replace solid fats in laminated doughs without compromising flakiness. Mid-tier bakeries in the US Southeast are retrofitting sheeting lines to accommodate these alternative lipid systems at accelerating pace. The structural consequence is miniaturizing the premium price gap between health-positioned and indulgence-positioned cracker tiers.
REACH restrictions on titanium dioxide whitening agents are forcing European manufacturers toward calcium carbonate and rice starch alternatives. ECHA's 2022 classification of TiO2 as a category 2 carcinogen by inhalation triggered immediate reformulation mandates across EU member states. German private-label suppliers have absorbed the highest compliance costs, accelerating consolidation among coating and seasoning specialists serving the crackers category.
Centralized procurement through retail consortiums is consolidating supplier rosters and compressing switching flexibility. Walmart's Sustainable Packaging Playbook and Kroger's Zero Hunger Zero Waste commitments now function as de facto gating criteria for national distribution. This behavioral shift concentrates volume with vertically integrated grain processors capable of documenting regenerative agriculture credentials across their supply bases.
Low Fat Crackers Market Segmentation
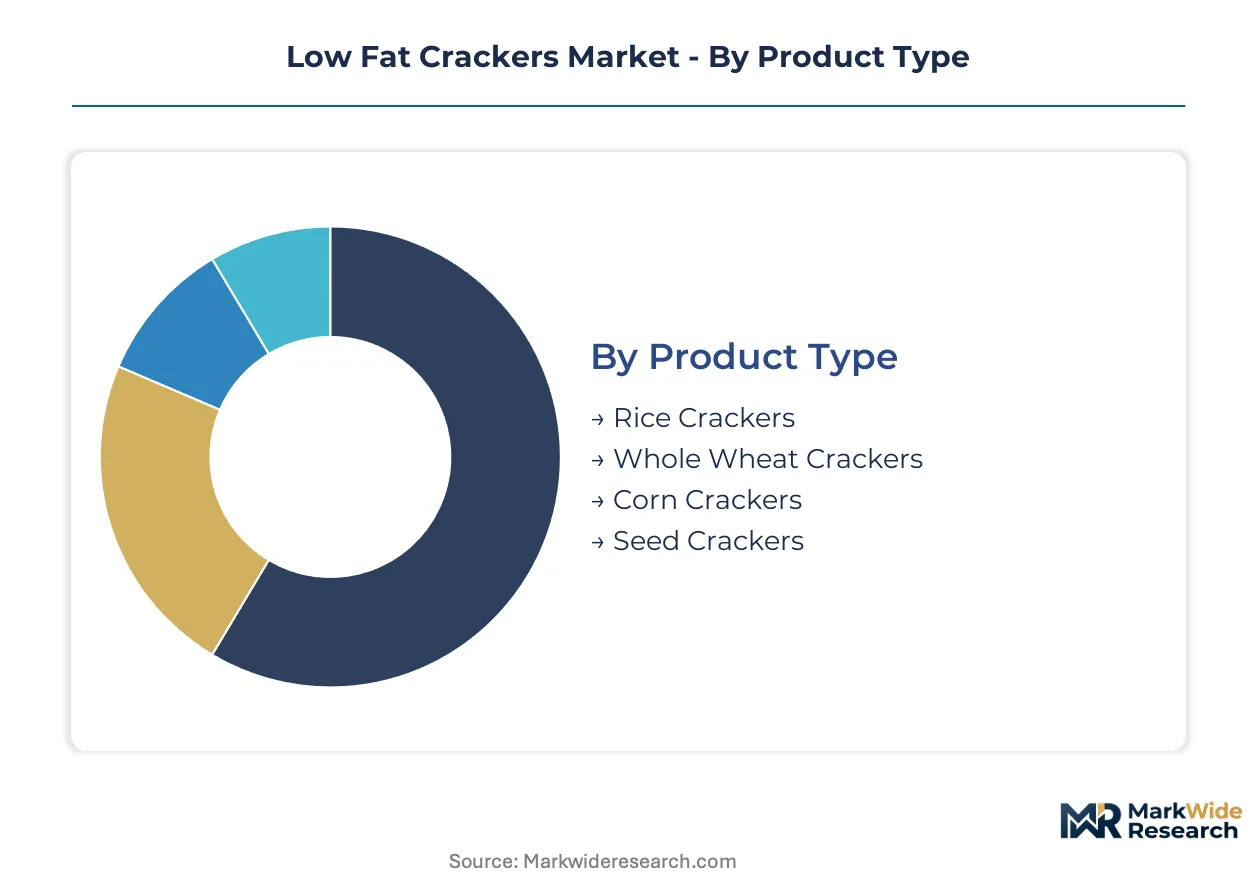
Low fat cracker manufacturers configure their product portfolios around four intersecting dimensions that determine channel access and price positioning. Each segmentation axis carries distinct regulatory, operational, and margin implications that shape competitive strategy.
Product Type:
Channel-mix patterns diverge sharply across product types, with conventional retail favoring whole wheat formats while specialty and natural channels concentrate seeded and grain-free alternatives.
- Whole Wheat Crackers:Formulated with refined or whole grain wheat flour as the primary structural base, achieving fat reduction through modified dough hydration and extended baking cycles. Demand concentrates in US conventional retail channels where fiber-adjacent health claims drive household penetration, though FDA serving-size standardization pressures sodium and fat thresholds simultaneously.
- Seed Crackers:Built on chia, flax, hemp, or sesame substrates that deliver omega-3 positioning and textural complexity without lipid-heavy binders. Expansion concentrates in natural specialty stores and direct-to-consumer subscription channels where consumers absorb 40-60% price premiums for organic certification and paleo alignment.
- Rice Crackers:Extruded or baked rice flour formulations dominant in Asian-American retail corridors and institutional feeding programs with allergen-management protocols.
- Corn Crackers:Masa-based or extruded corn products serving gluten-free demand segments and Latin American consumer preferences in border-state markets.
Whole wheat crackers dominate installed base. Seed crackers are where expansion concentrates.
Flavor:
Flavor architecture determines ingredient cost tiers and regulatory exposure, with savory profiles commanding manufacturing efficiency and sweet variants triggering state-level labeling mandates.
- Herb:Rosemary, thyme, and basil infusions leveraging natural flavor compounds to compensate for reduced fat mouthfeel, popular in Mediterranean-positioned product lines.
- Cheese:Nutritional yeast and cultured dairy powders delivering umami depth; California and New York sugar warning label frameworks create adjacent compliance complexity for honey-cheese hybrid formulations.
- Spicy:Capsicum and pepper extracts masking textural compromises in steam-injection baked formats, gaining traction in Southwest US markets and younger demographic cohorts.
- Sweet:Honey, fruit, and molasses-sweetened extensions facing heightened scrutiny under state sugar warning mandates and front-of-pack scoring systems.
Herb and cheese variants anchor volume throughput. Spicy formulations are climbing the fastest as manufacturers target heat-seeking younger consumers.
Packaging Type:
Packaging selection tracks retail channel requirements and sustainability credentialing, with format choice directly influencing shelf-life engineering and logistics cost structures.
- Pouches:Flexible film structures with resealable closures dominating club store and value-oriented retail channels where portion control and pantry storage convenience drive purchase decisions.
- Boxes:Paperboard cartons with inner film barriers serving conventional supermarket sets and meeting Walmart Sustainable Packaging Playbook criteria for national distribution access.
- Tubs:Rigid plastic containers with snap-fit lids capturing deli-adjacent and foodservice channels where bulk presentation and tabletop visibility matter.
- Bags:Traditional pillow pouches and stand-up formats occupying price-competitive private-label segments and convenience store impulse locations.
Boxes command the broadest channel presence. Pouches are gaining share fastest as club and e-commerce channels expand.
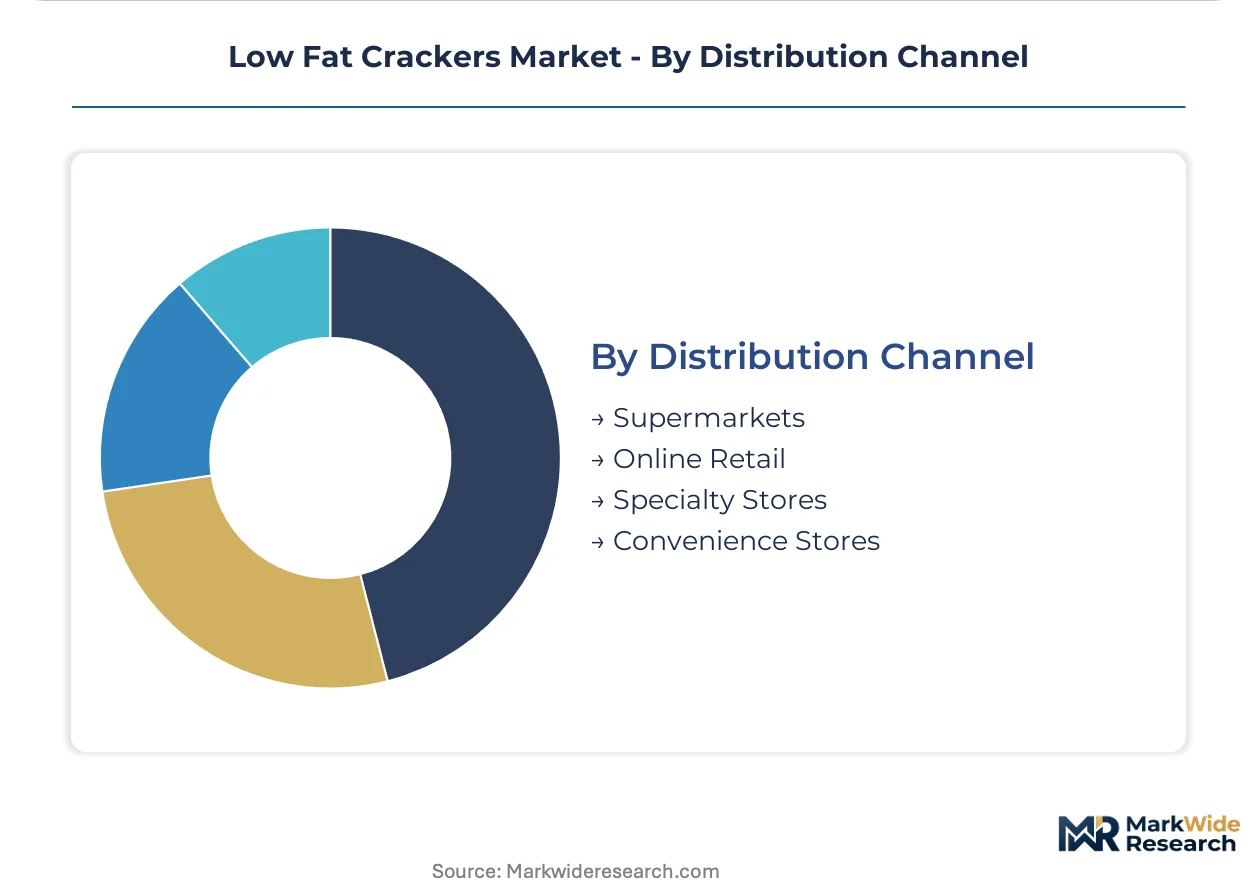
Distribution Channel:
Channel strategy determines margin capture and brand positioning, with each pathway imposing distinct certification, promotional, and supply chain requirements.
- Supermarkets:Conventional grocery and mass merchandiser channels accounting for the largest volume throughput, where slotting fees and promotional calendars strain mid-cap manufacturer cash flows.
- Online Retail:Amazon, Thrive Market, and brand-direct platforms enabling subscription models and granular consumer data capture, though fulfillment costs erode margin on low-weight, low-price items.
- Specialty Stores:Natural, organic, and gourmet retailers including Whole Foods and regional co-ops where Non-GMO Project verification and regenerative agriculture credentials function as table stakes.
- Convenience Stores:C-store and gas station channels prioritizing single-serve formats and immediate consumption occasions, with distribution concentrated through wholesale distributors like McLane and Core-Mark.
Supermarkets anchor installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serving-size standardization under 21 CFR 101.62 has triggered reformulation waves that concentrate competitive investment in North American and European manufacturing bases. Clean-label procurement mandates from Walmart and Kroger now function as de facto export standards for suppliers seeking developed-market access.
United States
Corporate wellness programs at Fortune 500 firms now specify sub-3g fat thresholds per serving, institutionalizing volume demand for compliant cracker formats. FDA front-of-pack labeling initiatives compress development timelines and redistribute shelf visibility toward simplified ingredient decks. Chicago and Minneapolis anchor Midwest grain processing clusters where identity-preserved corn and wheat supplies concentrate.
Germany
EFSA-approved health claims for chia and hemp ingredients unlock distribution in retail consortiums prioritizing sustainability credentials. REACH restrictions on titanium dioxide whitening agents triggered immediate reformulation mandates across German manufacturing bases. Bavaria-based private-label suppliers absorbed the highest compliance costs, accelerating consolidation among coating specialists.
United Kingdom
Clean-label penetration in conventional retail channels deepens fastest among health-conscious millennial and Gen Z consumer cohorts. FSA guidance on front-of-pack traffic-light labeling exerts secondary pressure on sodium and fat thresholds simultaneously. Greater London and the Southeast concentrate demand for premium seeded formats with organic certification.
Netherlands
EU Green Deal alignment priorities position Dutch retail consortiums as early adopters of regenerative agriculture credentialing systems. ECHA classification protocols for novel food ingredients create compliance complexity for oleogel-based formulations. The Randstad logistics corridor enables efficient distribution of low-weight snack products across Northwestern European markets.
Canada
Health Canada nutrition labeling requirements mirror FDA serving-size standardization, reducing regulatory friction for US exporters. Provincial school feeding programs in Ontario and Quebec represent underpenetrated volume pools with mandated nutritional ceilings. The Prairie Provinces supply non-GMO grain inputs that support clean-label positioning in cross-border retail channels.
Low Fat Crackers Market Competitive Landscape
Listed leaders compete with private specialists across procurement scale and formulation agility dimensions, producing a tiered structure where multinational CPG conglomerates anchor volume throughput while mid-cap specialists capture margin in premium niches. Three archetypes dominate: vertically integrated grain processors with regenerative agriculture credentials, almond-flour formulators occupying grain-free positioning, and organic seeded specialists with dedicated gluten-free production lines. Capacity expansion and strategic portfolio diversification toward clean-label compliant formats constitute the dominant competitive moves.
Within the multinational CPG tier, Mondelez International and Kellogg Company occupy positions that exemplify procurement scale advantages, while PepsiCo sits within the snack-food conglomerate archetype with cross-category brand leverage. Among mid-cap specialists, Simple Mills and Mary's Gone Crackers represent the premium clean-label positioning that commands dedicated retail space and absorbs 40-60% price premiums over conventional formats.
| Leading Market Players |
|---|
| Mondelez International |
| Kellogg Company |
| PepsiCo |
| Mary's Gone Crackers |
| Campbell Soup Company |
| Simple Mills |
| Crunchmaster |
| Kellanova |
| Snyder's-Lance |
| Others |
Value Network & Pricing Analysis
Mid-cap bakery capacity utilization below 70% in the US Southeast compresses margin recovery for non-integrated processors, forcing price floors upward as fixed costs spread across thinner volume bases while identity-preserved grain premiums concentrate procurement power with vertically integrated multinationals.
Pricing Analysis
Certification level creates the primary spread across low fat cracker tiers, with Non-GMO Project verification and USDA Organic status commanding 40-60% premiums over conventional formats in specialty retail channels. Three-tier pricing structure across premium almond-flour, standard whole-wheat, and economy private-label levels reflects ingredient cost stratification and channel slotting fee burdens. Pricing pressure stems from Walmart's Sustainable Packaging Playbook compliance costs transferring to suppliers. Private-label buyers at club stores exhibit highest price sensitivity, while direct-to-consumer subscribers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
The United States and Canada anchor North American grain processing, with identity-preserved corn and wheat supplies concentrating in the Midwest Prairie corridor and Ontario's organic belt. Oleogel inputs from high-oleic sunflower oil processors and ethylcellulose stabilizer stocks draw from specialized chemical suppliers in Germany and the Netherlands. Single-source vulnerability runs through concentrated Non-GMO Project verified grain handlers exposed to weather-driven harvest volatility. Distribution runs through retail consortium procurement desks that consolidate supplier rosters and compress switching flexibility for mid-tier bakeries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low fat cracker demand cycles with corporate wellness program renewal calendars and institutional feeding contract windows, creating predictable volume inflection points as Fortune 500 firms and K-12 systems rebid their snack procurement.
For Market Incumbents: Compound procurement scale advantages through backward integration into identity-preserved grain origination, securing captive supply of Non-GMO Project verified inputs before weather volatility intensifies. Defend shelf position by accelerating steam-injection baking retrofit timelines ahead of FDA front-of-pack labeling enforcement, as clean-label compliance becomes the gating criterion for national distribution access. For New Entrants and Emerging Players: Anchor in direct-to-institutional channels where K-12 feeding programs and hospital systems operate under mandated nutritional ceilings with long-term contract structures that insulate volume from retail promotional volatility. Target the underpenetrated almond-flour premium tier where paleo and keto-adjacent consumers absorb substantial price premiums and brand loyalty forms through subscription models rather than slotting fee competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors almond-flour formulators with grain-free production capabilities and regenerative agriculture credentialing systems that align with EU Green Deal procurement priorities. Acquisition targets should demonstrate validated gluten-free certification pathways and established relationships with retail consortium sustainability officers. The signal to watch is consolidation among coating and seasoning specialists serving European manufacturers adapting to REACH restrictions on titanium dioxide whitening agents.| Strategic Initiative | Industry Significance |
|---|---|
| Steam-Injection Baking Retrofit | Enables fat reduction below 3g per serving without textural compromise for FDA compliance. |
| Identity-Preserved Grain Contracting | Secures Non-GMO Project verified supply chains against weather-driven price volatility in Midwest clusters. |
| Almond-Flour Premium Tier Launch | Captures paleo and keto-adjacent consumers willing to absorb 40-60% price premiums over conventional formats. |
| Direct-to-Institutional Channel Development | Accesses K-12 and hospital systems with mandated nutritional ceilings and long-term contract structures. |
| EU Green Deal Alignment Certification | Unlocks distribution in German and Dutch retail consortiums prioritizing sustainability credentials and EFSA-approved health claims. |
Research Methodology
Cross-validation between primary interviews with category buyers at retail consortiums and secondary analysis of FDA enforcement patterns anchors the qualitative findings on regulatory compliance timelines. The research program combined discussions with brand managers at multinational CPG firms, procurement leads at grain processing cooperatives, and bakery operations directors with validation against USDA organic certification databases, Nielsen retail audit data, and SEC filings from publicly traded snack food conglomerates. Bottom-up volume modeling from individual facility capacities and top-down demand segmentation from channel-level consumption patterns were reconciled through iterative triangulation.
Sensitivity analysis across input cost scenarios and regulatory enforcement timelines shaped the analytical framework for value projections across the analysis window. Segmentation dimensions modeled include product type, flavor architecture, packaging format, and distribution channel, with additional granularity on certification status and grain input sourcing. CAGRs were derived from installed base growth rates adjusted for replacement demand and channel mix evolution, incorporating steam-injection baking adoption curves and corporate wellness program penetration rates as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued FDA front-of-pack labeling implementation and stable identity-preserved grain supply availability; material deviation in regulatory enforcement intensity or harvest volatility would warrant model refresh. Specific risk factors include ECHA reclassification of additional food contact substances, state-level sugar warning label expansion, and consolidation-driven procurement desk concentration. Recalibration cycles align with material shifts in FDA guidance documents and retail consortium sustainability playbook revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Fried Potato Chips Market
Snacks
Global Snack Food Market
Snacks
Spain Snack Bar Market
Snacks
Snack Bar Market
Snacks
China Snack Bar Market
Snacks
Fruit Jerky Market
Snacks
Low-Calorie Sweet Treats Market
Snacks
Veggie Chips Market
Snacks
South Africa Savory Snacks Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
North America Snack Pellets Market
Snacks
Seafood Snacks Market
Snacks
Global Fruit Snacks Market
Snacks
Nuts and Seeds (Savory Snacks) Market
Snacks
Low-Calorie Savoury Snacks Market
Snacks
Granola Market