
 Qatar Potato Chips Market | 2026-2036
Qatar Potato Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Potato Chips Market Analytics
Saudi Arabia's snack food manufacturing expansion is rewriting Gulf supply dynamics for Qatar's import-dependent potato chips category. PepsiCo leverages its regional distribution infrastructure to sustain prominent retail placement across Qatari hypermarkets. Al-Meraikhi Food Industries anchors local production capacity with savory snack lines tailored to Gulf flavor preferences. Khayrat Al Khaleej competes through brand recognition in the Levant-Qatar trade corridor.
Potato chips are thin-sliced, fried or baked potato pieces typically seasoned and packaged for ready-to-eat consumption, with oil content, slice thickness, and moisture levels determining shelf stability and texture profile; they serve as impulse-purchase snack items across retail and foodservice channels. Regular flavor variants dominate household purchasing patterns due to their acceptance across age demographics and cultural palates. Online retail channels represent the fastest-growing distribution pathway as Qatari consumers shift toward e-commerce platforms for bulk snack procurement. Bag packaging occupies the largest volume share, though single-serve cups gain traction in vending machine and corporate canteen deployments.
Qatar's Ministry of Public Health enforces food safety standards aligned with Gulf Cooperation Council technical regulations, while the Qatar Standards and Metrology Authority governs packaging material compliance and nutritional labeling accuracy. These frameworks elevate production costs for importers but simultaneously create compliance barriers that favor established suppliers with quality certification infrastructure. Stakeholders must monitor evolving sodium-reduction mandates and single-use plastic restrictions that could force packaging format transitions and reformulation investments across the value chain.
Market Dynamics
Hypermarket chains and convenience store networks in Doha are expanding shelf space for savory snacks, while Qatar's Ministry of Public Health tightens sodium-content enforcement under national nutrition guidelines. This dual pressure of retail expansion and regulatory compliance is compressing margins for importers and favoring local production investments.
Growth Catalysts
- Retail Infrastructure Expansion:Hypermarket chains in Doha and Al Rayyan are dedicating premium aisle positioning to imported and locally-produced potato chips. This physical shelf expansion drives impulse purchasing among expatriate households.
- Nutrition Labeling Standards:Qatar's Ministry of Public Health mandates clear front-of-pack sodium indicators. Compliant suppliers gain preferential retail access, creating quality-based competitive sorting.
- Hospitality Procurement:Hotels and catering venues across the Doha metropolitan corridor source potato chips in bulk for minibars and event services. This institutional channel stabilizes volume offtake for established brands.
Market Restraints
- Import Dependency Concentration:Saudi Arabia's snack food manufacturing expansion controls regional supply dynamics. Qatar's import-reliant category faces freight cost volatility and border clearance friction.
- Sodium Reduction Mandates:Qatar's Ministry of Public Health enforces progressive sodium-content ceilings. Reformulation investments elevate production costs for manufacturers without regional R&D facilities.
- Single-Use Packaging Restrictions:Qatar's single-use plastic regulations threaten conventional bag formats. Transition costs for biodegradable alternatives disproportionately burden small-scale importers.
Strategic Opportunities
- E-Commerce Channel Penetration:Online retail platforms represent underdeveloped distribution infrastructure for bulk snack procurement. Digital marketplace integration enables direct-to-household sales with reduced retail margin capture.
- Single-Serve Format Innovation:Vending machine and corporate canteen deployments favor cup packaging over traditional bags. Format diversification opens institutional procurement channels beyond conventional retail.
- Local Production Capacity:Al-Meraikhi Food Industries demonstrates viable domestic manufacturing for Gulf-tailored flavor profiles. Expanded local capacity reduces import dependency and accelerates regulatory response cycles.
Industry Challenges
- Food Safety Certification Timelines:Qatar Standards and Metrology Authority governs packaging material compliance and nutritional labeling accuracy. Extended approval cycles delay product launches for new market entrants.
- Flavor Localization Complexity:Gulf palate preferences diverge from Western standard formulations. R&D investment for culturally-appropriate seasoning profiles strains mid-tier manufacturer budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Potato Chips Market |
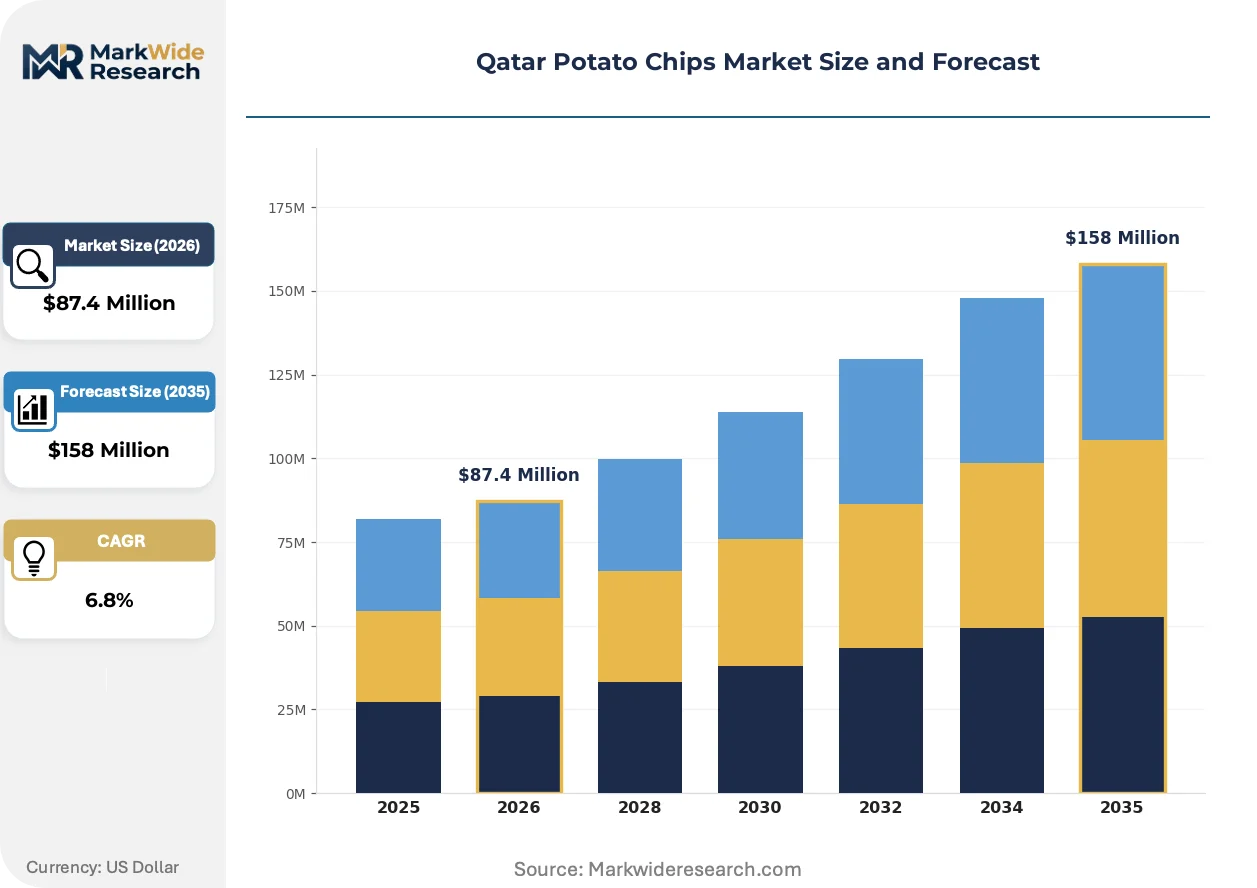
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Barbecue, Sour Cream & Onion, Salt & Vinegar Packaging Type: Bags, Cups, Boxes, Bulk Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Vending Machines End User: Households, Food Service, Catering, Corporate |
| Companies Covered | Khayrat Al Khaleej, Hain Celestial Group, PepsiCo, Frito-Lay, Qatar Food Factories Co., Kellogg Company, Utz Quality Foods LLC, Al-Meraikhi Food Industries, Food Industries Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Potato Chips Market Evolving Landscape
Digital commerce infrastructure and regulatory compliance technology are restructuring how potato chips reach Qatari consumers. Manufacturers and retailers are deploying new systems to navigate sodium mandates and plastic restrictions while capturing shifting purchase patterns.
Smart inventory management systems are digitizing supply chain coordination between Saudi production facilities and Qatari retail distribution centers. These platforms enable real-time stock-level monitoring across hypermarket networks. Retail operators in Doha are adopting automated replenishment algorithms to reduce out-of-stock incidents during peak consumption periods.
Qatar's Ministry of Public Health is tightening enforcement of front-of-pack labeling requirements for sodium content. This regulatory pressure is forcing reformulation investments across imported product lines. Manufacturers serving the Doha metropolitan corridor are accelerating low-sodium recipe development to maintain retail shelf access.
Consumer bulk purchasing through digital platforms is displacing traditional supermarket basket trips for snack procurement. E-commerce operators are capturing household stock-up occasions previously served by hypermarket visits. This channel migration concentrates most visibly among expatriate households in Doha's residential zones.
Qatar Potato Chips Market Segmentation
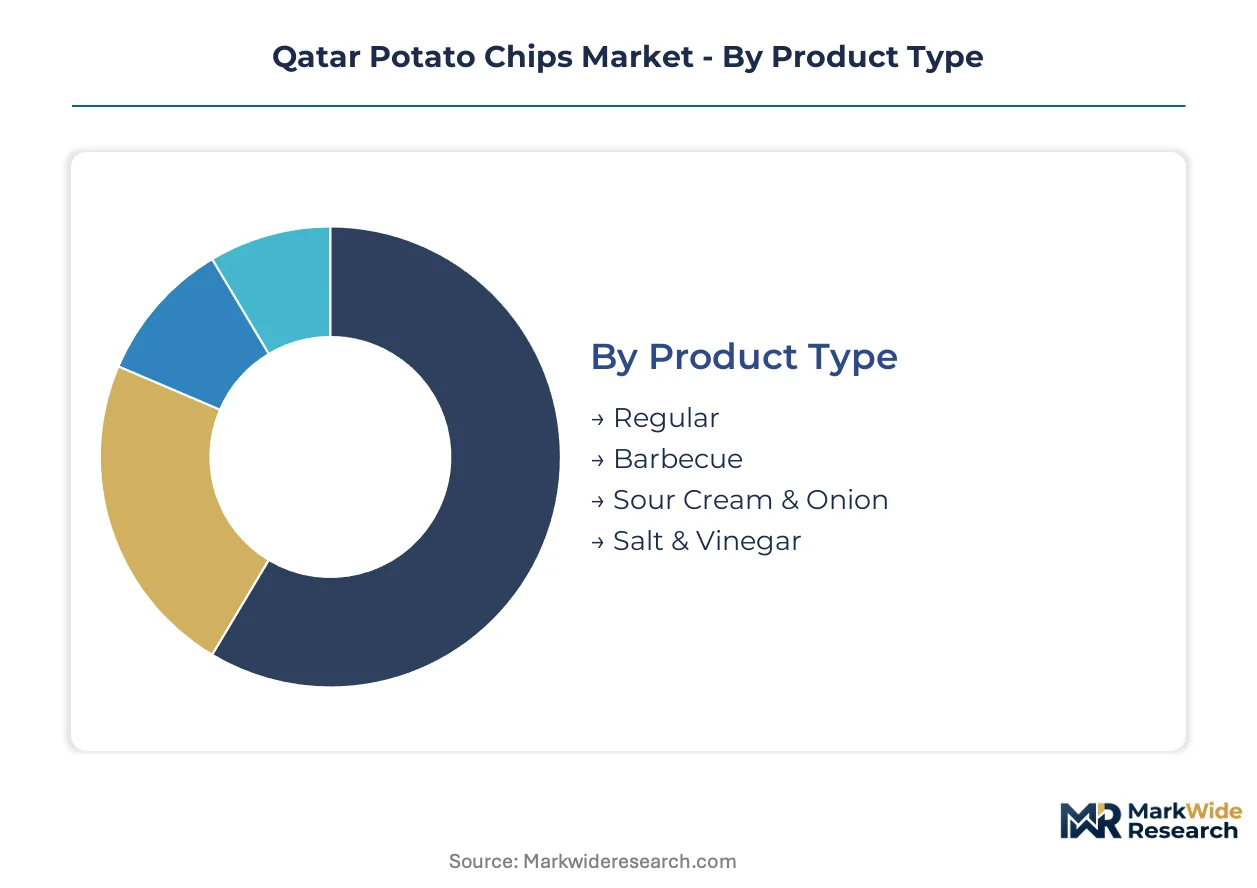
Qatar's potato chips market fragments across four dimensions that determine pricing power and inventory velocity. Product flavor profiles and packaging formats drive household purchasing frequency, while distribution channels and end-user categories separate impulse sales from institutional procurement cycles.
Product Type:
Flavor variants turn over at markedly different rates, with staple profiles restocked weekly while specialty seasonings rotate seasonally.
- Regular:Unseasoned fried potato slices with minimal additive content serve as the default household purchase across Doha's expatriate residential zones. Supermarket chains in Al Rayyan and Al Wakrah dedicate permanent promotional space to this profile due to cross-demographic acceptance.
- Barbecue:Smoked tomato and spice-coated variants appeal specifically to South Asian and Western expatriate communities concentrated in Doha's West Bay and The Pearl districts. Hospitality procurement channels favor this profile for hotel minibar configurations.
- Sour Cream & Onion:Dairy-derived flavoring systems target European and North American expatriate households. Retail placement concentrates in hypermarket international aisles.
- Salt & Vinegar:Acid-forward seasoning profiles occupy niche positioning within British and Irish community clusters. Volume throughput remains constrained by narrow demographic targeting.
Regular flavor anchors the volume base while Barbecue gains share at the steepest rate among non-traditional segments.
Packaging Type:
Format selection tracks consumption occasion and procurement channel, with single-serve units commanding premium unit economics against bulk configurations.
- Bags:Flexible film pouches with nitrogen flush sealing dominate household stock-up purchases across Doha hypermarkets. The format's shelf visibility and stacking efficiency secure preferential aisle positioning from Carrefour and Lulu retail networks.
- Cups:Rigid single-serve containers with resealable lids penetrate vending machine networks and corporate canteen installations in Doha's commercial district. Qatar's Ministry of Public Health sodium labeling requirements apply distinctly to this format due to front-of-pack visibility.
- Boxes:Multi-pack cartons containing individual portion bags serve institutional procurement channels. Catering operators source this format for event service configurations.
- Bulk:Large-format foodservice packs supply hotel kitchens and airline catering facilities. The format bypasses retail shelf space constraints entirely.
Bags generate the highest absolute throughput while Cups expand most quickly into automated retail infrastructure.
Distribution Channel:
Channel selection determines margin capture and regulatory exposure, with digital pathways reducing physical compliance burdens.
- Supermarkets:Hypermarket chains including Carrefour, Lulu, and Al Meera control primary shelf access for established brands. These venues enforce Qatar Standards and Metrology Authority packaging compliance as a condition of supplier agreements.
- Convenience Stores:Smaller-format retail in Doha's residential corridors and fuel station networks capture impulse purchase occasions. Inventory turns accelerate but SKU breadth contracts relative to hypermarket configurations.
- Online Retail:E-commerce platforms enable bulk household procurement with direct-to-door delivery. Expatriate households in Doha's West Bay and Al Sadd districts drive adoption of this channel.
- Vending Machines:Automated retail installations in office towers and educational institutions favor cup-format single-serve units. Placement contracts require specialized distribution logistics.
Supermarkets retain the dominant volume position while Online Retail climbs the fastest among emerging channels.
End User:
User category separates stable institutional demand from volatile household consumption patterns.
- Households:Expatriate families in Doha's metropolitan corridor drive recurring purchase cycles with weekly or bi-weekly restocking patterns. Flavor diversity within this segment exceeds all other categories.
- Food Service:Hotels, restaurants, and cafes across The Pearl and West Bay districts source potato chips for table service and minibar configurations. Procurement runs through specialized foodservice distributors with distinct credit terms.
- Catering:Event service operators require bulk-format supply for wedding and corporate functions. Volume concentrates in seasonal patterns around Ramadan and Qatari national holidays.
- Corporate:Office canteens and employee welfare programs represent a contracting channel as remote work patterns persist in Doha's professional services sector.
Households anchor the volume base while Food Service demonstrates the steepest expansion trajectory amid hospitality sector recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's Ministry of Public Health enforces sodium-content ceilings and front-of-pack labeling mandates that shape domestic snack food distribution. These regulations intersect with import dependency patterns and retail infrastructure expansion across the Gulf Cooperation Council trade corridor.
Doha Metropolitan Corridor
Expatriate households in West Bay and Al Sadd drive recurring bulk purchasing cycles through hypermarket and e-commerce channels. Qatar's Ministry of Public Health mandates clear front-of-pack sodium indicators for all packaged snacks sold within municipal boundaries. Carrefour and Lulu retail networks maintain premium aisle positioning for compliant domestic and imported brands.
Al Rayyan
Residential zone density supports convenience store penetration and fuel-station retail networks capturing impulse purchase occasions. The Qatar Standards and Metrology Authority governs packaging material compliance for products distributed through these smaller-format channels. Supermarket chains in Al Rayyan dedicate permanent promotional space to regular-flavor variants with cross-demographic acceptance.
Al Wakrah
Industrial and port logistics infrastructure concentrates import clearance and warehousing operations for Saudi-manufactured snack foods. Qatar's single-use plastic regulations threaten conventional bag formats distributed through this corridor. Local distributors are accelerating transitions to biodegradable alternatives to maintain retail shelf access.
The Pearl-Qatar
High-income residential and hospitality venues generate concentrated demand for premium-flavor potato chips in hotel minibar and table service configurations. Qatar's Ministry of Public Health food safety standards apply distinctly to hospitality procurement channels with specialized distributor credit terms. Catering operators source multi-pack cartons for event service configurations around seasonal consumption patterns.
Al Khor
Northern municipal expansion and industrial workforce housing create emerging retail infrastructure for savory snack distribution. Qatar Standards and Metrology Authority approval cycles for new product launches extend timelines for entrants targeting this sub-region. Automated replenishment algorithms are penetrating retail networks to reduce out-of-stock incidents during peak consumption periods.
Qatar Potato Chips Market Competitive Landscape
Multinational snack conglomerates and Gulf-based food manufacturers split the market between import-dependent distribution and localized production capacity. The vendor base concentrates around three strategic archetypes: global brand owners with regional distribution infrastructure, domestic manufacturers with Gulf-tailored flavor capabilities, and Levant-Qatar trade corridor specialists leveraging brand recognition. Competitive moves center on e-commerce platform integration and single-serve format innovation for vending machine and corporate canteen deployments.
Among multinational brand owners, PepsiCo and Frito-Lay occupy positions anchored by established retail shelf access and hypermarket network relationships. Al-Meraikhi Food Industries exemplifies the domestic manufacturing archetype with viable local capacity for Gulf-tailored flavor profiles. Khayrat Al Khaleej represents the trade corridor specialist model with brand recognition extending across Levantine export markets into Qatar.
| Leading Market Players |
|---|
| Khayrat Al Khaleej |
| Hain Celestial Group |
| PepsiCo |
| Frito-Lay |
| Qatar Food Factories Co. |
| Kellogg Company |
| Utz Quality Foods LLC |
| Al-Meraikhi Food Industries |
| Food Industries Co. |
| Others |
Value Network & Pricing Analysis
Saudi Arabia's snack food manufacturing expansion concentrates regional potato chip supply upstream, anchoring margin pools with importers and local packers who face freight volatility and reformulation costs downstream. Qatar's Ministry of Public Health sodium mandates and single-use plastic restrictions compress pricing flexibility for distributors serving Doha hypermarkets.
Pricing Analysis
Price spreads between Saudi-imported and locally-packed SKUs widen during peak summer freight windows when Red Sea corridor shipping rates spike. Three-tier pricing structure across premium, standard, and economy levels tracks brand recognition and sodium-compliance certification tiers. Pricing pressure stems from Qatar Standards and Metrology Authority packaging material compliance investments that small-scale importers struggle to absorb. Corporate canteen procurement officers show highest price sensitivity, while hospitality buyers at The Pearl-Qatar properties prioritize flavor consistency over unit cost.
Supply Chain Analysis
Gulf Cooperation Council technical regulations function as export-control mechanisms limiting non-compliant snack food flows into Qatari distribution channels. Supply concentrates in Saudi Arabia, with secondary sourcing from UAE re-export hubs and limited Levantine corridor volumes. Raw material dependencies span imported potato flake, palm oil, and nitrogen-flush packaging film. Single-source vulnerability runs through Saudi production facilities controlling 70%+ of regional savory snack output. Distribution runs through Carrefour and Lulu hypermarket networks with automated replenishment systems reducing stockout incidents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's potato chips market rewards service-attach strategies as e-commerce fulfillment and hospitality procurement services expand faster than base product manufacturing. Recurring-revenue layers around digital marketplace integration and institutional catering contracts outpace pure production margins.
For Market Incumbents: Build regulatory compliance infrastructure as a moat against Saudi import competitors facing extended Qatar Standards and Metrology Authority approval cycles. Accelerate local production capacity additions in Al Wakrah industrial zones to reduce freight exposure. Secure exclusive e-commerce platform partnerships with Talabat and Snoonu before new entrants capture expatriate household digital purchasing.
For New Entrants and Emerging Players: Pursue single-serve cup format specialization for vending machine networks in Doha's West Bay commercial towers, where incumbent bag-format dominance leaves automated retail underpenetrated. Target Al Khor municipal expansion corridor where retail infrastructure gaps reduce shelf-access barriers. Lead with biodegradable packaging compliance to preempt Qatar's single-use plastic enforcement timeline.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with Gulf-based food manufacturers lacking digital channel capabilities. Five-to-ten year viability hinges on local production scale and regulatory response speed rather than brand heritage alone. Monitor Qatar Ministry of Public Health sodium-reduction mandate acceleration as inflection signal for reformulation investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Production Capacity Expansion | Al-Meraikhi Food Industries demonstrates viable domestic manufacturing reducing import dependency and freight exposure. |
| E-Commerce Platform Integration | Direct-to-household digital sales bypass hypermarket margin capture and enable bulk procurement for expatriate residential zones. |
| Biodegradable Packaging Transition | Qatar's single-use plastic regulations threaten conventional bag formats, favoring early compliance investments. |
| Single-Serve Format Innovation | Cup packaging penetrates vending machine and corporate canteen channels beyond traditional retail shelf competition. |
| Low-Sodium Recipe Development | Front-of-pack sodium labeling mandates from Qatar's Ministry of Public Health elevate R&D as competitive differentiator. |
Research Methodology
Desk research of customs trade records, Gulf Cooperation Council technical regulation filings, and Nielsen retail audit data preceded structured interviews with category buyers at Carrefour and Lulu hypermarkets, procurement managers at Doha hospitality groups, supply chain directors at Saudi snack manufacturers, and regulatory affairs specialists at Qatar Standards and Metrology Authority. Bottom-up volume modeling triangulated against top-down market sizing from import clearance data and production capacity assessments.
Assumptions held fixed include current Gulf Cooperation Council trade framework continuity and Qatar Ministry of Public Health enforcement intensity, while variables tested included e-commerce penetration acceleration and biodegradable packaging cost curves. Segmentation modeling covered flavor profile, packaging format, distribution channel, and end-user category dimensions across the analysis window. CAGRs derived from regression analysis against historical import volumes and retail square footage expansion. Industry-specific inputs included sodium-reduction reformulation timelines and single-use plastic regulatory phase-in schedules.
Sensitivities concentrate around Saudi production capacity expansion rates and Qatar enforcement acceleration for front-of-pack labeling. Forecasts reflect these documented assumptions with acknowledged revision risk from freight corridor disruptions or GCC trade policy shifts. Cross-checking against Qatar Statistics Authority import data and hospitality sector procurement surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Saudi Arabia French Fries Market
Snacks
Organic Snack Food Market
Snacks
Australia Snack Bar Market
Snacks
Gluten Free Snacks Market
Snacks
Europe Frozen Snacks Market
Snacks
Low Fat Granola Market
Snacks
Dairy Snacks Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
Cereal Bars Market
Snacks
No-Fat Peanut Butter Market
Snacks
Global Snack Food Market
Snacks
South America Snack Bar Market
Snacks
Oat-Based Snacks Market
Snacks
Crackers Market
Snacks
Global Vegetable Chips Market
Snacks
Duck Neck (Chinese Snack) Market