
 Specialty Snacks Market | 2026-2036
Specialty Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Snacks Market Outlook
Millennial and Gen-Z households is reorganizing category purchasing away from legacy mass-market brands toward premium functional formats. Nestlé leverages its R&D infrastructure to sustain innovation velocity across plant-based snack lines. PepsiCo anchors North American shelf space through direct-store-delivery networks that control convenience channel access. Mondelez International differentiates via European chocolate-hybrid specialty portfolios that occupy premium price tiers.
Specialty snacks comprise differentiated food products manufactured with non-standard ingredients, specialized processing techniques such as freeze-drying or cold-pressing, and elevated nutritional or sensory profiles targeting specific consumer occasions beyond conventional satiety. The category spans granola bars formulated with ancient grains, air-dried fruit with no added sugars, and vegetable-based chips produced through extrusion or vacuum-frying methods designed to deliver texture parity with fried alternatives at reduced oil content. Specialty chips currently lead volume contribution within product type segmentation due to savory occasion frequency and format familiarity, while vegan snacks represent the fastest-expanding margin pool as ingredient cost premiums compress with scale. Single-serve packaging dominates impulse and on-the-go channels, though resealable bags capture higher household penetration and repeat purchase rates in specialty retail.
FDA nutrition labeling rules and EFSA health claims frameworks shape permissible on-pack messaging and constrain speed-to-market for functional positioning. EU Green Deal packaging directives and emerging state-level extended producer responsibility laws in California and New York are forcing material transitions that raise unit economics for flexible film formats. Stakeholders must monitor regulatory divergence between jurisdictions and decide whether to regionalize packaging specifications or absorb compliance costs through unified global SKUs.
Market Dynamics
Clean-label mandates from FDA and EFSA are forcing simultaneous reformulation of ingredient decks and packaging specifications, compressing margin structures while accelerating R&D cycles across multinational portfolios.
Growth Catalysts
- EFSA Health Claims Framework:Permissible on-pack functional messaging is expanding positioning space for protein-fortified and gut-health formats in European retail channels.
- Freeze-drying Technology:Capital investment in low-temperature dehydration is preserving volatile micronutrients and enabling clean-label fruit snacks without added humectants.
- Urban China:Tier-1 city consumers are trading up from conventional packaged goods to premium imported specialty formats with transparent supply chain documentation.
Market Restraints
- Oil Price Volatility:Sunflower and avocado oil input costs fluctuate with Black Sea supply disruptions, squeezing unit economics for vacuum-fried vegetable chips.
- Flexible Film Concentration:Three Southeast Asian converters dominate global supply of high-barrier snack packaging, creating single-source vulnerability for resealable formats.
- Moisture Migration Limits:Technical barriers prevent clean-label shelf-stable products from achieving parity texture with fried alternatives beyond 90-day windows.
Strategic Opportunities
- India Tier-2 Cities:Underpenetrated distribution infrastructure in Ahmedabad, Pune, and Chandigarh offers first-mover positioning for premium snack entrants before modern retail saturation.
- EU Green Deal Packaging Directives:Mandatory recycled content thresholds are creating compliant-material premiums that reward early adopters with preferred shelf placement.
- Direct-to-Consumer Subscriptions:Curated monthly boxes bypass slotting fee structures and capture lifetime value data for personalization algorithms.
Industry Challenges
- Clean-Label R&D Talent:Formulation chemists with expertise in natural preservation systems command premium compensation and limited availability slows pipeline velocity.
- Dual Jurisdiction Compliance:Divergent FDA and EFSA additive approval lists force regional SKU proliferation or lowest-common-denominator formulation compromises.
- Legacy ERP Integration:Batch-level traceability requirements for EU Green Deal accountability collide with decades-old manufacturing execution systems at mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Snacks Market |
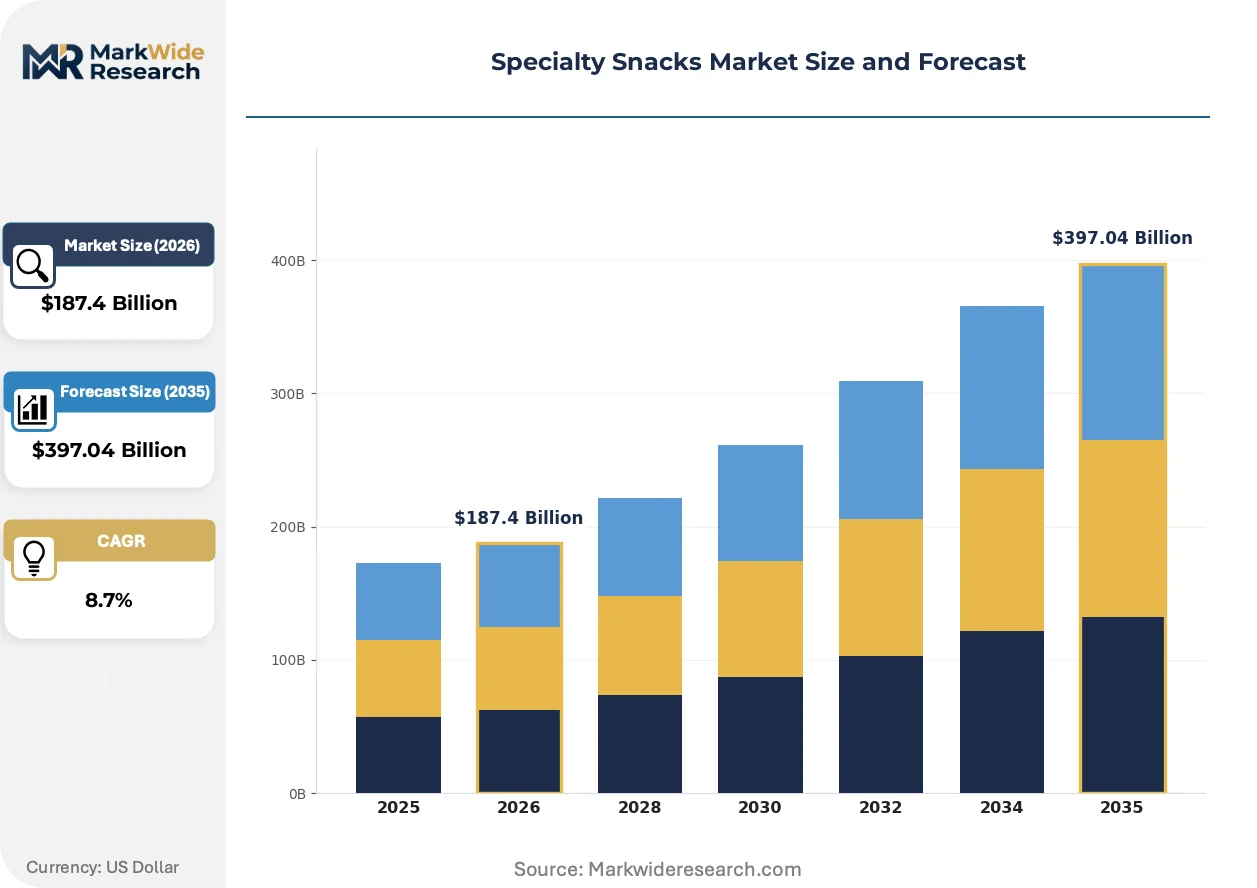
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Dried Fruit, Specialty Chips, Vegan Snacks Flavor Profile: Sweet, Savory, Spicy, Exotic Packaging Type: Single-Serve, Resealable Bags, Bulk Packaging, Gift Packs Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Convenience Stores |
| Companies Covered | Nestlé, Kraft Heinz, PepsiCo, Calbee, Conagra Brands, Mondelez International, Mars, Utz Brands, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Snacks Market Strategic Shifts
Processing technology convergence and regulatory packaging mandates are rewriting cost structures while consumer data capture through digital channels is restructuring go-to-market economics.
Precision fermentation-derived proteins are displacing conventional isolates in functional snack bars. Clean-label buyers in United States coastal metros are adopting these formats at double-digit rates. This displacement is compressing commodity soy protein margins while opening premium positioning for fermentation suppliers with carbon accounting credentials.
California's extended producer responsibility legislation is mandating post-consumer recycled content minimums for flexible snack packaging. Brand owners face material cost premiums of 15-30 percent versus virgin films. Premium private-label specialists with sustainability-forward positioning are absorbing these costs to secure differentiated shelf space in specialty retail.
Household purchasing of specialty snacks through quick-commerce platforms is fragmenting traditional supermarket basket economics. Young urban consumers in Berlin, Shanghai, and New York City now source impulse formats through 15-minute delivery apps. This channel shift is forcing CPG giants to rebuild trade promotion strategies around algorithmic visibility rather than end-cap placement fees.
Specialty Snacks Market Segmentation
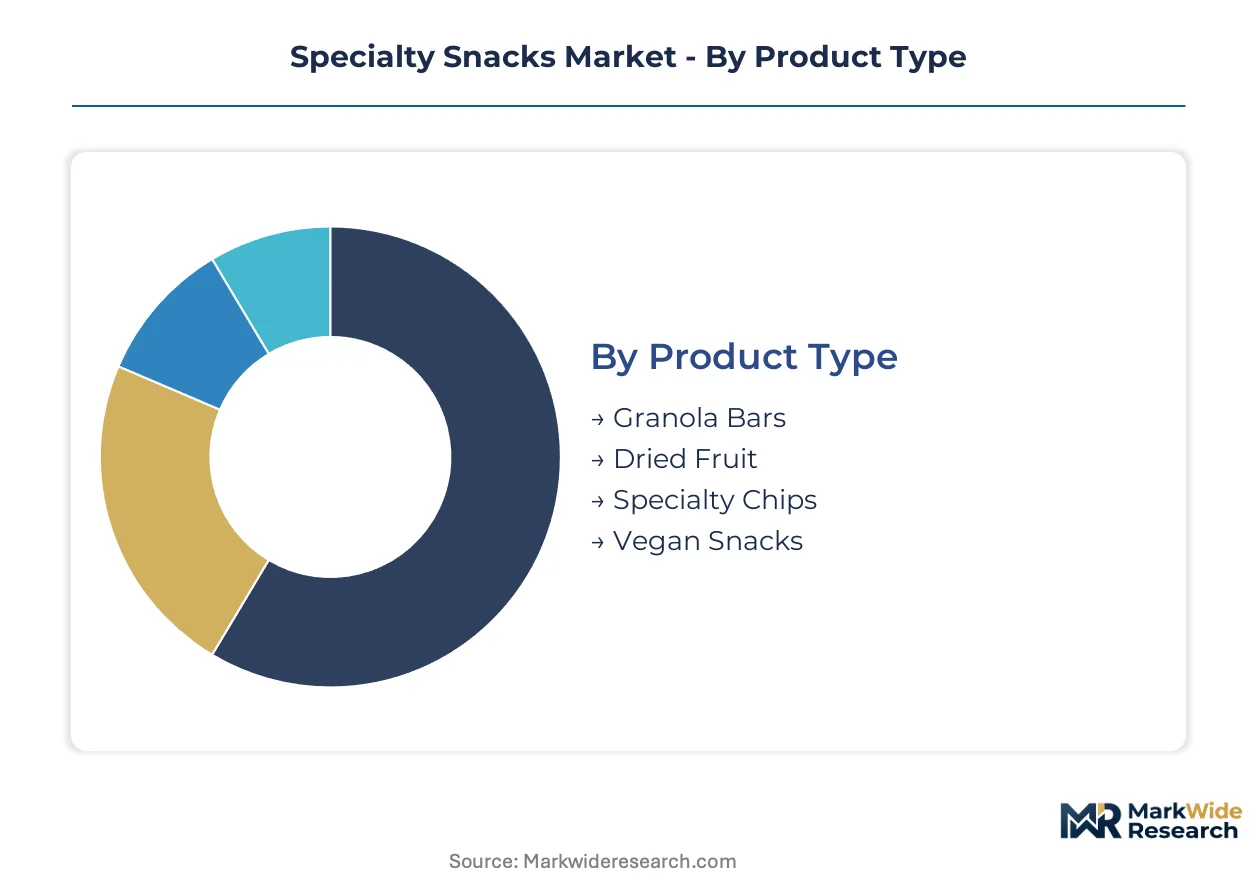
Specialty snack manufacturers must navigate divergent consumer occasions and channel economics simultaneously. Granola bars compete against fresh bakery alternatives in morning routines. Dried fruit formats battle conventional confectionery for shelf space. Understanding substitution dynamics across each dimension determines portfolio prioritization and R&D resource allocation.
Product Type:
Specialty chips face the most acute substitution pressure from conventional fried alternatives that dominate volume share and price positioning in mainstream retail.
- Specialty Chips:Vacuum-fried and air-popped formats using root vegetables, legumes, or alternative grains achieve texture parity at reduced oil content. Demand concentrates in United States convenience channels where health-positioned savory options capture trade-up occasions from standard potato chips.
- Vegan Snacks:Plant-based cheese puffs, jerky alternatives, and protein-fortified crisps leverage precision fermentation and extrusion technologies. Germany and United Kingdom retail buyers are expanding shelf sets for these formats as EFSA clean-label frameworks validate protein content claims.
- Granola Bars:Ancient grain and seed-based formulations with reduced sugar binders serve athletic and workplace snacking occasions.
- Dried Fruit:Freeze-dried and air-dried formats without added humectants target lunchbox and travel snacking segments.
Specialty chips retain volume leadership; vegan snacks hold the steepest expansion curve.
Flavor Profile:
Cost tier stratification separates commodity-positioned offerings from premium formats commanding ingredient premiums and specialized processing.
- Savory:Umami-forward profiles using nutritional yeast, fermented seasonings, and smoked salts dominate afternoon snacking occasions in urban China and United States coastal markets. These formats justify price premiums through clean-label positioning that conventional savory snacks cannot match.
- Sweet:Reduced-sugar formulations using date paste, monk fruit, and allulose target parental purchasing for children's lunchboxes. FDA added sugar labeling rules have accelerated reformulation investment across North American portfolios.
- Spicy:Chili-forward heat levels calibrated to regional tolerance thresholds serve adult snacking occasions.
- Exotic:Yuzu, matcha, and cardamom profiles target experimental purchasing in specialty retail channels.
Savory formats capture the highest household penetration; exotic profiles deliver the steepest expansion trajectory.
Packaging Type:
Application context determines format selection, with impulse occasions demanding portability and household consumption requiring preservation integrity.
- Single-Serve:Individual portion formats of 28-42 grams serve vending, airline, and hospitality channels where portion control and food safety protocols dominate procurement specifications. United States institutional buyers are mandating these formats for school and corporate feeding programs.
- Resealable Bags:Multi-serve pouches with zipper closures and high-barrier films extend shelf life for premium products with elevated fat content. California's extended producer responsibility legislation is forcing material transitions that raise unit costs for these formats.
- Bulk Packaging:Foodservice-sized formats target hospitality and workplace pantry channels.
- Gift Packs:Curated assortments in premium presentation packaging serve seasonal and corporate gifting occasions.
Resealable bags retain the highest repeat purchase rates; single-serve formats are expanding most quickly through quick-commerce channels.
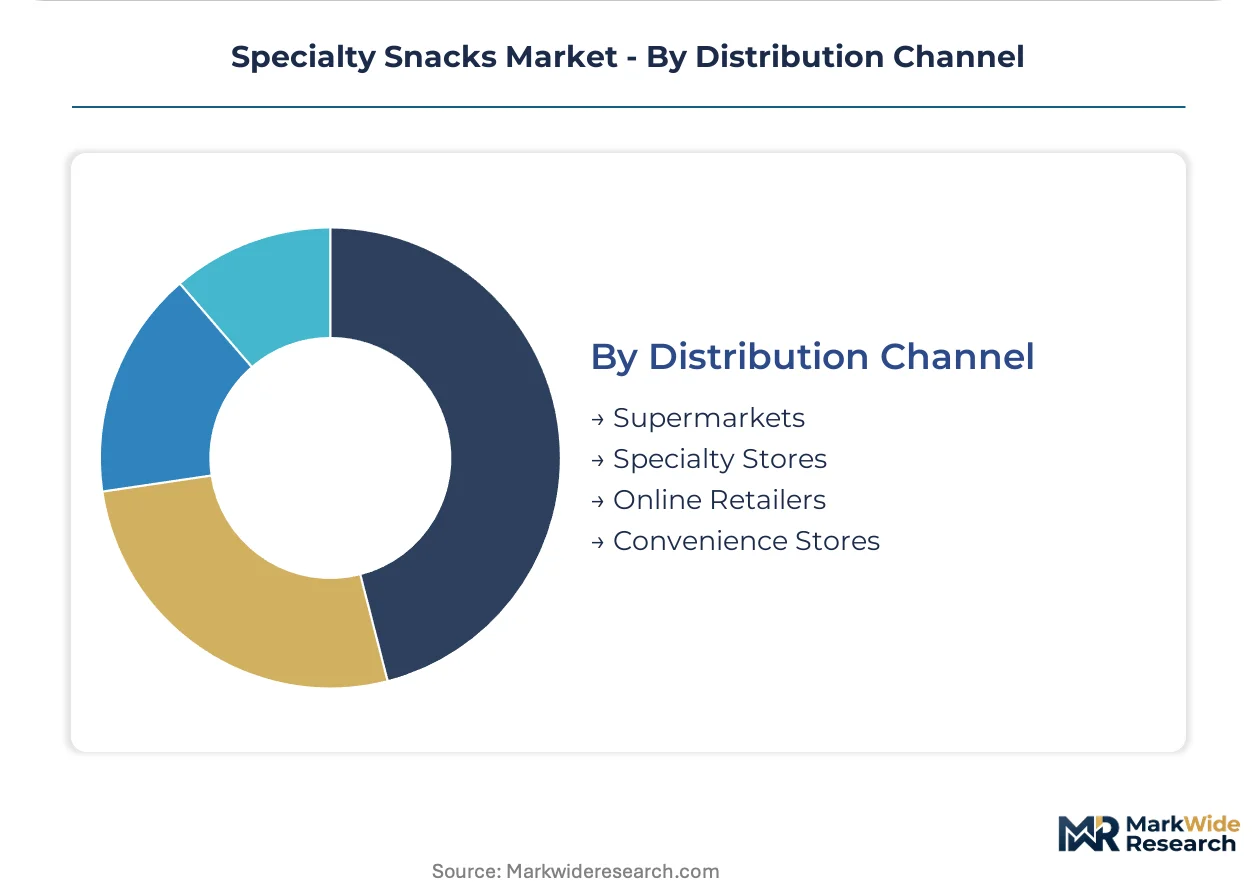
Distribution Channel:
Customer type stratification separates mass-market penetration from premium positioning, with channel selection determining margin structure and brand equity development.
- Specialty Stores:Curated independent retailers and natural food chains provide discovery environments for emerging brands. These channels absorb price premiums for clean-label and sustainability-certified formats that mainstream supermarkets cannot support.
- Online Retailers:Direct-to-consumer platforms and marketplace aggregators enable subscription models and personalization algorithms. Berlin, Shanghai, and New York City consumers source impulse formats through 15-minute delivery apps, fragmenting traditional basket economics.
- Supermarkets:Mass retail chains demand slotting fees and promotional support that favor scaled manufacturers.
- Convenience Stores:High-velocity locations prioritize grab-and-go formats with extended shelf life.
Specialty stores retain the highest margin contribution per unit; online retailers are gaining share fastest through algorithmic visibility optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban professional households in tier-1 cities across multiple continents are trading up from conventional packaged goods to premium functional formats with transparent supply chain documentation.
United States
Millennial and Gen-Z consumers in coastal metros are shifting procurement toward plant-based and clean-label specialty formats. FDA nutrition labeling rules and added sugar disclosure requirements are accelerating reformulation investment across domestic portfolios. Chicago and Austin host emerging clusters of precision fermentation suppliers serving functional snack bar manufacturers.
Germany
Discerning buyers in Berlin and Munich are expanding shelf space for vegan snack formats with EFSA-validated protein content claims. EU Green Deal packaging directives mandating recycled content thresholds are raising unit economics for flexible film formats. The Baden-Württemberg region contains specialized packaging converters developing compliant high-barrier materials.
China
Tier-1 city consumers in Shanghai and Beijing are sourcing premium imported specialty snacks with documented supply chain transparency. SAMR food labeling standards and dual carbon goals are reshaping permissible on-pack messaging and material specifications. The Yangtze River Delta hosts contract manufacturers scaling freeze-drying capacity for clean-label fruit snack exports.
India
Affluent households in Mumbai and Delhi-NCR are adopting premium snacking occasions previously served by conventional confectionery. FSSAI clean-label frameworks and plastic waste management rules are forcing material transitions and ingredient deck reformulation. Ahmedabad and Pune present underpenetrated distribution infrastructure for first-mover premium entrants before modern retail saturation.
United Kingdom
Health-positioned consumers in London and Manchester are driving demand for reduced-sugar granola bars and air-dried fruit formats. EFSA health claims frameworks and emerging extended producer responsibility legislation are constraining speed-to-market for functional positioning. The Midlands region hosts co-manufacturing facilities specializing in ancient grain extrusion for private-label specialty brands.
Specialty Snacks Market Competitive Environment
Player mix skews toward multinational CPG conglomerates with diversified snack portfolios alongside emerging specialists in plant-based and clean-label formats. Market structure exhibits tiered concentration where scale leaders control mainstream retail shelf space while niche players capture premium positioning in specialty channels. Three strategic archetypes dominate: legacy conglomerates leveraging R&D infrastructure, regional specialists with localized taste expertise, and venture-backed insurgents targeting functional occasion expansion. Competitive dynamics center on portfolio diversification into plant-based lines and strategic partnerships with precision fermentation ingredient suppliers.
Within the legacy conglomerate tier, Nestlé, PepsiCo, and Mondelez International represent contrasting geographic and capability emphases. Nestlé exemplifies European-anchored innovation velocity across plant-based snack lines. PepsiCo occupies a position controlling North American convenience channel access through direct-store-delivery networks. Mondelez International sits within the premium chocolate-hybrid specialty portfolio segment with European market concentration.
| Leading Market Players |
|---|
| Nestlé |
| Kraft Heinz |
| PepsiCo |
| Calbee |
| Conagra Brands |
| Mondelez International |
| Mars |
| Utz Brands |
| General Mills |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal packaging directives gate both supplier qualification and price differentiation simultaneously, mandating recycled content thresholds that raise unit economics for flexible film formats while rewarding early adopters with preferred shelf placement in premium retail channels.
Pricing Analysis
Technology-generation pricing gaps separate freeze-dried formats from conventional dehydration methods and emerging precision fermentation ingredients. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with EFSA-validated functional claims commanding ingredient premiums. Pricing pressure stems from oil price volatility in Black Sea supply regions, squeezing vacuum-fried vegetable chip margins. Mass-market retail buyers exhibit highest price sensitivity, while specialty channel purchasers absorb premiums for clean-label positioning.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints in Southeast Asian hubs elevate inbound logistics costs for flexible film packaging. Raw material sourcing draws from Thailand, Vietnam, and Indonesia for high-barrier snack films, with sunflower and avocado oil inputs anchored in Black Sea and Latin American origins. Single-source vulnerability concentrates among three Southeast Asian converters for resealable formats. Distribution runs through direct-store-delivery networks controlling North American convenience channel access alongside quick-commerce platforms fragmenting urban basket economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fresh bakery alternatives and conventional confectionery represent persistent substitute threats that specialty snack incumbents must navigate through occasion-based positioning and texture parity investments.
For Market Incumbents: Secure R&D talent in natural preservation systems to accelerate clean-label pipeline velocity against emerging plant-based specialists. Anchor shelf space through direct-store-delivery network control in North American convenience channels, defending against quick-commerce platform fragmentation. Prioritize backward integration into precision fermentation ingredient supply to capture carbon accounting premiums. For New Entrants and Emerging Players: EFSA health claims fast-track certification opens positioning space for protein-fortified formats in European retail. Target tier-2 Indian cities including Ahmedabad and Pune before modern retail saturation, leveraging underpenetrated distribution infrastructure. Pursue curated direct-to-consumer subscription models to bypass slotting fee structures and capture lifetime value data. For Investors and Strategic Acquirers: California extended producer responsibility legislation reshapes the acquisition landscape toward packaging-converter capabilities in compliant high-barrier materials. Five-to-ten year viability favors mid-tier producers with batch-level traceability systems already integrated. Watch for EU Green Deal enforcement tightening as the signal indicating material cost inflection and consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Secures carbon-accounted protein supply for functional snack bar expansion. |
| Compliant Packaging Converter Acquisition | Captures EU Green Deal recycled-content premiums in flexible film formats. |
| Freeze-Drying Capacity Expansion | Preserves volatile micronutrients for clean-label fruit snack differentiation. |
| Direct-to-Consumer Platform Launch | Bypasses slotting fees while building personalization algorithm data assets. |
| Tier-2 India Distribution Buildout | Establishes first-mover positioning in underpenetrated urban markets. |
Study Parameters
The analysis maps specialty chips, vegan snacks, granola bars, and dried fruit segments, each validated through category buyers at specialty retailers, brand managers at CPG conglomerates, procurement leads at packaging converters, and formulation chemists at co-manufacturing facilities. Primary interviews combined with secondary validation from FDA filing databases, EFSA health claims registers, EU packaging directive compliance records, and Nielsen retail audit data. Bottom-up volume builds and top-down macroeconomic checks triangulate output consistency.
Consistency checks validated segment-level outputs against external benchmarks including customs trade flows and industry association production estimates. The projection horizon spans product type, flavor profile, packaging format, and distribution channel dimensions, with CAGRs derived from elasticity-adjusted demand curves and input cost trajectory modeling. Freeze-drying technology adoption curves and quick-commerce penetration rates served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable regulatory enforcement and commodity price assumptions; material deviation in oil supply disruptions or packaging mandate timelines would warrant model refresh. Practitioners should keep alternative scenarios live as EFSA health claims framework interpretations and state-level extended producer responsibility implementations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Snack Bar Market
Snacks
China Snack Bar Market
Snacks
Sweet Potato Fries Market
Snacks
Protein Crisps Market
Snacks
France Energy Bar Market
Snacks
Potato Chips Market
Snacks
Pretzel Salts Market
Snacks
Popcorn Market
Snacks
Better for You Snacks Market
Snacks
Cereal Bars Market
Snacks
Protein Bars Market
Snacks
Europe Cereal Bar Market
Snacks
Low Calorie Crackers Market
Snacks
South America Snack Bar Market
Snacks
Organic Chips Market
Snacks
Low Fat Granola Market