
 Savory Snacks Market | 2026-2036
Savory Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Savory Snacks Market Intelligence
The capital-intensity gap between multinational conglomerates and regional specialists is collapsing as co-manufacturing networks democratize extrusion and flavor-coating capabilities. PepsiCo leverages its direct-store-delivery infrastructure to control impulse-buy placement in North American convenience channels. Intersnack Group anchors its competitiveness through private-label partnerships and regional brand portfolios across Central Europe. Mondelēz International differentiates via precision seasoning technologies and clean-label ingredient sourcing for premium lines.
Savory snacks comprise shelf-stable, seasoned food products manufactured through frying, baking, or extrusion of grains, tubers, legumes, or nuts, typically formulated with salt, oil, and flavor systems to deliver palatability in portable formats. Their primary commercial purpose is to serve as affordable, ready-to-eat consumption occasions between meals or during social and entertainment activities. Chips retain the largest revenue pool due to established production economics and universal flavor acceptance, though popcorn competes aggressively for health-positioned shelf space with air-popped and low-oil variants. Nuts command premium price tiers as protein-forward positioning attracts health-conscious consumers, while pretzels occupy a mature, slower-rotation niche concentrated in specific regional markets.
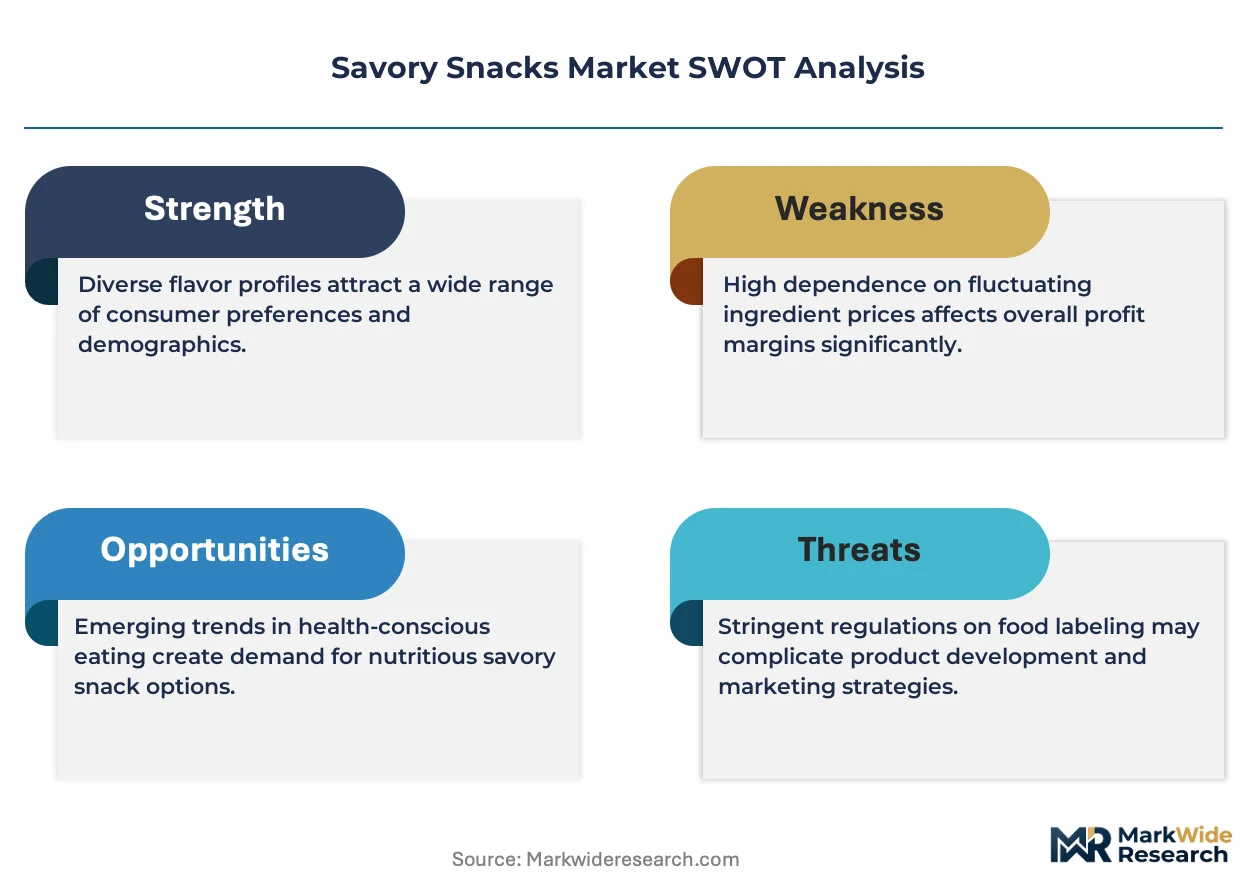
FDA sodium guidance and EU nutrient profiling models for front-of-pack labels are reshaping permissible salt and saturated fat levels, compelling manufacturers to reformulate base recipes or risk retail delisting. BIS fortification standards and FSSAI labeling mandates in India add complexity for entrants targeting that growth corridor. Stakeholders must monitor how regional regulator divergence on ultra-processed food classifications affects portfolio allocation between developed and emerging markets.
Market Dynamics
Co-manufacturing networks are collapsing the capital-intensity gap between multinational conglomerates and regional specialists, democratizing extrusion and flavor-coating capabilities that once anchored competitive moats.
Growth Catalysts
- Urban Millennial Demand:India's metropolitan centers concentrate premium and regional flavor adoption, with convenience stores expanding shelf space for on-the-go formats.
- FDA Sodium Guidance:Recipe reformulation mandates create first-mover advantages for manufacturers achieving compliant salt reduction ahead of enforcement timelines.
- Air-Popped Extrusion:Low-oil processing technologies enable health-positioned popcorn variants to capture shelf space from traditional fried alternatives.
Market Restraints
- Input Cost Volatility:Edible oil and potato supply fluctuations compress margins for frying-dependent product lines.
- Regulatory Divergence:Ultra-processed food classification inconsistencies between EU nutrient profiling models and FDA frameworks complicate portfolio allocation decisions.
- Technical Sodium-Fat Tradeoffs:Salt reduction technologies compromise mouthfeel and shelf stability in baked grain formats.
Strategic Opportunities
- Clean-Label Convergence:Precision seasoning technologies combined with transparent sourcing claims unlock premium price tiers in North American convenience channels.
- Front-of-Pack Tailwind:EU labeling requirements favor manufacturers with pre-compliant nutrient portfolios, creating delisting risk for laggards.
- Quick-Service Restaurant Penetration:Impulse-buy placement partnerships with drive-through and grab-and-go formats expand consumption occasions beyond traditional retail.
Industry Challenges
- Flavor Chemist Scarcity:Reformulation expertise for salt-fat reduction without palatability loss commands premium compensation and extended recruitment cycles.
- Co-Manufacturing Integration:Quality consistency across distributed extrusion networks requires capital-intensive audit and certification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Savory Snacks Market |
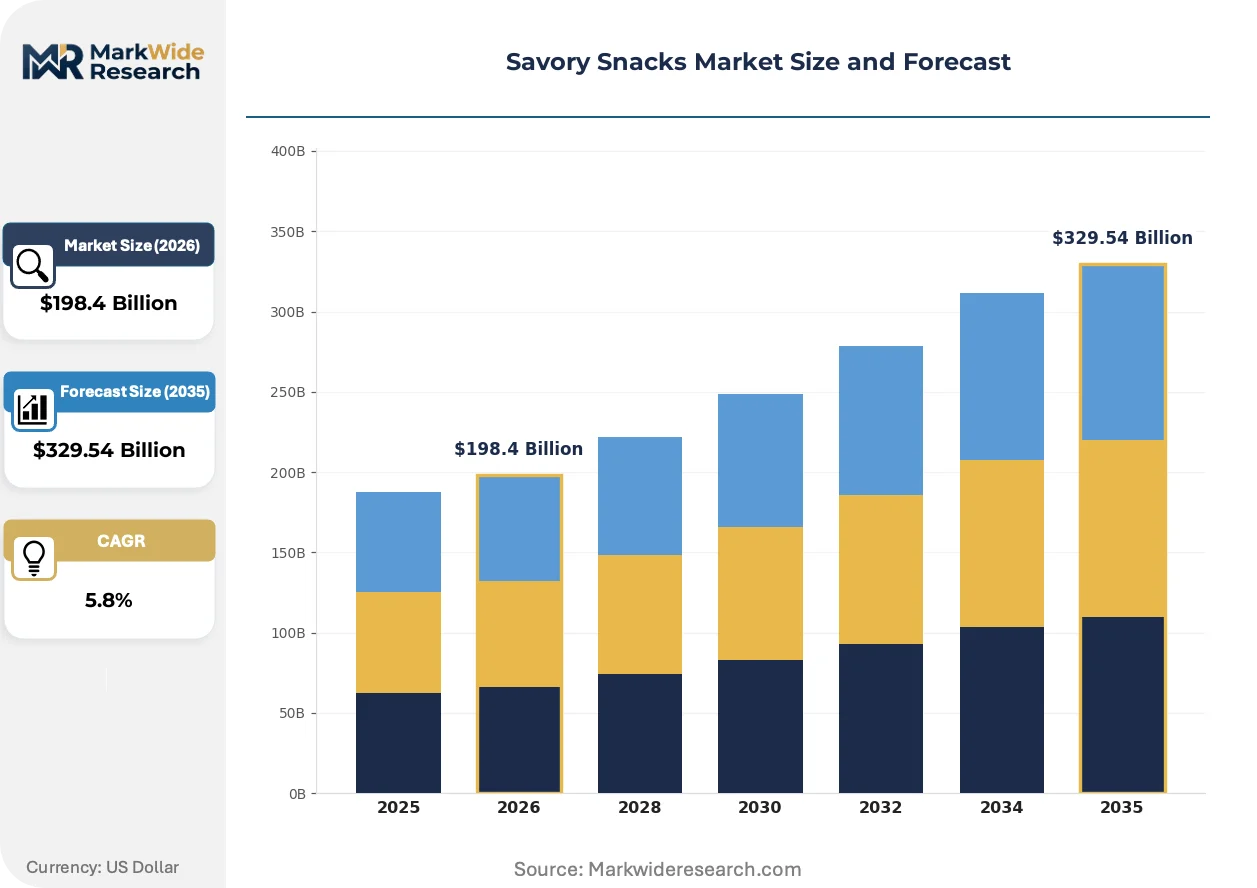
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $329.54 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Popcorn, Nuts, Pretzels Flavor Profile: Spicy, Sour, Sweet, Smoky Packaging Type: Bags, Boxes, Pouches, Tins Target Audience: Children, Adults, Health-Conscious Consumers, Athletes |
| Companies Covered | Mars, The Hershey Company, PepsiCo, Conagra Brands, Campbell Soup Company, Nestlé, General Mills, Intersnack Group, Mondelēz International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Savory Snacks Market Strategic Shifts & Innovations
Active reformulation imperatives and channel restructuring are compressing traditional competitive advantages while opening white space for technology-enabled positioning shifts.
Precision seasoning deposition systems enable micro-layered flavor delivery with reduced sodium loads. Health-positioned manufacturers in North American markets adopt these systems at accelerating rates. The technology is displacing conventional tumble-drum coating methods in premium line production.
EU front-of-pack Nutri-Score mandates force reformulation of base recipes to avoid retail delisting. Saturated fat and salt thresholds now determine shelf access in major continental markets. Chips and extruded snacks face the steepest compliance curves, with private-label portfolios experiencing faster rotation disruption than branded alternatives.
Millennial buyers in Indian metropolitan clusters prioritize regional flavor authenticity over multinational brand recognition. Traditional trade kirana stores cede volume to modern convenience formats with curated premium assortments. Mumbai and Bangalore clusters demonstrate the fastest channel shift velocity, with direct-store-delivery infrastructure becoming the decisive competitive variable.
Savory Snacks Market Segmentation
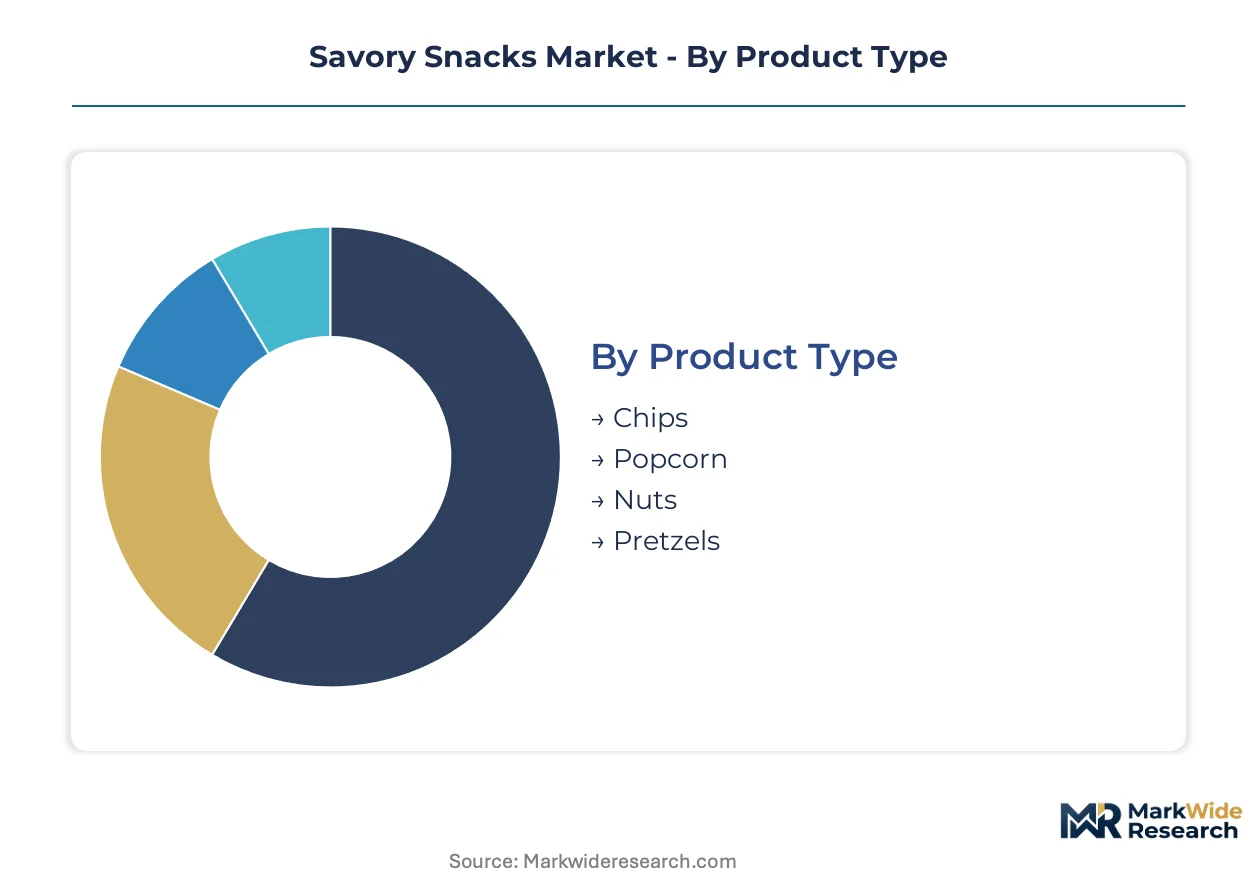
Savory snacks segmentation determines channel placement and margin architecture. Product format dictates processing capital requirements, while flavor and packaging configurations align with distinct consumption occasions and retail formats.
Product Type:
Chips and popcorn dominate export-led demand through multinational distribution networks, while nuts and pretzels concentrate in domestic premium channels with localized sourcing requirements.
- Chips:Thin-sliced tuber or grain substrates fried or baked to crisp texture, seasoned through tumble-drum or precision deposition systems. Demand concentrates in North American convenience stores where impulse-buy placement drives volume, though FDA sodium guidance forces reformulation of base recipes to maintain shelf access.
- Popcorn:Air-popped or low-oil extruded variants capture health-positioned shelf space through reduced fat claims and whole-grain positioning. Mumbai and Bangalore convenience formats show fastest adoption velocity as urban millennials prioritize portable, better-for-you alternatives.
- Nuts:Protein-forward positioning commands premium price tiers in domestic specialty retail.
- Pretzels:Mature rotation niche concentrated in Central European regional markets with established consumption rituals.
Chips holds the largest share; momentum sits with popcorn.
Flavor Profile:
Spicy and sour variants align with emerging market volume expansion, while smoky and sweet profiles concentrate in mature market premiumization strategies.
- Spicy:Capsicum-derived heat systems formulated through oil-based or dry seasoning deposition. Indian metropolitan clusters demonstrate fastest adoption as regional authenticity preferences override multinational brand recognition.
- Sour:Acidulated coatings through citric, malic, or lactic acid application create palate-stimulating consumption occasions. Health-conscious positioning in North American markets favors clean-label acid sources over synthetic alternatives.
- Sweet:Honey, maple, or brown sugar glazes occupy cross-category snack occasions.
- Smoky:Liquid smoke or pyroligneous acid applications target premium barbecue-positioned lines.
Spicy formulations gain share fastest; sweet maintains stable rotation in mature channels.
Packaging Type:
Bags and pouches dominate export-compatible formats with barrier film requirements, while boxes and tins concentrate in gift and premium domestic segments.
- Bags:Multi-layer laminated films with oxygen and moisture barriers extend shelf stability for fried products. Quick-service restaurant partnerships favor single-serve bag formats for drive-through and grab-and-go placement.
- Pouches:Stand-up configurations with resealable closures target pantry stocking occasions. EU front-of-pack labeling requirements favor portion-controlled pouch sizes that signal compliance through visible serving architecture.
- Boxes:Paperboard secondary packaging enables shelf-ready retail display.
- Tins:Metal containers preserve crispness for premium nut assortments.
Bags command the largest volume; pouches show steepest expansion trajectory.
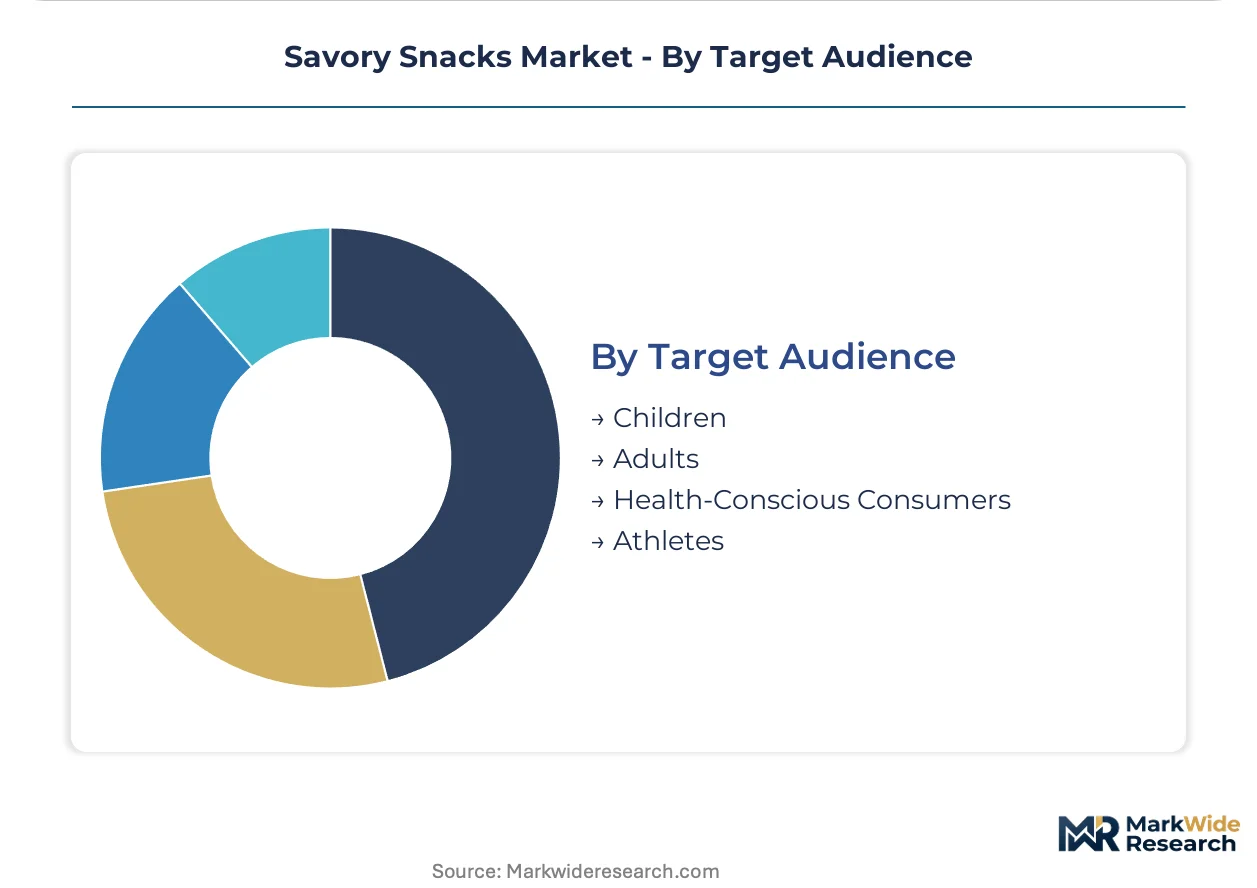
Target Audience:
Adults and health-conscious consumers drive export-led premium innovation, while children and athletes concentrate in domestic functional and convenience positioning.
- Adults:Sophisticated flavor complexity and portion-controlled formats align with social consumption occasions. Co-manufacturing networks enable regional specialists to match multinational scale for adult-targeted premium lines.
- Health-Conscious Consumers:Clean-label ingredient sourcing, reduced sodium, and air-popped processing technologies unlock price premiums. BIS fortification standards and FSSAI labeling mandates in India add compliance complexity for entrants targeting this segment.
- Children:Mild flavor profiles and character-licensed packaging dominate.
- Athletes:High-protein nut and legume formats with electrolyte positioning.
Adults represent the largest addressable base; health-conscious consumers expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Brazil exhibit high price elasticity, gravitating toward value packs and regional flavors, while consumers in Germany and the United States absorb premium pricing for clean-label and functional positioning without volume attrition.
United States
Impulse-buy placement in convenience stores and quick-service restaurants drives volume concentration, with air-popped popcorn variants capturing health-positioned shelf space. FDA sodium guidance forces reformulation timelines that favor early movers. The Dallas-Fort Worth metroplex anchors co-manufacturing network expansion for extrusion and flavor-coating capabilities.
India
Urban millennials in metropolitan clusters prioritize regional flavor authenticity over multinational brand recognition, accelerating premium assortment adoption. FSSAI labeling mandates and BIS fortification standards add compliance complexity for entrants. Mumbai and Bangalore demonstrate the fastest channel shift velocity from traditional kirana stores to modern convenience formats.
Germany
Private-label partnerships and regional brand portfolios sustain competitiveness amid EU Nutri-Score front-of-pack labeling requirements. REACH compliance and EFSA nutrient profiling thresholds reshape permissible salt and saturated fat levels. The North Rhine-Westphalia industrial corridor concentrates flavor technology and precision seasoning system suppliers.
Brazil
Price-sensitive consumers favor value-pack formats and spicy flavor profiles aligned with regional palate preferences. ANVISA food labeling regulations and import tariff structures influence portfolio composition for multinational entrants. São Paulo state anchors domestic manufacturing capacity and distribution infrastructure for pan-Latin American supply.
Japan
Mature consumers demand portion-controlled packaging and mild flavor complexity for social consumption occasions. PMDA and METI standards on food additives and health claims constrain rapid reformulation cycles. The Kanto region around Tokyo maintains the densest convenience store network per capita, driving single-serve format innovation.
Savory Snacks Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the capital-intensity gap collapsing as co-manufacturing networks democratize production capabilities. The structure concentrates around three archetypes: multinational conglomerates leveraging direct-store-delivery infrastructure, regional specialists anchoring competitiveness through private-label partnerships, and technology-enabled premium players differentiating via precision seasoning and clean-label sourcing. Dominant competitive moves include strategic co-manufacturing alliances to extend geographic reach and accelerated reformulation investments to preempt regulatory delisting risks.
Within the multinational tier, PepsiCo and Mondelēz International exemplify scale-driven positioning, while Intersnack Group occupies a specialist role across Central European markets. These entities represent contrasting strategic anchors: the first two leverage integrated distribution and flavor technology portfolios, while the third demonstrates how regional brand aggregation sustains competitiveness against global scale advantages.
| Leading Market Players |
|---|
| Mars |
| The Hershey Company |
| PepsiCo |
| Conagra Brands |
| Campbell Soup Company |
| Nestlé |
| General Mills |
| Intersnack Group |
| Mondelēz International |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts for edible oil and potato supply lock in both raw material access and cost visibility for frying-dependent product lines, insulating manufacturers from commodity volatility while compressing margin flexibility for spot-market purchasers. These arrangements concentrate pricing power among processors with backward-integrated sourcing networks in India and the United States.
Pricing Analysis
After-sales revenue from co-manufacturing service contracts and flavor technology licensing drives lifetime value for extrusion equipment suppliers and seasoning system providers. Three-tier pricing structure across premium, standard, and economy levels separates precision-seasoned clean-label lines from conventional tumble-drum coated alternatives. Cost compression in economy-tier fried chips intensifies because edible oil supply fluctuations compress margins. Health-conscious consumers in North American convenience channels show least price sensitivity, while urban millennials in India gravitate toward value-pack regional flavors.
Supply Chain Analysis
Inventory buffers for potato and edible oil inputs stretch lead times during harvest volatility periods, forcing just-in-sequence coordination between agricultural suppliers and extrusion facilities. Manufacturing concentrates in the United States, India, and Germany, with flavor technology sourcing anchored in the North Rhine-Westphalia corridor. Raw material dependencies center on palm oil, sunflower oil, and specialty grain starches. Single-source vulnerability for precision seasoning deposition equipment creates procurement risk. Distribution runs through direct-store-delivery networks in North America and modern convenience formats in Indian metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The savory snacks market sits in a cyclical recovery phase driven by post-reformulation demand recapture as FDA sodium guidance enforcement timelines approach.
For Market Incumbents: Fortify shelf access through accelerated sodium-reduction investments ahead of FDA enforcement windows, locking in retail placement before delisting risk materializes. Deepen backward integration into specialty oil sourcing to insulate margin structures from commodity volatility. Co-manufacturing network consolidation presents a defensive lever against regional specialist encroachment. For New Entrants and Emerging Players: Precision seasoning technology service gaps where multinational incumbents under-serve regional specialists offer white-space entry points. Target health-positioned popcorn variants in Mumbai and Bangalore convenience formats as the most penetrable segment. A go-to-market angle anchored in clean-label regional flavor authenticity overrides brand recognition deficits with urban millennials. For Investors and Strategic Acquirers: The market sits at a pre-enforcement phase that favors technology-enabled reformulation specialists over commodity-scale fryers. Long-term viability over the next decade hinges on regulatory compliance capabilities rather than volume scale. Acquisition targets should demonstrate precision seasoning IP and FSSAI pre-certification. The signal to watch is front-of-pack labeling delisting velocity in EU markets as a leading indicator for FDA-guided North American enforcement.| Strategic Initiative | Industry Significance |
|---|---|
| Sodium-Reduction Reformulation | FDA guidance timelines create first-mover shelf access advantages for compliant manufacturers. |
| Precision Seasoning Technology Deployment | Micro-layered flavor deposition displaces conventional coating in premium line production. |
| Co-Manufacturing Network Expansion | Distributed extrusion capabilities democratize scale advantages for regional specialists. |
| Clean-Label Ingredient Sourcing | Transparent supply chain claims unlock price premiums in health-positioned channels. |
| Quick-Service Restaurant Partnership | Drive-through placement expands consumption occasions beyond traditional retail formats. |
Research Approach
Cross-validation between primary interviews with flavor technology suppliers and secondary validation through FSSAI filing databases anchors the qualitative findings. Conversations with extrusion equipment manufacturers, retail category buyers, co-manufacturing network operators, and regulatory affairs specialists at multinational processors inform competitive positioning assessments. Secondary sources include Nielsen retail audit data, EU Nutri-Score compliance registries, and BIS fortification standard filings. Bottom-up volume modeling triangulates against top-down category spend estimates.
Sensitivity analysis around sodium-reduction compliance timelines and edible oil price volatility bounds the forecast confidence intervals. The analytical framework segments by product format, flavor profile, packaging configuration, and target audience across the projection horizon. CAGRs derive from trend-line extrapolation adjusted for regulatory inflection points. Modeled inputs include urban millennial population growth in Indian metropolitan clusters and front-of-pack labeling adoption curves in EU markets.
Forecasts assume regulatory continuity in FDA sodium guidance and EU Nutri-Score regimes; material policy shifts would require re-modeling. Specific risks include ultra-processed food classification divergence between jurisdictions and flavor chemist scarcity extending reformulation timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Organic Chips Market
Snacks
Middle East and North Africa Extruded Snack Food Market
Snacks
Low Fat Crackers Market
Snacks
North America Frozen Snacks Market
Snacks
Forti Flakes Market
Snacks
Vegan Protein Balls Market
Snacks
Fat Free Meals and Snacks Market
Snacks
India Energy Bar Market
Snacks
Low Calorie Crackers Market
Snacks
Potato Chips Market
Snacks
Fiber Bars Market
Snacks
France Energy Bar Market
Snacks
Energy Bar Market
Snacks
Nuts and Seeds (Savory Snacks) Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Veggie Chips Market