
 Commercial Aircraft in-Seat Power System Market | 2026-2036
Commercial Aircraft in-Seat Power System Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft in-Seat Power System Market Analysis
Market Context with Strategic Players
China is tilting toward domestic in-seat power manufacturing as COMAC expands C919 production lines and local suppliers scale capacity. Astronics Corporation leverages its vertical integration across power conversion and cabin electronics to sustain delivery schedules for Boeing and Airbus programs. Panasonic Avionics Corporation anchors the premium wide-body segment through embedded IFE-power integration. KID-Systeme GmbH specializes in modular 110V AC and USB architectures that dominate European retrofit programs.
Technical Definition and Structural Segments
Commercial aircraft in-seat power systems encompass embedded electrical distribution units that convert 115V AC aircraft bus power to passenger-accessible outputs, typically delivering 5V DC via USB-A/USB-C ports or 110V AC through universal outlets for personal electronic device charging during flight. DC Power Supply configurations lead installation volumes across narrow-body retrofits where weight minimization and simplified harness routing reduce fuel burn penalties, while Integrated Power Systems capture expanding margin pools as airlines bundle USB-C PD, wireless charging, and data connectivity into single seat-back modules. Wired Connection remains the dominant connectivity category, though USB Ports and Multi-Functional Outlets are displacing legacy 110V AC-only configurations in new-generation seat designs.
Regulatory Framework and Forward Outlook
FAA Technical Standard Orders and EASA Certification Specifications govern electromagnetic compatibility, thermal runaway containment, and passenger injury prevention for in-seat power installations. The EU AI Act and CSRD disclosure requirements are beginning to shape supplier environmental reporting obligations for cabin electronics manufacturing. Stakeholders must monitor evolving USB Power Delivery specification adoption timelines and harmonized voltage standardization between FAA and EASA jurisdictions to align product roadmaps with certification pathways.
Market Dynamics
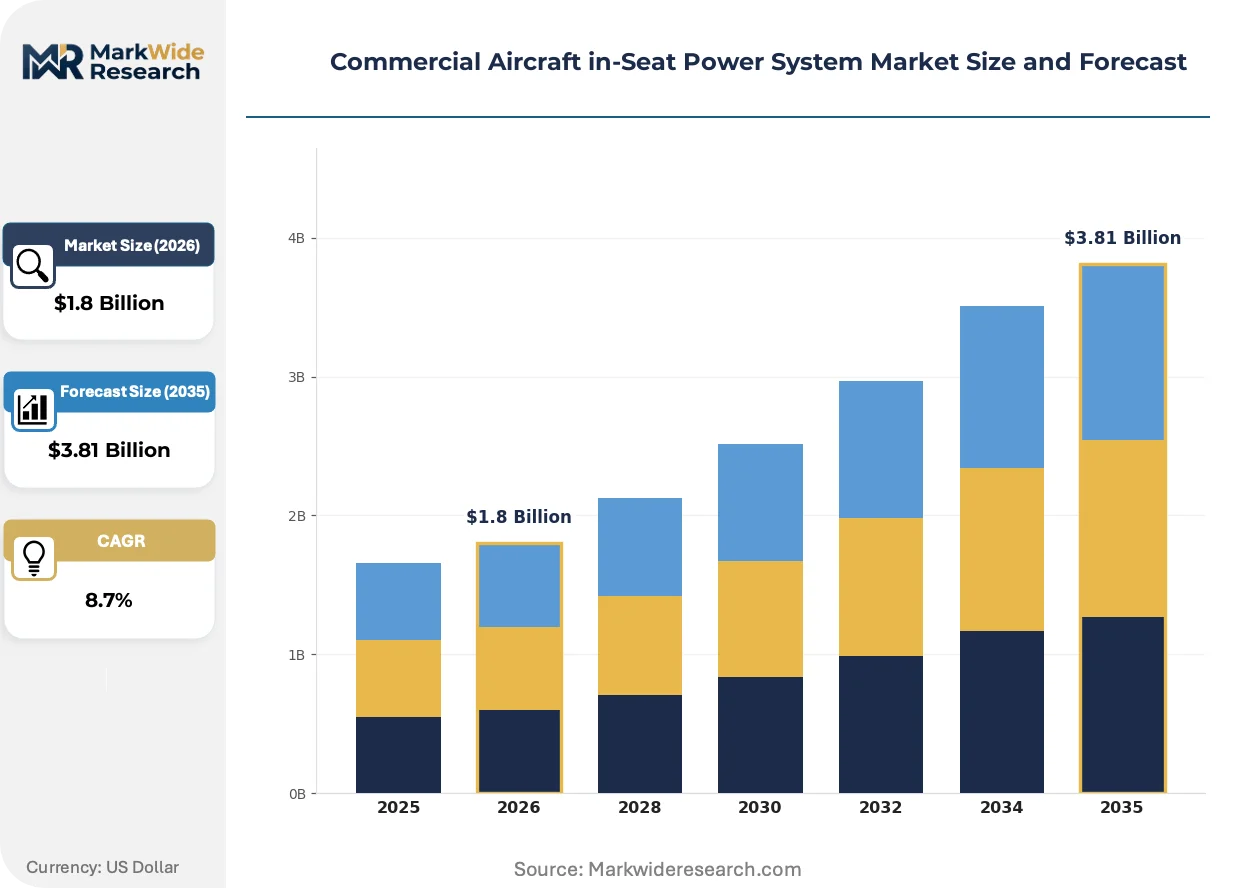
The commercial aircraft in-seat power system market is restructuring around USB-C Power Delivery standardization, which compresses hardware complexity while elevating thermal management requirements across narrow-body and wide-body retrofit programs.
Growth Catalysts
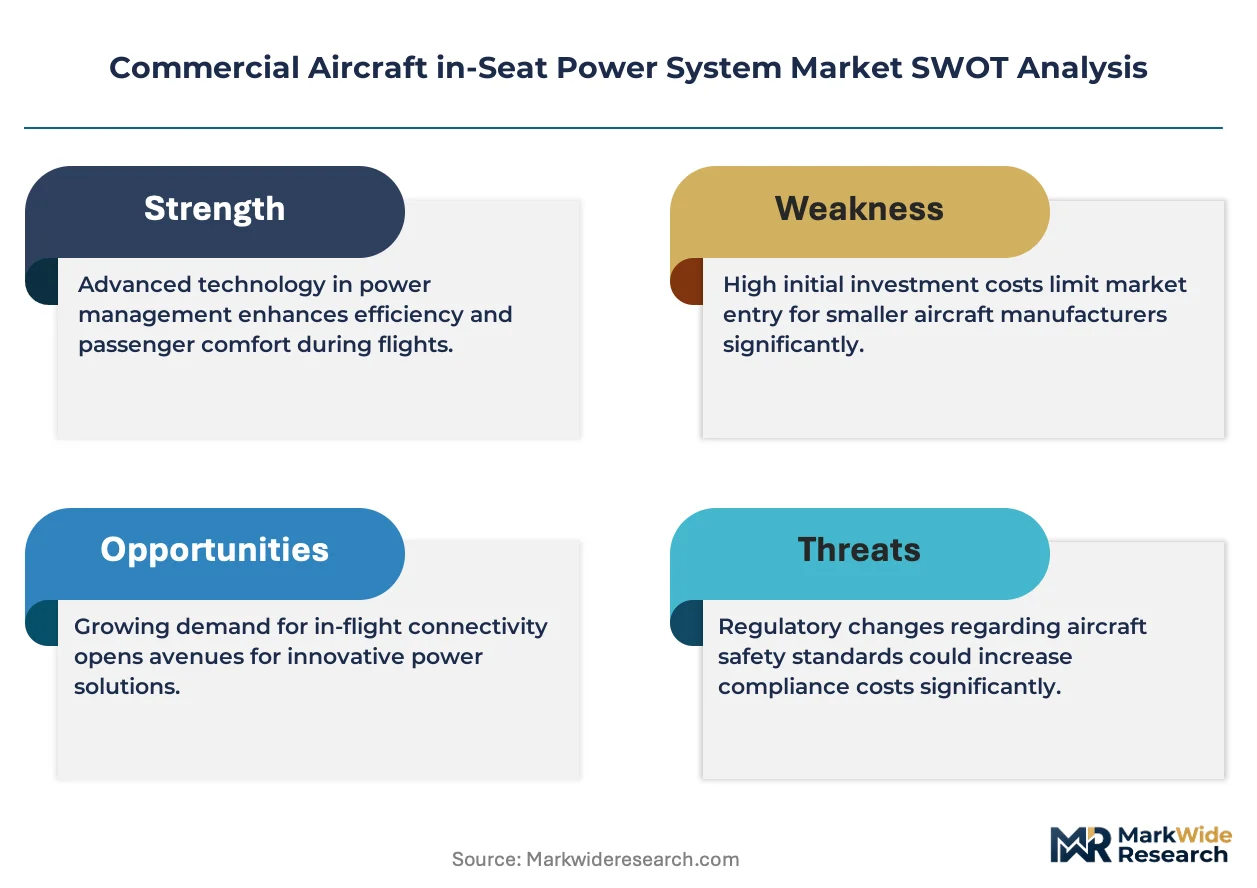
- FAA Technical Standard Order harmonization:Unified electromagnetic compatibility protocols between FAA and EASA jurisdictions accelerate dual-certification timelines for power conversion units, reducing supplier engineering overhead.
- Narrow-body fleet densification:Low-cost carriers operating Airbus A320neo and Boeing 737 MAX platforms prioritize seat-back power as a revenue-differentiating amenity, driving retrofit installation volumes.
- Lithium-ion containment mandates:Thermal runaway propagation requirements under EASA CS-25 certification specifications force power system redesigns that favor modular, field-replaceable battery architectures.
Market Restraints
- Copper and rare earth magnet volatility:Power conversion unit manufacturing faces input cost pressure from dysprosium and neodymium price swings, compressing margins on DC-DC converter assemblies.
- Single-source semiconductor dependency:Gallium nitride (GaN) power IC fabrication concentrates in Taiwan and South Korea, exposing supply continuity risk for high-efficiency conversion modules.
- 110V AC outlet displacement:USB-C PD 100W delivery capability substitutes traditional AC inverter requirements, cannibalizing higher-margin universal outlet product lines.
Strategic Opportunities
- India MRO infrastructure expansion:IndiGo and Air India fleet growth creates aftermarket installation demand at Bengaluru and Hyderabad maintenance hubs lacking legacy power system integration expertise.
- Wireless charging convergence:Qi2 magnetic alignment standards merging with USB-C PD controllers enable single-module seat-back solutions, reducing wiring harness complexity.
- EU CSRD disclosure alignment:Scope 3 emissions reporting requirements for cabin electronics procurement favor suppliers with documented circular material flows and repairable power module designs.
Industry Challenges
- EMC certification timeline compression:FAA and EASA electromagnetic interference testing queues extend lead times for new power system variants, delaying airline retrofit schedules.
- Legacy 28V DC harness incompatibility:Older narrow-body airframes require custom adapter installations to support modern 115V AC bus architectures, complicating field engineering deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft in-Seat Power System Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Power Supply, DC Power Supply, Integrated Power Systems, Universal Power Outlets End User: Commercial Airlines, Charter Services, Government Agencies, Private Operators Installation Type: Retrofitting, New Aircraft, Line Fit, Seat Back Installation Connectivity: Wired Connection, Wireless Charging, USB Ports, Multi-Functional Outlets |
| Companies Covered | Astronics Corporation, Panasonic Avionics Corporation, KID-Systeme GmbH, Mid-Continent Instrument Co., Inc., Burrana Pty Ltd., IFPL Group Limited, Inflight Canada Inc., Collins Aerospace, Diehl Aviation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft in-Seat Power System Market Emerging Trajectories
Power system architectures are converging around software-defined power management, collapsing discrete hardware functions into programmable controllers that adapt output profiles to passenger device signatures.
GaN-based power conversion is virtualizing traditional transformer-isolated architectures, enabling 3kW/kg power density in seat-back modules. Full-service carriers retrofitting premium cabins adopt these compact units to reclaim under-seat stowage volume. The technology is virtualizing the physical segregation between high-voltage distribution and passenger-accessible outputs, reducing harness mass by consolidating grounding planes.
EASA Certification Specification CS-25 Amendment 27 tightens electromagnetic emission thresholds for cabin electronics, compelling power system redesigns with integrated ferrite shielding. Manufacturers serving European retrofit programs absorb additional validation costs for dual FCC-EASA compliance. Narrow-body operators in Germany and France delay procurement decisions pending harmonized test protocol finalization.
Airline technical procurement teams consolidate vendor relationships around integrated cabin system providers, displacing discrete power component sourcing. Maintenance organizations favor single-point accountability for seat-back module warranty claims. This concentration is most pronounced among US network carriers consolidating Boeing 787 and Airbus A350 fleet standardization programs.
Commercial Aircraft in-Seat Power System Market Segmentation
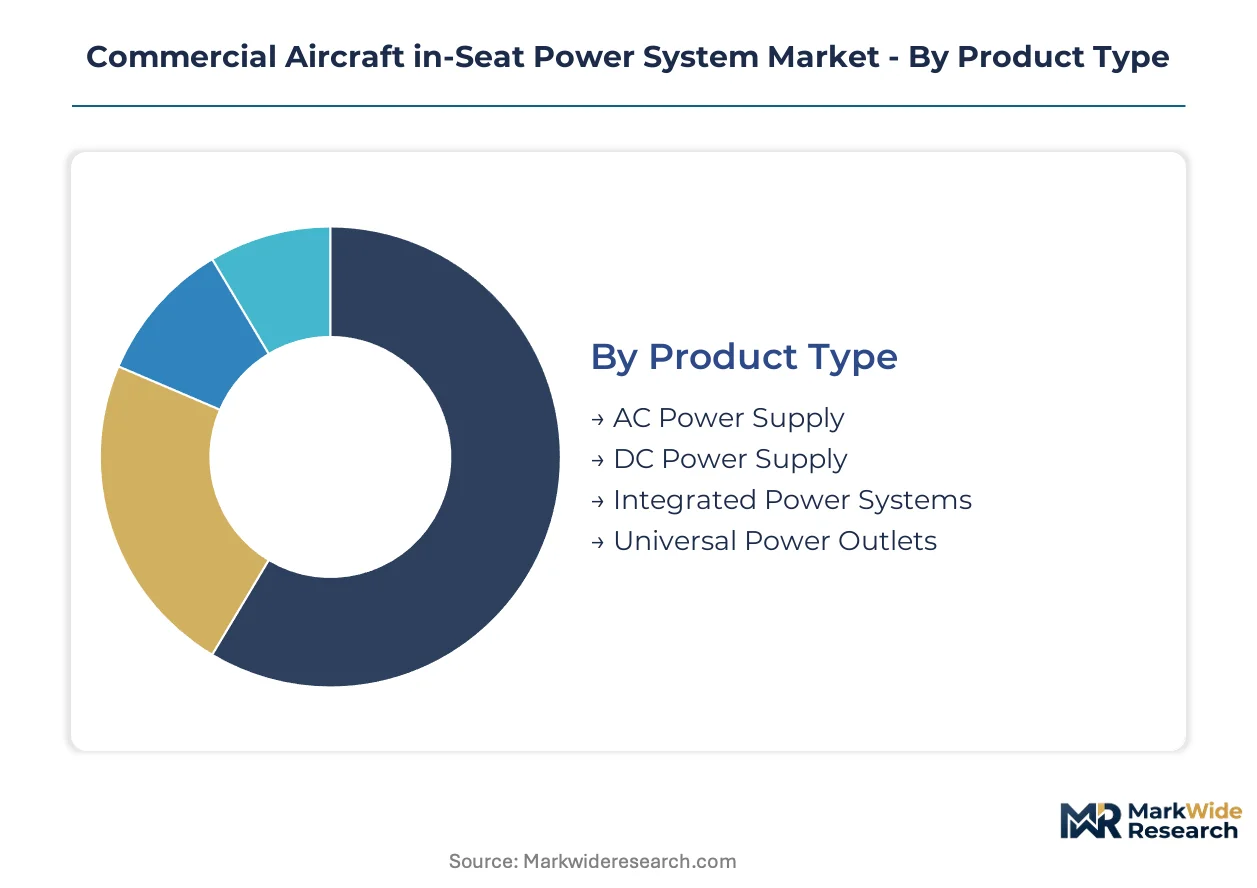
Segmentation in the commercial aircraft in-seat power system market reveals how technical specifications, regulatory pathways, and airline operational models reshape procurement priorities across retrofit and new-build programs.
Product Type:
Power conversion architectures span from discrete voltage transformation modules to unified cabin electronics platforms, with weight and certification complexity driving airline selection.
- DC Power Supply:Converts 115V AC aircraft bus power to 5V DC outputs through compact switching regulators optimized for narrow-body retrofits. Low-cost carriers operating Airbus A320neo and Boeing 737 MAX fleets in the United States prioritize these configurations to minimize fuel burn penalties from added harness weight.
- Integrated Power Systems:Consolidate USB-C PD, wireless charging coils, and data connectivity into single seat-back modules with unified thermal management. Full-service carriers retrofitting premium cabins on wide-body platforms favor these units to reclaim under-seat stowage volume and simplify warranty accountability.
- AC Power Supply:Maintains legacy 110V AC inverter architectures for universal outlet compatibility on older wide-body configurations.
- Universal Power Outlets:Standalone 110V AC passenger-accessible units requiring dedicated inverter modules and enhanced EMI shielding per FAA TSO-C73.
Established volume favors DC Power Supply; emerging adoption favors Integrated Power Systems.
End User:
Operator type dictates certification urgency, with scheduled commercial carriers facing the tightest retrofit windows to maintain competitive amenity parity.
- Commercial Airlines:Account for dominant installation volumes across both narrow-body densification programs and wide-body premium cabin refreshes. Network carriers in Germany and France delay procurement decisions pending EASA CS-25 Amendment 27 harmonization with FAA electromagnetic emission protocols.
- Charter Services:Concentrate demand in rapid-turnaround retrofit programs where modular, field-replaceable architectures minimize aircraft downtime. Operators serving executive travel corridors between London and Geneva prioritize USB-C PD 100W delivery to attract high-yield corporate passengers.
- Government Agencies:Require hardened power systems meeting military electromagnetic pulse resilience standards for VIP transport configurations.
- Private Operators:Specify bespoke cabin electronics integration through completion centers in the United States and Switzerland.
Procurement scale concentrates with Commercial Airlines; flexibility requirements peak with Private Operators.
Installation Type:
Integration pathway determines engineering validation burden, with line-fit installations leveraging OEM design authority while retrofits demand supplemental type certificate coordination.
- Retrofitting:Dominates current market activity as airlines upgrade existing narrow-body and wide-body fleets to match new-build amenity standards. FAA and EASA certification queues for electromagnetic interference testing extend lead times, compressing available installation windows between heavy maintenance checks.
- New Aircraft:Enables integrated power and IFE system design from preliminary design review, reducing harness mass through optimized routing. Boeing 787 and Airbus A350 production lines in the United States, China, and Germany embed these systems at final assembly.
- Line Fit:Represents OEM-facilitated installation during production with unified warranty coverage across seat and power system suppliers.
- Seat Back Installation:Targets modular replacement of discrete passenger service units without full cabin reconfiguration.
Near-term volume flows through Retrofitting; long-term efficiency gains concentrate in New Aircraft.
Connectivity:
Passenger interface technology is converging around USB-C standardization while wireless charging penetrates premium cabin segments.
- USB Ports:USB-A and USB-C configurations now dominate new-generation seat designs, with USB-C Power Delivery 100W capability substituting traditional AC inverter requirements. Airlines in China specify domestic supplier modules to align with COMAC C919 production ramp and local content mandates.
- Wired Connection:Maintains installed base across legacy fleets with dedicated charging cables and proprietary connectors. MRO hubs in India face capability gaps integrating modern 115V AC bus architectures with older 28V DC harness infrastructures.
- Wireless Charging:Qi2 magnetic alignment standards merging with USB-C PD controllers enable single-module seat-back solutions.
- Multi-Functional Outlets:Combine USB-C, USB-A, and 110V AC in unified passenger-facing units.
Deployment breadth favors USB Ports; technology trajectory favors Wireless Charging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Airlines in mature aviation markets retrofit legacy narrow-body fleets with USB-C Power Delivery modules, while emerging carriers in Asia-Pacific specify integrated power-IFE systems for new-build deliveries. Certification urgency and local content mandates reshape procurement priorities.
United States
Network carriers operating Boeing 737 MAX and 787 platforms drive retrofit volumes for DC power supply configurations. FAA Technical Standard Order C73 governs electromagnetic compatibility testing for passenger-accessible outlets. Seattle and Charleston final assembly lines embed Astronics and Collins Aerospace systems at production.
China
COMAC C919 production ramp accelerates domestic supplier qualification for seat-back power modules. MIIT local content mandates steer procurement toward indigenous manufacturers. Shanghai Pudong and Tianjin aviation clusters host emerging power conversion specialists scaling capacity for narrow-body line-fit programs.
Germany
Lufthansa Group fleet standardization programs prioritize EASA CS-25 Amendment 27 pre-compliant integrated systems. KID-Systeme GmbH anchors modular AC-USB architectures from Hamburg engineering centers. Bavarian MRO hubs at Munich absorb supplemental type certificate coordination costs for A320neo retrofit installations.
India
IndiGo and Air India narrow-body densification creates aftermarket demand exceeding local installation capacity. DGFT import certification delays for cabin electronics complicate supplier onboarding. Bengaluru and Hyderabad maintenance clusters face capability gaps integrating 115V AC bus architectures with legacy 28V DC harness infrastructures.
Japan
ANA and JAL premium cabin refreshes specify Qi2 wireless charging convergence in single-module seat-back designs. METI industrial standards harmonization with USB Power Delivery specifications accelerates domestic controller sourcing. Nagoya aerospace suppliers specialize in compact ferrite shielding for EASA electromagnetic emission compliance.
Commercial Aircraft in-Seat Power System Market Vendor Landscape
Capability concentration sits with vertically integrated cabin electronics specialists; scale advantage sits with diversified aerospace conglomerates serving multiple OEM programs. The vendor base stratifies across three tiers: integrated system architects owning design authority, modular component suppliers competing on certification speed, and regional fabricators capturing local content mandates. Consolidation pressures intensify as airlines consolidate vendor relationships around single-point warranty accountability. Technology licensing and strategic partnerships represent the dominant competitive vectors as GaN power conversion IP becomes critical.
Among US-based integrated system providers, Astronics Corporation and Collins Aerospace exemplify the design-authority tier, anchoring Boeing and Airbus line-fit programs through captive power conversion and cabin electronics capabilities. KID-Systeme GmbH represents the European modular specialist archetype, occupying a position in EASA-certified retrofit architectures. Panasonic Avionics Corporation sits within the premium wide-body integration segment, exemplifying IFE-power convergence strategies.
| Leading Market Players |
|---|
| Astronics Corporation |
| Panasonic Avionics Corporation |
| KID-Systeme GmbH |
| Mid-Continent Instrument Co., Inc. |
| Burrana Pty Ltd. |
| IFPL Group Limited |
| Inflight Canada Inc. |
| Collins Aerospace |
| Diehl Aviation |
| Others |
Supply Flow & Price Mechanics
Shanghai Pudong aviation clusters anchor global power conversion module capacity, with domestic supplier qualification for COMAC C919 programs compressing pricing power for European and North American incumbents serving retrofit channels. Local content mandates under MIIT directives tilt procurement toward indigenous manufacturers, forcing foreign suppliers to absorb margin compression or cede narrow-body line-fit volumes.
Pricing Analysis
Price spreads between German-engineered modular systems and Chinese-produced alternatives widen to 40-60 percent at equivalent USB-C PD output ratings, with EASA CS-25 Amendment 27 pre-compliance commanding certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates integrated IFE-power bundles from discrete DC supplies and basic USB-A retrofits. Cost compression in standard-tier DC-DC converter assemblies intensifies as gallium nitride controller prices soften, though low-cost carriers remain most price-sensitive while full-service carriers prioritize warranty consolidation over unit economics.
Supply Chain Analysis
Dysprosium and neodymium feedstock draws from Chinese rare earth processing hubs and Australian mining operations, with Taiwanese and South Korean gallium nitride foundries anchoring high-efficiency power IC fabrication. Copper busbar and ferrite shielding materials hinge on volatile commodity exchanges, exposing converter assembly margins to input cost swings. Single-source vulnerability concentrates in GaN wafer supply, with distribution running through aerospace-tier electronics distributors holding FAA TSO-C73 certification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Field-replaceable module services and extended warranty programs expand faster than hardware shipments, creating recurring revenue pools that offset cyclical new-build procurement. Airlines consolidate vendor relationships around single-point accountability, elevating attach rates for aftermarket power system maintenance.
For Market Incumbents: Pre-empt USB-C PD standardization fragmentation by certifying dual-voltage architectures ahead of EASA-FAA harmonization finalization. Secure backward integration into gallium nitride controller supply through captive partnerships with Taiwanese foundries, insulating conversion module margins from semiconductor allocation shocks. For New Entrants and Emerging Players: Pursue aftermarket retrofit capacity gaps at Indian MRO hubs in Bengaluru and Hyderabad, where 115V AC bus integration expertise remains scarce. Target charter services operating London-Geneva executive corridors with rapid-turnaround modular installations, leveraging USB-C PD 100W delivery as a passenger-amenity differentiator against legacy fleet operators. For Investors and Strategic Acquirers: Long-term, this sits as a certification-moat play because FAA and EASA electromagnetic interference testing queues create durable barriers against rapid commoditization. Acquire modular component specialists holding existing supplemental type certificates rather than greenfield certification investments. Monitor Qi2 wireless charging adoption curves in ANA and JAL premium cabin programs as inflection signals for technology substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Power Conversion IP Licensing | Enables 3kW/kg density gains that reclaim under-seat stowage for premium cabin retrofits. |
| EASA CS-25 Amendment 27 Pre-Certification | Positions suppliers ahead of Lufthansa Group fleet standardization procurement windows. |
| India MRO Capability Partnership | Addresses IndiGo and Air India retrofit demand exceeding local installation capacity. |
| Wireless Charging-Qi2 Convergence | Consolidates USB-C PD controllers with magnetic alignment standards for single-module designs. |
| EU CSRD Circular Material Documentation | Meets Scope 3 emissions reporting requirements for Lufthansa and Air France-KLM procurement. |
Methodological Framework
Initial hypotheses were tested against primary input from airline technical procurement directors, MRO engineering managers, cabin electronics OEM program leads, and FAA/EASA certification consultants, and refined through secondary validation against SEC 10-K filings, EASA Certification Specification amendments, customs trade data for power conversion components, and aircraft production databases. Bottom-up triangulation across narrow-body and wide-body fleet retrofit schedules converged with top-down market sizing from OEM delivery projections.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type, installation pathway, connectivity standard, and operator category. CAGRs derived from installed base turnover rates and new-build line-fit penetration curves incorporated USB Power Delivery specification adoption timelines and harmonized voltage standardization progress between FAA and EASA jurisdictions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated cabin electronics conglomerates or state-backed Chinese suppliers would shift outcomes beyond modeled ranges. Cross-checking against COMAC C919 production ramp disclosures and Lufthansa Group technical fleet refresh announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Lavatory System Market
Aircraft
Global Business Jets Market
Aircraft
LAMEA Aircraft Band Clamps Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
Japan Aircraft Windshield Wiper and Washer System Market
Aircraft
Global Commercial Aircraft Windows and Windshields Market
Aircraft
Airplane Ailerons Market
Aircraft
Aero Wing Market
Aircraft
Europe Aircraft Manufacturing Market
Aircraft
Military Rotorcraft Market
Aircraft
Commercial Helicopter Market
Aircraft
Europe Freighter Aircraft Market
Aircraft
Airship Market
Aircraft
Japan Aviation Market
Aircraft
Global Aircraft Transparencies Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market