
 Indonesia Plastic Bottles Market | 2026-2036
Indonesia Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Plastic Bottles Market Insights
Lightweighting and rPET integration is rewriting how Indonesian converters engineer bottle structures for cost and compliance. PT Jayatama Selaras leverages its blow-molding scale to supply beverage majors across Java. PT Biggy Cemerlang anchors the personal care segment with decorated HDPE bottles for shampoo and lotion brands. Amcor Group competes through preform design expertise that reduces resin use per unit.
Indonesia plastic bottles are hollow thermoplastic containers, typically blow-molded from PET or polyethylene resins in capacities from 50 milliliters to 20 liters, serving as primary packaging for liquids and semi-solids across consumer and industrial supply chains. PET dominates beverage applications due to its clarity, gas barrier, and recyclability, while HDPE sustains share in household and pharmaceutical segments where chemical resistance matters. The closure type dimension differentiates margin pools: pump dispensers for personal care command premium pricing, whereas screw caps in bulk beverage formats operate on volume-driven economics. Distribution through wholesale channels still controls rural penetration, though convenience stores in urban clusters are capturing faster turnover for single-serve formats.
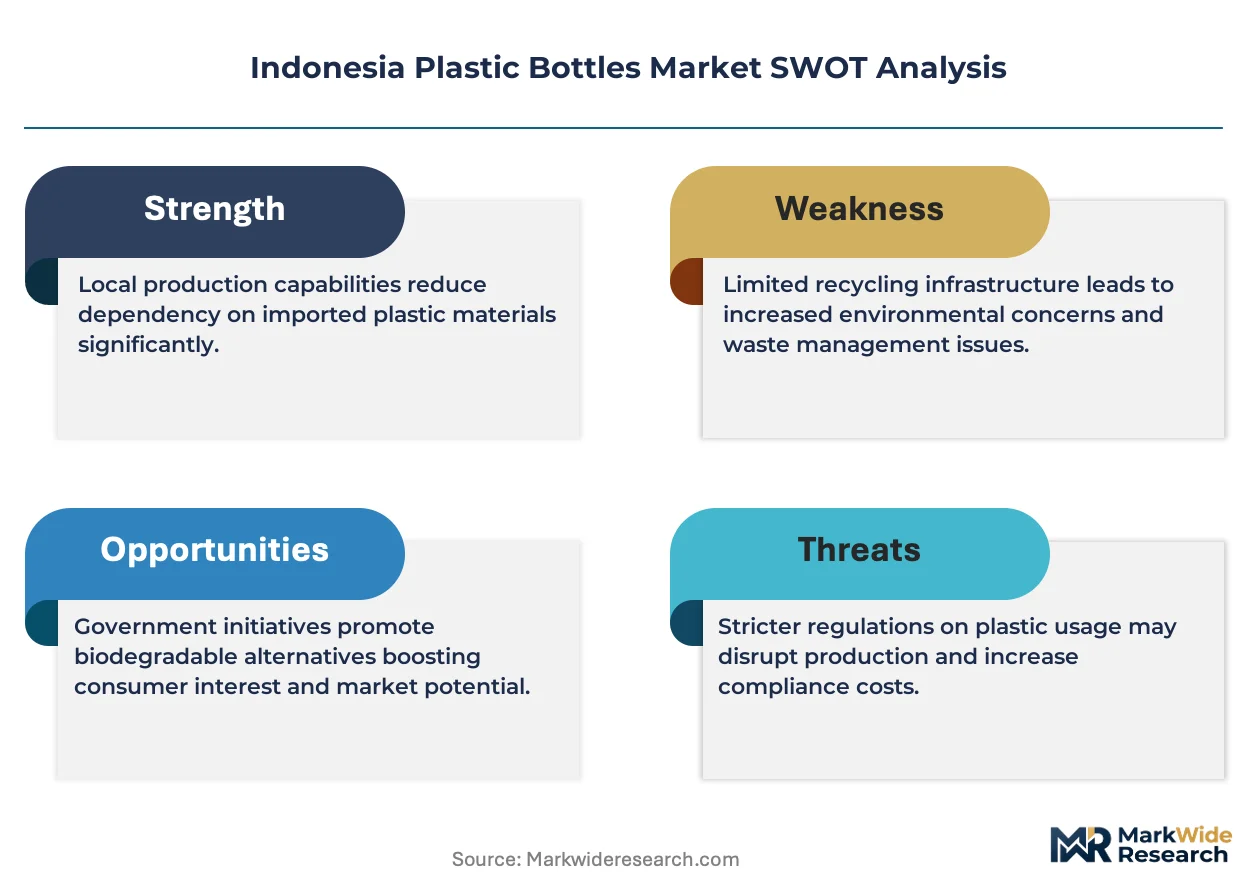
BIS-equivalent national standards and Indonesia's Ministry of Environment and Forestry regulations on plastic waste reduction shape material specifications and recycling content mandates for domestic producers. The country's national pharmaceutical regulator enforces USP and ASEAN packaging guidelines that constrain resin grades and migration limits for drug-contact bottles. Stakeholders must monitor how enforcement of extended producer responsibility rules affects rPET feedstock availability and converter cost structures.
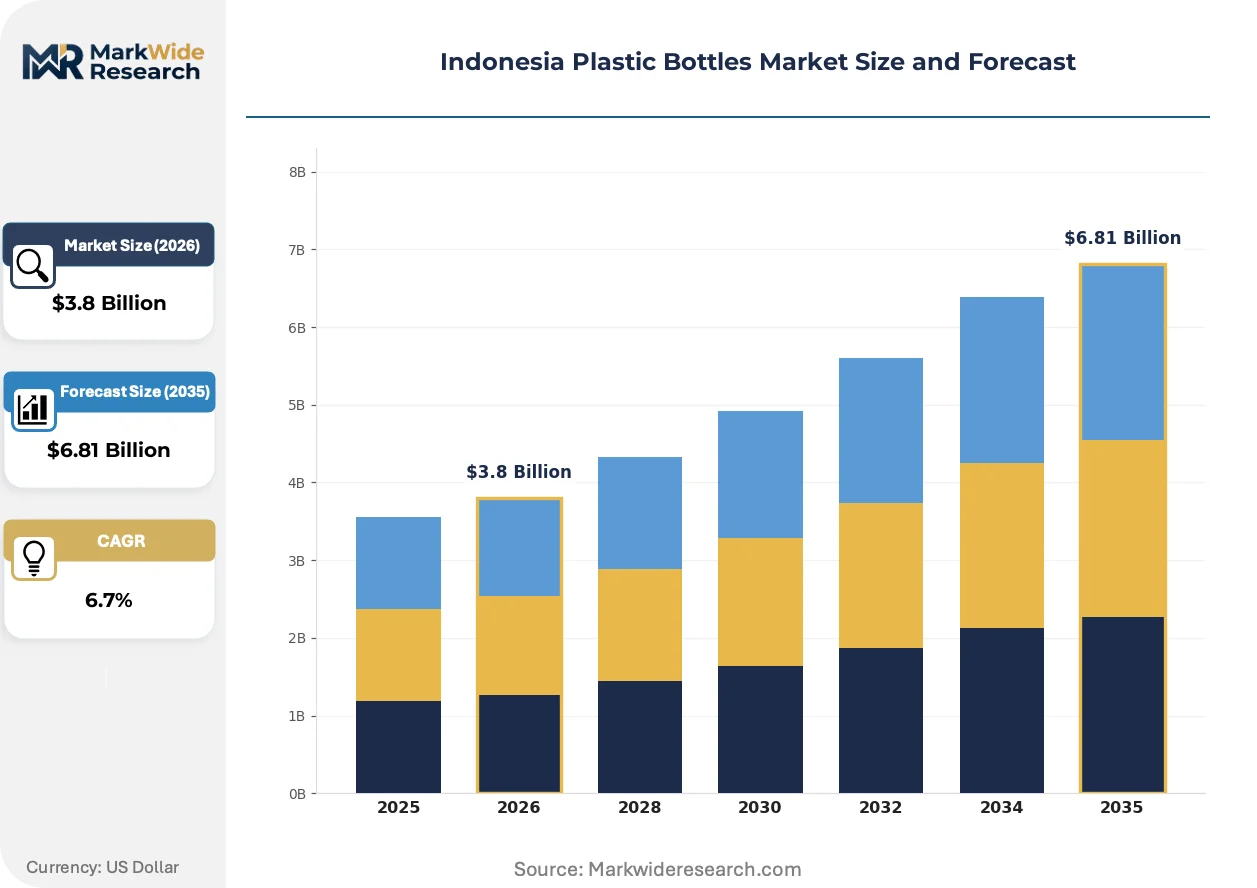
Market Dynamics
Indonesia's Ministry of Environment and Forestry has tightened extended producer responsibility enforcement, forcing converters to re-engineer bottle structures around rPET integration while maintaining cost parity with virgin resin formulations.
Growth Catalysts
- EPR Mandate Expansion:Indonesia's Ministry of Environment and Forestry regulations on plastic waste reduction now require measurable recycled content in primary packaging, creating pull-through demand for rPET flake and driving converter investment in decontamination lines.
- Beverage Volume Concentration:Ready-to-drink tea and bottled water consumption in Java and Sumatra is expanding PET bottle procurement from blow-molding facilities serving both domestic brands and export-oriented multinationals.
- Preform Lightweighting:Advanced stretch-blow molding technologies are reducing resin use per unit by optimizing wall thickness distribution, cutting material costs for high-volume beverage formats without sacrificing burst pressure performance.
Market Restraints
- rPET Feedstock Scarcity:Post-consumer bottle collection rates in secondary cities remain below converter requirements, creating supply concentration risk around Greater Jakarta's recycling infrastructure.
- Resin Price Volatility:Purified terephthalic acid and monoethylene glycol feedstock costs fluctuate with naphtha-linked pricing, compressing margin predictability for converters locked into annual supply contracts with beverage majors.
- Mechanical Recycling Limitations:Current reprocessing technologies degrade PET molecular weight through thermal oxidation, limiting rPET incorporation rates in pressure-sensitive carbonated beverage bottles below levels achievable in still water formats.
Strategic Opportunities
- Eastern Indonesia Penetration:Sulawesi and Papua represent underdeveloped territories where wholesale distribution networks for bulk beverage formats remain fragmented, offering first-mover advantages to converters establishing regional preform supply depots.
- Pharmaceutical Barrier Packaging:Cyclic olefin copolymer and multilayer co-injection technologies are converging to create oxygen-scavenging bottle structures for drug-contact applications, opening premium pricing tiers beyond commodity beverage segments.
- Deposit-Return System Pilots:Provincial environmental agencies in Bali and Yogyakarta are trialing container deposit legislation that would formalize collection infrastructure and secure rPET feedstock supply for integrated converters.
Industry Challenges
- Blow-Molding Technician Scarcity:Process engineers capable of calibrating multi-cavity high-speed lines with rPET blends command wage premiums, constraining capacity expansion timelines for mid-tier converters.
- Migration Testing Bottlenecks:BIS-equivalent national standards compliance for food-contact applications requires extended laboratory validation cycles, delaying commercialization of novel barrier structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Plastic Bottles Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PVC Closure Type: Flip Top, Screw Cap, Pump Dispenser, Snap-on Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale End User: Beverage Industry, Personal Care, Household Products, Pharmaceuticals |
| Companies Covered | PT Jayatama Selaras, PT Biggy Cemerlang, Jebsen & Jessen Pte Ltd, Amcor Group, PT Kadujaya Perkasa, PT Berlina Tbk, PT Indo Tirta Abadi, PT Hokkan Deltapack Industri, PT Namasindo Plas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Plastic Bottles Market Trends and Innovations
Converters across Java are reconfiguring production lines around three concurrent shifts: material substitution, regulatory compliance automation, and channel-specific format proliferation.
Mono-material polyethylene structures are collapsing multi-layer barrier complexity in personal care bottles. Shampoo and lotion brands in Greater Jakarta are adopting all-HDPE pump bottles with compatible PP closures to satisfy Indonesia's Ministry of Environment and Forestry recyclability guidelines. This collapse eliminates adhesive label substrates and metallized decoration that previously contaminated mechanical recycling streams.
Indonesia's Ministry of Environment and Forestry has operationalized mandatory extended producer responsibility reporting through digital waste-tracking platforms. Converters must now document post-consumer collection volumes and recycling rates by brand owner, creating administrative overhead that favors larger blow-molding groups with dedicated compliance functions. Small and mid-tier processors in Surabaya and Bandung are consolidating to share audit costs.
Convenience store chains in urban clusters are capturing single-serve beverage turnover from traditional wholesale channels. This channel rotation demands 350-milliliter and 500-milliliter formats with tamper-evident closures and shrink-sleeve decoration compatibility, displacing the undecorated bulk bottles dominant in rural distribution. Jakarta's convenience store density is driving fastest format innovation cycles among local preform designers.
Indonesia Plastic Bottles Market Segmentation
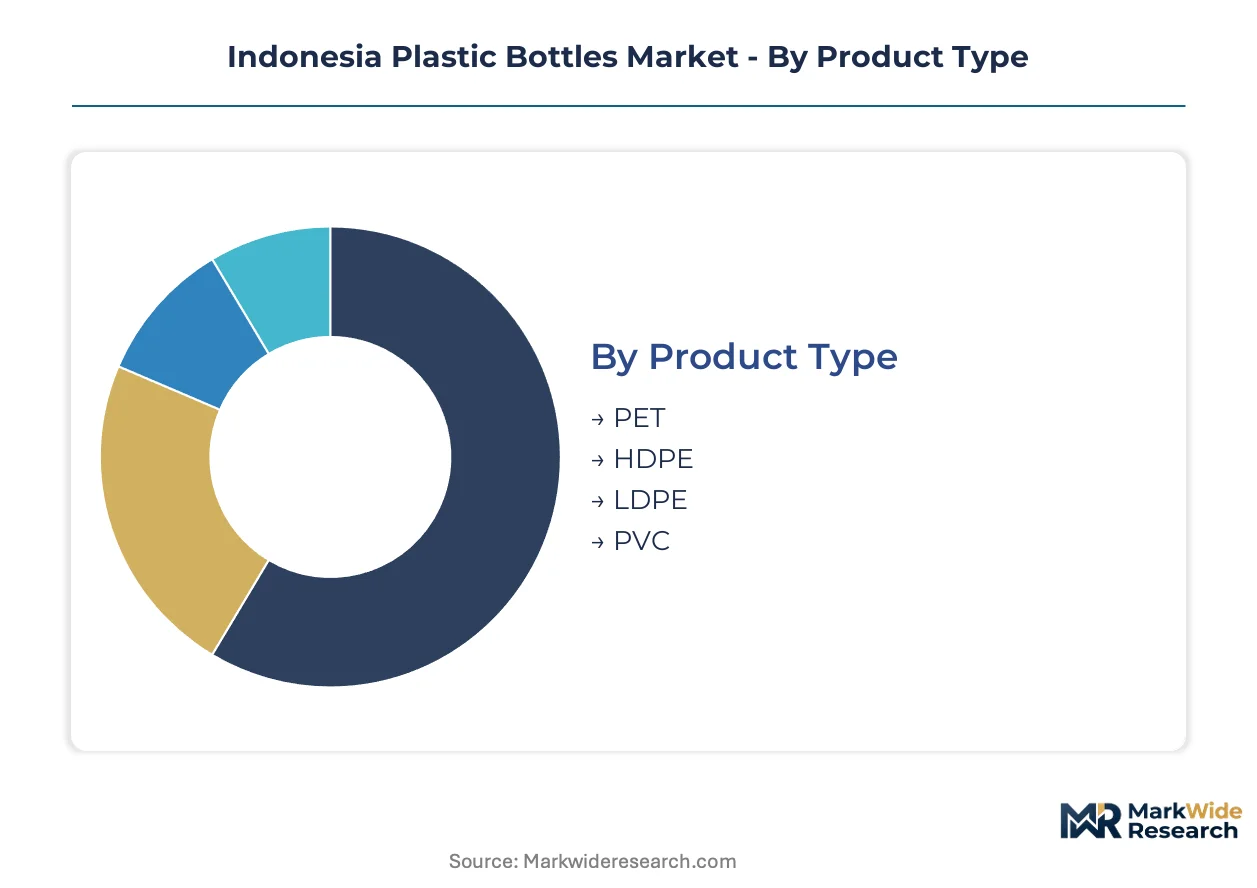
Segmentation in the Indonesia plastic bottles market reveals how resin selection, closure engineering, and channel strategy determine margin capture. Each dimension reflects distinct technical requirements and regulatory pressures shaping converter investment priorities.
Product Type:
Resin chemistry dictates barrier performance, recyclability pathways, and compliance with Indonesia's Ministry of Environment and Forestry mandates.
- PET:Amorphous polyester with excellent clarity and carbon dioxide barrier properties serves carbonated beverages and bottled water across Java's manufacturing corridor. Stretch-blow molding dominance in Greater Jakarta concentrates procurement volumes for ready-to-drink tea brands.
- HDPE:High-density polyethylene offers chemical resistance and stiffness for household cleaners and personal care formulations. Surabaya converters supply shampoo bottles to domestic brands seeking compatibility with mechanical recycling streams.
- LDPE:Lower crystallinity enables squeezeability in small-format pharmaceutical droppers and cosmetic tubes. Bandung processors target export-oriented skincare multinationals.
- PVC:Chlorinated structure provides oxygen and oil barrier for specialty pharmaceutical applications. Limited volumes reflect regulatory scrutiny on plasticizer migration under BIS-equivalent national standards.
The dominant share belongs to PET, while HDPE is closing the gap fastest as personal care brands pivot toward mono-material recyclability.
Closure Type:
Closure mechanism selection separates premium personal care positioning from commodity beverage economics.
- Screw Cap:Threaded polyethylene or polypropylene closures dominate bulk beverage formats in rural wholesale distribution. Cost engineering focuses on torque consistency and tamper-evident ring integrity.
- Pump Dispenser:Spring-loaded mechanisms with dip tubes command premium pricing in shampoo and lotion segments. Greater Jakarta decorators integrate metallized finishes for brand differentiation.
- Flip Top:Hinged polypropylene lids suit single-serve condiments and sports drinks. Convenience store channel rotation drives 350-milliliter format adoption.
- Snap-on:Press-fit closures for industrial and agricultural chemical bottles prioritize child resistance and spill prevention. Lower complexity margins attract mid-tier processors.
Screw caps retain volume leadership, though pump dispensers generate the steepest margin expansion trajectory as personal care brands upgrade packaging tiers.
Distribution Channel:
Channel structure determines format specifications, decoration requirements, and working capital intensity for converters.
- Wholesale:Bulk palletized shipments of undecorated 19-liter and 1.5-liter bottles serve traditional trade in secondary cities. Lower unit margins offset by volume concentration and minimal SKU complexity.
- Convenience Stores:Urban Jakarta clusters demand shrink-sleeve compatible 500-milliliter formats with high shelf impact. Faster inventory turns justify premium pricing for decorated preforms.
- Supermarkets:Multi-pack configurations and promotional labeling requirements strain blow-molding flexibility. National beverage majors dominate shelf space allocation.
- Online Retail:E-commerce penetration remains nascent for bulk liquids, though sample-size personal care formats gain traction through direct-to-consumer subscription models.
Wholesale channels still command the dominant volume position, while convenience stores are expanding most quickly as urbanization reshapes purchasing patterns.
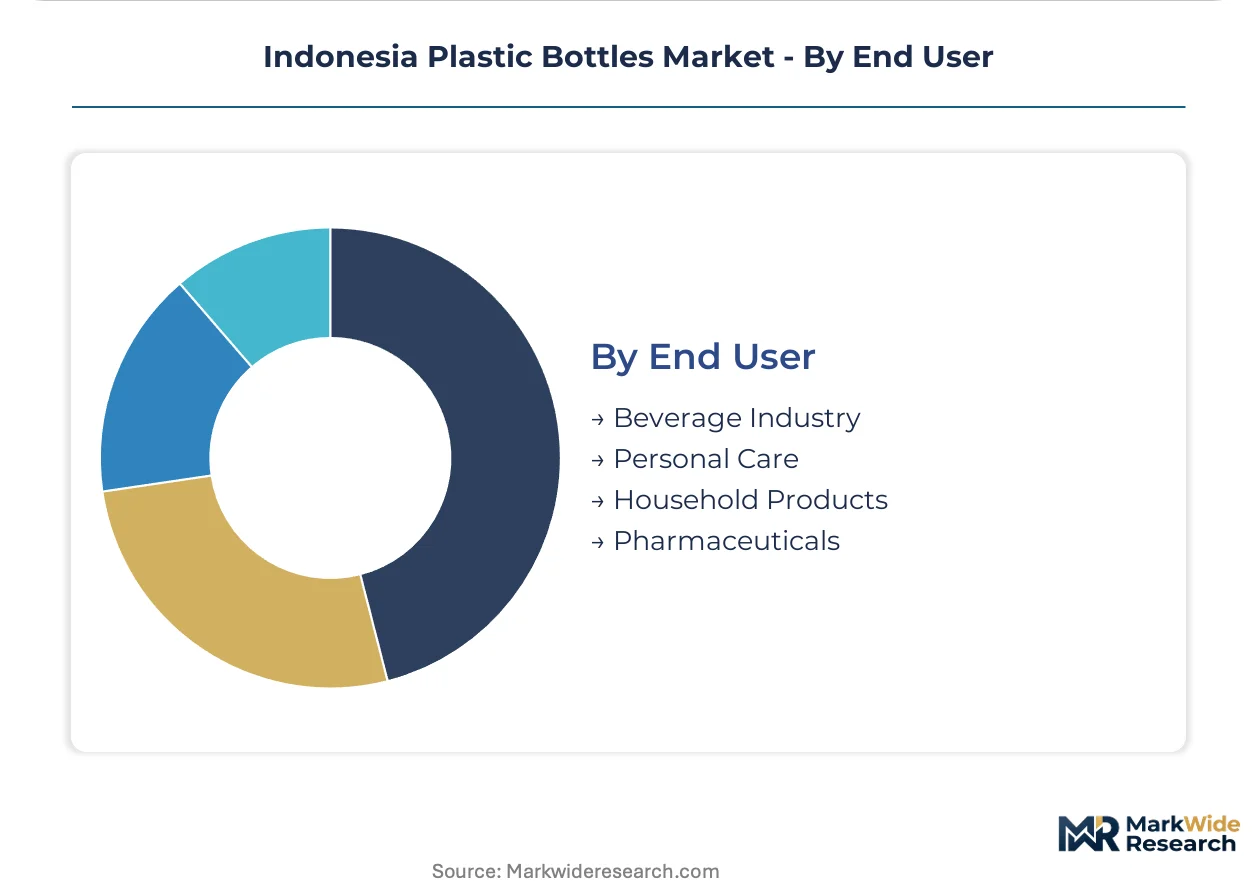
End User:
End-use application dictates regulatory burden, barrier technology requirements, and customer concentration risk.
- Beverage Industry:Carbonated soft drinks, bottled water, and ready-to-drink tea represent the largest resin offtake. EPR compliance deadlines from Indonesia's Ministry of Environment and Forestry are accelerating rPET integration timelines.
- Personal Care:Shampoo, conditioner, and lotion brands in Greater Jakarta drive decorated HDPE and PET-G demand. Mono-material pump bottle adoption simplifies recycling compliance.
- Household Products:Detergent and disinfectant bottles prioritize chemical resistance and ergonomic handling. Surabaya converters serve both domestic brands and ASEAN export markets.
- Pharmaceuticals:Drug-contact bottles face USP and ASEAN packaging guidelines enforced by the national pharmaceutical regulator. Migration testing bottlenecks delay novel barrier commercialization.
The beverage industry holds the dominant share, while pharmaceuticals present the steepest regulatory barrier to entry despite smaller volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian converters supply PET and HDPE bottles to ASEAN beverage and personal care brands, with Java's manufacturing corridor serving as the primary export staging point for regional distribution networks.
Java
Greater Jakarta anchors national blow-molding capacity, with Bekasi and Tangerang hosting integrated preform-to-bottle facilities serving ready-to-drink tea majors. Indonesia's Ministry of Environment and Forestry mandates EPR compliance documentation through digital waste-tracking platforms, favoring larger processors with dedicated compliance teams. Surabaya's converters in East Java supply shampoo and detergent bottles to domestic brands and ASEAN export markets.
Sumatra
Medan and Palembang clusters process resin for bottled water distribution across the island's plantation belt and urban centers. Provincial environmental agencies pilot deposit-return container schemes to formalize post-consumer collection infrastructure. Batam's free trade zone hosts export-oriented facilities supplying personal care multinationals with decorated HDPE formats.
Sulawesi
Makassar represents an underdeveloped territory where wholesale distribution networks for bulk beverage formats remain fragmented, offering first-mover positioning to converters establishing regional preform supply depots. The national pharmaceutical regulator enforces USP and ASEAN packaging guidelines that constrain resin grades for drug-contact applications. Local processors face technician scarcity when calibrating multi-cavity high-speed lines.
Bali and Nusa Tenggara
Tourism-driven consumption concentrates single-serve beverage demand in Denpasar and Mataram convenience store channels. Provincial environmental agencies in Bali trial container deposit legislation to secure rPET feedstock supply for integrated converters. Lombok's emerging manufacturing zones attract mid-tier processors seeking lower operational costs than Java.
Papua
Jayapura and Sorong serve mining and energy sector logistics with industrial chemical bottles, though pharmaceutical and beverage applications remain nascent. BIS-equivalent national standards compliance requires extended laboratory validation cycles for food-contact applications. Remote geography limits resin supply chain reliability, constraining capacity expansion timelines.
Indonesia Plastic Bottles Market Competitive Landscape
On the supply side, the industry is tiered between integrated blow-molding groups with captive preform capacity and mid-tier decorators serving niche personal care segments. Strategic archetypes include scale-driven beverage specialists, premium personal care decorators, and regional wholesale suppliers. Dominant competitive moves center on backward integration into rPET flake processing and geographic expansion through regional preform depot establishment.
Among Indonesia-based converters, PT Jayatama Selaras and PT Biggy Cemerlang exemplify distinct positioning archetypes within the domestic supply base. Amcor Group represents multinational preform design expertise that reduces resin use per unit. These three entities occupy positions spanning integrated blow-molding scale, decorated HDPE specialization, and global technical standards.
| Leading Market Players |
|---|
| PT Jayatama Selaras |
| PT Biggy Cemerlang |
| Jebsen & Jessen Pte Ltd |
| Amcor Group |
| PT Kadujaya Perkasa |
| PT Berlina Tbk |
| PT Indo Tirta Abadi |
| PT Hokkan Deltapack Industri |
| PT Namasindo Plas |
| Others |
Pricing and Supply Chain Analysis
Greater Jakarta's blow-molding corridor concentrates PET preform capacity, granting integrated converters pricing leverage over beverage majors locked into annual offtake contracts. Indonesia's Ministry of Environment and Forestry rPET mandates are forcing resin substitution economics that compress margin predictability for mid-tier processors lacking decontamination infrastructure.
Pricing Analysis
Prior-generation virgin PET formulations trade at commodity spot discounts against next-generation rPET-integrated structures that command compliance premiums. Three-tier pricing structure across premium, standard, and economy levels separates pump-dispenser personal care bottles from screw-cap beverage formats and undecorated wholesale bulk containers. Price differentiation rests on certification grade and volume scale, with EPR-compliant rPET blends carrying cost premiums that virgin resin cannot match. Cost compression in standard-tier beverage bottles is intensifying because naphtha-linked feedstock volatility transfers risk to converters, while personal care brands show least price sensitivity for barrier-enhanced pharmaceutical formats.
Supply Chain Analysis
Extended payment terms from beverage majors strain working capital for mid-tier converters, driving supply-chain finance facility adoption among Bandung and Surabaya processors. Purified terephthalic acid and monoethylene glycol feedstocks draw from Singapore, South Korea, and Thailand petrochemical hubs, while rPET flake sourcing concentrates around Greater Jakarta's collection infrastructure. Single-source vulnerability runs through mechanical recycling capacity that degrades PET molecular weight, limiting pressure-sensitive carbonated beverage applications. Distribution runs through wholesale pallet networks for rural bulk formats and convenience store direct delivery for urban single-serve SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's plastic bottles market rewards defensive positioning through regulatory entrenchment, where EPR compliance documentation and BIS-equivalent national standards certification create switching costs that anchor multi-year beverage supply contracts.
For Market Incumbents: Entrench position through backward integration into rPET flake processing and captive preform capacity expansion in East Java's Surabaya cluster. Indonesia's Ministry of Environment and Forestry digital waste-tracking platforms favor processors with dedicated compliance teams, while blow-molding technician scarcity threatens capacity timelines for competitors. Defend margin structure by locking long-term resin supply contracts before naphtha volatility intensifies. For New Entrants and Emerging Players: Sulawesi's Makassar corridor and Papua's Jayapura logistics hubs represent the most penetrable entry points for regional preform depot establishment, where fragmented wholesale distribution lacks integrated supply. Eastern Indonesia's underdeveloped collection infrastructure offers first-mover positioning for deposit-return system pilots before provincial environmental agencies formalize rPET feedstock channels. Target pharmaceutical barrier packaging as a go-to-market angle, where USP and ASEAN packaging guideline compliance delays incumbent innovation cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with decontamination line investments and digital EPR compliance infrastructure. Long-term viability over a multi-year horizon rests on securing rPET feedstock supply through collection infrastructure control rather than spot market dependence. Acquisition target archetype: mid-tier decorators in Greater Jakarta with personal care brand relationships and underutilized blow-molding capacity. Monitor provincial environmental agency deposit-return legislation progression as the inflection signal for feedstock security.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Decontamination Line Investment | Indonesia's Ministry of Environment and Forestry mandates drive compliance-capable capacity expansion. |
| Regional Preform Depot Establishment | Sulawesi and Papua fragmentation offers first-mover positioning before wholesale consolidation. |
| Pharmaceutical Barrier Packaging Development | Cyclic olefin copolymer co-injection opens premium tiers beyond commodity beverage segments. |
| Digital EPR Compliance Platform Integration | Waste-tracking documentation requirements favor processors with dedicated audit functions. |
| Backward Integration into Collection Infrastructure | Deposit-return pilots in Bali and Yogyakarta secure captive rPET flake supply. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with blow-molding plant managers, beverage procurement leads, personal care brand packaging directors, and recycling facility operators. Secondary validation drew from Indonesia's Ministry of Environment and Forestry regulatory filings, BIS-equivalent national standards documentation, customs trade data on resin imports, and ASEAN packaging guideline repositories. Bottom-up capacity assessments across Java, Sumatra, and Eastern Indonesia triangulated against top-down consumption estimates from ready-to-drink tea and bottled water volume trends.
Calibration against historical resin price volatility and EPR implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include resin chemistry tier, closure mechanism complexity, distribution channel structure, and end-use regulatory burden. CAGRs were derived from weighted average growth trajectories across beverage, personal care, household, and pharmaceutical demand clusters. Industry-specific inputs incorporated stretch-blow molding technology adoption curves and mechanical recycling yield degradation rates.
Practitioners should monitor provincial environmental agency deposit-return legislation progression and rPET collection infrastructure buildout for early signals of feedstock security shifts. Forecasts reflect documented assumptions on EPR enforcement intensity, naphtha-linked resin pricing continuity, and blow-molding technician labor market tightness. Macroeconomic contraction, regulatory enforcement deviation, or advanced chemical recycling technology commercialization would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
North America Soft Drinks Packaging Market
Beverage Packaging
Foldable Bottles Market
Beverage Packaging
Cup Filler Market
Beverage Packaging
French Square Bottle Market
Beverage Packaging
Zippered Bottle Suit Market
Beverage Packaging
Bottle Shippers Market
Beverage Packaging
Stackable Beaker Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Disposable Water Bottle Market
Beverage Packaging
Beverage Cups Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
Ice Transport Buckets Market
Beverage Packaging
Tumblers Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
US Soft Drinks Packaging Market
Beverage Packaging
Bottled Water Packaging Market