
 Self-Chilling Can Market | 2026-2036
Self-Chilling Can Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Chilling Can Market Analytics
CE marking under the EU Machinery Directive is bifurcating which self-chilling can manufacturers can access European retail channels. Ball Corporation leverages its aluminum can production scale to integrate chilling chambers directly into standard beverage lines. Tempra Technology specializes in proprietary heat-exchange chemistries that differentiate its licensing portfolio from commodity packaging suppliers.
A self-chilling can is a pressurized beverage container with an integrated endothermic cooling mechanism, typically activated by a twist or button that releases a desiccant or refrigerant into an isolated chamber to absorb heat from the beverage. The primary commercial purpose is to deliver chilled drinks without external refrigeration infrastructure, targeting consumption moments where ice or coolers are impractical. Aluminum cans anchor the product type segment due to thermal conductivity advantages and established recycling streams, while eco-friendly options represent the fastest-growing category as brands respond to Extended Producer Responsibility frameworks. Outdoor events dominate the use case segment in volume terms, though sports activities capture higher per-unit premiums through branded athletic partnerships.
The EPA Significant New Alternatives Policy program governs which refrigerant chemistries qualify for US-market self-chilling devices, directly constraining R&D pathways for domestic manufacturers. REACH compliance in Europe adds toxicity-testing burdens that favor established chemical suppliers over novel coolant entrants. Stakeholders must monitor how evolving state-level beverage container deposit laws interact with multi-chamber can designs that complicate material sorting at recycling facilities.
Market Dynamics
The EU F-Gas Regulation's hydrofluorocarbon phase-down is compressing coolant options and forcing water-based and CO2 activation systems into commercial production ahead of planned R&D cycles.
Growth Catalysts
- Outdoor recreation demand:Portable cooling solutions align with United States camping and festival culture where ice access is unreliable. Beverage brands embed self-chilling cans into premium summer product lines.
- REACH compliance barriers:European toxicity-testing requirements favor established chemical suppliers, creating protected licensing positions for compliant heat-exchange formulations.
- Aluminum thermal conductivity:Established recycling streams and heat-transfer efficiency make aluminum cans the default substrate, reducing commercialization risk for new entrants.
Market Restraints
- Desiccant cost volatility:Zeolite and silica gel input prices fluctuate with industrial gas separation demand, squeezing margins on high-volume production runs.
- Multi-chamber recycling complexity:Deposit-return schemes in Germany and Scandinavian markets face material-sorting failures when consumers discard intact dual-chamber designs.
- EPA SNAP refrigerant constraints:The Significant New Alternatives Policy program limits approved chemistries, extending R&D timelines for novel coolant pathways.
Strategic Opportunities
- Sports beverage partnerships:Athletic event sponsorships command per-unit premiums and create branded consumption moments outside traditional retail.
- Extended Producer Responsibility frameworks:EU packaging waste directives incentivize eco-friendly can designs with simplified material separation.
- Military and emergency services procurement:Field ration applications in the United States and NATO member states require refrigeration-independent cooling for operational readiness.
Industry Challenges
- Heat-exchange engineering talent scarcity:Cross-disciplinary expertise combining chemical kinetics and pressure-vessel design concentrates in aerospace and automotive sectors, not packaging.
- CE marking timeline compression:Machinery Directive compliance for twist-activation mechanisms requires extensive safety documentation, delaying European market entry.
- Legacy filling line retrofit costs:Integrated chilling chambers demand modified seaming and pressurization equipment, straining capital allocation at mid-tier beverage co-packers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Chilling Can Market |
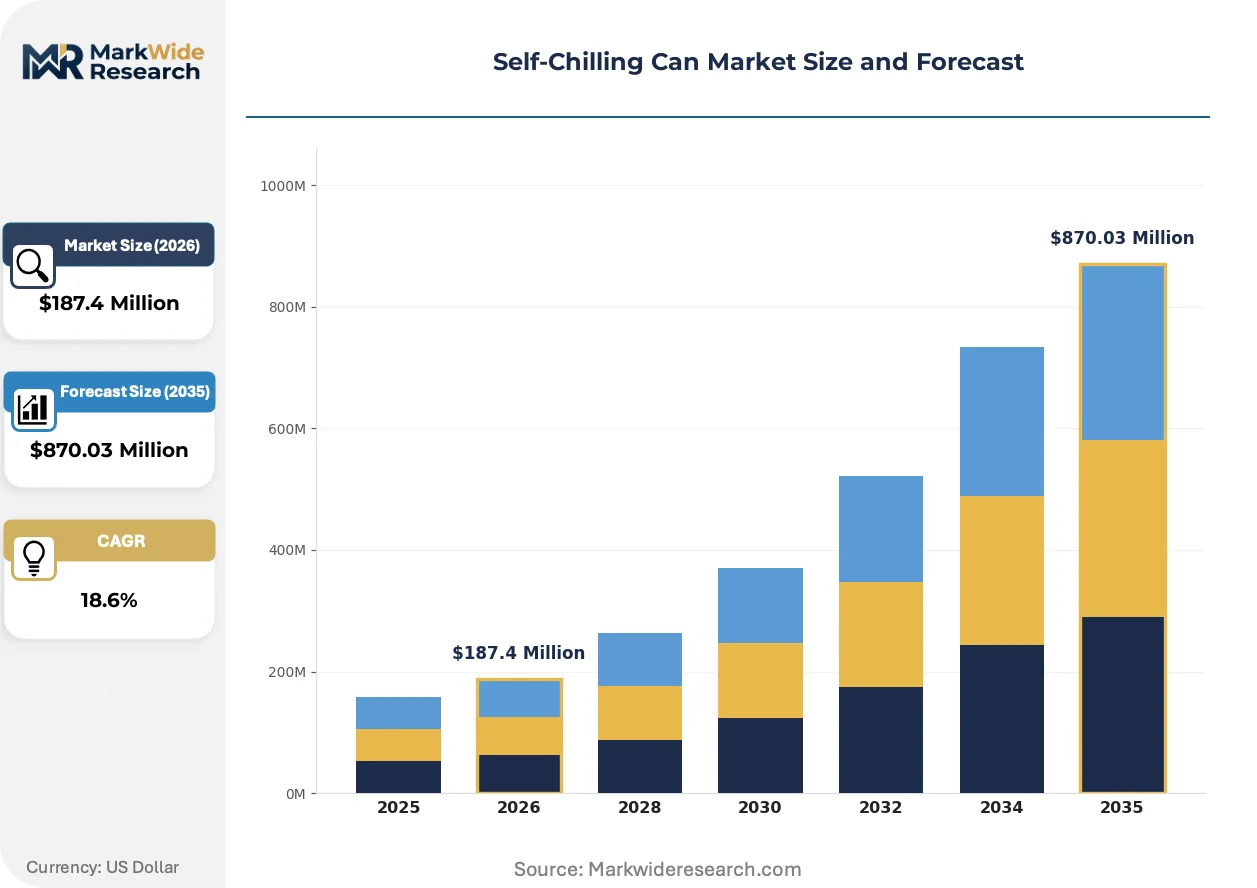
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Plastic Cans, Glass Bottles, Eco-friendly Options Use Case: Outdoor Events, Sports Activities, Parties, Picnics Distribution Channel: Retail Stores, E-commerce, Wholesale, Direct Sales Customer Segment: Young Adults, Families, Event Planners, Outdoor Enthusiasts |
| Companies Covered | The Joseph Company International, Ball Corporation, PepsiCo, Ardagh Group, Delta H Innovations, Coca-Cola, Carlsberg, Heineken, Tempra Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Chilling Can Market Evolving Landscape
Activation mechanisms are diversifying beyond twist-release designs as manufacturers compete on user experience and safety certification speed. The technology frontier is fragmenting across multiple competing approaches.
CO2-adsorption cooling is fragmenting the incumbent desiccant market by offering faster temperature drops without hydrofluorocarbon regulatory exposure. Premium ready-to-drink coffee and functional beverage brands in the United States are piloting button-activated designs for convenience-store channels. This fragmentation is compressing licensing windows for older heat-exchange chemistries before they achieve scale.
The EU F-Gas Regulation's 2024-2030 phase-down schedule is eliminating R-134a and similar coolants from self-chilling device approvals. Manufacturers are reformulating around water-vapor compression and solid-state thermoelectric alternatives, though energy density remains inferior. German and French retail chains now require pre-approval documentation proving coolant compliance before listing negotiations begin.
Direct-to-consumer subscription models for premium beverage discovery boxes are bypassing traditional grocery slotting fees and creating test markets for novel packaging formats. Specialty coffee and craft cocktail mixers use these channels to validate self-chilling acceptance before mass retail negotiations. This pattern is most visible in California and Texas metropolitan markets where warehouse club penetration is lower and delivery density supports experimentation.
Self-Chilling Can Market Segmentation
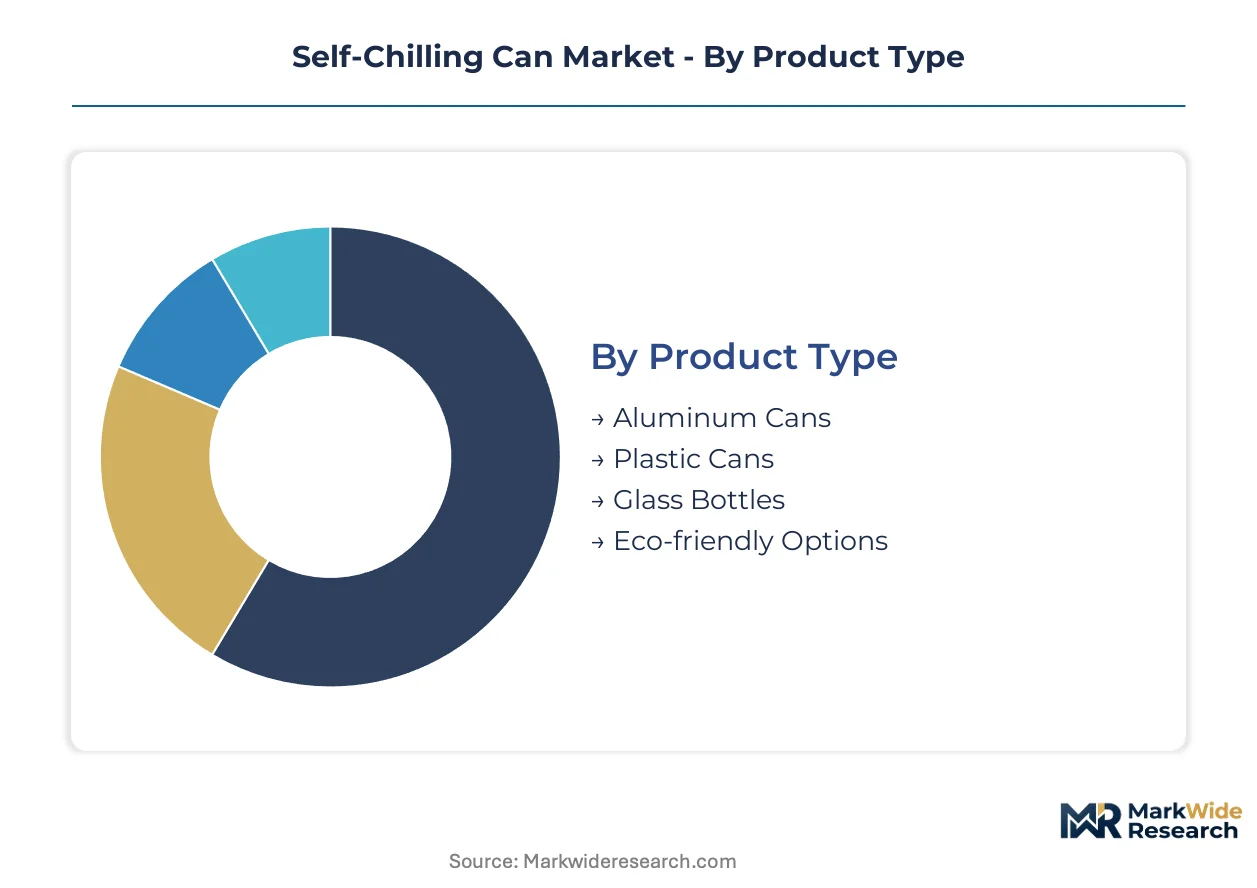
Self-chilling packaging configurations vary sharply by thermal conductivity requirements and recycling infrastructure compatibility. Manufacturers align substrate choices with regional deposit-return schemes and beverage brand sustainability commitments.
Product Type:
Aluminum can formats dominate export volumes to North American and European markets, while plastic and glass variants serve localized distribution in regions with weaker aluminum recycling loops.
- Aluminum Cans:Superior thermal conductivity enables faster heat transfer from endothermic chambers to beverage contents. United States outdoor recreation brands specify aluminum for premium summer product lines targeting camping and festival consumption moments where ice access is unreliable.
- Eco-friendly Options:Biodegradable substrates and simplified single-material designs respond to Extended Producer Responsibility frameworks in Germany and France. These formats gain shelf space in Scandinavian retail chains where pre-approval documentation for material separation is mandatory.
- Plastic Cans:Lightweight PET barriers suit markets with underdeveloped aluminum collection infrastructure.
- Glass Bottles:Premium positioning in direct-to-subscription channels where breakage risk is controlled.
Aluminum Cans holds the largest share; momentum sits with Eco-friendly Options.
Use Case:
Volume concentration tracks seasonal outdoor activity patterns, with per-unit premiums correlating to branded athletic partnerships and emergency procurement specifications.
- Outdoor Events:Music festivals and camping gatherings in the United States generate bulk demand for refrigeration-independent cooling. Beverage manufacturers embed twist-activation designs into limited-edition summer releases to capture impulse purchases at convenience-store channels near recreational corridors.
- Sports Activities:Marathons and endurance events command pricing premiums through exclusive supplier contracts. NATO field ration applications represent a parallel demand stream with stringent operational readiness requirements for temperature-controlled hydration.
- Parties:Social gathering formats favor multi-packs with synchronized activation mechanisms.
- Picnics:Smaller household units suit suburban retail distribution.
Outdoor Events anchors volume; Sports Activities captures the steepest expansion trajectory through procurement diversification.
Distribution Channel:
Channel selection reflects capital intensity tradeoffs between slotting fee negotiations and logistics infrastructure ownership.
- Retail Stores:Grocery and convenience-store placement requires modified seaming equipment compatibility with existing filling lines. German and French retail chains now demand coolant compliance documentation before listing negotiations for self-chilling SKUs.
- E-commerce:Direct-to-consumer subscription models bypass traditional slotting fees and create test markets for novel packaging formats. Specialty coffee and craft cocktail mixers in California and Texas metropolitan markets use these channels to validate acceptance before mass retail expansion.
- Wholesale:Bulk procurement serves event catering and institutional buyers.
- Direct Sales:Military and emergency services contracts specify technical performance standards.
Retail Stores maintains channel dominance; E-commerce is climbing the fastest on subscription model adoption.
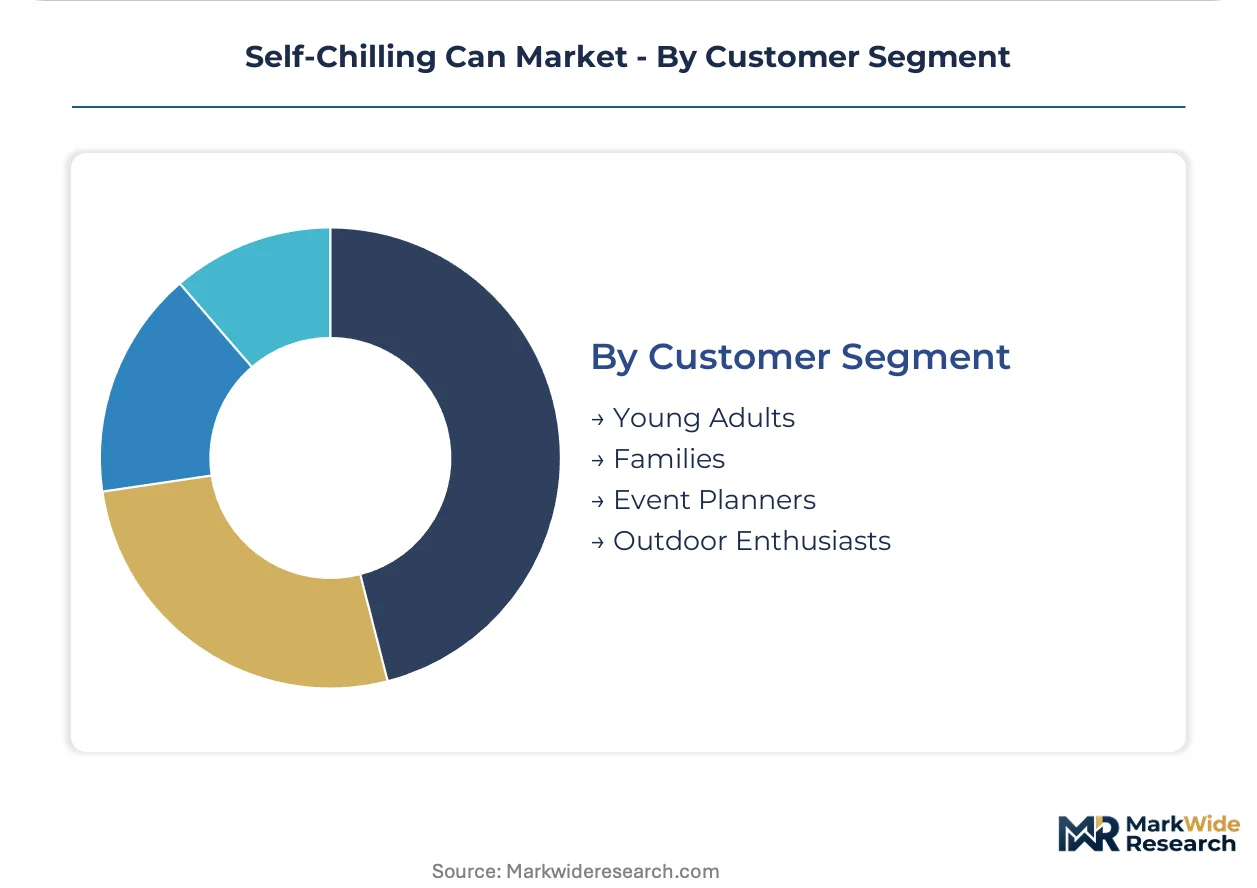
Customer Segment:
Purchasing behavior splits between experiential trial seekers and repeat buyers prioritizing convenience reliability.
- Young Adults:Festival attendance and social media shareability drive trial purchases of button-activated designs. This cohort shows highest willingness to pay premium pricing for novel activation mechanisms in United States convenience-store channels.
- Outdoor Enthusiasts:Camping and hiking practitioners require consistent performance across temperature extremes. Product loyalty concentrates here due to repeated backcountry use cases where equipment failure carries consequential costs.
- Families:Picnic and beach outing formats favor multi-unit packaging.
- Event Planners:Corporate and wedding procurement specifies bulk reliability.
Young Adults represents the largest addressable base; Outdoor Enthusiasts delivers the highest lifetime value through repeat purchase concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Outdoor enthusiasts and festival-goers cluster in the United States, while European premium beverage buyers respond to sustainability mandates. Military procurement programs in NATO member states generate specialized demand for field-ready cooling. Asian markets remain nascent, with Japanese convenience-store chains testing limited summer releases.
United States
Camping and music festival culture drives bulk adoption of twist-activation designs. The EPA Significant New Alternatives Policy constrains refrigerant chemistries, extending R&D timelines for domestic manufacturers. Austin and Denver anchor test markets where craft beverage brands pilot button-activated formats in convenience-store channels.
Germany
Extended Producer Responsibility frameworks mandate simplified material separation in multi-chamber designs. The EU F-Gas Regulation's hydrofluorocarbon phase-down eliminates legacy coolant options ahead of planned cycles. Bavarian retail chains now require pre-approval coolant compliance documentation before listing negotiations commence.
France
Premium ready-to-drink coffee brands target direct-to-consumer subscription channels. REACH compliance adds toxicity-testing burdens that favor established chemical suppliers over novel entrants. Parisian metropolitan markets host pilot programs for solid-state thermoelectric alternatives in summer beverage lines.
United Kingdom
Deposit-return scheme infrastructure faces sorting failures with intact dual-chamber can designs. CE marking under the EU Machinery Directive bifurcates manufacturer access to European retail channels. London-based beverage co-packers retrofit filling lines to accommodate integrated chilling chamber seaming requirements.
Japan
Convenience-store density supports limited-edition summer product testing. The country's national chemical safety regulator evaluates heat-exchange formulations under industrial chemical notification procedures. Tokyo and Osaka metropolitan clusters demonstrate highest willingness-to-pay for portable cooling in premium beverage segments.
Self-Chilling Can Market Competitive Landscape
Player mix skews toward diversified packaging conglomerates with aluminum production scale. The vendor base concentrates around three strategic tiers: integrated can manufacturers with chilling chamber fabrication capabilities, specialty heat-exchange chemistry licensors, and beverage brand owners pursuing captive packaging differentiation. Competitive moves center on filling line retrofit partnerships and coolant formulation licensing agreements.
Within the integrated packaging tier, Ball Corporation and Ardagh Group occupy positions that exemplify scale-driven substrate advantages. Tempra Technology represents the specialty chemistry archetype through its proprietary heat-exchange formulations. The Joseph Company International anchors the independent technology development segment. These three entities collectively illustrate how competitive positioning fragments across manufacturing scale, chemical intellectual property, and activation mechanism innovation.
| Leading Market Players |
|---|
| The Joseph Company International |
| Ball Corporation |
| PepsiCo |
| Ardagh Group |
| Delta H Innovations |
| Coca-Cola |
| Carlsberg |
| Heineken |
| Tempra Technology |
| Others |
Value Network & Pricing Analysis
Ninety-day desiccant inventory buffers at German chemical suppliers concentrate pricing leverage among established REACH-compliant formulators, compressing margins for mid-tier beverage co-packers unable to secure long-term offtake agreements. This lead-time rigidity forces smaller manufacturers toward spot-market zeolite procurement, amplifying cost volatility that larger integrated players can absorb through captive supply arrangements.
Pricing Analysis
Cost-plus contracts indexed to industrial gas separation demand govern bulk desiccant supply, with Ball Corporation and Ardagh Group leveraging aluminum production scale to secure fixed-price multi-year agreements. Price differentiation separates premium button-activated designs commanding athletic sponsorship premiums from standard twist-release formats in convenience-store channels. Pricing pressure intensifies in the eco-friendly segment as Extended Producer Responsibility frameworks mandate simplified material separation without volume scale to amortize R&D. Outdoor enthusiasts demonstrate lowest price sensitivity due to repeated backcountry use cases, while young adult trial purchasers in United States festival corridors exhibit highest elasticity.
Supply Chain Analysis
Strait of Malacca transit underwrites zeolite feedstock flows from Australian mineral processors to Chinese activation facilities, creating a chokepoint where shipping congestion propagates through downstream refrigerant chemistry production. Supply concentration centers on Germany and France for REACH-compliant heat-exchange formulations, with United States EPA SNAP constraints forcing domestic manufacturers to source from approved import channels. Raw material dependencies span high-purity aluminum sheet, synthetic zeolite grades, and pressurized CO2 charges. Single-source vulnerability in specialty desiccant activation exposes mid-tier players to allocation cuts during industrial gas demand spikes. Distribution runs through beverage co-packer networks with modified seaming equipment, bypassing traditional packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives against portable thermoelectric coolers and insulated flask technologies that erode the convenience advantage of single-use chilling packaging. Refrigeration-independent alternatives threaten to commoditize the core value proposition if activation mechanisms fail to differentiate on speed and reliability.
For Market Incumbents: Consolidate heat-exchange chemistry licensing positions through exclusive supply agreements with REACH-compliant German formulators, securing protected access as EU F-Gas Regulation phase-down eliminates commodity coolant alternatives. Acquire mid-tier beverage co-packers with installed chilling chamber seaming capacity to lock out new entrants from filling line retrofit queues. Vertical integration into aluminum can fabrication insulates against Ball Corporation and Ardagh Group pricing power in substrate supply. For New Entrants and Emerging Players: Anchor in direct-to-consumer subscription channels for premium ready-to-drink coffee and functional beverages, where warehouse club penetration gaps in California and Texas metropolitan markets support experimentation without mass retail slotting fee burdens. Target military and emergency services procurement specifications in NATO member states, where operational readiness requirements create insulated demand with stringent technical barriers to incumbent pivot. Pursue white-label manufacturing partnerships with athletic event organizers seeking branded cooling solutions for endurance sports sponsorships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state thermoelectric alternatives as energy density improvements demand specialized semiconductor fabrication partnerships. Long-term viability hinges on identifying acquisition targets with captive heat-exchange chemistry IP rather than commodity packaging assembly capacity. Watch for inflection signals in German retail chain pre-approval documentation timelines, which compress licensing windows for novel coolant pathways and favor incumbent chemical suppliers with established compliance dossiers.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Exchange Chemistry Licensing | REACH-compliant formulations from German suppliers create protected market positions under EU F-Gas Regulation phase-down mandates. |
| Filling Line Retrofit Partnerships | Modified seaming equipment agreements with United States beverage co-packers lock in capacity before queue congestion intensifies. |
| Athletic Event Sponsorship Contracts | Exclusive supplier status at marathons commands per-unit premiums and validates button-activation designs for mass retail expansion. |
| Military Procurement Certification | NATO field ration specifications generate insulated demand with operational readiness requirements that civilian alternatives cannot satisfy. |
| Eco-Friendly Material Separation Simplification | Single-chamber biodegradable designs respond to Extended Producer Responsibility frameworks in Scandinavian retail chains. |
Research Methodology
Initial hypotheses were tested against primary input from beverage packaging R&D directors, heat-exchange chemistry formulators, retail category buyers, and military procurement officers, then refined through secondary validation against EPA SNAP refrigerant approval databases, EU F-Gas Regulation implementation guidance, and aluminum industry trade flow records. Bottom-up demand modeling across outdoor recreation, sports activities, and emergency services use cases triangulated with top-down packaging consumption projections to constrain variance bands.
Variance decomposition across product type, use case, distribution channel, and customer segment dimensions isolated growth contribution by substrate format and activation mechanism. CAGRs were derived from segment-level volume build-ups incorporating filling line retrofit timelines and coolant compliance approval pathways. Forecast inputs included desiccant cost index trajectories, deposit-return scheme expansion schedules, and direct-to-consumer subscription penetration rates in test markets.
Material uncertainties — desiccant price volatility, CE marking timeline compression for novel activation mechanisms, and state-level beverage container deposit law evolution — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and filling line retrofit capacity availability. Practitioners should keep alternative scenarios live as EU F-Gas Regulation enforcement intensity and United States outdoor recreation participation rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
US Beverage Packaging Market
Beverage Packaging
Insulated Cup Sleeves Market
Beverage Packaging
Indonesia Plastic Bottles Market
Beverage Packaging
Multicomponent Bottle Market
Beverage Packaging
Asia Pacific Beverage Packaging Market
Beverage Packaging
Vending Cups Market
Beverage Packaging
Bottle Shippers Market
Beverage Packaging
Juice Packaging Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Drink Hoses Market
Beverage Packaging
North America Beverage Packaging Market
Beverage Packaging
Cup Filler Market
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
US Soft Drinks Packaging Market
Beverage Packaging
Water Bottle Racks Market