
 Dual Chamber Bottles Market | 2026-2036
Dual Chamber Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Chamber Bottles Market Foresight
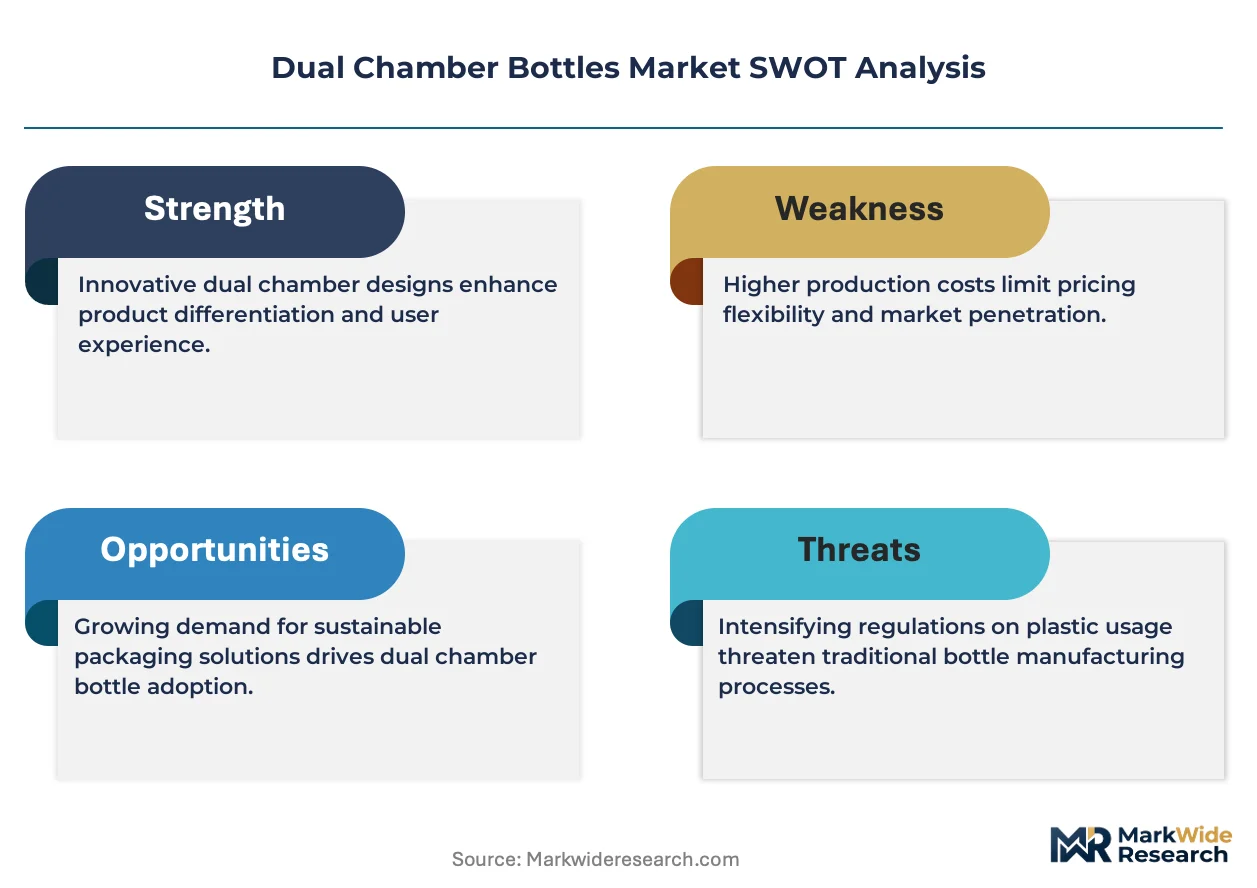
The capital-intensity divergence between blow-molding specialists and glass converters is rotating competitive advantage toward firms with in-house toolmaking and barrier-coating capabilities. Berry Global Inc. leverages its thermoforming scale to supply multi-layer plastic dual chamber systems for personal care brands. Gerresheimer AG anchors pharmaceutical demand through borosilicate glass expertise and cleanroom-certified production lines. TekniPlex Healthcare competes in healthcare applications with coextrusion technology that extends oxygen and moisture barriers for sensitive drug formulations.
Dual chamber bottles are rigid containers engineered with two isolated compartments within a single vessel, typically separated by an internal wall or membrane, enabling simultaneous storage and sequential dispensing of incompatible ingredients such as reactive adhesives, two-part pharmaceuticals, or separated cosmetic actives. Plastic dominates unit volume due to polyethylene terephthalate and polypropylene compatibility with injection-blow molding, though glass commands premium positioning in parenteral and high-barrier pharmaceutical segments. Flip top and pump closure types are gaining share in cosmetics end use where consumer convenience drives replacement cycles, while screw cap configurations sustain industrial and food applications where reseal integrity outweighs dispensing sophistication.
FDA enforces child-resistant packaging standards under 16 CFR 1700 that directly shape dual chamber bottle design for pharmaceutical and household chemical applications, while EMA's Annex 1 sterile manufacturing guidelines elevate barrier performance requirements for European drug packaging. REACH chemical registration and RoHS substance restrictions in Europe further constrain material selection for plastic and composite variants, compelling converters to validate alternative stabilizers and colorants. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and individual US state legislation, as these will increasingly determine material recyclability specifications and post-consumer collection economics for multi-component packaging formats.
Market Dynamics
Pharmaceutical serialization mandates and EMA Annex 1 sterile manufacturing guidelines are forcing dual chamber bottle converters to revalidate barrier architectures and cleanroom protocols, compressing development timelines while elevating capital requirements for compliant production lines.
Growth Catalysts
- EMA Annex 1 sterile guidelines:European pharmaceutical packaging demand now requires validated barrier separation systems, accelerating dual chamber adoption for parenteral drug delivery.
- Cosmetic actives stabilization:Premium skincare brands in Germany and France deploy dual chamber formats to isolate vitamin C and retinol compounds until point-of-use activation.
- Polypropylene coextrusion advances:Multi-layer blow-molding improvements enable oxygen transmission rates below 0.1 cc per day, opening pharmaceutical applications previously reserved for glass.
Market Restraints
- Specialized tool steel scarcity:Precision mold fabrication for dual chamber geometries requires Swedish and Japanese tool steel grades subject to export licensing delays.
- Barrier coating input volatility:Ethylene vinyl alcohol resin prices fluctuate with ethylene feedstock costs, squeezing margin predictability for multi-layer plastic converters.
- Glass substitution persistence:Borosilicate vials retain preference for biologic drugs requiring absolute inertness, limiting plastic dual chamber penetration in high-value parenterals.
Strategic Opportunities
- Indian pharmaceutical contract manufacturing:CDSCO export-oriented unit approvals for sterile injectables create demand for pre-sterilized dual chamber systems with integrated closure.
- Dual-cure adhesive packaging:Industrial assembly applications in automotive and electronics sectors require separated resin-hardener formats with precision mix ratios.
- EU Green Deal packaging targets:Extended producer responsibility frameworks incentivize mono-material dual chamber designs compatible with existing polyethylene recycling streams.
Industry Challenges
- Cleanroom certification timelines:ISO 14644 Class 7 validation for dual chamber pharmaceutical production extends facility commissioning by 8-14 months.
- Multi-component assembly precision:Internal wall welding and membrane integration demand micron-level tolerance control that exceeds standard blow-molding capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Chamber Bottles Market |
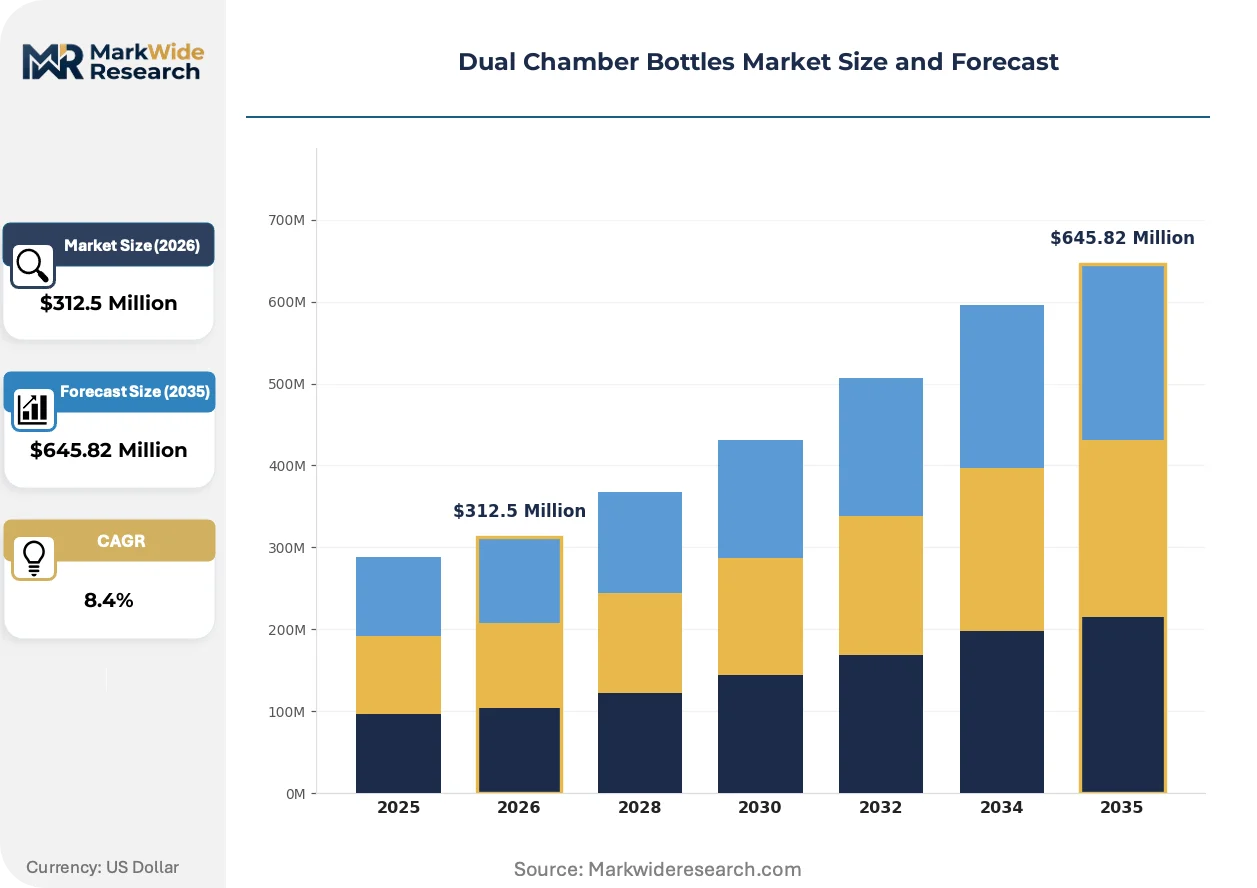
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Metal, Composite Capacity: 50ml, 100ml, 200ml, 500ml End User: Cosmetics, Pharmaceuticals, Food & Beverages, Industrial Closure Type: Screw Cap, Flip Top, Pump, Dropper |
| Companies Covered | Berry Global Inc., TekniPlex Healthcare, AptarGroup, Inc., Gidea Packaging, Cospack America, Silgan Holdings Inc., TricorBraun, Raepak, Gerresheimer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Chamber Bottles Market Shifts & Advancements
Barrier coating technologies and closure integration advances are compressing the performance gap between plastic and glass dual chamber systems, while regulatory pressure on pharmaceutical packaging sterility accelerates format standardization.
Silicon oxide plasma-enhanced chemical vapor deposition is displacing traditional multilayer coextrusion for oxygen-sensitive pharmaceutical applications. Parenteral drug packagers in Switzerland and Germany are qualifying these barrier-coated polyethylene terephthalate bottles for 24-month shelf life claims. The technology is displacing glass vials in non-critical biologic delivery where break resistance and weight reduction justify validation costs.
REACH Annex XIV authorization requirements for phthalate plasticizers are compelling converters to validate alternative polymerization catalysts and external lubricant systems. European compounders must now document full substance flow for stabilizers used in polypropylene dual chamber bottles. Small-volume parenteral applications face the steepest compliance burden, driving consolidation toward suppliers with in-house regulatory affairs capabilities.
Direct-to-clinic procurement platforms are compressing traditional distribution tiers for pharmaceutical dual chamber packaging. Hospital networks in the United States and Nordic countries now specify lot-level traceability and temperature excursion documentation as standard contract terms. Generic drug manufacturers without captive molding operations face margin compression as these requirements pass through to packaging specifications.
Dual Chamber Bottles Market Segmentation
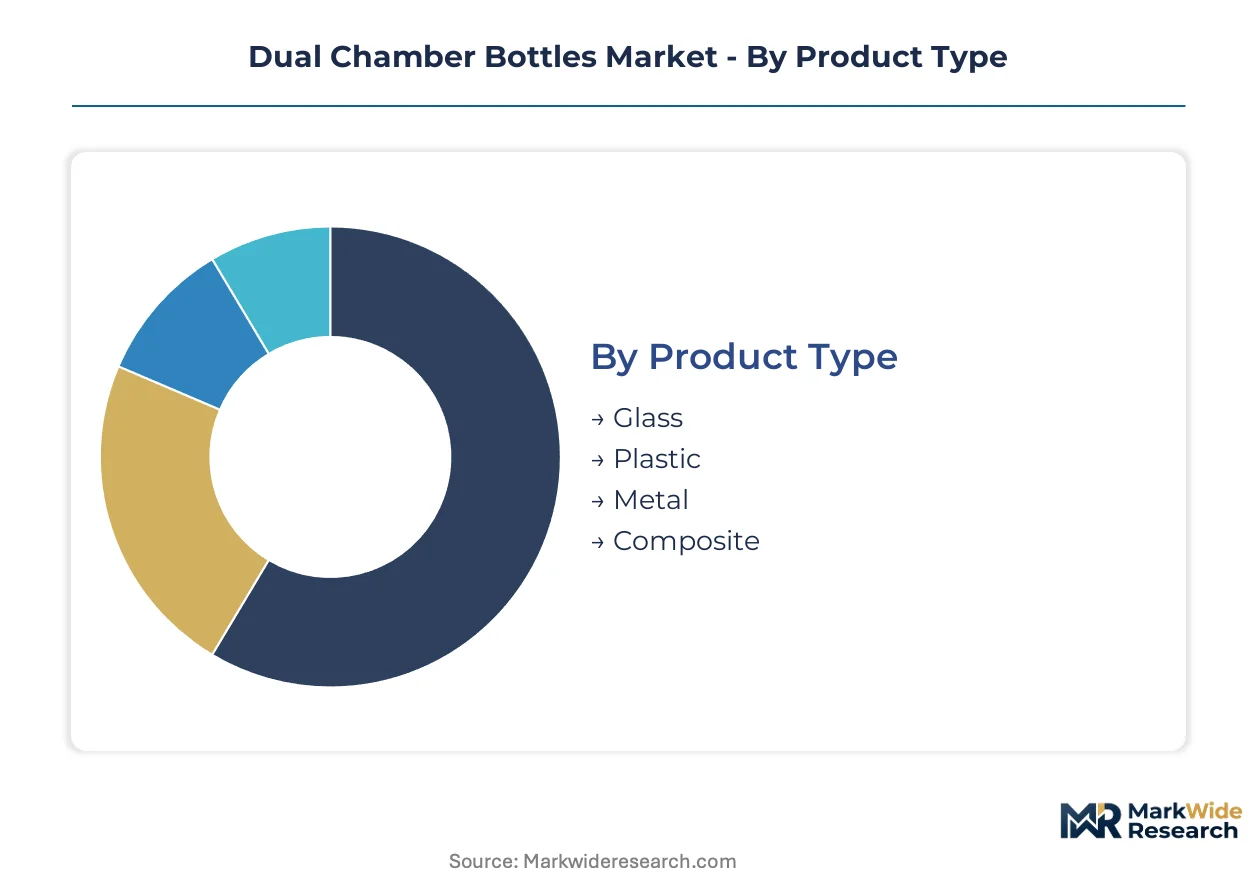
Dual chamber bottle converters configure production assets around material-process pairings and end-use certification tiers. Segment boundaries shift as barrier coating advances redraw the plastic-glass frontier and as pharmaceutical serialization mandates reshape closure integration requirements.
Product Type:
Glass dual chamber formats face intensifying substitution pressure from silicon oxide barrier-coated polyethylene terephthalate in parenteral applications, while metal and composite variants defend niche positions through electromagnetic shielding and structural rigidity.
- Glass:Borosilicate and soda-lime compositions deliver absolute chemical inertness for biologic drugs. Swissmedic and EMA Annex 1 sterile guidelines sustain premium positioning in European parenteral packaging despite weight and breakage penalties.
- Plastic:Polyethylene terephthalate and polypropylene dominate through injection-blow molding compatibility and coextrusion scalability. Plasma-enhanced chemical vapor deposition barrier coatings now enable 24-month shelf life claims previously reserved for glass.
- Metal:Aluminum dual chamber systems serve industrial adhesive applications requiring electromagnetic compatibility and crush resistance. Demand concentrates in German automotive assembly lines.
- Composite:Multi-material laminates combine polymer flexibility with metal foil barrier layers. REACH substance restrictions constrain adhesive selection for European food contact applications.
Plastic retains volume leadership; glass holds the steepest expansion curve in barrier-coated variants.
Capacity:
Volume scale determines automation economics and sterilization batch efficiency across pharmaceutical contract packaging networks.
- 50ml:Single-dose ophthalmic and emergency injectable formats require precision metering pumps. CDSCO sterile unit approvals in India drive demand for pre-sterilized 50ml systems with integrated needle safety.
- 100ml:Standard parenteral vial replacement size for hospital infusion. German hospital networks specify lot-level traceability as standard procurement terms.
- 200ml:Intermediate scale serving diagnostic reagent kits and cosmetic serum duos. French premium skincare brands deploy 200ml formats for vitamin C-retinol activation systems.
- 500ml:Industrial two-part adhesive and sealant containers. Screw cap reseal integrity outweighs dispensing sophistication in German automotive supplier specifications.
100ml commands the highest unit value; 50ml is climbing the fastest on single-dose pharmaceutical demand.
End User:
Regulatory intensity and shelf life requirements create divergent margin profiles across customer categories.
- Cosmetics:Premium skincare actives stabilization drives flip top and pump closure adoption. German and French brands lead point-of-use activation format deployment.
- Pharmaceuticals:EMA Annex 1 and FDA 16 CFR 1700 child-resistance standards enforce validated barrier separation. Cleanroom certification timelines extend facility commissioning by 8-14 months.
- Food & Beverages:Oxygen-sensitive ingredient isolation in beverage concentrates and oil-vinegar duos. EFSA migration limits constrain multi-layer plastic material selection.
- Industrial:Dual-cure adhesive resin-hardener separation with precision mix ratios. Automotive and electronics assembly in Germany and Switzerland specify dropper or pump dispensing accuracy.
Pharmaceuticals retains value leadership; cosmetics is gaining share fastest on premium format adoption.
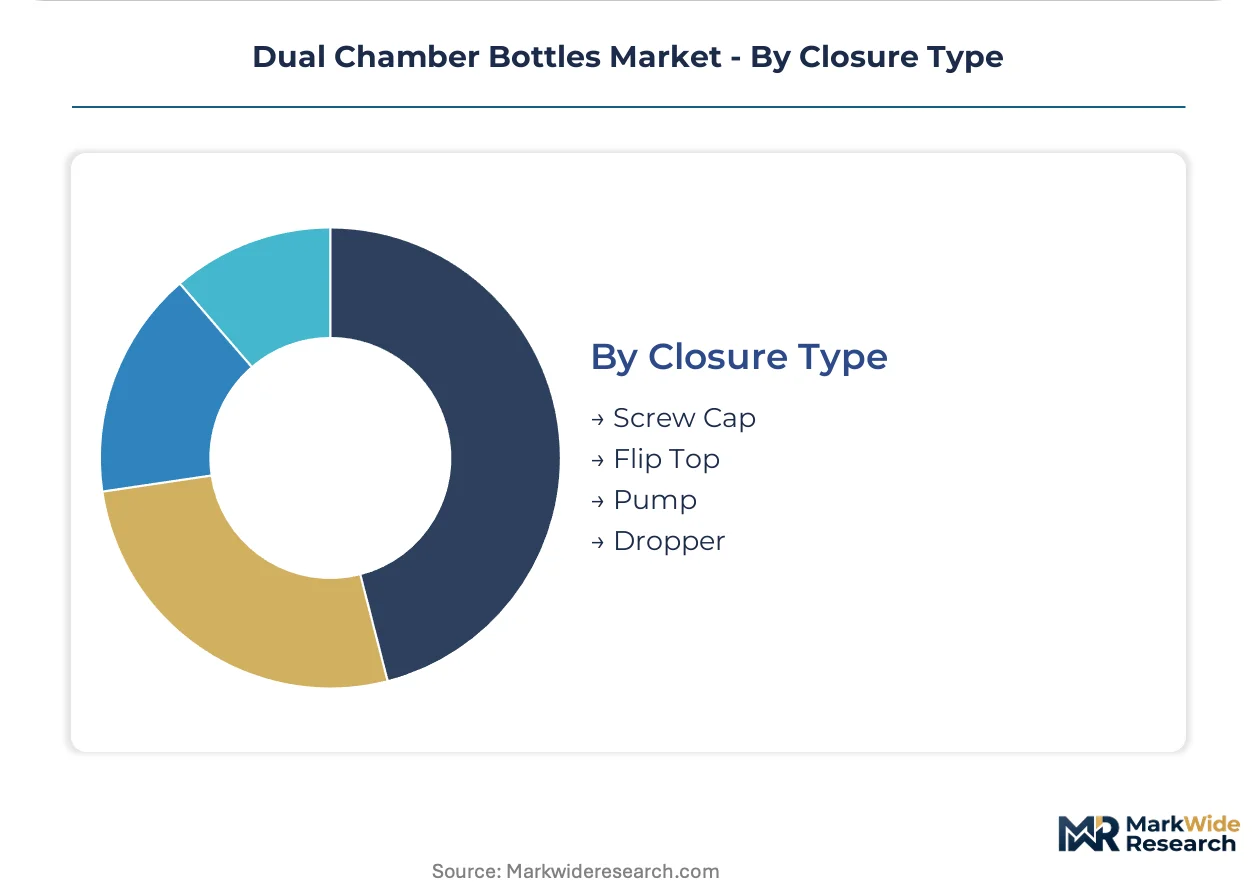
Closure Type:
Dispensing mechanism selection trades consumer convenience against reseal integrity and child-resistance compliance.
- Screw Cap:Reseal reliability for industrial and food applications. German chemical packaging specifications prioritize torque consistency over dispensing speed.
- Flip Top:Single-handed operation for cosmetic and pharmaceutical compliance. FDA child-resistance testing protocols add 3-6 months to qualification timelines.
- Pump:Metered dosing precision for high-value pharmaceuticals and serums. Swiss parenteral packagers specify pump actuation force tolerances within 5% variance.
- Dropper:Micro-volume accuracy for ophthalmic and diagnostic applications. Integrated bulb materials face REACH Annex XIV phthalate authorization requirements.
Screw cap sustains volume leadership in industrial segments; pump is expanding most quickly in pharmaceutical and cosmetic premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in dual chamber bottles track pharmaceutical packaging demand and cosmetics manufacturing concentration. Germany and Switzerland run structural surpluses in high-barrier pharmaceutical formats, while the United States and China absorb volumes through contract manufacturing networks and domestic brand expansion.
United States
FDA serialization mandates and 16 CFR 1700 child-resistance standards drive specification complexity for pharmaceutical dual chamber systems. Hospital procurement platforms now require lot-level traceability as standard contract terms. New Jersey and Pennsylvania host the densest converter clusters serving generic drug manufacturers.
Germany
EMA Annex 1 sterile guidelines and REACH chemical registration constraints elevate barrier validation requirements for parenteral packaging. Gerresheimer AG anchors production in Baden-Württemberg with cleanroom-certified glass lines. Bavarian automotive suppliers specify precision dual-cure adhesive containers for assembly line integration.
Switzerland
Swissmedic pharmaceutical regulations sustain premium positioning for borosilicate glass dual chamber formats in biologic delivery. Basel and Zürich concentrate sterile packaging innovation for parenteral drugs. Silicon oxide barrier coating qualification programs are compressing the plastic-glass performance gap.
India
CDSCO export-oriented unit approvals for sterile injectables create demand for pre-sterilized dual chamber systems with integrated closures. Maharashtra and Gujarat host contract manufacturing clusters serving European and North American pharmaceutical markets. Domestic skincare brands in Mumbai and Delhi deploy point-of-use activation formats.
China
NMPA pharmaceutical packaging standards and dual carbon goals constrain material selection for plastic dual chamber variants. Yangtze River Delta converters supply multi-layer coextrusion systems for cosmetic and industrial applications. Zhejiang and Jiangsu provinces concentrate blow-molding capacity for personal care brands.
Dual Chamber Bottles Market Competitive Landscape
Concentration sits with diversified packaging conglomerates and specialized pharmaceutical converters. The vendor base spans three tiers: global plastics specialists with thermoforming scale, glass converters with cleanroom certification, and regional fabricators serving cosmetic and industrial niches. Strategic moves center on barrier coating technology licensing and backward integration into precision mold fabrication.
Among diversified packaging specialists, Berry Global Inc. and Silgan Holdings Inc. exemplify scale-driven archetypes with multi-material capabilities. Gerresheimer AG occupies the pharmaceutical glass tier with borosilicate expertise and sterile production lines. TekniPlex Healthcare represents the healthcare-focused coextrusion specialist segment.
| Leading Market Players |
|---|
| Berry Global Inc. |
| TekniPlex Healthcare |
| AptarGroup, Inc. |
| Gidea Packaging |
| Cospack America |
| Silgan Holdings Inc. |
| TricorBraun |
| Raepak |
| Gerresheimer AG |
| Others |
Supply & Pricing Matrix
EMA Annex 1 sterile manufacturing guidelines gate both supplier qualification timelines and price tier separation, compressing development cycles for pharmaceutical-grade dual chamber systems while elevating barrier-coated polyethylene terephthalate premiums against commodity plastic alternatives. Certification backlog creates scarcity pricing for cleanroom-validated production slots, particularly in German and Swiss converter networks serving parenteral drug packagers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scale discounts, while pharmaceutical procurement runs through premium-mid-economy pricing differentiation keyed to barrier performance certification and child-resistance validation. Price differentiation rests on ISO 14644 cleanroom tier and EMA Annex 1 compliance status, with Swiss and German converters commanding 15-30 percent premiums over non-certified Asian suppliers. Cost compression in standard plastic tiers is intensifying because ethylene vinyl alcohol resin feedstock volatility squeezes multi-layer coextrusion margins. Generic drug manufacturers exhibit highest price sensitivity due to direct-to-clinic procurement platform margin pressure, whereas biologic drug packagers prioritize barrier reliability over unit cost.
Supply Chain Analysis
Tool steel inventory cycles extending 8-14 months strain precision mold fabrication timelines for dual chamber geometries, particularly for Swedish and Japanese grades subject to export licensing. Geographic supply concentration centers on Germany, Switzerland, and China, with Baden-Württemberg and Zürich anchoring pharmaceutical glass output while Zhejiang and Jiangsu provinces dominate blow-molding capacity for personal care applications. Raw material dependencies draw from borosilicate glass feedstock, polypropylene resin, and ethylene vinyl alcohol barrier coatings. Single-source vulnerability in specialized tool steel grades exposes converters to qualification delays. Distribution runs through pharmaceutical contract packaging networks and direct-to-clinic procurement platforms that compress traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual chamber packaging is approaching a platform-economics inflection as barrier coating standardization and serialization interoperability reshape competitive moats from proprietary mold geometries to validated cleanroom network effects.
For Market Incumbents: Consolidate backward integration into precision toolmaking and silicon oxide barrier coating equipment to defend margin position against emerging Asian converters with coextrusion scale. Lock in multi-year offtake agreements with German and Swiss pharmaceutical packagers before EMA Annex 1 validation timelines extend further. Priority lever: captive supply of Swedish tool steel grades through inventory pre-positioning. For New Entrants and Emerging Players: FDA 510(k) fast-track and CDSCO sterile unit approval pathways open white-space penetration in Indian pharmaceutical contract manufacturing and US generic drug packaging. Target 50ml single-dose ophthalmic formats where barrier coating technology gaps persist. Go-to-market angle: pre-sterilized integrated closure systems with lot-level traceability bundled as standard. For Investors and Strategic Acquirers: EU Green Deal extended producer responsibility milestones reshape the acquisition landscape toward mono-material dual chamber designs compatible with polyethylene recycling streams. Five-to-ten year viability favors converters with in-house regulatory affairs capabilities and cleanroom-certified assets in European pharmaceutical clusters. Acquisition target archetype: mid-cap healthcare coextrusion specialists with EMA validation history. Signal to watch: REACH Annex XIV authorization rulings on phthalate alternatives in polypropylene stabilizers.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Technology Licensing | Silicon oxide PECVD qualification programs compress plastic-glass performance gaps for 24-month shelf life claims. |
| Precision Mold Fabrication Backward Integration | Swedish tool steel captive supply defends against 8-14 month qualification delays in pharmaceutical converter networks. |
| Cleanroom Certification Pre-Positioning | ISO 14644 Class 7 validation ahead of EMA Annex 1 enforcement captures scarce pharmaceutical packaging slots. |
| Mono-Material Design Transition | Polyethylene-only dual chamber formats align with EU Green Deal recycling stream compatibility requirements. |
| Direct-to-Clinic Distribution Partnership | Lot-level traceability and temperature excursion documentation meet US hospital network procurement platform standards. |
Research Methodology
The analysis maps pharmaceutical parenteral packaging, premium skincare activation systems, industrial adhesive separation, and food-grade oxygen-sensitive formats, each validated through regulatory affairs directors at dual chamber converters, procurement managers at German hospital networks, and category buyers at French cosmetics brands. Primary interviews with cleanroom operations heads and barrier coating R&D leads combined with secondary validation from EMA submission databases, FDA 16 CFR 1700 guidance documents, and REACH Annex XIV authorization listings. Bottom-up capacity modeling and top-down pharmaceutical packaging spend estimates triangulate volume and value outputs.
Consistency checks against external benchmarks validated projections across the analysis window, with segmentation dimensions spanning material-process pairings, capacity tiers, end-use regulatory intensity, and closure integration complexity. CAGRs derive from installed capacity growth rates, pharmaceutical serialization mandate timelines, and cosmetics premium format adoption curves. Industry-specific forecast inputs include ethylene vinyl alcohol resin price trajectories and cleanroom facility commissioning timelines.
Underlying assumptions cover EMA Annex 1 enforcement continuity, REACH substance restriction evolution, and pharmaceutical serialization mandate adherence, with deviation risk concentrated in tool steel export licensing delays and barrier coating technology qualification setbacks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
US Beverage Packaging Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
Graduated Sample Bottle Market
Beverage Packaging
Fruit Juice Packaging Market
Beverage Packaging
Heavy Wall Bottles Market
Beverage Packaging
North America Beverage Packaging Market
Beverage Packaging
Bottle Shippers Market
Beverage Packaging
Self-Chilling Can Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Cold Beverage Cups Market
Beverage Packaging
Pop-Up Pourer Market
Beverage Packaging
French Square Bottle Market
Beverage Packaging
Pouring Spout Market