
 Graduated Sample Bottle Market | 2026-2036
Graduated Sample Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Graduated Sample Bottle Market Foresight
Asset-light leasing and rental models for laboratory consumables is fragmenting competitive dynamics across the graduated sample bottle landscape. Thermo Fisher Scientific leverages its channel density to bundle bottle procurement with instrument service contracts. Gerresheimer AG anchors European supply through captive borosilicate glass melting operations. Cole-Parmer Instrument Co. competes via specialized private-label configurations for academic buyers.
A graduated sample bottle is a volumetrically calibrated container, typically manufactured from borosilicate glass or polypropylene, featuring etched or printed scale markings with tolerances conforming to ISO 4787 or ASTM E438 standards for precise liquid measurement and storage. The device serves pharmaceutical stability testing, environmental sample collection, and clinical diagnostic workflows where quantitative volume verification is mandatory. Plastic variants lead unit volumes due to disposability and breakage resistance in high-throughput laboratories, while borosilicate glass commands margin pools in pharmaceutical applications requiring thermal shock resistance and inert surfaces. Capacity segmentation shows 100ml configurations dominating standard protocol adoption, with 10ml formats expanding fastest in pediatric and micro-sampling workflows.
FDA stability-testing guidelines and EMA good manufacturing practice frameworks enforce volumetric traceability for pharmaceutical submissions, directly shaping product calibration requirements and documentation standards. ISO 4787 and ASTM E438 govern dimensional tolerances and marking permanence, creating compliance barriers for uncertified suppliers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP chapters to anticipate specification convergence or divergence in multi-jurisdictional trials.
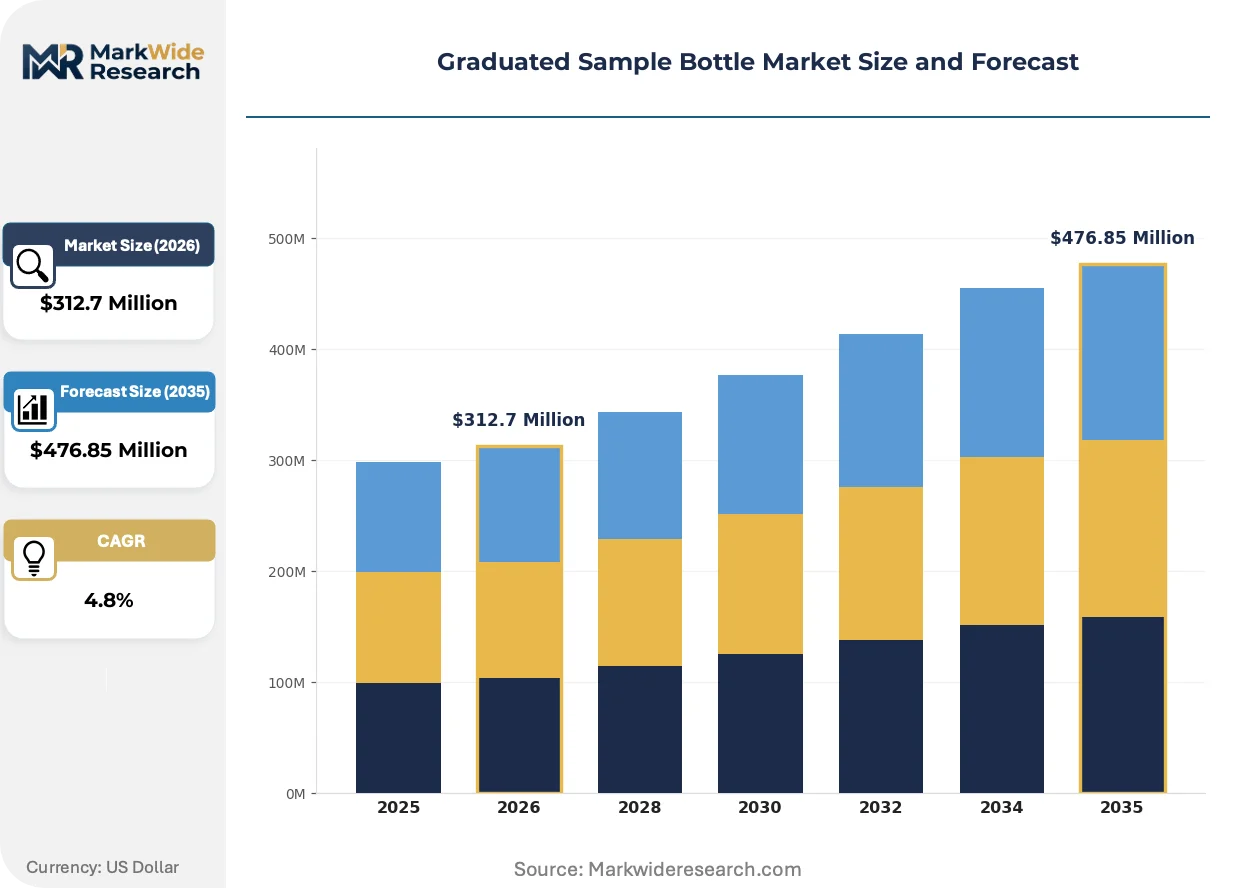
Market Dynamics
Pharmaceutical quality control laboratories are expanding procurement of calibrated sampling vessels as FDA and EMA stability-testing guidelines mandate volumetric traceability for regulatory submissions, compressing demand toward certified suppliers with documented ISO 4787 compliance.
Growth Catalysts
- EMA GMP Frameworks:European manufacturing practice guidelines enforce volumetric traceability for pharmaceutical submissions, compelling contract research organizations to source calibrated borosilicate vessels with permanent etched markings.
- Pediatric Micro-Sampling:Clinical diagnostic workflows for neonatal and pediatric applications are driving 10ml format adoption where precise small-volume measurement reduces sample waste.
- German Glass Manufacturing Clusters:Precision borosilicate melting operations in the Rhine-Main region supply European contract research organizations with thermal shock-resistant containers for stability testing protocols.
Market Restraints
- Raw Material Concentration:High-purity borosilicate glass feedstock production concentrates among limited European and North American specialty chemical suppliers, exposing margins to energy cost volatility.
- Calibration Infrastructure:Volumetric certification requires accredited metrology laboratories with liquid displacement measurement systems, creating geographic supply constraints outside established pharmaceutical hubs.
- Plastic Substitution in High-Throughput Settings:Polypropylene variants displace glass in environmental monitoring and routine quality control where breakage risk and disposability outweigh thermal performance requirements.
Strategic Opportunities
- Asset-Light Leasing Models:Laboratory consumable rental programs bundle bottle procurement with instrument service contracts, capturing recurring revenue from mid-sized contract research organizations.
- Pharmacopeial Harmonization:Convergence between USP, EP, and JP chapters on volumetric tolerances creates certification efficiencies for suppliers serving multi-jurisdictional clinical trials.
- Private-Label Academic Configurations:Specialized scale marking formats and reduced certification documentation address price-sensitive university research buyers outside regulated pharmaceutical workflows.
Industry Challenges
- Metrology Talent Scarcity:Accredited liquid volume calibration requires technicians trained in ISO/IEC 17025 procedures, with limited pipeline expansion in secondary education systems.
- Legacy Inventory Integration:Pharmaceutical laboratories maintain decades of stability study data tied to specific vessel lot numbers, complicating supplier switching without protocol amendment submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graduated Sample Bottle Market |
| Market Size in 2026 | $312.7 Million |
| Market Size in 2035 | $476.85 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Metal, Disposable Capacity: 10ml, 50ml, 100ml, 250ml End User: Laboratories, Hospitals, Educational Institutions, Research Facilities Material: Polypropylene, Borosilicate Glass, Stainless Steel, PET |
| Companies Covered | Gerresheimer AG, Cole-Parmer Instrument Co., Thermo Fisher Scientific Inc., Berlin Packaging, VWR, DWK Life Sciences, Merck KGaA, Qorpak, Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graduated Sample Bottle Market Shifts & Advancements
Graduated sample bottle specifications are tightening around permanent marking technologies and material traceability as regulatory documentation requirements extend backward through supply chains.
Laser-etched volumetric scales are migrating from printed ceramic ink markings in pharmaceutical applications. FDA submission reviewers now flag fading or solvent-degraded markings as protocol deviations. Major contract research organizations in the United States and Germany have adopted laser-etched borosilicate vessels as default specifications, compressing demand for traditional screen-printed alternatives and raising capital requirements for supplier equipment upgrades.
REACH Annex XVII restrictions on heavy metals in printing inks are forcing reformulation of scale pigments across European manufacturing. ECHA compliance deadlines have accelerated supplier transitions to cerium-doped glass substrates with intrinsic UV fluorescence for marking visibility. German and Swiss pharmaceutical packaging suppliers are absorbing certification costs fastest, while Southern European converters face extended qualification timelines with contract research organization customers.
Academic procurement offices are consolidating vendor lists through e-procurement platforms that automate compliance documentation upload. University laboratory managers in North America and Western Europe now filter supplier catalogs by pre-loaded ISO 4787 certificate availability, bypassing traditional distributor sales engagement. This channel compression favors direct manufacturer relationships and private-label specialists with digital certificate infrastructure over legacy distribution intermediaries.
Graduated Sample Bottle Market Segmentation
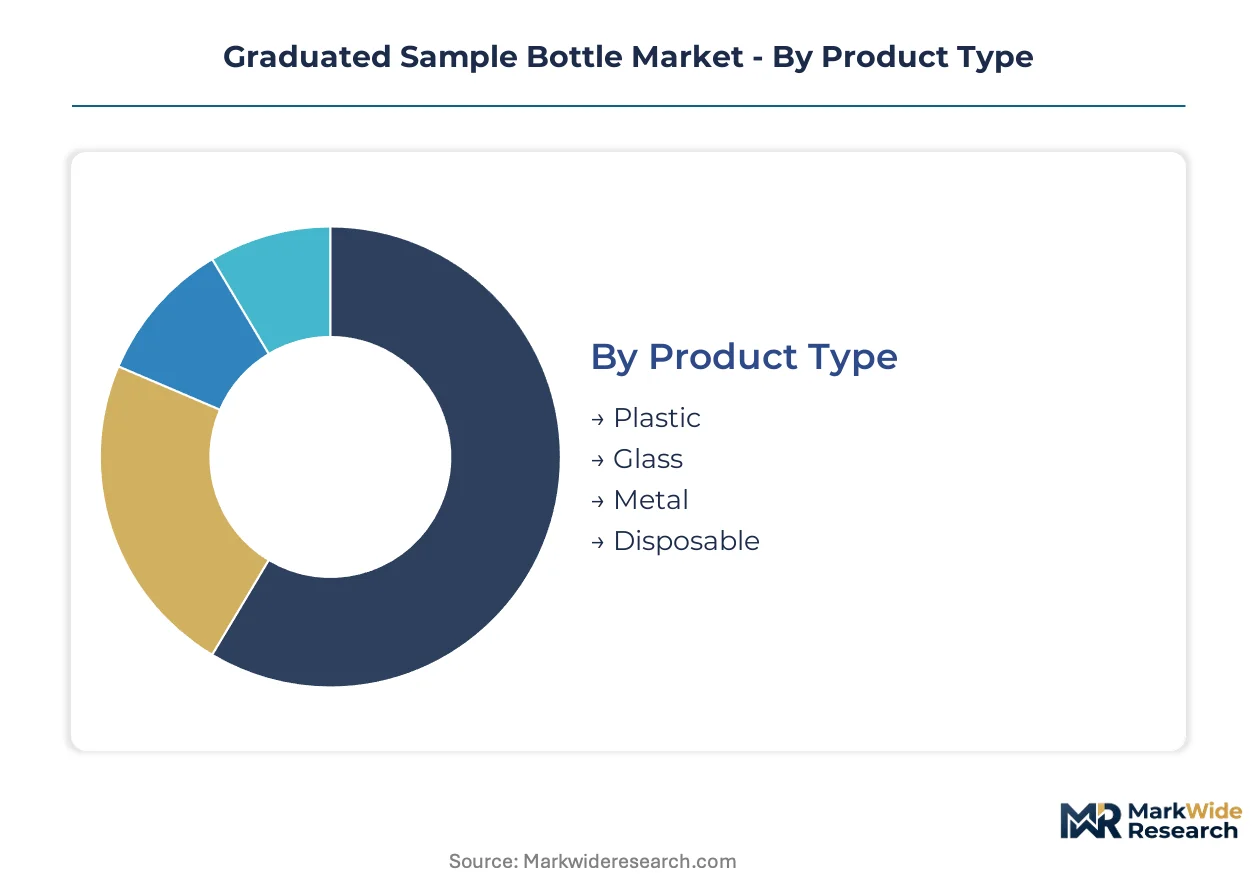
Segmentation in graduated sample bottles reveals divergent procurement cycles across material grades and use environments. Pharmaceutical stability testing demands multi-year vessel qualification timelines, while environmental field sampling operates on quarterly replenishment schedules. Understanding these cycle-time differentials enables suppliers to align inventory positioning with customer replenishment patterns.
Product Type:
Plastic variants turn inventory fastest through single-use protocols in high-throughput screening, while glass vessels persist through multi-year stability study commitments.
- Plastic:Polypropylene and copolymer formulations dominate environmental monitoring and routine quality control where disposability eliminates cross-contamination risk. German contract research organizations procure polypropylene bottles on quarterly cycles for high-volume dissolution testing workflows.
- Glass:Borosilicate constructions with thermal shock resistance anchor pharmaceutical stability protocols requiring thermal cycling from freezer storage to analytical thaw. FDA submission reviewers mandate permanent volumetric markings for long-term studies, extending replacement cycles to five-plus years.
- Metal:Stainless steel variants serve hydrocarbon sampling and solvent extraction applications where glass breakage risk and plastic solvent incompatibility converge.
- Disposable:Pre-sterilized single-use configurations eliminate autoclave validation overhead in academic and clinical diagnostic settings with limited infrastructure.
Glass anchors the volume base while plastic gains share at the steepest rate.
Capacity:
Cost tier stratification separates premium small-format precision from economy-scale bulk configurations.
- 100ml:Standard protocol workhorse across pharmaceutical dissolution and environmental grab sampling. ISO 4787 Class A tolerances command 40-60% price premiums over Class B equivalents in regulated submissions.
- 10ml:Pediatric micro-sampling and neonatal diagnostic applications drive precision demand where sample volume constraints mandate sub-milliliter measurement accuracy. Clinical laboratories in the United States and Germany have adopted 10ml as default for pediatric pharmacokinetic studies.
- 50ml:Intermediate format bridging routine quality control and specialized stability testing with balanced unit economics.
- 250ml:Bulk environmental composite sampling and industrial process control where precision tolerance relaxes proportionally with volume scale.
100ml configurations dominate procurement spend while 10ml formats climb the fastest.
End User:
Application severity separates life-science regulated workflows from education procurement with documentation tolerance.
- Laboratories:Pharmaceutical quality control and contract research organizations drive calibrated vessel demand with ISO 4787 certificate requirements. EMA GMP frameworks mandate volumetric traceability, compressing vendor qualification to documented metrology suppliers.
- Hospitals:Clinical diagnostic laboratories balance precision requirements against infection control protocols, favoring disposable configurations with pre-validated sterility.
- Educational Institutions:University teaching laboratories prioritize cost efficiency over certification depth, accepting Class B tolerances and screen-printed markings for undergraduate instruction.
- Research Facilities:Government and independent research institutes occupy intermediate territory with project-specific calibration demands.
Laboratories anchor the volume base while hospitals gain share at the steepest rate.
Material:
Supply concentration in German and Swiss borosilicate melting operations shapes geographic procurement patterns.
- Polypropylene:Injection-molded disposables serve high-throughput screening with gamma-sterilization compatibility. Asian polymer converters supply cost-optimized variants for environmental monitoring outside regulated pharmaceutical workflows.
- Borosilicate Glass:Thermal expansion coefficient below 3.3 × 10⁻⁶/K enables autoclave cycling and cryogenic storage. Gerresheimer AG and DWK Life Sciences anchor European supply through captive melting operations in the Rhine-Main region.
- Stainless Steel:316L grade vessels resist organic solvent attack in hydrocarbon analysis and accelerated extraction protocols.
- PET:Lightweight clarity for visual inspection applications with lower thermal performance than borosilicate alternatives.
Borosilicate glass anchors the volume base while polypropylene gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in graduated sample bottles track pharmaceutical manufacturing density and laboratory infrastructure investment. Germany and the United States maintain trade surpluses in calibrated borosilicate vessels, while Asian markets absorb polymer variants for environmental monitoring applications.
United States
FDA stability-testing guidelines drive calibrated vessel procurement from contract research organizations clustered in Massachusetts and North Carolina. The agency's submission reviewers mandate volumetric traceability documentation, compressing vendor qualification toward ISO 4787-certified suppliers. Boston-Cambridge pharmaceutical hubs anchor demand for laser-etched borosilicate configurations in long-term stability protocols.
Germany
EMA GMP frameworks enforce permanent marking standards for pharmaceutical submissions, compelling Rhine-Main region laboratories to source thermal shock-resistant containers. Gerresheimer AG and DWK Life Sciences operate captive borosilicate melting facilities near Frankfurt, supplying European contract research organizations with certified vessels. REACH Annex XVII compliance deadlines accelerate transitions to cerium-doped glass substrates.
China
NMPA pharmacopoeial harmonization initiatives reshape import requirements for volumetric calibration documentation. Shanghai and Suzhou pharmaceutical manufacturing zones drive demand for pre-sterilized disposable configurations in high-throughput screening workflows. Domestic polymer converters supply cost-optimized polypropylene variants for environmental monitoring outside regulated drug development.
Japan
PMDA quality guidelines for stability testing mandate documented volumetric traceability, favoring precision glass imports from German and Swiss suppliers. Tokyo-Osaka pharmaceutical corridors concentrate demand for 10ml micro-sampling formats in pediatric pharmacokinetic studies. METI industrial standards programs support domestic metrology laboratory accreditation for liquid displacement calibration.
India
CDSCO regulatory convergence with ICH guidelines elevates calibration requirements for contract research organizations in Hyderabad and Bangalore. CDSCO's stability testing directives now reference volumetric tolerances, shifting procurement toward certified suppliers. Maharashtra and Gujarat pharmaceutical clusters import borosilicate vessels while domestic injection molders serve environmental and academic segments with polypropylene alternatives.
Graduated Sample Bottle Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material and calibration niches. Thermo Fisher Scientific leverages instrument service contract density to bundle consumable procurement, while glass manufacturers defend position through captive melting operations. Three archetypes dominate: diversified life-science platforms, precision glass specialists with vertical integration into borosilicate feedstock, and private-label distributors serving price-sensitive academic segments. Competitive moves center on asset-light leasing program expansion and digital certificate infrastructure deployment.
Within the precision glass tier, Gerresheimer AG and DWK Life Sciences occupy positions anchored by Rhine-Main manufacturing clusters. Thermo Fisher Scientific exemplifies the platform integrator archetype, bundling vessel procurement with analytical instrument service contracts. Cole-Parmer Instrument Co. sits within the specialized distributor category, addressing academic buyers through configurable private-label formats.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Cole-Parmer Instrument Co. |
| Thermo Fisher Scientific Inc. |
| Berlin Packaging |
| VWR |
| DWK Life Sciences |
| Merck KGaA |
| Qorpak |
| Corning Incorporated |
| Others |
Supply & Pricing Matrix
Rhine-Main precision glass melting clusters anchor global supply capacity for borosilicate graduated vessels, translating captive feedstock control into pricing power over pharmaceutical contract research organizations facing FDA and EMA volumetric traceability mandates. German and Swiss manufacturers leverage ISO 4787 certification scarcity to sustain margin premiums against Asian polymer converters serving price-sensitive environmental monitoring segments.
Pricing Analysis
Pharmaceutical quality control laboratories anchor tiered pricing stratification across premium certified, standard documented, and economy unmarked tiers. Price differentiation hinges on ISO 4787 Class A versus Class B tolerance grades and laser-etched versus screen-printed marking permanence. Cost compression in economy polypropylene segments intensifies as Asian injection molders expand capacity for high-throughput screening workflows. Academic procurement offices exhibit highest price sensitivity, while FDA submission-bound pharmaceutical sponsors accept substantial premiums for documented metrology traceability.
Supply Chain Analysis
Export control restrictions on high-purity borosilicate glass melting technology limit capacity expansion outside established European and North American manufacturing bases. Supply concentrates in Germany, Switzerland, and the United States for precision glass, while China, South Korea, and India feed polymer variant demand. Raw material dependencies encompass high-purity silica sand, cerium oxide for UV-fluorescent substrates, and pharmaceutical-grade polypropylene resin. Single-source vulnerability concentrates in Rhine-Main borosilicate feedstock production. Distribution runs through direct manufacturer relationships with large contract research organizations and specialized laboratory distributors serving fragmented academic accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities multiply across this market as asset-light leasing models and digital certificate infrastructure reshape procurement patterns, creating niches for specialized private-label configurators alongside integrated platform providers.
For Market Incumbents: Build certification moats through accelerated ISO/IEC 17025 metrology laboratory accreditation in underserved pharmaceutical manufacturing zones. Expand backward integration into cerium-doped glass substrate production to capture REACH Annex XVII compliance premiums. Defend against plastic substitution threats by embedding thermal shock resistance specifications into FDA stability study protocols. Prioritize channel control through instrument service contract bundling that locks in multi-year vessel replenishment schedules. For New Entrants and Emerging Players: Pursue private-label white space in North American and Western European academic procurement channels where e-procurement platform consolidation favors digital-native certificate infrastructure. Target pediatric micro-sampling segments with specialized 10ml format configurations as clinical laboratories expand neonatal pharmacokinetic workflows. Enter through configurable scale marking formats with reduced documentation overhead priced below pharmaceutical certification tiers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because volumetric traceability mandates embed incumbent supplier relationships across multi-year stability study commitments. Acquisition candidates include precision glass specialists with captive borosilicate melting operations and digital certificate infrastructure providers serving e-procurement platforms. Monitor pharmacopeial harmonization progress between USP, EP, and JP chapters as signal for certification efficiency consolidation or persistent fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Metrology Laboratory Accreditation | ISO/IEC 17025 certification in emerging pharmaceutical hubs captures regulatory compliance premiums. |
| Laser Etching Equipment Deployment | FDA submission reviewers now flag fading markings as protocol deviations, mandating permanent technologies. |
| Asset-Light Leasing Program Expansion | Instrument service contract bundling locks mid-sized contract research organizations into recurring revenue streams. |
| Digital Certificate Infrastructure | E-procurement platform integration automates compliance documentation upload for university laboratory managers. |
| Cerium-Doped Substrate Transition | REACH Annex XVII heavy metal restrictions force reformulation toward intrinsic UV-fluorescent glass alternatives. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical quality control directors, contract research organization procurement managers, metrology laboratory accreditation officers, and academic laboratory supply coordinators, then refined through secondary validation against FDA stability testing guidance documents, EMA GMP framework publications, ISO 4787 calibration standards, and REACH Annex XVII regulatory filings. Bottom-up demand modeling across end-user segments triangulated with top-down supply capacity assessments from borosilicate glass melting operations and polymer injection molding facilities.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation modeling spanning material grade, capacity format, calibration certification tier, and end-use application severity. CAGRs derived from weighted average growth contributions across pharmaceutical stability testing expansion, environmental monitoring protocol standardization, and pediatric micro-sampling adoption curves. Industry-specific inputs encompassed EMA GMP enforcement timelines, FDA submission reviewer marking permanence preferences, and REACH compliance deadline acceleration effects.
Sensitivities concentrate around pharmacopeial harmonization convergence or divergence, raw material energy cost volatility, and metrology technician pipeline expansion rates. Forecasts reflect documented assumptions on regulatory enforcement intensity and substitution elasticity between glass and polymer formats. Material shifts in FDA marking permanence standards or ECHA substrate composition restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
PET Bottle Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
US Beverage Packaging Market
Beverage Packaging
Beverage Packaging Machine Market
Beverage Packaging
Cup Filler Market
Beverage Packaging
Media Bottles Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Beverage Cans Market
Beverage Packaging
Heavy Wall Bottles Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
Twin Neck Bottles Market
Beverage Packaging
Bamboo Cups Market
Beverage Packaging
Square Media Bottle Market
Beverage Packaging
Middle East and Africa Soft Drinks Packaging Market
Beverage Packaging
Foldable Bottles Market