
 Pouring Spout Market | 2026-2036
Pouring Spout Market Size, Share, and Industry Trends Forecast 2026-2036
Pouring Spout Market Analytics
Food-grade specification upgrades across beverage and edible oil packaging are unwinding legacy cost structures in pouring spout procurement. AptarGroup leverages polymer science capabilities to sustain premium positioning in adjustable dispensing formats. Silgan Dispensing Systems anchors North American supply through captive manufacturing scale. Guangdong Wintime Industrial Co. Ltd competes on export volume from Pearl River Delta production bases.
A pouring spout is a controlled-flow dispensing attachment, typically injection-molded from polypropylene or polyethylene with internal vent channels, that enables drip-free liquid transfer from rigid or flexible containers. Plastic spouts lead unit volume due to compatibility with standard bottle neck finishes and cost-efficient thermoforming, though silicone spouts capture expanding share in high-temperature culinary applications. Specialty spouts command margin premiums through patented flow-control mechanisms, while standard spouts remain the mature baseline for commodity chemical transfer.
FDA food-contact notifications and EU Regulation 10/2011 on plastic materials shape migration-limit testing protocols for spout manufacturers seeking cross-border market access. China's GB standards for food packaging, enforced by SAMR, add a third compliance layer for exporters targeting Asia-Pacific distribution. Stakeholders must monitor evolving extended producer responsibility frameworks in Europe and North America, as these will increasingly dictate material recyclability requirements and design-for-disassembly mandates across pouring spout specifications.
Market Dynamics
Food-contact compliance mandates from FDA and EU EFSA are compressing supplier qualification timelines while precision dispensing requirements from beverage bottlers are pulling capital toward vented channel engineering.
Growth Catalysts
- EU Regulation 10/2011 migration limits:Manufacturers achieving dual FDA-EFSA certification capture shelf-space commitments from multinational edible oil brands seeking unified packaging specifications.
- Hot-fill beverage processing:Silicone spout demand accelerates as ready-to-drink coffee and functional beverage lines adopt 185°F filling protocols incompatible with standard polypropylene.
- Pearl River Delta export manufacturing:Guangdong injection-molding clusters supply cost-optimized standard spouts to African and Southeast Asian packaging converters.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer price swings from Gulf Coast petrochemical complexes transmit directly to spout unit economics, squeezing mid-tier converters.
- Single-source vent-channel tooling:Precision mold fabrication for laminar-flow geometries concentrates among three German and Japanese equipment suppliers, creating 14-week lead time exposure.
- Mechanical recycling incompatibility:Multi-material spout assemblies with silicone gaskets and polypropylene bodies fail near-infrared sortation at municipal recovery facilities, triggering EPR fee escalations in France and Germany.
Strategic Opportunities
- India FSSAI food-grade acceleration:Domestic edible oil majors are localizing packaging procurement under import-substitution policies, opening demand for SAMR-certified Chinese exporters and BIS-compliant Indian molders.
- Connected dispensing integration:RFID-enabled spouts for pharmaceutical compliance tracking converge with IoT inventory management systems in hospital and long-term care channels.
- Refill station retail formats:Bulk liquid dispensing networks in Germany and the Netherlands require standardized 38mm spout interfaces, creating specification lock-in potential for first-mover designers.
Industry Challenges
- Migration testing laboratory capacity:FDA food-contact notification queues extend to 180 days, delaying commercialization timelines for novel polymer formulations.
- Legacy bottle neck retrofit compatibility:Pharmaceutical and chemical containers with non-standard 28-410 threads require custom adapter development, fragmenting engineering resources across low-volume SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pouring Spout Market |
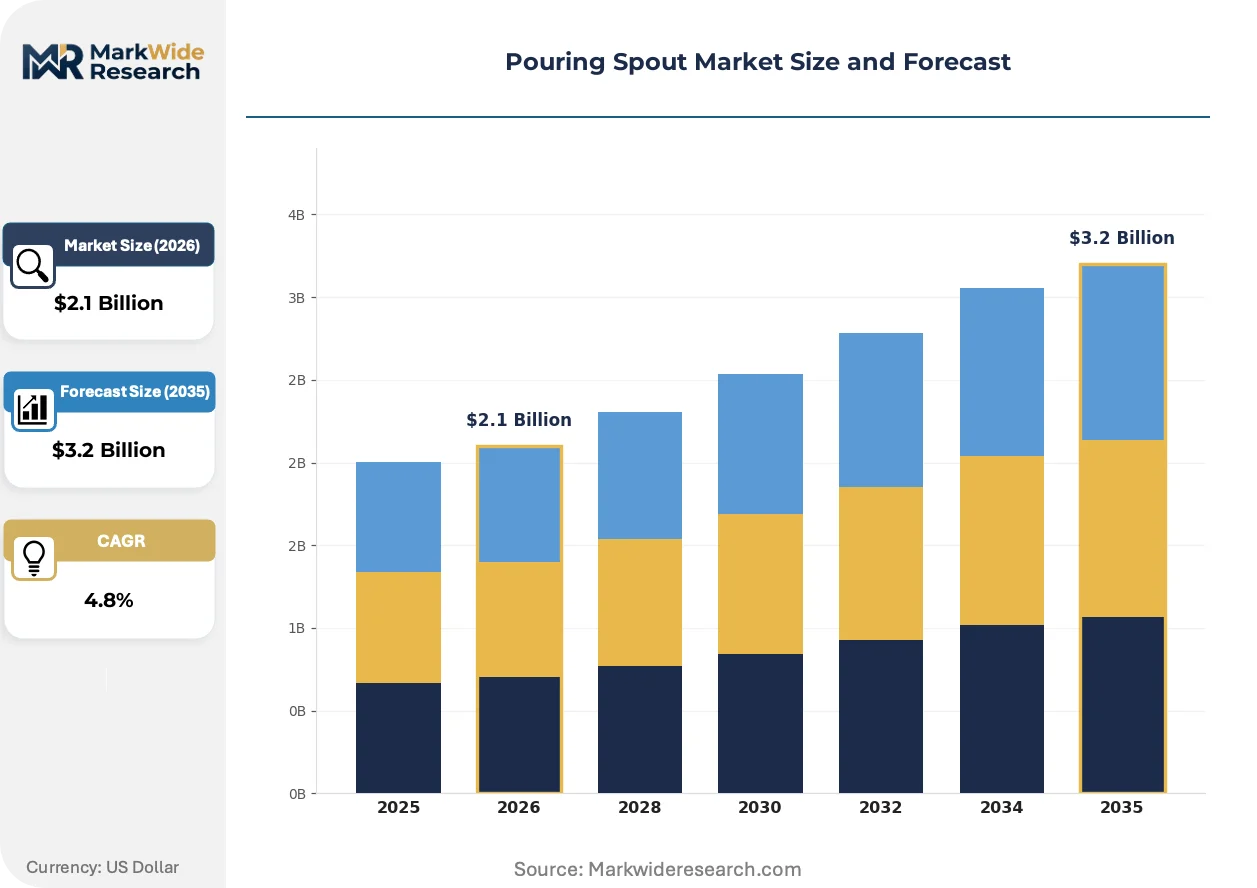
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Spouts, Metal Spouts, Silicone Spouts, Glass Spouts End User: Households, Restaurants, Food Processing, Chemical Industries Design Style: Standard Spouts, Adjustable Spouts, Spout Caps, Specialty Spouts Use Case: Beverage Dispensing, Oil Pouring, Chemical Transfer, Gardening |
| Companies Covered | Seal-Spout Corporation, Spill-Stop Mfg. LLC, AptarGroup, Silgan Dispensing Systems, Weener Plastics, Berry Global, Amcor plc, Guangdong Wintime Industrial Co. Ltd, Xiamen Xintonglian Plastic Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pouring Spout Market Evolving Landscape
Converging pressures from sustainability disclosure rules and precision dosing requirements are rewiring spout design priorities toward material traceability and flow-control engineering.
Micro-vent channel architecture is miniaturizing. Laser-drilled 0.3mm air-return passages replace molded vent tubes, enabling single-piece spout bodies that cut assembly steps. Premium olive oil and craft spirits bottlers in Italy and California are specifying these designs for drip-free pour control. The technology is miniaturizing internal component counts from seven parts to two, collapsing failure modes and warranty exposure.
Extended producer responsibility frameworks are hardening. France's AGEC law and Germany's Verpackungsgesetz amendments now mandate recycled content thresholds for household packaging components, including dispensing closures. Spout manufacturers serving Unilever and Nestlé export programs must validate post-consumer polypropylene feedstock chains through third-party mass-balance certification. European converters are responding by qualifying chemically recycled resins ahead of mechanical recycling infrastructure maturity.
Direct procurement from molders is consolidating buyer power. Large beverage and edible oil groups are bypassing traditional closure distributors to negotiate multi-year spout supply agreements with injection specialists. This disintermediation concentrates volume with producers holding captive polymer compounding and in-house mold-making capabilities. The shift is most visible in Germany, where private-label bottlers for Aldi and Lidl have consolidated supplier panels to three approved molders.
Pouring Spout Market Segmentation
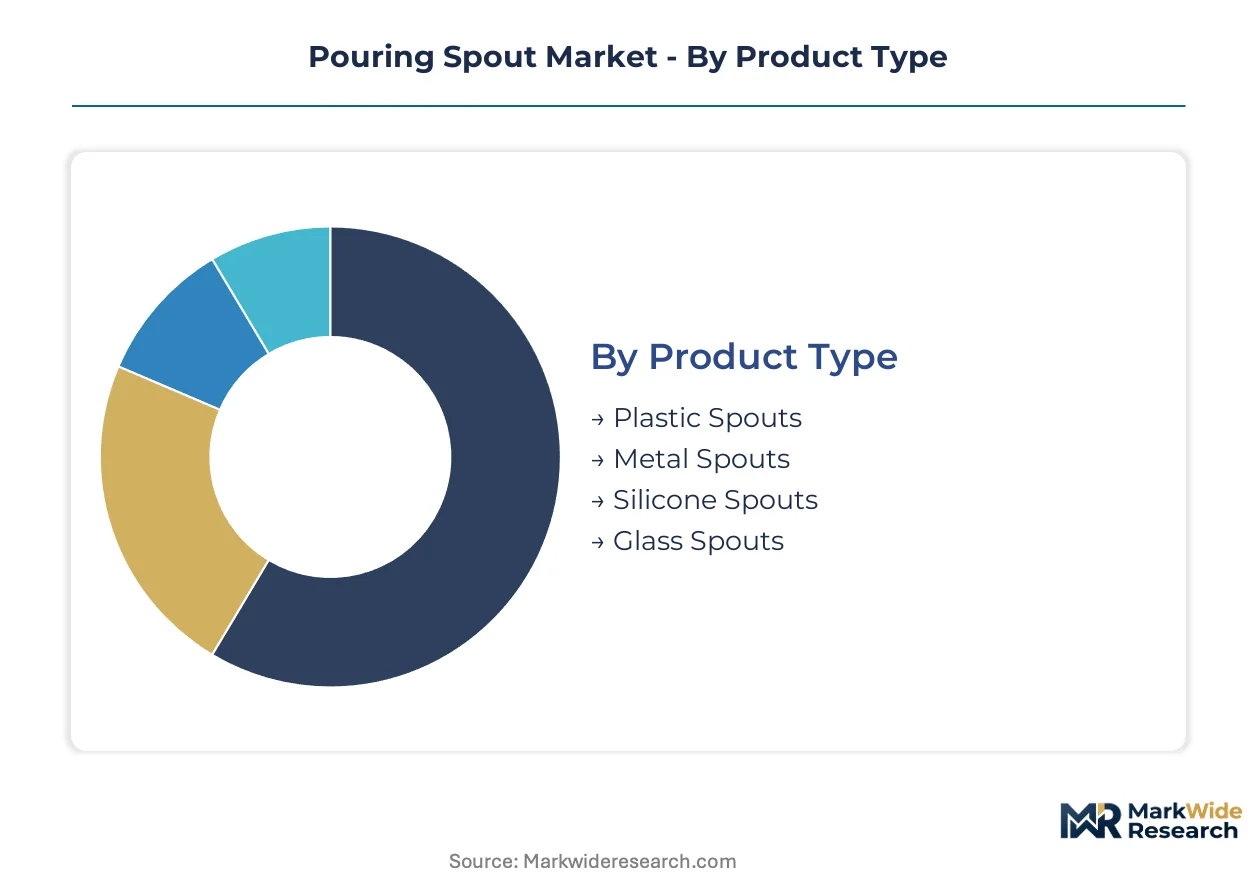
Margin concentration across pouring spout categories follows material performance hierarchies and regulatory certification burdens. Procurement patterns diverge sharply between commodity volume plays and specialty precision formats.
Product Type:
Polypropylene and polyethylene formats capture the widest margin pools through thermoforming efficiency and FDA food-contact scalability.
- Plastic Spouts:Injection-molded polypropylene bodies with internal vent channels dominate unit economics through compatibility with standard 28-410 and 38-400 bottle neck finishes. Demand concentrates in United States edible oil packaging and German beverage bottling lines where EFSA migration compliance is mandatory.
- Silicone Spouts:Platinum-cured elastomer construction withstands 185°F hot-fill protocols for ready-to-drink coffee and functional beverages. Japanese and Italian bottlers specify these for thermal stability beyond polypropylene limits, though unit costs run three to four times higher than thermoplastic alternatives.
- Metal Spouts:Stainless steel 304/316 variants serve high-viscosity industrial chemical transfer with mechanical durability.
- Glass Spouts:Borosilicate formats remain niche for premium spirits presentation and laboratory reagent dispensing.
The dominant share belongs to Plastic Spouts, while Silicone Spouts is closing the gap fastest.
End User:
Volume scale concentrates in institutional procurement channels with centralized specification authority.
- Food Processing:Automated bottling lines in edible oil and condiment manufacturing specify vented spouts for laminar flow control. German and Chinese packaging hubs drive standardization around 38mm interfaces.
- Households:Consumer retail formats through mass-market distributors emphasize cost-optimized polypropylene with snap-fit assembly.
- Restaurants:Commercial kitchen procurement favors dishwasher-safe silicone for high-temperature sauce dispensing.
- Chemical Industries:Laboratory and agricultural chemical transfer demands solvent-resistant fluoropolymer seals.
Food Processing commands the largest procurement volumes, with Restaurants expanding most quickly as commercial kitchen automation spreads.
Design Style:
Patent-protected flow mechanisms command premium positioning against commodity baseline formats.
- Specialty Spouts:Proprietary venturi geometries and drip-free lip designs secure shelf-space commitments from premium olive oil and craft spirits brands. Italian and California bottlers specify laser-drilled micro-vent channels that collapse internal part counts.
- Adjustable Spouts:Rotating collar mechanisms enable variable flow rates for multi-viscosity product lines. AptarGroup polymer science capabilities sustain premium positioning in this tier.
- Standard Spouts:Fixed-geometry polypropylene bodies serve commodity chemical and water transfer applications.
- Spout Caps:Integrated closure-dispenser hybrids reduce packaging component counts for sustainability-focused brands.
Standard Spouts retains volume leadership, though Specialty Spouts gains share fastest through premiumization in edible oil and spirits packaging.
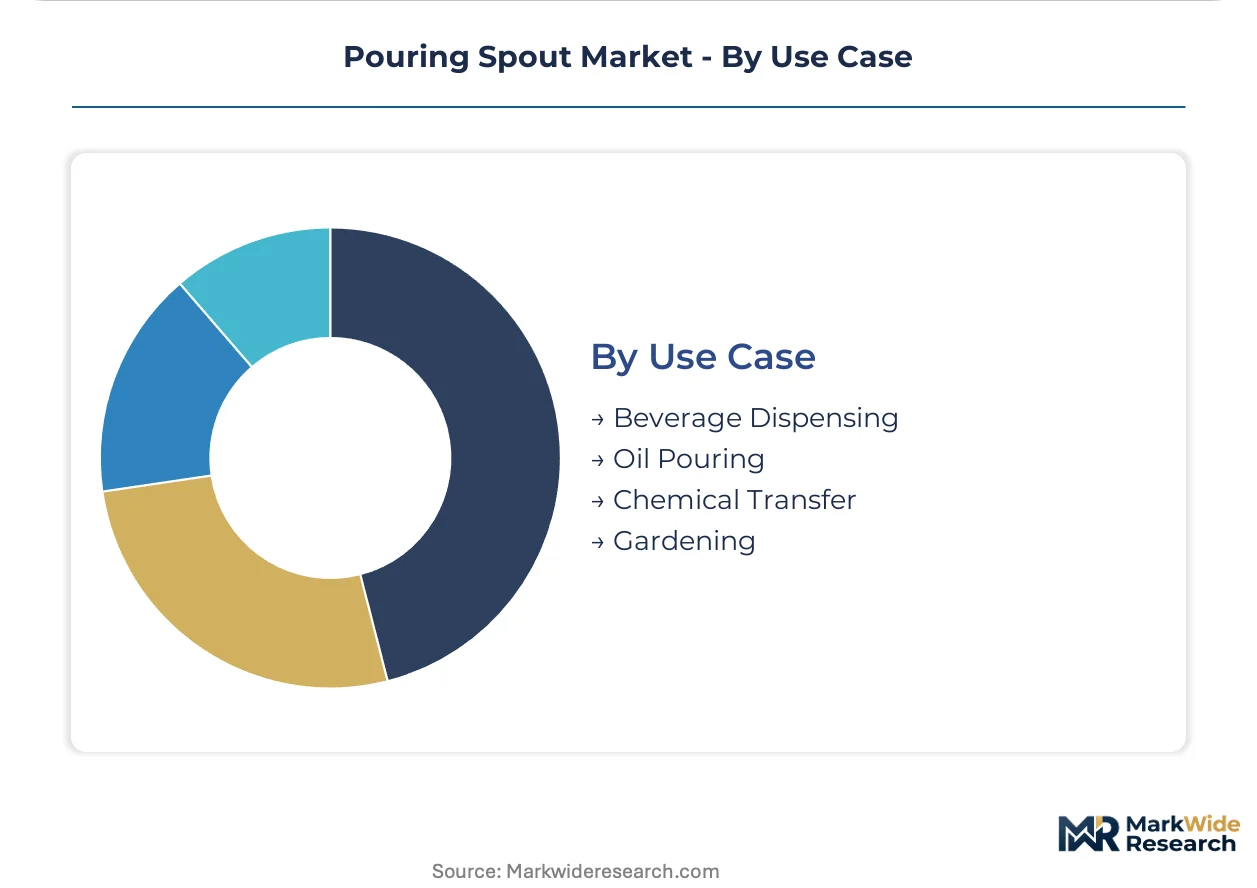
Use Case:
Regulatory intensity varies sharply across liquid categories, shaping material selection and certification requirements.
- Beverage Dispensing:Hot-fill compatibility requirements from United States ready-to-drink coffee processors pull silicone adoption. EFSA and FDA dual certification is table stakes for multinational supply.
- Oil Pouring:Edible oil migration testing under EU Regulation 10/2011 and China's GB standards creates compliance barriers. SAMR enforcement in Shanghai and Shenzhen inspection regimes adds third-layer certification for exporters.
- Chemical Transfer:Industrial solvent resistance demands fluoropolymer or metal construction with UN-certified containment.
- Gardening:Fertilizer and pesticide dispensing tolerates lower-spec polypropylene with basic thread sealing.
Oil Pouring represents the most regulated application segment, while Beverage Dispensing climbs the fastest on hot-fill processing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade balances in pouring spout procurement tilt toward export-oriented manufacturing clusters, with import dependency concentrated in markets lacking domestic injection-molding scale. FDA and EFSA compliance certifications now function as de facto trade barriers, filtering supplier access across North American and European procurement channels.
United States
Edible oil bottlers in California and Illinois drive vented spout specifications for automated filling lines. FDA food-contact notification requirements compress supplier qualification timelines to 180-day windows. Chicago-area packaging converters source polypropylene spouts from domestic molders to avoid propylene feedstock volatility exposure.
Germany
Beverage bottlers for Aldi and Lidl private-label programs consolidate supplier panels to three approved molders. EFSA migration limits under EU Regulation 10/2011 mandate dual certification for edible oil packaging exports. Bavarian injection specialists capture volume through captive polymer compounding capabilities.
China
Pearl River Delta export manufacturing supplies cost-optimized standard spouts to African and Southeast Asian packaging converters. SAMR enforcement of GB standards in Shanghai and Shenzhen inspection regimes adds compliance layers for food-contact exports. Guangdong Wintime Industrial anchors regional production scale.
India
Domestic edible oil majors localize packaging procurement under FSSAI import-substitution policies. BIS compliance requirements filter mid-tier Chinese exporters from premium supply tiers. Maharashtra and Gujarat molders expand capacity to serve HUL and Adani Wilmar contract volumes.
Japan
Hot-fill beverage processors specify silicone spouts for ready-to-drink coffee lines exceeding polypropylene thermal limits. METI guidance on packaging recyclability pressures multi-material spout redesign. Kanto-region bottlers source platinum-cured elastomer components from domestic compounders.
Pouring Spout Market Competitive Landscape
Listed leaders compete with private specialists across certification breadth and mold-making autonomy. The vendor base splits between multinational closure conglomerates with captive polymer science labs and regional injection specialists serving cost-sensitive export markets. Two archetypes dominate: integrated polymer compounders holding FDA-EFSA dual certification, and Pearl River Delta fabricators competing on thermoforming efficiency. Competitive moves concentrate on backward integration into mold fabrication and strategic partnerships with hot-fill beverage processors seeking thermal-stable materials.
Within the integrated compounder tier, AptarGroup and Silgan Dispensing Systems exemplify premium positioning through polymer science capabilities and North American manufacturing scale. Guangdong Wintime Industrial Co. Ltd occupies a position among export-volume specialists serving African and Southeast Asian packaging converters from Pearl River Delta production bases.
| Leading Market Players |
|---|
| Seal-Spout Corporation |
| Spill-Stop Mfg. LLC |
| AptarGroup |
| Silgan Dispensing Systems |
| Weener Plastics |
| Berry Global |
| Amcor plc |
| Guangdong Wintime Industrial Co. Ltd |
| Xiamen Xintonglian Plastic Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Captive polymer compounding capacity in Bavarian and Guangdong injection clusters compresses unit cost floors for FDA-EFSA dual-certified spouts while simultaneously concentrating price-setting power among molders with in-house resin formulation. This scale asymmetry forces mid-tier converters toward undifferentiated standard-spout segments or exit.
Pricing Analysis
Industrial OEM buyers anchor contract pricing around multi-year volume commitments with polypropylene feedstock pass-through clauses. Three-tier pricing structure across premium, standard, and economy levels separates silicone hot-fill specifications from polypropylene commodity formats from unvented basic transfer spouts. Price differentiation hinges on FDA-EFSA dual certification status and captive mold-making capability. Cost compression in standard polypropylene tiers is intensifying because Pearl River Delta export volumes face propylene monomer volatility from Gulf Coast petrochemical complexes. Mass-market retail distributors exhibit highest price sensitivity; pharmaceutical and premium edible oil bottlers demonstrate lowest sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
Fourteen-week lead times for precision vent-channel tooling concentrate inventory risk among German and Japanese equipment suppliers serving North American and European molders. Manufacturing gravity centers on Germany, China, and the United States, with Guangdong Wintime Industrial and Bavarian injection specialists commanding regional supply. Raw material flows draw from propylene monomer streams, platinum-cured silicone elastomers, and precision mold steel grades. Single-source vulnerability for laminar-flow geometry tooling creates bottleneck exposure. Distribution runs through direct procurement relationships where Aldi and Lidl private-label bottlers consolidate supplier panels to three approved molders, bypassing traditional closure distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Standardized 38mm spout interfaces for refill station retail formats in Germany and the Netherlands are creating platform-economics dynamics where first-mover specification lock-in determines long-term procurement relationships.
For Market Incumbents: Fortify backward integration into mold fabrication to reduce 14-week lead time exposure from German and Japanese equipment suppliers. Deepen captive polymer compounding capabilities to absorb propylene monomer volatility that squeezes mid-tier converters. Prioritize EFSA-FDA dual certification maintenance as Unilever and Nestlé export programs mandate post-consumer recycled content validation under France's AGEC law and Germany's Verpackungsgesetz amendments. For New Entrants and Emerging Players: Anchor in India's FSSAI import-substitution corridor where domestic edible oil majors localize packaging procurement away from mid-tier Chinese exporters. Target Maharashtra and Gujarat molder expansion zones serving HUL and Adani Wilmar contract volumes. Pursue BIS compliance as a go-to-market wedge to filter SAMR-certified Chinese competitors from premium supply tiers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated compounders with FDA-EFSA dual certification and in-house mold-making capabilities over Pearl River Delta volume specialists facing EPR fee escalations. Long-term viability rests on material traceability infrastructure for extended producer responsibility compliance. Monitor RFID-enabled spout adoption in pharmaceutical channels as an inflection signal for connected dispensing convergence with IoT inventory management systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mold Fabrication | Cuts 14-week lead time exposure from German and Japanese equipment suppliers. |
| Dual Certification Investment | Captures Unilever and Nestlé export program mandates under EU EFSA migration limits. |
| Post-Consumer Recycled Content Qualification | Validates mass-balance certification chains for France's AGEC law compliance. |
| RFID-Enabled Spout Development | Converges with IoT inventory management in hospital and long-term care channels. |
| Refill Station Interface Standardization | Locks in 38mm specification dominance for German and Dutch bulk liquid networks. |
Research Methodology
A standing panel of injection molding plant managers, edible oil packaging procurement leads, beverage bottler technical directors, and FDA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA food-contact notification databases, EU EFSA migration limit guidance documents, SAMR GB standards enforcement records, and customs trade flow data for polypropylene closure components. Bottom-up volume estimates from molder capacity utilization surveys were triangulated against top-down demand projections from edible oil and beverage bottling line expansion announcements.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including material type, end-use industry, design style, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical volume trajectories adjusted for hot-fill beverage processing expansion and EPR framework implementation timelines. Industry-specific forecast inputs incorporated propylene monomer price elasticity coefficients and migration testing laboratory queue durations.
Material uncertainties — propylene feedstock volatility, FDA notification processing delays, and EPR fee escalation trajectories — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding hot-fill adoption curves and refill station retail format penetration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Fruit Juice Packaging Market
Beverage Packaging
North America Beverage Packaging Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Beverage Cans Market
Beverage Packaging
Global Beverage Container Market
Beverage Packaging
Cold Beverage Cups Market
Beverage Packaging
Bullet Bottles Market
Beverage Packaging
Stackable Beaker Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Skep Bottle Market
Beverage Packaging
US Soft Drinks Packaging Market
Beverage Packaging
Europe Beverage Container Market
Beverage Packaging
Beverage Cups Market
Beverage Packaging
Bottle Pourers Market