
 Beveled Bottles Market | 2026-2036
Beveled Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Beveled Bottles Market Outlook
The EU Green Deal is consolidating demand for lower-carbon glass packaging across European spirits and cosmetics houses. Ardagh Group S.A. leverages its furnace modernization program to sustain energy-efficient output of decorative beveled designs. Saverglass Group anchors the premium segment through specialized mold capabilities for complex angular geometries. Stoelzle Glass Group competes on pharmaceutical-grade beveled bottles with precise dimensional tolerances.
Beveled bottles feature angular, faceted sidewalls engineered through mold-based forming or post-mold cutting processes, typically achieving wall thickness uniformity within 0.5 millimeters for structural integrity. These containers serve primarily as premium packaging vehicles where tactile differentiation and light-refracting aesthetics command shelf attention. Glass dominates the product type landscape owing to its refractive clarity and compatibility with spirit and fragrance applications, while plastic variants gain traction in travel-retail sizes where weight reduction matters. The cosmetics end user segment captures the deepest margin pools, as luxury houses commission limited-run beveled designs with bespoke closure systems.
REACH compliance governs chemical migration thresholds for decorative coatings applied to beveled glass surfaces in Europe, while FDA regulations in the United States dictate pharmaceutical packaging integrity standards that constrain angular geometries in certain drug delivery formats. The EU Packaging and Packaging Waste Directive shapes recycled content mandates that push mold designers toward compatibility with cullet-heavy batch formulations. Stakeholders must monitor evolving extended producer responsibility schemes that will recalibrate cost structures for complex decorative bottles across their primary demand centers.
Market Dynamics
The EU F-Gas Regulation is compressing allowable glass furnace emissions, forcing converters toward electric melting technologies and lighter-weight formulations that preserve beveled geometries at reduced material intensity.
Growth Catalysts
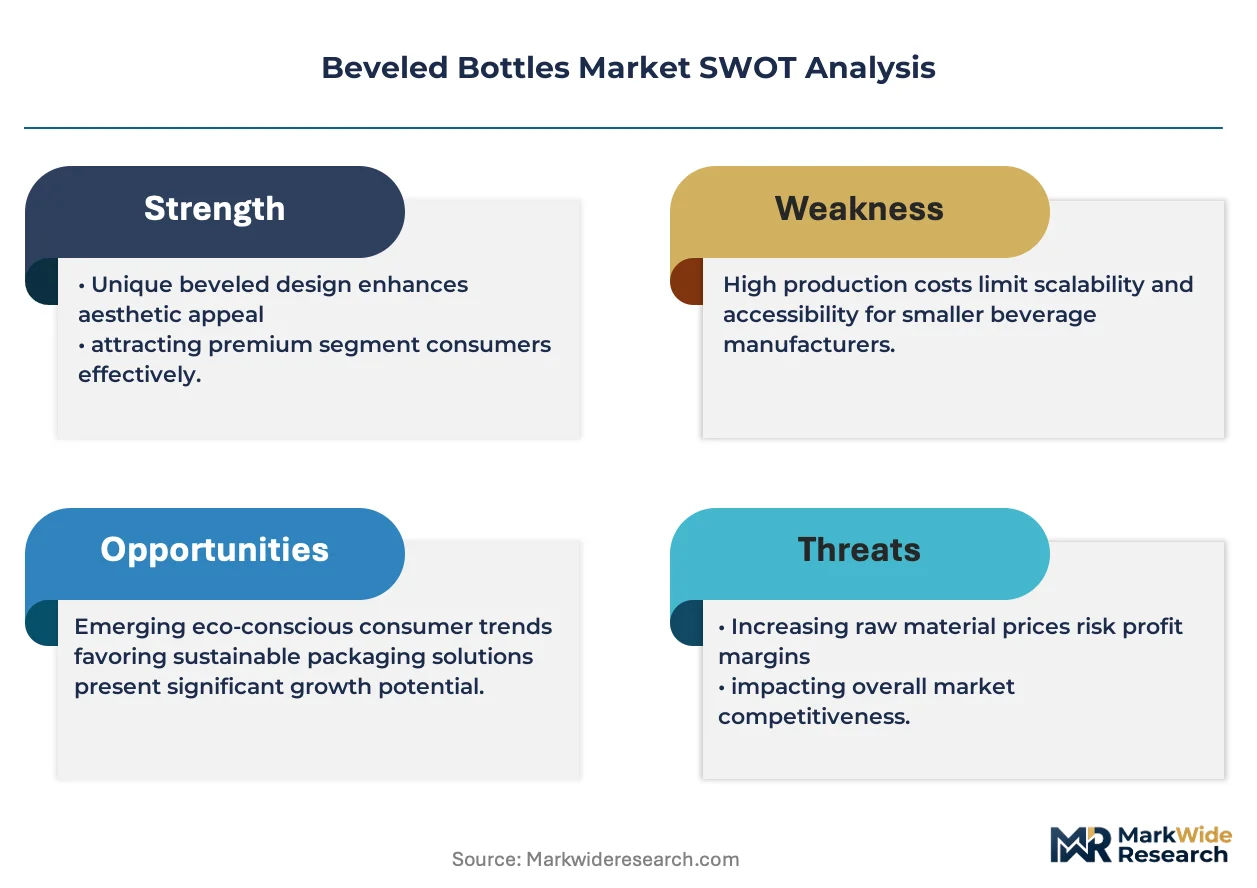
- REACH-compliant decorative coatings:European cosmetics houses now specify low-migration surface treatments for angular glass surfaces, expanding addressable premium packaging applications.
- France:Verallia and Saverglass maintain concentrated mold engineering capabilities that shorten development cycles for complex beveled prototypes.
- Lightweighting processes:Narrow-neck press-and-blow forming advances enable wall thickness reduction to 2.8 millimeters without sacrificing facet definition.
Market Restraints
- Natural gas price volatility:Soda-lime batch melting depends on fossil fuel feedstock, exposing margins to energy input swings across European production clusters.
- Single-source mold steel:High-nickel alloy tooling for angular geometries concentrates with Swedish and Austrian specialty metallurgy suppliers.
- Pharmaceutical geometry constraints:FDA packaging integrity standards limit angular sidewall angles in certain drug delivery formats to 15 degrees maximum.
Strategic Opportunities
- Travel-retail miniatures:Plastic beveled variants below 50 milliliters penetrate duty-free channels where weight restrictions favor polymer over glass.
- EU Green Deal recycled content mandates:The Packaging and Packaging Waste Directive creates pull for post-consumer cullet-compatible mold designs.
- Laser cold-cutting convergence:Post-forming diamond-wheel cutting integrates with robotic handling to enable micro-batch customization for limited fragrance releases.
Industry Challenges
- Mold pattern digitization:CAD-to-CAM translation for faceted geometries demands specialized surface modeling expertise scarce outside French and German glass engineering programs.
- Furnace reconfiguration timelines:Electric melting retrofits require 18-to-24-month certification cycles under ECHA industrial emissions protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beveled Bottles Market |
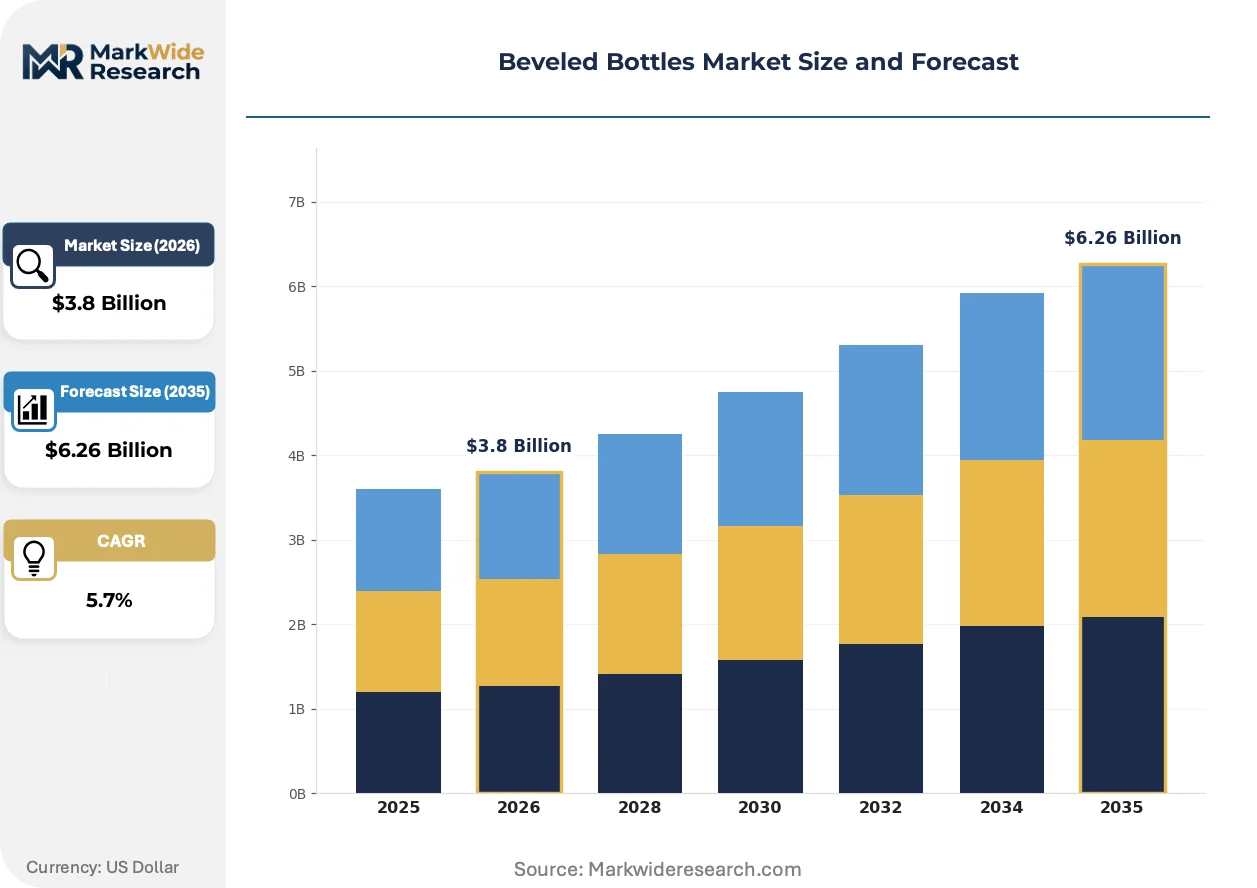
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Metal, Composite Closure Type: Screw Cap, Dropper, Cork, Pump End User: Pharmaceuticals, Beverages, Cosmetics, Chemicals Packaging Size: 50ml, 100ml, 250ml, 500ml |
| Companies Covered | Owens-Illinois Inc. (O-I Glass), Ardagh Group S.A., Verallia (Saint-Gobain Packaging), Saverglass Group, Vitro Packaging, Stoelzle Glass Group, Vidrala S.A., Piramal Glass, Vetropack Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beveled Bottles Market Strategic Shifts
Active furnace electrification and post-consumer cullet integration are rewriting batch chemistry requirements, while digital surface finishing expands design latitude beyond traditional mold constraints.
Laser-assisted cold-cutting is absorbing manual grinding operations for precision facet definition. Premium spirits brands in Cognac and Speyside adopt this for limited editions requiring 16-to-20 distinct angular planes. The technology is absorbing artisan finishing timelines from three weeks to four days, compressing new product introduction cycles.
REACH Annex XVII restrictions on chromium VI in decorative coatings are eliminating legacy electroplating for metallic facet accents. French and Italian cosmetics houses now specify physical vapor deposition alternatives. The fragrance segment is responding with accelerated qualification of titanium nitride surface treatments.
Direct brand-to-glasshouse collaboration is displacing traditional design agency intermediation. Luxury houses in Paris and Milan now embed in-house industrial designers at Saverglass and Stoelzle facilities during prototype phases. This pattern concentrates in limited-edition fragrance launches where 12-week development cycles override standard 26-week commercial timelines.
Beveled Bottles Market Segmentation
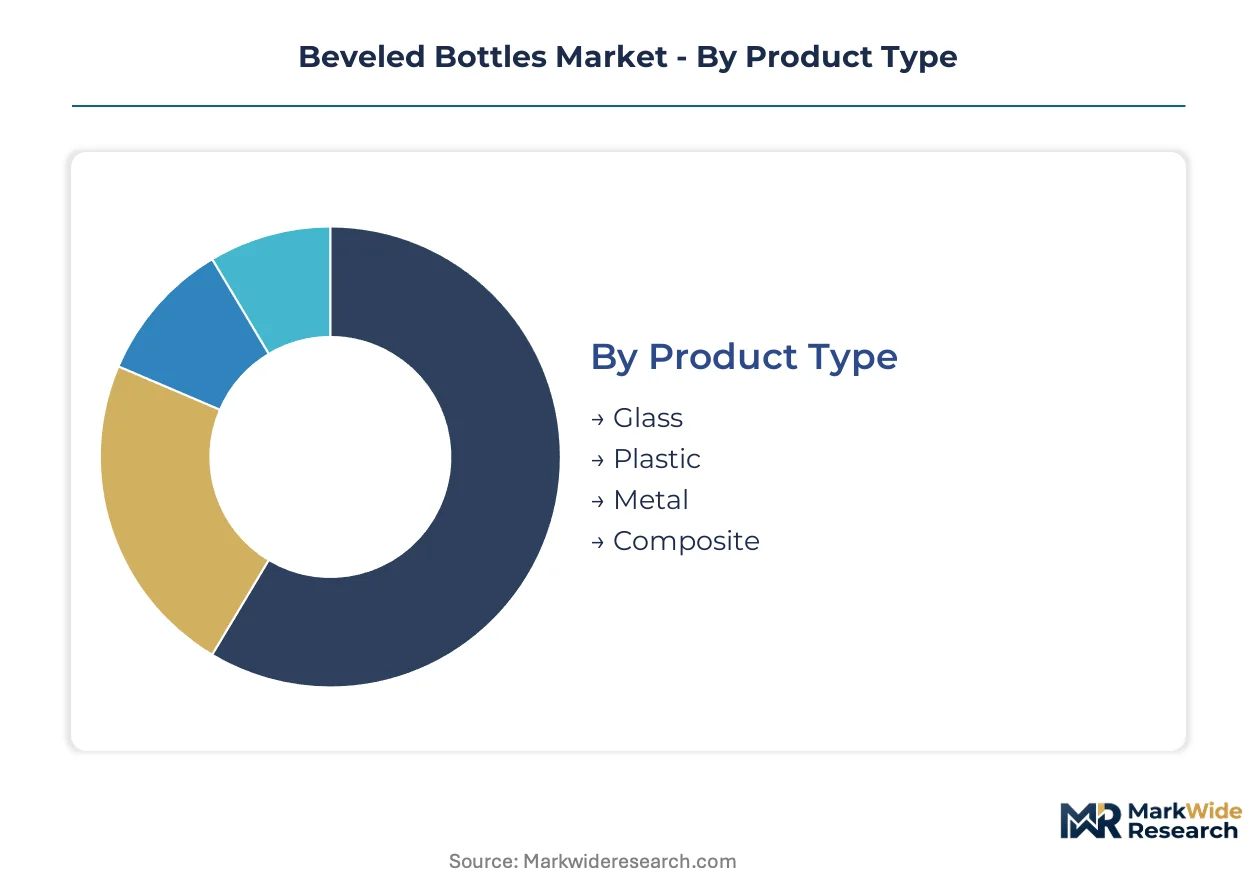
Beveled bottle converters engineer distinct product architectures to balance refractive aesthetics against functional requirements across spirits, fragrance, and pharmaceutical channels. Segmentation reveals how material selection and closure systems calibrate premium positioning against regulatory compliance and supply chain constraints.
Product Type:
Glass commands volume leadership while plastic captures travel-retail expansion.
- Glass:Soda-lime and borosilicate formulations achieve wall thickness uniformity within 0.5 millimeters for structural integrity of angular geometries. Demand concentrates in French Cognac houses and Scottish whisky distilleries where light-refracting clarity signals craft heritage against EU F-Gas Regulation pressures on furnace emissions.
- Plastic:PET and acrylic variants enable sub-50 millimeter travel-retail formats where weight restrictions favor polymer over glass. Duty-free channels in Paris Charles de Gaulle and London Heathrow drive specification for injection-molded faceted designs with comparable tactile differentiation.
- Metal:Aluminum beveled containers serve niche fragrance applications requiring electromagnetic shielding for volatile compounds.
- Composite:Glass-plastic hybrid constructions address pharmaceutical child-resistance mandates while preserving angular shelf presence.
Mature deployment sits with Glass. Newer deployment is concentrated in Plastic.
Closure Type:
Threaded systems dominate commercial scale while precision dispensers command premium cosmetics.
- Screw Cap:Continuous-thread aluminum and phenolic resin closures accommodate high-speed capping lines for spirits volume production. Standardization with GPI and SPI neck finishes reduces tooling proliferation across Ardagh and Verallia manufacturing networks.
- Dropper:Glass pipette assemblies with bulb actuators serve serum and essential oil applications requiring precise volumetric dispensing. Italian cosmetics houses in Milan specify borosilicate droppers with silicone bulbs for 15-30 milliliter beveled flacons.
- Cork:Natural and synthetic stopper systems anchor premium wine and whisky positioning.
- Pump:Metered-dose actuators integrate with beveled shoulder geometries for lotion and fragrance mist applications.
Cost efficiency clusters around Screw Cap. Margin expansion concentrates in Dropper.
End User:
Cosmetics generate deepest margin pools while pharmaceuticals impose strictest dimensional tolerances.
- Cosmetics:Limited-run beveled designs with bespoke closure systems capture premium fragrance and skincare positioning. Paris and Milan luxury houses commission 12-week development cycles through direct glasshouse collaboration, displacing traditional design agency intermediation.
- Pharmaceuticals:FDA packaging integrity standards constrain angular sidewall angles to 15 degrees maximum for certain drug delivery formats. Stoelzle Glass Group competes on dimensional tolerances meeting USP <660> glass grain durability requirements.
- Beverages:Premium spirits brands expand beveled glass adoption for craft positioning in Cognac and Speyside.
- Chemicals:Industrial solvents and reagents utilize beveled containers for ergonomic handling and label adhesion.
Regulatory stringency peaks in Pharmaceuticals. Design flexibility expands most quickly in Cosmetics.
Packaging Size:
Mid-range formats balance production efficiency against sampling and travel convenience.
- 50ml:Miniature formats serve airline duty-free and hotel amenity channels where weight and breakage risk favor plastic beveled variants. Laser cold-cutting enables micro-batch customization for limited fragrance releases at this scale.
- 100ml:Standard fragrance and spirits format optimizes mold utilization and filling line throughput across European production clusters.
- 250ml:Premium spirits and gourmet condiment applications utilize this intermediate capacity.
- 500ml:Larger format serves high-volume beverage and institutional chemical dispensing.
Volume concentration sits with 100ml. Steepest expansion trajectory runs through 50ml.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris anchors the global beveled bottle trade through concentrated mold engineering capabilities and direct collaboration between luxury houses and glass converters in the Île-de-France corridor.
France
Premium spirits brands in Cognac and fragrance houses in Paris commission complex angular geometries through 12-week development cycles. The EU F-Gas Regulation compresses furnace emissions allowances, pushing Verallia and Saverglass toward electric melting retrofits. Production clusters concentrate in Hauts-de-France and Nouvelle-Aquitaine where specialized mold steel suppliers maintain proximity to converter facilities.
Germany
Pharmaceutical packaging demand from Frankfurt and Munich drives dimensional tolerance requirements for beveled glass containers. ECHA industrial emissions protocols govern 18-to-24-month certification cycles for furnace electrification. The Baden-Württemberg region hosts precision mold engineering programs supplying CAD-to-CAM translation expertise for faceted geometries.
United States
FDA packaging integrity standards constrain angular sidewall angles to 15 degrees maximum for certain drug delivery formats, shaping pharmaceutical segment specifications. Owens-Illinois operates production networks serving premium spirits brands expanding craft positioning. The Midwest glass corridor maintains soda-lime batch melting capacity exposed to natural gas price volatility.
Italy
Milan-based cosmetics houses specify borosilicate droppers with silicone bulbs for 15-30 milliliter beveled flacons. REACH Annex XVII restrictions on chromium VI eliminate legacy electroplating for metallic facet accents. The Veneto and Lombardy regions concentrate physical vapor deposition qualification for titanium nitride surface treatments.
United Kingdom
Scottish whisky distilleries in Speyside adopt laser-assisted cold-cutting for limited editions requiring 16-to-20 distinct angular planes. The EU Packaging and Packaging Waste Directive shapes recycled content mandates affecting mold design compatibility. Greater London serves as a coordination hub for direct brand-to-glasshouse collaboration displacing traditional design agency intermediation.
Beveled Bottles Market Competitive Environment
Premium-margin players sit above commodity-margin players across mold complexity and development cycle speed, with tiered capabilities separating limited-run fragrance specialists from high-volume spirits suppliers. The vendor base organizes around furnace scale, mold engineering depth, and vertical integration into decorative finishing. Three archetypes dominate: integrated glass-converters with captive mold shops, specialized premium-segment boutiques, and diversified packaging conglomerates with glass divisions. Competitive moves concentrate on electric furnace retrofit partnerships and laser cold-cutting technology licensing.
Among European-based converters, Ardagh Group S.A., Verallia, and Saverglass Group occupy positions across the premium-to-mass tier spectrum. Ardagh exemplifies the diversified conglomerate archetype with furnace modernization programs sustaining energy-efficient output. Verallia represents integrated production gravity in the French market. Saverglass sits within the specialized boutique tier, anchoring premium-segment capabilities for complex angular geometries.
| Leading Market Players |
|---|
| Owens-Illinois Inc. (O-I Glass) |
| Ardagh Group S.A. |
| Verallia (Saint-Gobain Packaging) |
| Saverglass Group |
| Vitro Packaging |
| Stoelzle Glass Group |
| Vidrala S.A. |
| Piramal Glass |
| Vetropack Group |
| Others |
Value Chain & Pricing Dynamics
Specialized mold engineering talent concentrated in France and Germany widens pricing spreads between limited-run fragrance prototypes and mass-market spirits volumes. Labor-cost differentials between Hauts-de-France mold shops and automated high-volume lines in Spain compress margins at the standard tier while preserving premium markups for angular geometries.
Pricing Analysis
Development-cycle speed commands value-based premiums, with 12-week prototype timelines from Saverglass and Stoelzle fetching 40-60% markups over 26-week commercial schedules. Price differentiation rests on mold complexity tiers and REACH-compliant coating certifications. Cost compression in standard spirits formats is intensifying because natural gas price volatility squeezes soda-lime batch melting margins. Mass-market beverage buyers exhibit highest price sensitivity; cosmetics houses commissioning limited editions show lowest.
Supply Chain Analysis
EU Green Deal recycled content mandates are reshaping sourcing patterns toward post-consumer cullet-compatible mold designs. Production gravity centers on France, Germany, and Italy for glass forming; China and South Korea supply high-nickel alloy mold steel. Raw material dependencies include soda-lime batch chemicals, borosilicate formulations, and specialty mold metallurgy. Single-source vulnerability concentrates in Swedish and Austrian specialty steel suppliers. Distribution runs through direct brand-to-glasshouse collaboration displacing traditional design agency channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as converters pursue captive mold engineering capabilities to compress development cycles and defend premium positioning against commoditization.
For Market Incumbents: Cement dominance through furnace electrification retrofits and captive mold shop acquisitions. Electric melting partnerships with equipment suppliers secure ECHA certification timelines before competitors. Laser cold-cutting technology licensing blocks emerging boutiques from matching 4-day finishing turnaround. Threat substitution from plastic travel-retail miniatures demands glass lightweighting investment to preserve material share. For New Entrants and Emerging Players: The 100ml-to-50ml price-point gap between standard fragrance and travel-retail miniature formats offers white-space entry. Unpenetrated duty-free channels at Dubai International and Singapore Changi favor sub-50ml plastic variants where weight restrictions exclude glass. Target pharmaceutical-grade dimensional tolerances as the most penetrable segment given FDA geometry constraints limit incumbent design latitude. Go-to-market through direct collaboration with Milan and Paris cosmetics houses bypasses established agency relationships. For Investors and Strategic Acquirers: Re-rating potential sits with specialized premium-segment boutiques given EU F-Gas Regulation catalyst forcing electric furnace consolidation. Long-term viability favors converters with backward integration into mold engineering and decorative finishing. Acquisition target archetype: French or German mid-caps with CAD-to-CAM surface modeling expertise and REACH-compliant coating qualifications. Signal to watch: laser cold-cutting equipment orders as inflection indicator for micro-batch customization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Furnace Retrofit Partnership | Secures ECHA certification timelines ahead of EU F-Gas Regulation compliance deadlines. |
| Laser Cold-Cutting Technology Licensing | Compresses artisan finishing from three weeks to four days for Cognac limited editions. |
| Captive Mold Engineering Acquisition | Eliminates single-source dependency on Swedish and Austrian specialty steel suppliers. |
| Direct Brand Collaboration Program | Displaces traditional design agency intermediation for 12-week fragrance prototype cycles. |
| REACH-Compliant Coating Qualification | Replaces chromium VI electroplating with titanium nitride for Milan cosmetics houses. |
Study Parameters
Independent corroboration across converter production managers, mold engineering specialists, and luxury house packaging directors underwrites the qualitative findings. Primary interviews with furnace operations leads at Ardagh and Verallia, procurement officers at Paris fragrance houses, and regulatory affairs managers navigating REACH Annex XVII restrictions combined with secondary validation from ECHA industrial emissions protocols, EU Packaging and Packaging Waste Directive filings, and glass industry trade association capacity reports. Bottom-up segment sizing and top-down market triangulation cross-validated volume estimates.
Rate-of-change decomposition across material type, closure system, end-use application, and packaging size dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectories weighted by production cluster capacity expansion plans and regulatory compliance timelines. Industry-specific forecast inputs included EU F-Gas Regulation furnace retrofit schedules and laser cold-cutting adoption curves among Cognac and Speyside distilleries.
Underlying measurement precision varies by segment; glass material type and cosmetics end-use carry tighter precision than emerging plastic variants and pharmaceutical applications. Forecasts reflect assumptions about electric melting technology maturation and recycled cullet batch chemistry stability. Natural gas price volatility, single-source mold steel supply disruptions, and REACH coating restriction amendments present revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Zippered Bottle Suit Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
French Square Bottle Market
Beverage Packaging
Water Cooler Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Beverage Cans Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Europe Soft Drinks Packaging Market
Beverage Packaging
North America Beverage Packaging Market
Beverage Packaging
US Beverage Packaging Market
Beverage Packaging
Vending Cups Market
Beverage Packaging
North America Soft Drinks Packaging Market
Beverage Packaging
Square Media Bottle Market
Beverage Packaging
Cold Beverage Cups Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Combi Cans Market