
 Drink Can Market | 2026-2036
Drink Can Market Size, Share, and Industry Trends Forecast 2026-2036
Drink Can Market Analysis
EU Green Deal packaging mandates is decoupling virgin aluminum dependence from cost-efficient production models. Ball Corporation leverages backward integration into recycled metal sourcing to sustain margin resilience across European operations. Crown Holdings anchors its competitiveness through manufacturing scale in North American beverage corridors. Ardagh Group S.A. differentiates via specialty shaping capabilities that serve craft beer branding requirements.
A drink can constitutes a cylindrical metal container engineered from aluminum alloy or tinplate steel, typically wall-thickness between 0.097 mm and 0.115 mm, formed through deep drawing and ironing processes to hold carbonated or non-carbonated beverages under internal pressure. Its primary commercial purpose centers on shelf-stable liquid distribution with minimal weight, maximal stackability, and full recyclability. Aluminum dominates type segmentation due to its superior strength-to-weight ratio and infinite recyclability loop, while steel retains niche presence in price-sensitive emerging markets. The 330ml size category leads volume globally, though 500ml formats are gaining traction in energy drink and premium craft beer applications where per-unit value capture runs higher.
FDA food-contact regulations in the United States, REACH chemical compliance in Europe, and BIS standards in India collectively govern coating formulations, metal purity thresholds, and migration limits that determine market access for can manufacturers. These frameworks elevate R&D spending on BPA-non-intent linings and low-carbon smelting certifications as baseline qualification criteria. Stakeholders must monitor evolving extended producer responsibility schemes and deposit-return system expansions that will reshape collection infrastructure investments and recycled content mandates.
Market Dynamics
EU Green Deal packaging mandates are decoupling virgin aluminum dependence from cost-efficient production models across European supply chains. Ball Corporation leverages backward integration into recycled metal sourcing to sustain margin resilience.
Growth Catalysts
- Aluminum Recyclability Mandates:EU Green Deal directives mandate minimum recycled content thresholds, accelerating demand for post-consumer scrap processing infrastructure.
- Craft Beer Proliferation:Small-batch breweries in Brazil and the United States favor aluminum formats for lightweight logistics and shelf differentiation.
- Energy Drink Format Expansion:500ml can specifications are displacing PET bottles in functional beverage segments seeking premium tactile differentiation.
Market Restraints
- Aluminum Ingot Volatility:LME price swings for primary aluminum compress converter margins during contract renegotiation cycles.
- Coating Chemical Constraints:REACH restrictions on epoxy-based BPA linings force reformulation timelines that extend qualification periods.
- Steel Can Substitution:Tinplate alternatives retain cost advantages in price-sensitive Indian and African markets.
Strategic Opportunities
- Deposit-Return System Expansion:Germany and Scandinavian markets demonstrate closed-loop collection economics that reduce raw material exposure.
- Smart Can Integration:NFC-enabled packaging convergence with mobile commerce platforms opens direct-to-consumer engagement channels.
- India Urbanization:Rising packaged beverage consumption in Tier-2 cities outpaces glass infrastructure deployment.
Industry Challenges
- Coating Formulation Talent Scarcity:Polymer chemistry expertise for BPA-non-intent linings concentrates among a limited supplier base.
- Smelter Certification Timelines:ASI Chain of Custody documentation requirements extend supplier onboarding by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drink Can Market |
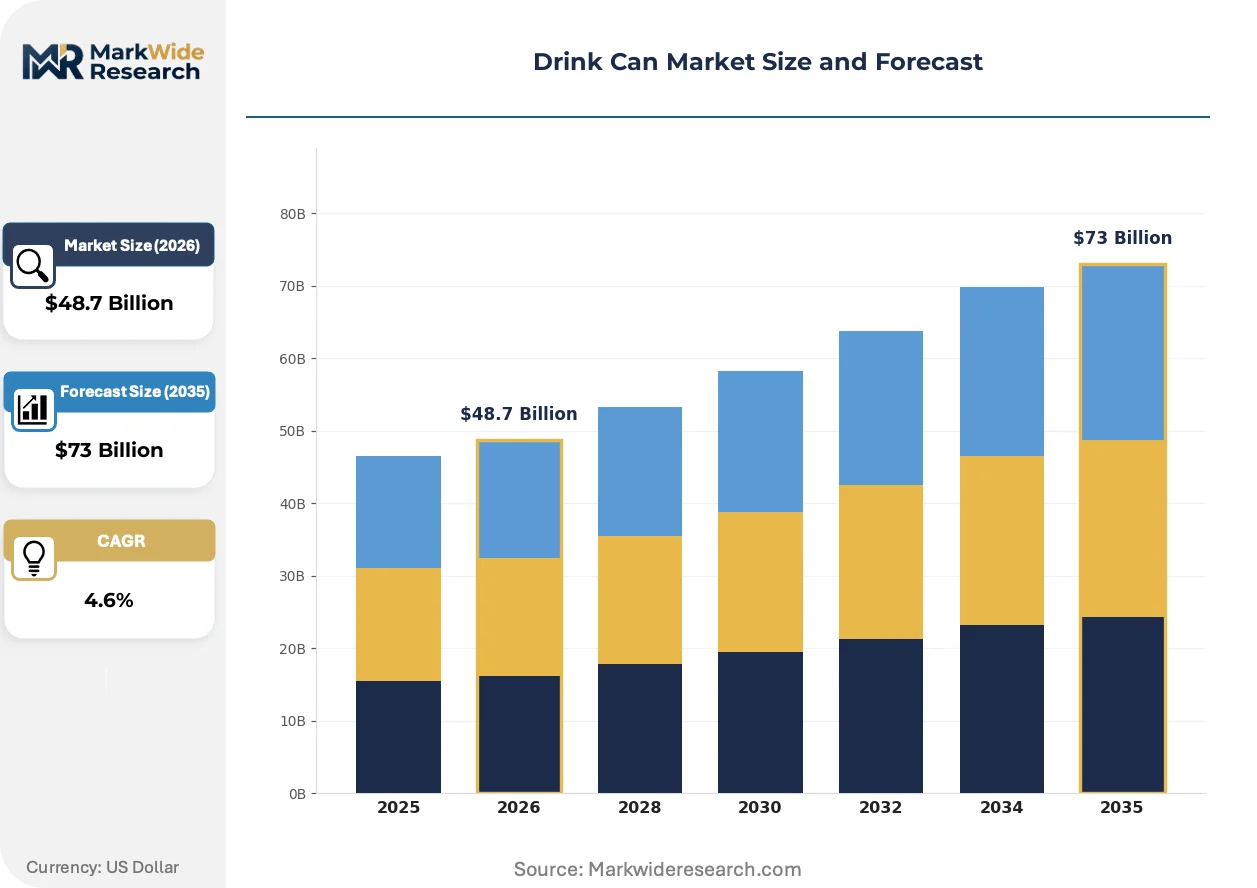
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Aluminum, Steel, Biodegradable, Composite Size: 250ml, 330ml, 500ml, 1L Closure Type: Pull-Tab, Twist-Off, Push-Pull, Spout Application: Soft Drinks, Energy Drinks, Craft Beers, Sodas |
| Companies Covered | Ball Corporation, Crown Holdings, Inc., Ardagh Group S.A., CPMC Holdings Ltd., Orora Packaging Australia Pty Ltd, CANPACK S.A., Toyo Seikan Co., Ltd., Silgan Holdings, Mahmood Saeed Can and End Industry Company Limited (MSCANCO), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drink Can Market Emerging Trajectories
Active reshaping in drink can markets centers on material circularity, regulatory chemistry compliance, and format premiumization. These forces are compressing traditional production economics while opening new value capture mechanisms.
Digital printing on aluminum substrates is unifying short-run customization with mass-production economics. Craft breweries in the United States and Brazil adopt direct-to-can decoration for seasonal releases and limited editions. This capability is compressing minimum order quantities from hundreds of thousands to tens of thousands, fragmenting volume concentration historically controlled by major brands.
REACH chemical compliance in Europe mandates migration testing for all food-contact coatings, including emerging polyester and acrylic alternatives. Manufacturers must maintain dual formulation portfolios during transition periods. Beverage exporters to the EU face the steepest compliance burden, particularly those serving carbonated and acidic product categories where lining integrity is critical.
Direct-store-delivery networks for convenience channel beverage replenishment are compressing order cycles from weekly to daily frequencies. Distributors in Brazil and Mexico now require just-in-time can availability to match perishable dairy and juice adjacencies. This operational shift favors regional canning plants with sub-500km radius coverage over centralized continental supply.
Drink Can Market Segmentation
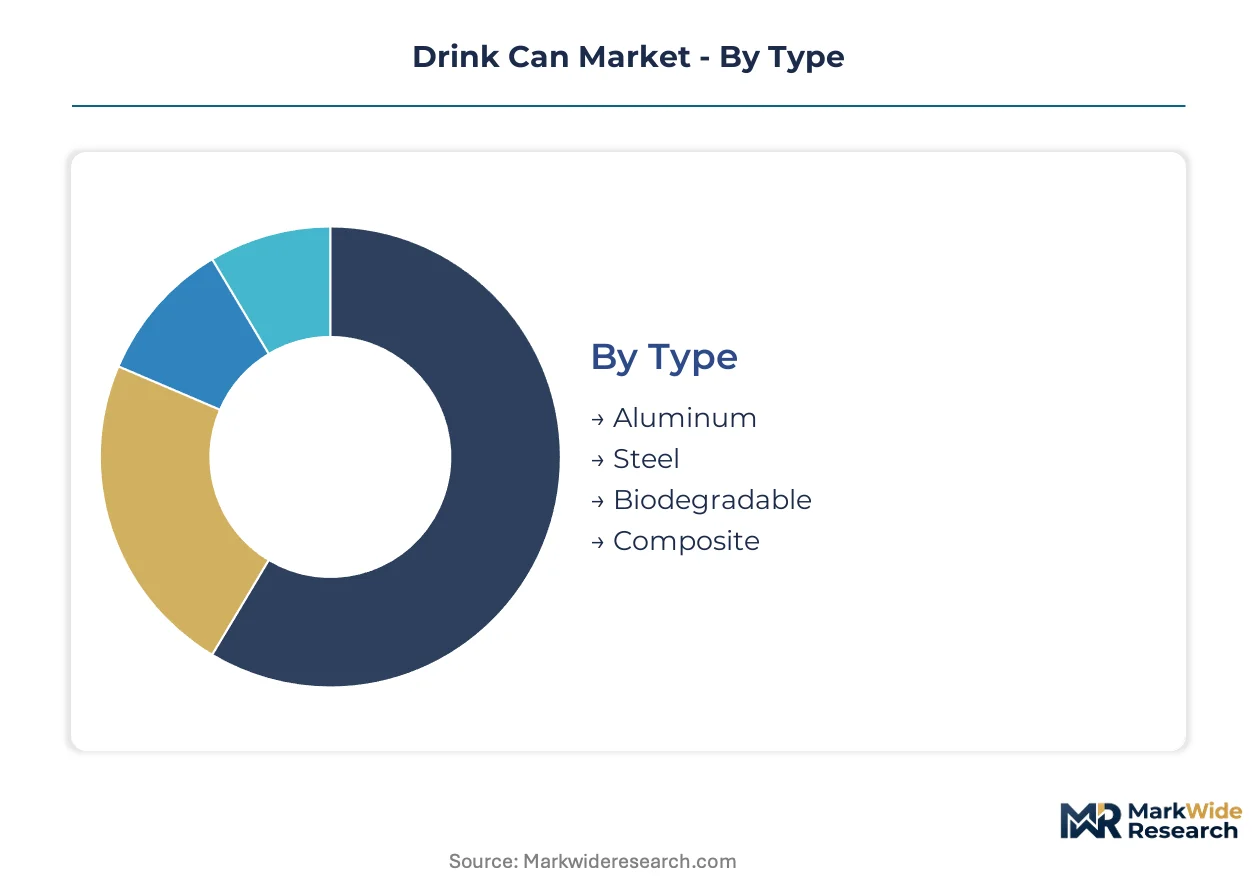
Drink can manufacturers configure production lines around material chemistry, dimensional specifications, and end-use pressure requirements. Each segmentation axis determines capital allocation, coating formulation, and regional plant placement decisions.
Type:
Supply concentration for primary metal inputs dictates converter sourcing strategies and margin exposure to commodity volatility.
- Aluminum:Engineered from 3104-H19 or 3004-H19 alloy with wall thickness between 0.097 mm and 0.115 mm, formed through deep drawing and ironing processes. Demand concentrates in Brazil and the United States where craft breweries and energy drink producers prioritize lightweight logistics and infinite recyclability loops. Ball Corporation and Crown Holdings anchor smelter relationships to secure ASI-certified recycled content quotas mandated by EU Green Deal directives.
- Steel:Tinplate substrates with chromium passivation layers offer cost advantages in price-sensitive procurement environments. Indian and African markets retain steel preference where beverage price points resist aluminum conversion premiums. Ardagh Group maintains dedicated steel canning capacity to serve these regional cost structures.
- Biodegradable:Emerging plant-fiber and bio-polymer laminates target single-use plastic bans in municipal jurisdictions.
- Composite:Multi-layer barrier structures combining aluminum foil with polymer substrates serve niche aseptic applications.
Today's leader: Aluminum. Tomorrow's challenger: Biodegradable.
Size:
Format selection tracks per-unit value capture potential and channel-specific consumption occasions across beverage categories.
- 330ml:The dominant global specification for carbonated soft drinks and standard beer serves. This dimension optimizes pallet density for intercontinental shipping while matching single-serve consumption norms in convenience retail. Brazilian and Mexican distributors specify 330ml as the baseline for direct-store-delivery networks.
- 500ml:Energy drink and premium craft beer segments drive displacement of PET bottles through tactile differentiation and higher per-unit margins. Monster Energy and Red Bull procurement contracts specify 500ml aluminum for on-premise and convenience channel placement.
- 250ml:Compact formats target airline hospitality and sample-size marketing programs.
- 1L:Family-size and sharing occasions in emerging markets where refrigeration penetration limits multi-pack storage.
Volume concentrates in 330ml. Value expansion runs through 500ml.
Closure Type:
Opening mechanism engineering balances child safety mandates, resealability premiums, and high-speed filling line compatibility.
- Pull-Tab:The industry standard for aluminum beverage cans utilizes scored metal tabs with rivet attachment. This mechanism dominates carbonated applications where single-open consumption matches product positioning. Crown Holdings and Ball Corporation have optimized pull-tab forming to 2,000+ cans per minute on integrated lines.
- Twist-Off:Threaded aluminum closures enable resealability for multi-serve occasions and higher-value beverages. European craft breweries specify twist-off for 500ml formats targeting on-premise consumption where portion control extends session length.
- Push-Pull:Simplified aperture mechanisms reduce metal content for cost-engineered steel cans.
- Spout:Directional flow designs serve sports and children's beverage categories requiring controlled consumption.
Pull-tab commands filling line economics. Twist-off captures resealability premiums.
Application:
End-use chemistry determines internal coating specifications, pressure rating requirements, and shelf-life validation protocols.
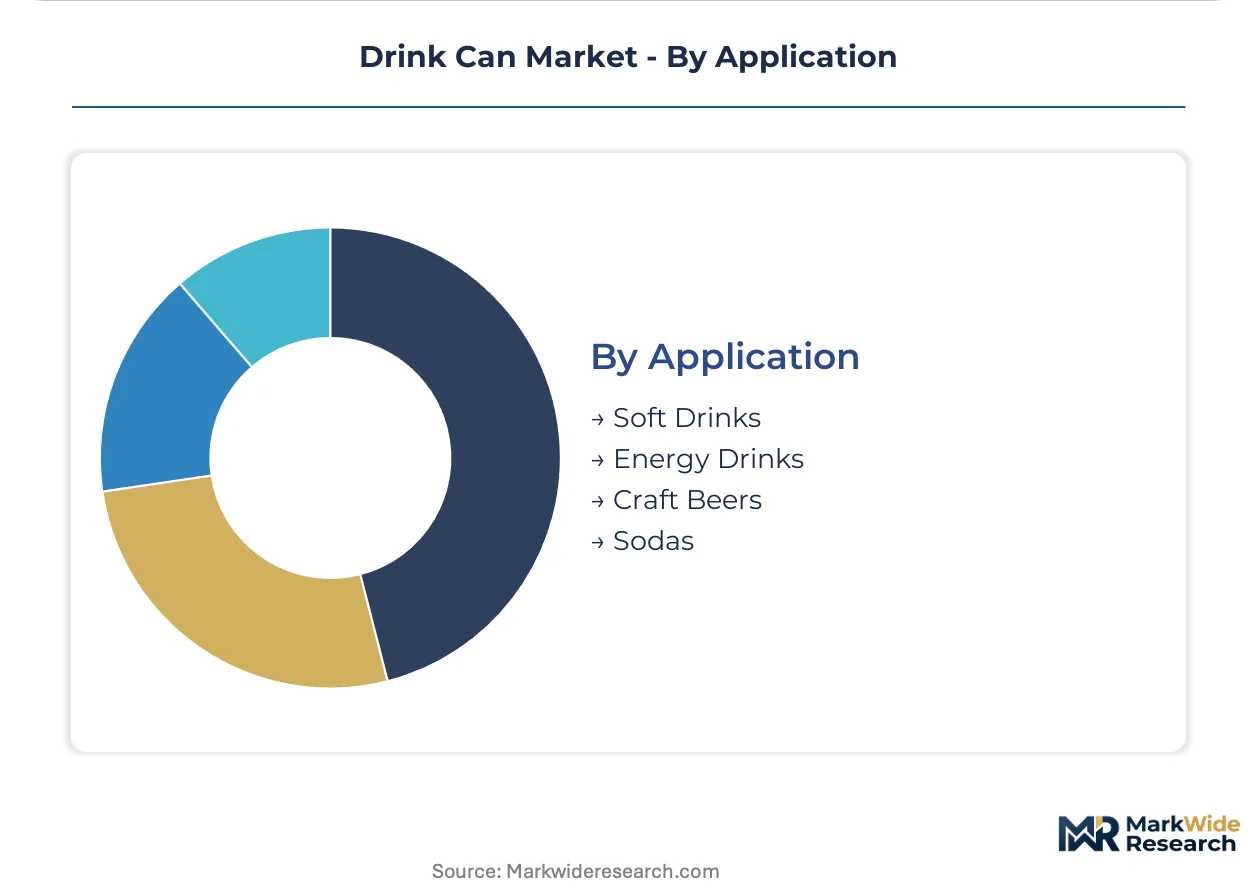
- Soft Drinks:Carbonated formulations with phosphoric or citric acid demand epoxy or polyester linings with sub-5 ppm migration limits under REACH and FDA frameworks. Coca-Cola and PepsiCo procurement specifications drive standardization across 330ml aluminum capacity globally.
- Energy Drinks:Taurine and caffeine formulations at lower pH values stress lining integrity, requiring enhanced barrier coatings. 500ml format expansion in Red Bull and Monster supply chains concentrates demand with converters certified for acidic beverage contact.
- Craft Beers:Hop compounds and dissolved CO2 create unique permeation challenges addressed through specialized vinyl or epoxy-phenolic formulations.
- Sodas:Traditional sugar-sweetened and diet variants follow soft drink coating protocols with regional taste preference variations.
Soft drinks anchor volume scale. Energy drinks drive format innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled polymer chemists and coating formulation specialists concentrate in German industrial corridors and American Midwest manufacturing belts, anchoring regional competitive advantages in regulatory-compliant can production.
United States
Craft breweries in Colorado and California drive aluminum can procurement for seasonal releases and limited-edition branding. FDA food-contact regulations govern BPA-non-intent lining qualifications for domestic and export-bound production. Chicago and Milwaukee anchor Ball Corporation and Crown Holdings manufacturing clusters serving direct-store-delivery networks.
Germany
Deposit-return system economics create closed-loop aluminum collection infrastructure that reduces virgin material exposure for converters. EU Green Deal packaging waste directives mandate minimum recycled content thresholds across beverage supply chains. Bavaria and North Rhine-Westphalia concentrate Ardagh Group specialty shaping capacity for European craft beer exporters.
Brazil
Energy drink producers and mass-market brewers expand 500ml format adoption for premium positioning in convenience channels. ANVISA governs food-contact coating migration limits for acidic and carbonated beverage categories. São Paulo and Rio de Janeiro anchor CANPACK S.A. and Crown Holdings canning capacity serving Latin American export corridors.
India
Tier-2 urbanization outpaces glass infrastructure deployment, creating packaged beverage demand in aluminum and steel formats. BIS standards regulate metal purity thresholds and coating specifications for domestic market access. Maharashtra and Gujarat concentrate tinplate steel canning capacity for price-sensitive procurement environments.
Japan
Premium beverage segments demand specialized barrier coatings for acidic formulations and extended shelf-life requirements. METI industrial standards and JIS specifications govern can manufacturing quality and recyclability protocols. Kanto and Kansai regions anchor Toyo Seikan Co., Ltd. production facilities serving domestic and regional export markets.
Drink Can Market Vendor Landscape
The competitive structure tilts toward integrated metal converters with captive recycled content sourcing and regional plant networks. Three to five multinational converters control substantial capacity share across North American, European, and Latin American corridors. Strategic archetypes separate backward-integrated scrap processors, specialty shaping specialists, and emerging-market cost leaders. Capacity expansion and qualification for ASI Chain of Custody certification represent dominant competitive moves.
Among North American integrated converters, Ball Corporation and Crown Holdings exemplify scale-driven archetypes with smelter relationships and recycled metal sourcing infrastructure. Ardagh Group S.A. occupies a positioning tier defined by specialty shaping capabilities and European regulatory compliance depth. CANPACK S.A. anchors emerging-market presence with Brazilian manufacturing concentration and Latin American distribution reach.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings, Inc. |
| Ardagh Group S.A. |
| CPMC Holdings Ltd. |
| Orora Packaging Australia Pty Ltd |
| CANPACK S.A. |
| Toyo Seikan Co., Ltd. |
| Silgan Holdings |
| Mahmood Saeed Can and End Industry Company Limited (MSCANCO) |
| Others |
Supply Flow & Price Mechanics
Digital printing adoption on aluminum substrates is compressing minimum order quantities from hundreds of thousands to tens of thousands, fragmenting volume concentration while simultaneously elevating per-unit costs for short-run craft beer batches and compressing margins for converters lacking flexible line configurations.
Pricing Analysis
Bundled coating-formulation services separate from bare metal supply dominate converter-buyer contracts. Three-tier pricing structure across premium ASI-certified, standard recycled-content, and economy virgin-aluminum tiers tracks certification grade and volume scale. Price erosion runs through economy-tier virgin aluminum as LME volatility compresses spot-contract spreads. Mass-market brewers in Brazil exhibit highest price sensitivity; European craft exporters demonstrate lowest sensitivity due to resealability premiums.
Supply Chain Analysis
EU Green Deal domestic-content mandates and India's PLI scheme for metal processing are reshaping sourcing patterns away from concentrated Chinese smelter dependence. Primary aluminum supply concentrates in Brazil, Russia, and Australia; recycled scrap processing clusters in Germany and the United States. Raw material dependencies rest on bauxite refining capacity, rolling mill availability, and polymer chemistry for BPA-non-intent linings. Single-source vulnerability in ASI-certified smelter networks poses structural risk. Distribution runs through direct-store-delivery networks in Brazil and Mexico, just-in-time regional plants in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drink can market functions as a regulatory compounder where EU Green Deal packaging waste directives and ASI Chain of Custody certification requirements are accelerating demand for compliant converter capacity.
For Market Incumbents: Cement backward integration into recycled scrap processing to secure margin resilience against virgin aluminum volatility. Expand ASI-certified capacity in Bavaria and North Rhine-Westphalia to capture European craft beer export demand. Defend against biodegradable laminate substitutes by deepening coating formulation expertise for acidic beverage barriers.
For New Entrants and Emerging Players: Launch via specialty shaping partnerships targeting 500ml energy drink formats where tactile differentiation commands premium positioning. Penetrate India's Tier-2 cities where aluminum infrastructure outpaces glass deployment. Exploit coating chemistry talent scarcity by recruiting German polymer specialists for BPA-non-intent formulation capabilities.
For Investors and Strategic Acquirers: Valuations sit cheapest among steel-can converters with Indian and African market exposure. Long-term viability hinges on circular infrastructure deployment across deposit-return system expansions. Target acquisition archetype: regional plants with sub-500km radius coverage and existing FDA or REACH qualification. Watch German and Scandinavian closed-loop collection economics as inflection signal for recycled content margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| ASI Chain of Custody Certification | Qualifies converters for EU Green Deal recycled content mandates and secures European brewer contracts. |
| Backward Integration into Scrap Processing | Ball Corporation's captive metal sourcing insulates margins from LME primary aluminum volatility. |
| Digital Printing Line Deployment | Enables short-run craft brewery customization previously uneconomical at mass-production scale. |
| Regional Plant Network Expansion | Sub-500km radius coverage matches Brazilian direct-store-delivery daily replenishment frequencies. |
| BPA-Non-Intent Coating R&D | REACH-compliant polyester and acrylic formulations extend qualification timelines but lock out non-compliant rivals. |
Methodological Framework
Bottom-up beverage end-use modeling reconciled against top-down converter capacity tracking forms the analytical core of this study. Primary interviews with coating formulation chemists, brewery procurement directors, aluminum rolling mill operators, and retail category buyers combined with secondary validation from EU Green Deal directive texts, ANVISA migration limit publications, BIS metal purity standards, and ASI certification registries. Trade flow data from customs records and beverage industry association production statistics anchored supply-side triangulation.
Historical trendline analysis of aluminum can shipments across material type, size specification, closure mechanism, and beverage application informed projection framework construction. Segmentation dimensions modeled include alloy grade tier, end-use beverage chemistry, regional regulatory cluster, and plant radius coverage category. CAGRs derived from fitted growth curves applied to base-year volume estimates, with sensitivity testing around recycled content mandate implementation pace and deposit-return system expansion timelines.
Several conditions sit outside the modeled scope, including speculative biodegradable laminate commercialization timelines and potential REACH restriction scope expansions beyond BPA. Forecasts reflect documented assumptions regarding smelter certification onboarding durations and coating reformulation qualification periods. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Global Beverage Container Market
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
Beveled Bottles Market
Beverage Packaging
Europe Beverage Packaging Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Media Bottles Market
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
Water Bottle Racks Market
Beverage Packaging
Stackable Beaker Market
Beverage Packaging
Beverage Crates Market
Beverage Packaging
Bottled Water Packaging Market
Beverage Packaging
Beverage Packaging Market
Beverage Packaging
Pre-Made Cups Market