
 Global Medical Lasers Market | 2026-2036
Global Medical Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Lasers Market Foresight
German precision optics manufacturers is consolidating supply-side capacity for solid-state laser resonators. Lumenis Ltd leverages vertically integrated diode pump sources to sustain margin control across dermatology and ophthalmology platforms. El.En. S.p.A. anchors European production of CO2 and Er:YAG systems for surgical and aesthetic applications. Candela Corporation competes through specialized distribution in North American ambulatory surgical centers.
Medical lasers are coherent light sources operating at specific wavelengths between ultraviolet and infrared spectra, typically delivering energy densities measured in joules per square centimeter for tissue ablation, coagulation, or photobiomodulation. Nd:YAG lasers penetrate deeper tissue layers with 1064 nm output for urology and oncology interventions, while Er:YAG systems at 2940 nm optimize water absorption for precise dermatological resurfacing with minimal thermal collateral damage. Diode lasers dominate volume deployment in dentistry and hair removal due to compact footprint and lower capital cost, though Alexandrite platforms command premium positioning in vascular lesion treatment where wavelength selectivity determines clinical efficacy.
FDA 510(k) clearance timelines and EU MDR technical documentation requirements shape product development cycles and market access barriers for manufacturers targeting transatlantic distribution. China's NMPA registration pathways and Japan's PMDA quality management standards add further compliance layers for companies seeking Asia-Pacific commercialization. Stakeholders must monitor evolving reimbursement codes for laser-assisted procedures across national health systems to align portfolio investments with payer-covered indications.
Market Dynamics
EU MDR technical documentation requirements and FDA 510(k) clearance pathways are compressing product development timelines while simultaneously elevating capital barriers for new entrants across ophthalmic and aesthetic laser platforms.
Growth Catalysts
- EU MDR conformity pathways:Tightened performance documentation standards for surgical laser systems are filtering out marginal manufacturers and consolidating demand around certified suppliers in German and Italian hospital procurement networks.
- China's tier-one hospital networks:Accelerated capital equipment budgets for ophthalmic and urology laser systems are pulling volume through state-owned distributor channels in Beijing, Shanghai, and Guangzhou.
- Photobiomodulation protocols:Expanding clinical evidence for low-level laser therapy in pain management and wound healing is opening reimbursement discussions with national health systems in Australia and South Korea.
Market Restraints
- Precious metal input volatility:Rhodium and palladium price swings in solid-state laser resonator coatings are compressing gross margins for diode-pumped Nd:YAG manufacturers.
- Optics supply concentration:German precision optics houses control 60-70% of solid-state laser resonator capacity, creating single-source vulnerability for mid-tier system assemblers.
- Water absorption physics:Er:YAG wavelength limitations in highly vascularized tissue restrict penetration depth, confining the technology to superficial dermatological applications despite precision advantages.
Strategic Opportunities
- Brazil's private clinic expansion:Underpenetrated ambulatory surgical centers in São Paulo and Rio de Janeiro present first-mover positioning for CO2 and diode laser platforms outside saturated North American markets.
- AI-assisted beam profiling:Convergence of machine vision with real-time tissue feedback is enabling automated parameter adjustment that reduces operator training burden in high-volume hair removal chains.
- India's PLI scheme for medical devices:Production-linked incentives for domestic laser system assembly are attracting component suppliers to establish captive diode and fiber laser module facilities near Hyderabad and Bengaluru.
Industry Challenges
- Clinical application specialist scarcity:Shortage of certified laser safety officers and tissue interaction specialists is extending training timelines for new clinic deployments in Middle Eastern markets.
- Legacy EMR integration friction:Proprietary control architectures from 1990s-era surgical laser platforms resist API connectivity with modern hospital information systems, forcing expensive middleware solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Lasers Market |
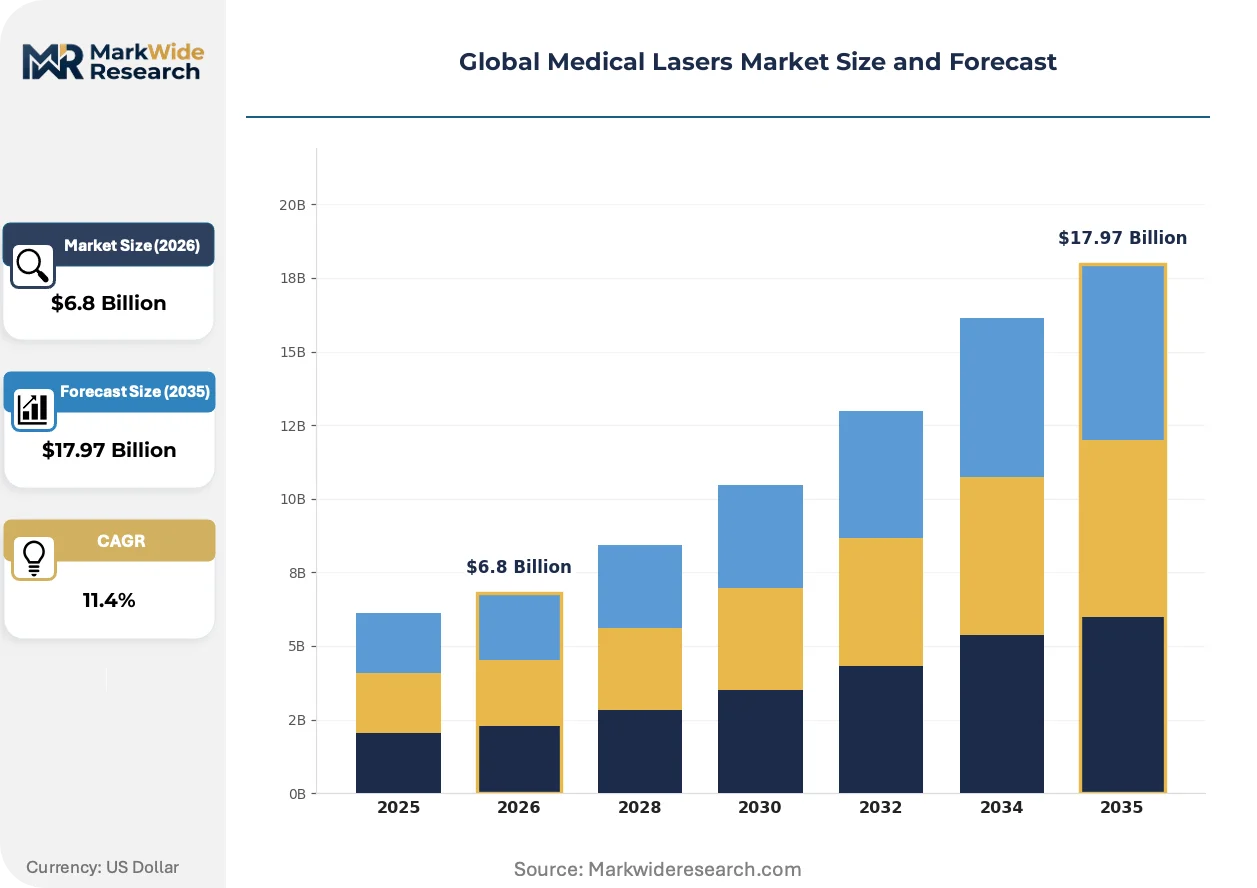
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CO2 Lasers, Diode Lasers, Er:YAG Lasers, Nd:YAG Lasers, Alexandrite Lasers Therapy Area: Ophthalmology, Dentistry, Dermatology, Urology, Oncology End User: Hospitals, Ambulatory Surgical Centers, Specialized Clinics, Diagnostic Laboratories Delivery Mode: Continuous Wave, Pulsed Wave, Q-Switched, Mode Locked |
| Companies Covered | Topcon Corporation, Sisram Medical Ltd, Lumenis Ltd, Koninklijke Philips, Boston Scientific Corporation, Bausch + Lomb, El.En. S.p.A., Candela Corporation, IRIDEX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Lasers Market Shifts & Advancements
Digital beam delivery systems and real-time tissue feedback mechanisms are displacing fixed-parameter protocols across aesthetic and surgical applications, compressing the skill gradient between novice and expert operators.
Femtosecond pulse architectures are integrating swept-source optical coherence tomography guidance to enable depth-resolved tissue targeting without mechanical contact. Aesthetic dermatology chains in South Korea and Germany are adopting these platforms at replacement cycle compression rates of 18-24 months versus historical 5-7 year equipment lifespans. The technology is integrating predictive maintenance algorithms that reduce unplanned downtime in high-throughput clinic environments.
EU MDR Article 10 technical documentation requirements now mandate clinical performance data for all Class IIb and Class III laser devices, extending pre-market preparation by 12-18 months for manufacturers without existing notified body relationships. Surgical laser vendors are responding by consolidating product portfolios around proven wavelength-platform combinations rather than pursuing novel indications. German and Italian manufacturers with established EU MDR certificates are capturing displaced demand from competitors still navigating conformity assessment gaps.
Hospital procurement committees are unbundling capital equipment purchases from mandatory service contracts, forcing laser system vendors to compete on discrete maintenance pricing rather than bundled lifecycle proposals. This disintermediation is most visible in China's provincial hospital networks where centralized government tendering platforms publish component-level pricing benchmarks. After-sales revenue compression is pushing manufacturers toward consumable-anchored business models for disposable delivery fibers and single-use handpieces.
Global Medical Lasers Market Segmentation
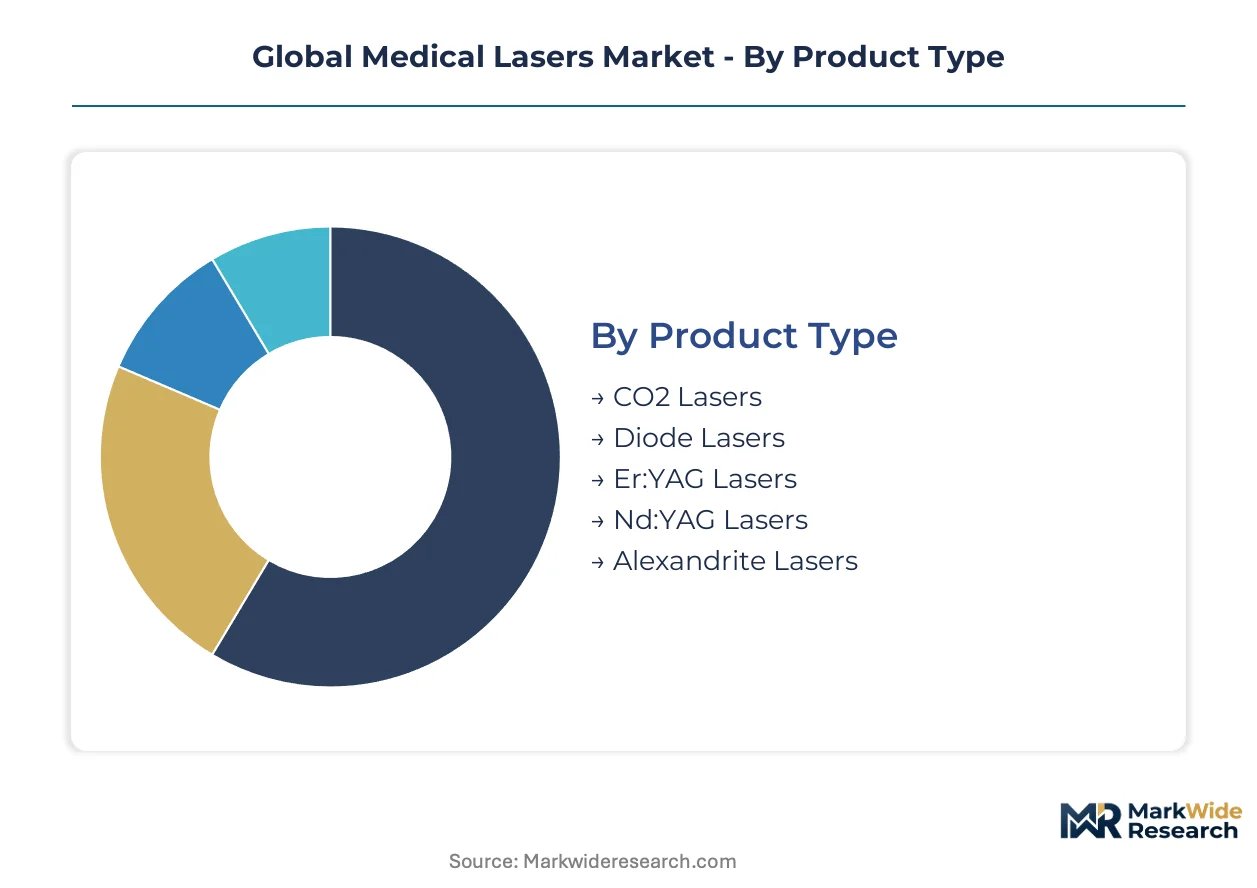
Medical laser segmentation reflects competing technical architectures and divergent clinical economics. Wavelength-platform combinations determine tissue interaction physics, while delivery mode specifications shape capital intensity and operator training requirements across surgical and aesthetic applications.
Product Type:
Wavelength output and gain medium composition define the core technology axis for system classification and procurement decisions.
- CO2 Lasers:Gas discharge systems emitting at 10600 nm deliver high-power continuous wave output for soft tissue incision and ablation. German surgical equipment manufacturers anchor supply for these platforms, with demand concentrating in hospital networks across China and Brazil where capital budgets favor versatile general surgery tools.
- Diode Lasers:Semiconductor junction devices operating between 800-980 nm dominate volume deployment through compact footprint and electrical efficiency. Hair removal chains in South Korea and dental practices across India pull volume through lower capital thresholds and reduced maintenance overhead.
- Er:YAG Lasers:Erbium-doped yttrium aluminum garnet crystals at 2940 nm optimize water absorption for precise dermatological resurfacing.
- Nd:YAG Lasers:Neodymium-doped systems at 1064 nm penetrate deeper tissue layers for urology and vascular applications.
- Alexandrite Lasers:Chromium-doped beryllium aluminate crystals at 755 nm command premium positioning for pigmented lesion treatment.
Diode lasers lead on scale through volume economics; Er:YAG systems lead on momentum through aesthetic clinic replacement cycles.
Therapy Area:
Clinical indication determines reimbursement pathways, regulatory classification, and capital equipment procurement authority.
- Ophthalmology:Femtosecond and excimer platforms for refractive correction and cataract surgery carry the highest capital intensity per procedure room. China's tier-one hospital networks in Beijing and Shanghai are accelerating procurement of these systems through centralized government tendering platforms.
- Dermatology:Aesthetic applications span resurfacing, hair removal, and vascular lesion treatment with the broadest platform diversity. South Korean clinic chains compress replacement cycles to 18-24 months as competitive positioning demands technology refresh.
- Dentistry:Soft tissue procedures and caries detection drive compact diode and Er:YAG deployment in ambulatory settings.
- Urology:Stone fragmentation and benign prostatic hyperplasia treatment anchor Nd:YAG and holmium laser demand.
- Oncology:Photodynamic therapy and tumor ablation represent emerging applications with evolving reimbursement codes.
Dermatology leads on scale through aesthetic volume; ophthalmology leads on momentum through precision technology adoption.
End User:
Facility type shapes procurement authority, service contract expectations, and regulatory compliance burden.
- Hospitals:Integrated health systems with centralized capital committees and mandatory preventive maintenance contracts. German and Italian hospital procurement networks are consolidating supplier relationships around EU MDR-certified manufacturers.
- Ambulatory Surgical Centers:Physician-owned facilities with unbundled purchasing authority and compressed equipment lifespans. North American ASCs in Texas and Florida favor lease structures over capital acquisition for aesthetic platforms.
- Specialized Clinics:Single-discipline practices with direct consumer payment models and rapid technology refresh cycles.
- Diagnostic Laboratories:Pathology and research applications with lower volume but higher specification requirements.
Hospitals lead on scale through capital concentration; ambulatory surgical centers lead on momentum through purchasing flexibility.
Delivery Mode:
Temporal energy distribution determines thermal tissue interaction and clinical application range.
- Continuous Wave:Steady-state output enables rapid tissue cutting with predictable thermal zones. CO2 surgical platforms in general hospital settings deploy this architecture for incision efficiency.
- Pulsed Wave:Discrete energy packets reduce thermal diffusion for selective photothermolysis. Hair removal and vascular applications favor this mode for epidermal protection.
- Q-Switched:Nanosecond pulse compression delivers peak power for pigment fragmentation. Tattoo removal and melasma treatment in aesthetic clinics require this specification.
- Mode Locked:Femtosecond pulse trains enable nonlinear tissue interaction without thermal damage. Ophthalmic applications in premium refractive surgery centers are climbing the fastest for this technology.
Continuous wave leads on scale through surgical versatility; mode locked leads on momentum through precision ophthalmology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting manufacturing investment toward jurisdictions with streamlined conformity pathways. EU MDR compliance timelines and FDA 510(k) review durations now factor heavily in site selection for laser system assembly and component sourcing.
United States
FDA 510(k) clearance pathways shape product development cycles for ophthalmic and surgical laser platforms. The agency's tightened documentation standards for Class IIb devices extend pre-market preparation timelines. Texas and Florida ambulatory surgical centers favor lease structures over capital acquisition for aesthetic systems.
Germany
EU MDR Article 10 technical documentation requirements filter demand toward certified suppliers in hospital procurement networks. German precision optics manufacturers control solid-state laser resonator capacity, creating supply concentration. Bavarian and Baden-Württemberg industrial clusters anchor European production of CO2 and Er:YAG surgical systems.
China
NMPA registration pathways add compliance layers for ophthalmic and urology laser commercialization. State-owned distributor channels in Beijing, Shanghai, and Guangzhou pull volume through accelerated capital equipment budgets. Tier-one hospital networks dominate procurement authority for femtosecond and excimer platforms.
South Korea
MFDS quality management standards govern aesthetic laser platform approvals for dermatology clinic chains. Photobiomodulation protocols for pain management are opening reimbursement discussions with the national health system. Seoul metropolitan aesthetic chains compress replacement cycles to 18-24 months through competitive technology refresh demands.
Brazil
ANVISA regulatory pathways for Class III medical devices structure market access for imported laser systems. Underpenetrated ambulatory surgical centers in São Paulo and Rio de Janeiro present positioning opportunities outside saturated North American markets. Private clinic expansion drives demand for versatile CO2 and diode laser platforms.
Global Medical Lasers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized wavelength niches and regional service contracts. The vendor base stratifies across integrated multinationals with captive optics supply, mid-tier system assemblers dependent on German resonator sourcing, and regional distributors with localized regulatory expertise. Three archetypes dominate: vertically integrated wavelength-platform owners, component-specialist assemblers, and geography-anchored service providers. Competitive moves concentrate on EU MDR certificate acquisition and unbundled maintenance pricing to capture hospital procurement committee preference.
Within the integrated-system tier, Lumenis Ltd and El.En. S.p.A. exemplify wavelength-platform consolidation strategies, while Candela Corporation occupies a position in specialized North American distribution. These entities represent contrasting approaches to margin control—captive component supply versus geographic concentration.
| Leading Market Players |
|---|
| Topcon Corporation |
| Sisram Medical Ltd |
| Lumenis Ltd |
| Koninklijke Philips |
| Boston Scientific Corporation |
| Bausch + Lomb |
| El.En. S.p.A. |
| Candela Corporation |
| IRIDEX Corporation |
| Others |
Supply & Pricing Matrix
Femtosecond pulse architecture adoption is compressing equipment replacement cycles to 18-24 months in South Korean and German aesthetic chains, simultaneously elevating capital intensity for clinics and concentrating procurement power around multi-system vendors with captive service networks. This technology transition rewards manufacturers with backward-integrated resonator production and punishes assemblers dependent on external optics sourcing.
Pricing Analysis
Distributor margins in China's state-owned procurement channels absorb 15-25 points of system value, forcing manufacturers to compete on net-back pricing or pursue direct hospital relationships. Pricing stratifies across premium femtosecond ophthalmic platforms, standard diode dermatology systems, and economy-tier CO2 surgical units, with differentiation anchored in FDA 510(k) clearance tier and EU MDR certificate status. Cost compression in the standard tier is intensifying because mid-tier assemblers lack captive resonator supply and face rhodium price volatility in coating inputs. Ambulatory surgical centers in Texas and Florida exhibit highest price sensitivity, while tier-one hospital networks in Beijing and Shanghai prioritize specification compliance over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shenzhen, and Seoul anchor hub-and-spoke patterns for solid-state laser component flows, with final system assembly clustering near precision optics manufacturing in Bavaria and Baden-Württemberg. German and Italian producers control 60-70% of solid-state resonator capacity, while Chinese diode module foundries feed downstream assemblers across India and Brazil. Single-source vulnerability concentrates in germanium substrate supply for CO2 laser optics and rare-earth doping materials for YAG crystals. Distribution runs through authorized service partners with mandatory preventive maintenance contracts in hospital networks, shifting to unbundled component pricing in ambulatory settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
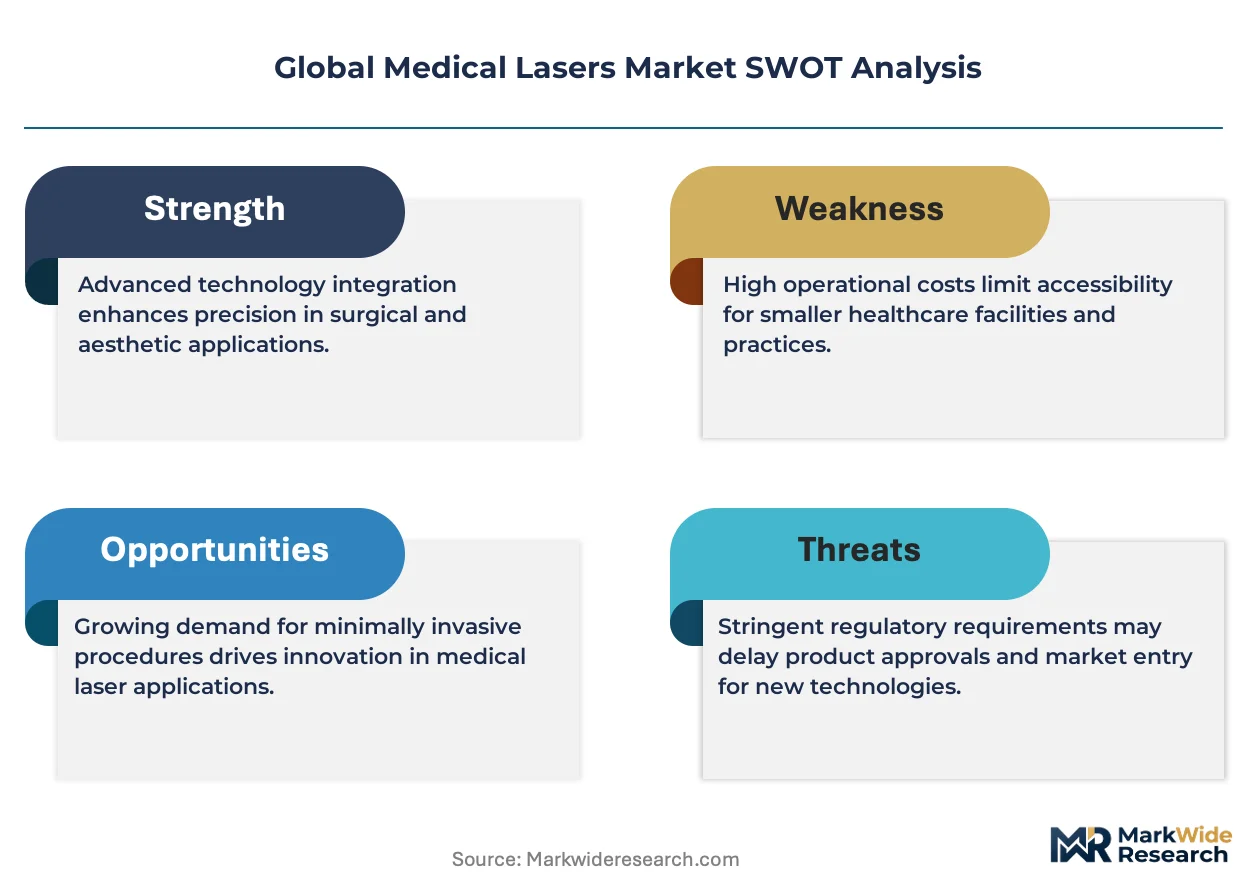
The Global Medical Lasers Market functions as a stable compounder, with recurring revenue from consumable handpieces and service contracts providing cash flow visibility that offsets capital equipment cyclicality. Regulatory certificate scarcity in EU MDR and FDA pathways creates durable competitive moats for incumbent suppliers.
For Market Incumbents: Deploy backward integration into diode pump source manufacturing to defend margin compression from precious metal volatility in resonator coatings. Consolidate product portfolios around proven wavelength-platform combinations with existing EU MDR certificates rather than pursuing novel indications that extend pre-market timelines. Lock in multi-year service contracts with China's tier-one hospital networks before procurement committees complete their shift to unbundled maintenance pricing. For New Entrants and Emerging Players: Capture white-space positioning in Brazil's underpenetrated ambulatory surgical centers in São Paulo and Rio de Janeiro, where ANVISA regulatory pathways remain less congested than FDA or EU MDR channels. Target India's PLI scheme for domestic laser system assembly, establishing captive diode and fiber laser module facilities near Hyderabad and Bengaluru to serve price-sensitive dental and hair removal markets. Lead with AI-assisted beam profiling as a training-reduction value proposition for high-volume clinic chains. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier system assemblers with established EU MDR certificates because certificate scarcity creates acquisition currency for consolidating displaced demand from non-compliant competitors. Platform-rollup strategies reward buyers who can cross-sell consumable handpieces across acquired installed bases. Watch for inflection in China's provincial tendering platforms publishing component-level pricing benchmarks, which signals completion of the shift from bundled to unbundled procurement and compresses after-sales revenue pools.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certificate Acquisition | Filters hospital procurement demand toward certified suppliers in German and Italian networks. |
| Backward Integration into Resonator Production | Insulates margin from germanium substrate and rare-earth doping price volatility. |
| AI-Assisted Beam Profiling Development | Reduces operator training burden and expands addressable clinic operator pool. |
| Unbundled Maintenance Pricing Transition | Captures procurement committee preference in China's centralized tendering platforms. |
| India PLI Scheme Manufacturing Footprint | Positions for cost-competitive supply to price-sensitive dental and dermatology markets. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers, GPO contracts specialists, and laser safety officers grounded qualitative findings in operational reality across German, Chinese, and South Korean healthcare systems. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body certificates, NMPA registration filings, and hospital capital equipment tender records. Bottom-up system shipment estimates triangulated against top-down healthcare expenditure allocations for laser-assisted procedures.
Segment-level value and volume trajectories across the projection horizon reflect modeled interactions between wavelength-platform replacement cycles, reimbursement code expansions, and regulatory certificate issuance rates. The analytical framework incorporated therapy area splits, end-user facility types, and delivery mode specifications alongside geographic procurement authority concentrations. CAGRs derived from fitted S-curve adoption patterns for femtosecond and diode platforms, calibrated to historical equipment lifespan compression observed in South Korean clinic chains.
Underlying measurement precision varies by segment; ophthalmology and dermatology platform data carry tighter precision than emerging oncology applications with evolving reimbursement codes. Forecasts reflect documented assumptions regarding EU MDR certificate issuance velocity, China's provincial tendering platform maturation, and rhodium price trajectory stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Equine Operating Tables Market
Medical Equipment
Global Kidney Dialysis Equipment and Supplies Market
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
China Radiotherapy Market
Medical Equipment
New-Born Screening Equipment Market
Medical Equipment
Hybrid Operating Room Market
Medical Equipment
X-Ray Machine Manufacturing Market
Medical Equipment
Cryochambers Market
Medical Equipment
Medical Linear Accelerators (MLA) Market
Medical Equipment
Ultrasound Equipment Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
Medical Computer Carts Market
Medical Equipment
MRI Transport Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Single-Coated Medical Tape Market
Medical Equipment
Clinical Microscopes Market