
 Japan Hair Transplant Market | 2026-2036
Japan Hair Transplant Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Hair Transplant Market Insights
Younger male professionals is unwinding the historical dominance of middle-aged patients in Japan's hair transplant demand. Shinwa Clinic leverages its Tokyo location to anchor premium FUE services for domestic executives. Aderans sustains brand recognition through decades of scalp-care retail presence that feeds transplant referrals. Arts Ginza Clinic differentiates via concierge recovery programs targeting high-net-worth clientele from central Tokyo wards.
A hair transplant relocates follicular units from donor scalp zones to thinning recipient areas, typically involving extraction densities of 30–50 grafts per square centimeter to achieve natural hairline restoration. FUE procedures lead Japan's procedural mix due to minimal scarring that aligns with cultural preferences for discreet aesthetic interventions. Automated systems within the technology dimension represent the fastest-growing segment as robotic graft harvesting reduces technician fatigue and improves follicle survival rates during lengthy sessions. Platelet-Rich Plasma adjunct therapy commands premium positioning in recovery options, with Tokyo clinics bundling it into post-procedure protocols to accelerate healing and graft retention.
PMDA oversight of cell-processing facilities governs clinics offering stem-cell-enhanced transplants, while METI monitors advertising claims under Japan's Act against Unjustifiable Premiums and Misleading Representations. JIS standards for medical device sterilization further constrain equipment sourcing, pushing independent clinics toward certified Japanese distributors rather than direct overseas procurement. Stakeholders must track how PMDA's evolving regenerative-medicine framework will classify autologous cell therapies, as reclassification could reshape which procedures require facility licensing versus standard clinic registration.
Market Dynamics
Robotic graft harvesting systems are compressing session times and technician labor intensity across Japanese hair transplant clinics. METI's advertising restrictions on regenerative medicine outcomes are forcing clinics to restructure patient communication protocols. These dual pressures are redrawing competitive boundaries between high-automation chains and traditional manual practices.
Growth Catalysts
- Regulatory clarity on autologous cell therapies:PMDA's evolving framework for regenerative medicine is reducing uncertainty for clinics investing in stem-cell-enhanced procedures. Facility licensing pathways are stabilizing.
- Medical tourism infrastructure:Kanto region's concentration of international hotels and translation services is attracting Southeast Asian patients seeking discreet aesthetic interventions.
- FUE technology maturation:Automated extraction systems are reducing follicle transection rates below manual benchmarks. Tokyo clinics are upgrading equipment fleets.
Market Restraints
- Input cost concentration:JIS-certified sterilization equipment must route through approved Japanese distributors. Direct overseas procurement is blocked.
- Technical ceiling on donor supply:Finite occipital scalp density limits graft yields per session. Patients with advanced Norwood patterns face incomplete coverage.
- Regulatory friction from METI advertising rules:Before-and-after imagery restrictions constrain visual marketing. Clinics rely on word-of-mouth referral networks.
Strategic Opportunities
- Underpenetrated regional markets:Kyushu and Hokkaido lack specialized hair transplant density. Osaka-based chains are scouting Fukuoka expansion sites.
- Adjunct therapy bundling:Platelet-Rich Plasma protocols are creating recurring revenue streams. Post-procedure maintenance packages extend patient lifetime value.
- Technology convergence of robotics and imaging:AI-assisted graft placement mapping is improving hairline design precision. Early adopters are differentiating on outcome predictability.
Industry Challenges
- Certification timeline compression:PMDA facility inspections for cell-processing capabilities average fourteen months. Clinic expansion plans face regulatory lag.
- Technician skill scarcity:Robotic systems still require manual oversight for graft quality verification. Training pipelines for hybrid operator competencies are underdeveloped.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Hair Transplant Market |
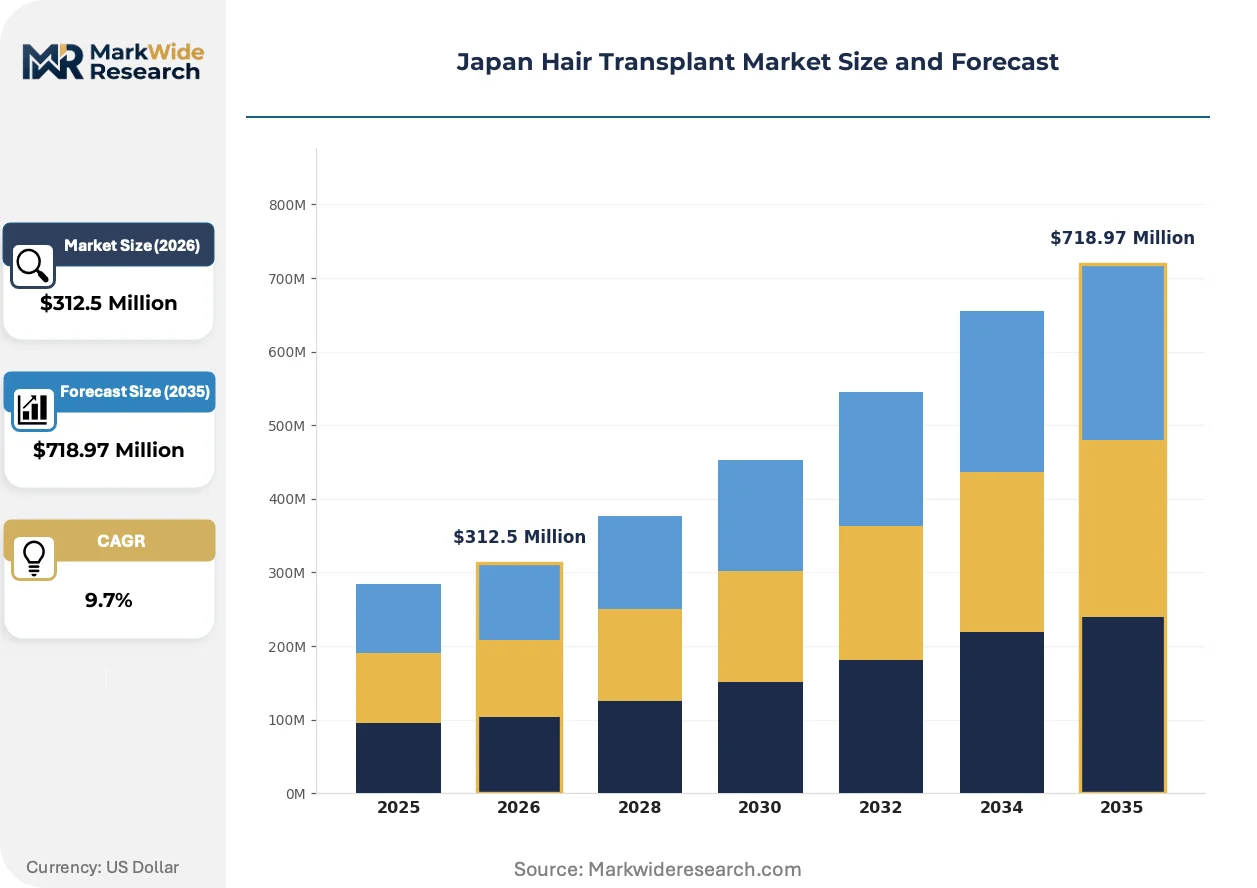
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $718.97 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: FUE, FUT, Robotic Hair Restoration, Scalp Micropigmentation Client Type: Men, Women, Clinics, Hospitals Technology: Manual Extraction, Automated Systems, Platelet-Rich Plasma, Laser Therapy Recovery Option: Post-Procedure Care, Massage Therapy, Nutritional Supplements, Topical Treatments |
| Companies Covered | Shinwa Clinic, Tokyo Hair Clinic, Clinique Haru, Aderans, Nagai Hair Restoration Academy, Arts Ginza Clinic, Nido Clinic, Clinic Japan, Yokobi Clinic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Hair Transplant Market Trends and Innovations
Automation is redefining labor allocation and session economics across Japanese transplant clinics. Three developments are compressing the gap between high-volume chains and boutique operators.
Robotic follicular unit extraction systems are displacing manual punch techniques in premium Tokyo clinics. Shinwa Clinic and Arts Ginza have deployed automated harvesters for sessions exceeding two thousand grafts. The technology is displacing overnight technician teams and enabling next-day patient discharge protocols.
METI's 2023 guidance on regenerative medicine advertising is tightening visual claim standards for before-and-after photography. Clinics must submit outcome documentation to independent review panels. Aesthetic dermatology chains are responding by shifting marketing spend toward physician credentialing and facility accreditation displays.
Younger male professionals in Tokyo's financial and technology sectors are compressing decision timelines for hairline restoration. Traditional consultation-to-procedure intervals of ninety days are collapsing to fourteen days through digital booking platforms. This behavioral shift is most visible in Minato and Shibuya wards where discretionary income concentration supports premium positioning.
Japan Hair Transplant Market Segmentation
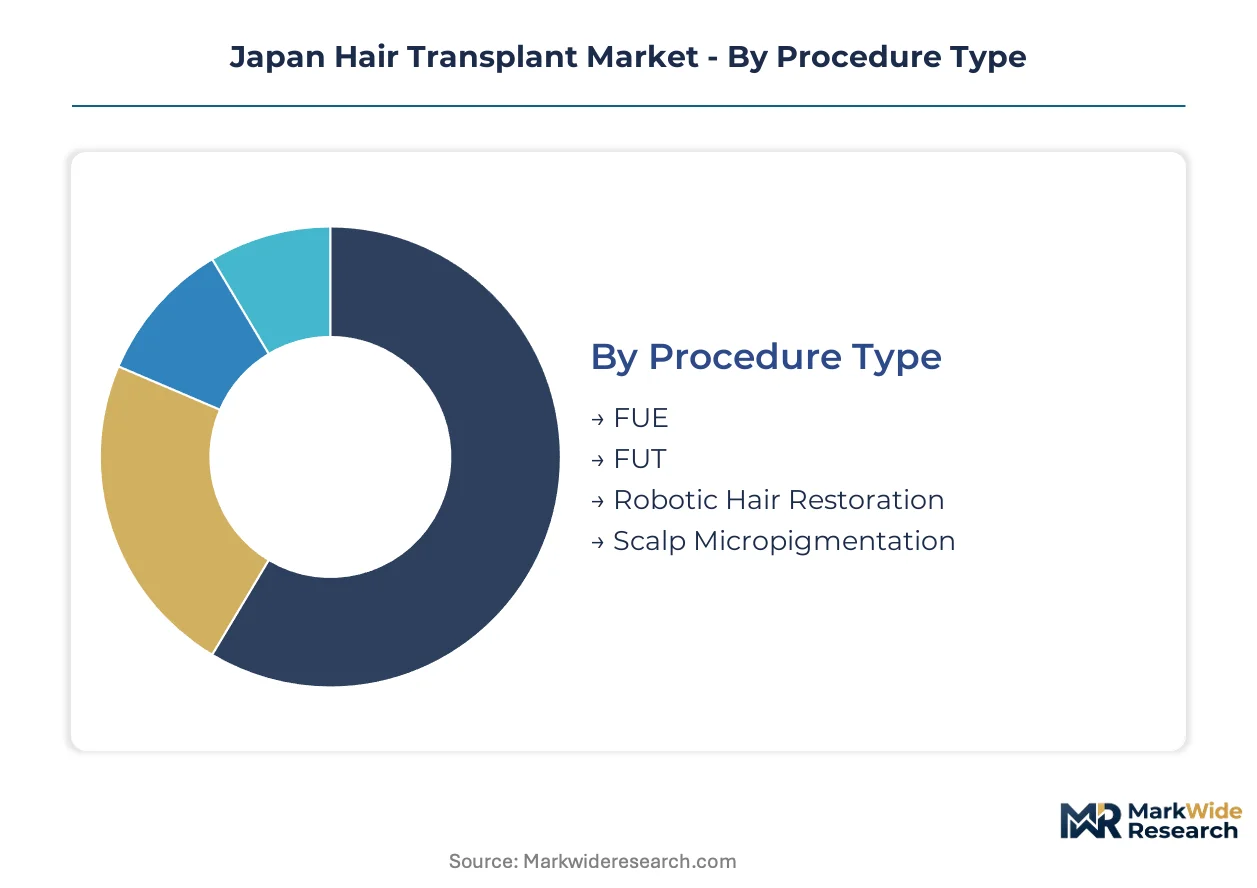
Japan's hair transplant market segments along procedural, technological, and service dimensions that reflect distinct margin structures. Each category reveals where clinics capture premium pricing versus where volume competition intensifies.
Procedure Type:
FUE commands the widest margin spread between premium Tokyo clinics and regional competitors, while robotic systems concentrate investment returns in high-volume operators.
- FUE:Follicular unit extraction harvests individual grafts via micro-punch tools, leaving pin-dot scars that satisfy Japanese cultural preferences for discretion. Tokyo's Minato and Shibuya wards concentrate demand from finance and technology professionals seeking minimal downtime.
- FUT:Follicular unit transplantation removes a donor strip for dissection into grafts, enabling higher graft yields per session but producing linear scarring. Demand concentrates among patients with advanced Norwood patterns requiring maximum coverage in single sessions.
- Robotic Hair Restoration:Automated extraction and placement systems reduce technician labor intensity. METI medical device regulations govern import pathways for these capital-intensive platforms.
- Scalp Micropigmentation:Cosmetic tattooing simulates hair density without surgical intervention. Lower price points attract younger clients delaying surgical commitment.
The dominant share belongs to FUE, while robotic systems are gaining share fastest among premium clinic chains.
Client Type:
Volume distribution across client categories tracks Japan's demographic and institutional healthcare patterns, with working-age males driving procedural throughput.
- Men:Working-age professionals in Tokyo and Osaka generate the majority of procedural volume. Corporate grooming standards and discretionary income concentration in Kanto fuel consistent demand.
- Women:Female patients seek eyebrow reconstruction and diffuse thinning correction. Marketing restrictions under METI guidelines complicate outreach to this segment.
- Clinics:Specialized aesthetic dermatology chains absorb technology investments and amortize equipment across high session volumes. PMDA facility licensing requirements favor established operators.
- Hospitals:General medical institutions offer transplant services as adjunct to dermatology departments. Lower marketing flexibility constrains patient acquisition relative to dedicated clinics.
Men retain the dominant patient share, though women are expanding fastest as social stigma around female hair loss diminishes in urban centers.
Technology:
Technology selection determines capital intensity and technician skill requirements, with automated platforms reshaping session economics.
- Automated Systems:Robotic harvesters and motorized punches reduce follicle transection rates below manual benchmarks. Tokyo clinics lead deployment due to capital access and session volume justification.
- Manual Extraction:Hand-controlled punch tools remain prevalent in regional markets where equipment investment is prohibitive. Technician skill variance produces wider outcome quality dispersion.
- Platelet-Rich Plasma:Autologous blood concentrate injections accelerate graft healing and retention. Bundling into post-procedure protocols generates recurring revenue streams.
- Laser Therapy:Low-level light devices stimulate follicular activity as non-surgical maintenance. Home-use device competition constrains clinic-based service pricing.
Manual extraction holds dominant installed base, yet automated systems show the steepest expansion trajectory as labor costs rise.
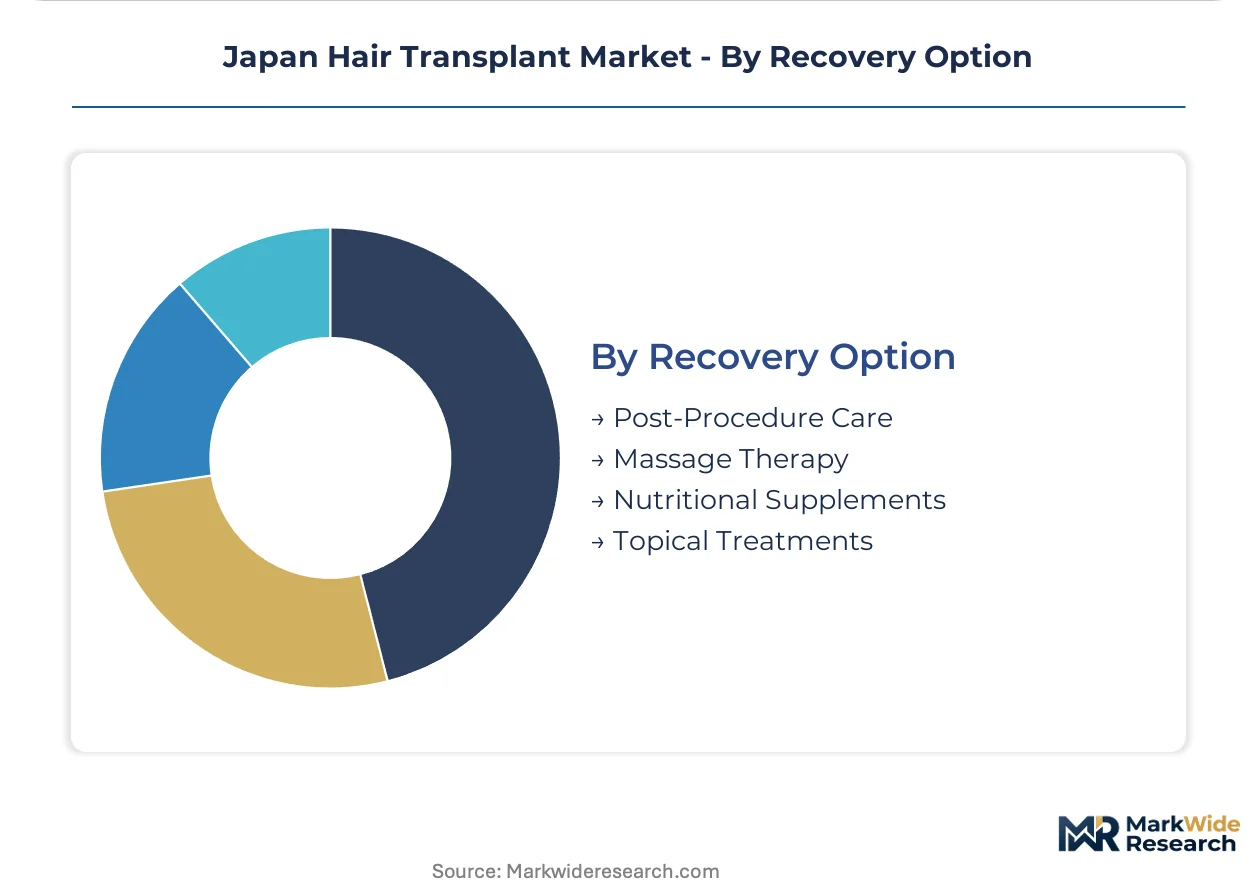
Recovery Option:
Post-procedure service bundling extends patient lifetime value and differentiates premium positioning.
- Post-Procedure Care:Structured follow-up protocols including wound monitoring and graft survival assessment. Kanto region clinics package these into all-inclusive pricing tiers.
- Massage Therapy:Scalp circulation treatments promote graft vascularization. Demand concentrates among patients prioritizing recovery speed over cost minimization.
- Nutritional Supplements:Oral formulations targeting hair growth factors. METI advertising rules restrict efficacy claims, pushing marketing toward ingredient transparency.
- Topical Treatments:Minoxidil and peptide-based applications support graft retention. Patient compliance challenges limit standalone revenue contribution.
Post-procedure care captures dominant share of recovery-related spending, with nutritional supplements climbing fastest as wellness positioning gains traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese hair transplant services flow domestically from Kanto metropolitan centers to regional prefectures lacking specialized infrastructure, while medical tourism channels bring Southeast Asian patients into Tokyo and Osaka clinics.
Kanto/Tokyo
Finance and technology professionals in Minato and Shibuya wards drive procedural volume through compressed booking timelines. METI advertising guidelines on regenerative medicine outcomes force clinics toward physician credentialing displays rather than visual marketing. Shinwa Clinic anchors premium FUE services for domestic executives from its Tokyo base.
Kansai/Osaka
Working-age male professionals in Osaka's corporate districts generate expanding demand for discreet aesthetic interventions. PMDA facility licensing requirements favor established operators with capital for fourteen-month inspection timelines. Regional chains scout Fukuoka expansion sites from Osaka headquarters to capture Kyushu underpenetration.
Chubu/Nagoya
Automotive sector professionals in Aichi Prefecture contribute steady procedural demand alongside manufacturing wages. JIS standards for medical device sterilization constrain equipment sourcing through approved Japanese distributors. Clinic density remains below Kanto levels, creating whitespace for technology-forward entrants.
Kyushu
Fukuoka's emerging medical tourism infrastructure attracts domestic patients seeking alternatives to metropolitan pricing. METI monitors advertising claims under Japan's Act against Unjustifiable Premiums and Misleading Representations across regional markets. Specialized hair transplant density lags national averages, prompting Osaka-based chain interest.
Hokkaido
Sapporo's isolated geography limits patient access to premium robotic systems concentrated in southern prefectures. PMDA oversight of cell-processing facilities governs clinics offering stem-cell-enhanced transplants regardless of location. Cold climate recovery protocols differentiate local post-procedure care offerings from standard Kanto packages.
Japan Hair Transplant Market Competitive Landscape
Player mix skews toward specialized aesthetic dermatology chains with PMDA facility licensing advantages over general hospital dermatology departments. Market structure concentrates investment returns in high-volume Tokyo operators capable of amortizing robotic equipment across dense session schedules. Two strategic archetypes dominate: premium concierge clinics targeting Minato ward executives, and technology-forward chains deploying automated extraction systems. Competitive moves center on equipment fleet upgrades and regional expansion licensing.
Among Tokyo-based specialized operators, Shinwa Clinic, Arts Ginza Clinic, and Aderans occupy distinct positioning vectors. Shinwa Clinic exemplifies the premium-tier archetype through its metropolitan location and executive clientele focus. Arts Ginza Clinic represents concierge recovery program differentiation for high-net-worth patients from central Tokyo wards. Aderans anchors brand recognition through decades of scalp-care retail presence that feeds transplant referral pipelines. These three operators illustrate how geographic concentration, service bundling, and historical market presence create defensible positioning against regional entrants.
| Leading Market Players |
|---|
| Shinwa Clinic |
| Tokyo Hair Clinic |
| Clinique Haru |
| Aderans |
| Nagai Hair Restoration Academy |
| Arts Ginza Clinic |
| Nido Clinic |
| Clinic Japan |
| Yokobi Clinic |
| Others |
Pricing and Supply Chain Analysis
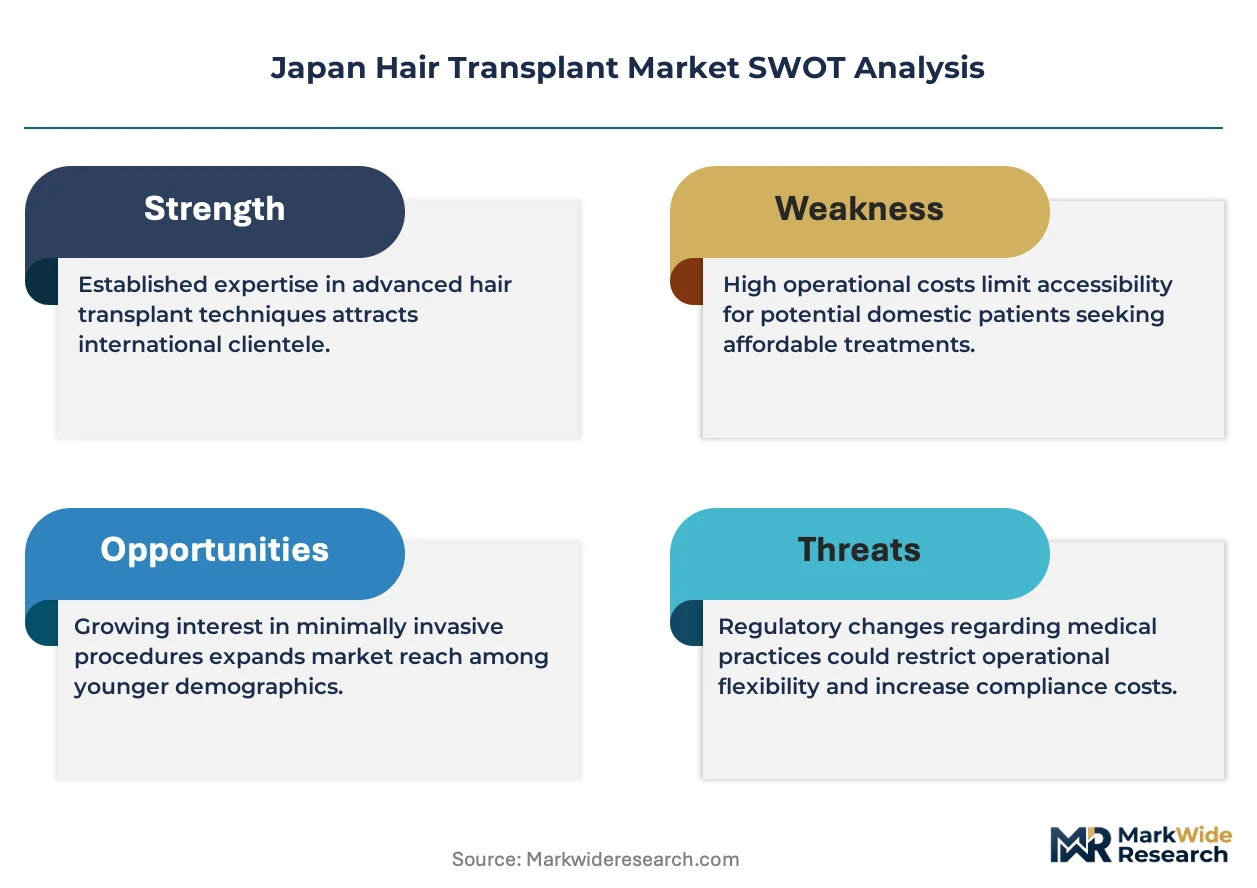
JIS certification requirements for medical device sterilization simultaneously gate equipment qualification and stratify clinic pricing tiers across Japan's hair transplant market. METI oversight of regenerative medicine advertising further segments service positioning by constraining how outcomes can be communicated to prospective patients.
Pricing Analysis
Robotic follicular unit extraction systems command premium positioning against manual punch techniques and emerging AI-assisted placement platforms. Three-tier pricing structure across premium, standard, and economy levels separates Tokyo's Minato ward concierge clinics from Osaka-based regional chains and Hokkaido's manual-technique operators. Cost compression in the standard tier intensifies as equipment leasing spreads automation access beyond capital-rich metropolitan incumbents. Corporate executives in Tokyo's financial districts exhibit lowest price sensitivity, while younger professionals in Kyushu regional markets prioritize cost minimization over technology generation.
Supply Chain Analysis
Just-in-time procurement dominates equipment and consumables flows among Tokyo's high-volume clinic chains, though PMDA facility licensing timelines force strategic stockpiling of JIS-certified sterilization hardware. Robotic harvester assemblies draw from Japanese domestic precision manufacturers, German optical component suppliers, and South Korean motor control systems. Single-source vulnerability concentrates in JIS-approved distributor networks that block direct overseas procurement of capital equipment. Distribution runs through certified medical device wholesalers to clinic operators, with aftermarket service contracts extending equipment vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as younger male professionals compress decision timelines and disperse demand across boutique concierge services, technology-forward automation chains, and regional manual-technique clinics.
For Market Incumbents: Compound automation advantages by deploying second-generation robotic systems before fourteen-month PMDA facility inspections complete for regional competitors. Vertical integration into in-house technician training pipelines addresses hybrid operator scarcity threatening session quality. Defend against Osaka-based chains scouting Fukuoka expansion by securing exclusive JIS distributor relationships in Kyushu prefectures. For New Entrants and Emerging Players: Differentiate on concierge recovery programming for high-net-worth patients in central Tokyo wards underserved by volume-focused automation chains. Target Sapporo's isolated geography where robotic system penetration lags Kanto benchmarks by exploiting cold-climate recovery protocol specialization. Pursue direct-to-patient digital booking platforms that collapse consultation-to-procedure intervals from traditional ninety-day cycles. For Investors and Strategic Acquirers: PMDA's evolving autologous cell therapy classification reshapes the acquisition landscape by separating facility-licensed operators from standard clinic registrants. Five-to-ten-year viability favors technology-forward chains with amortized robotic fleets over manual-technique regional players facing labor cost escalation. Signal to monitor: METI advertising guidance enforcement intensity against before-and-after imagery restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Equipment Fleet Upgrade | Automated harvesters reduce technician fatigue and improve follicle survival rates during extended sessions. |
| PMDA Facility Licensing Investment | Fourteen-month inspection timelines favor capitalized incumbents seeking stem-cell-enhanced procedure authorization. |
| Regional Expansion to Kyushu | Fukuoka's underpenetrated market offers whitespace for Osaka-based chains with proven automation economics. |
| Concierge Recovery Program Development | Post-procedure bundling extends patient lifetime value among Minato ward executive clientele. |
| Digital Booking Platform Deployment | Compression of consultation-to-procedure intervals captures younger professionals with compressed decision timelines. |
Research Methodology
Desk research of PMDA regulatory filings, METI advertising guidance documents, and JIS medical device standards preceded structured interviews with clinic operators, robotic equipment distributors, and regenerative medicine facility inspectors. Primary fieldwork with Tokyo-based aesthetic dermatology chains and Osaka regional expansion planners combined with secondary validation against hospital procurement databases and medical tourism infrastructure assessments. Bottom-up session volume estimates from clinic operators triangulated against top-down market sizing from equipment import records.
Variance decomposition across the projection horizon isolates technology adoption curves, regulatory timeline uncertainties, and regional penetration rate differentials. Segmentation dimensions modeled include procedure type, client category, technology generation, and recovery service bundling. CAGRs derive from equipment deployment trajectories and demographic demand shifts without reliance on single-source projections. Forecast inputs incorporate PMDA licensing completion rates and METI enforcement intensity patterns specific to regenerative medicine advertising.
Decision-makers should treat outputs as directional under stable PMDA classification assumptions for autologous cell therapies; material deviation would warrant model refresh. Forecasts reflect assumptions regarding fourteen-month facility inspection timelines and JIS distributor network stability. Revision becomes warranted when robotic equipment import volumes cross thresholds indicating accelerated automation adoption beyond baseline scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
China Laser Hair Removal Market
Medical Aesthetics
Laser Hair Removal Market
Medical Aesthetics
North America Dermal Fillers Market
Medical Aesthetics
Germany Hair Transplant Market
Medical Aesthetics
France Hair Transplant Market
Medical Aesthetics
North America Laser Tattoo and Striae Removal Market
Medical Aesthetics
Europe Medical Aesthetic Devices Market
Medical Aesthetics
Lip Augmentation Market
Medical Aesthetics
Breast Reconstruction and Augmentation Market
Medical Aesthetics
Cosmetic Laser Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market
Medical Aesthetics
Japan Laser Hair Removal Market
Medical Aesthetics
Scar Revision Market
Medical Aesthetics
Korea Medical Aesthetics Market
Medical Aesthetics
Non-Surgical Rhinoplasty Market