
 Global Single-Arm Medical Pendant Market | 2026-2036
Global Single-Arm Medical Pendant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Single-Arm Medical Pendant Market Foresight
Aftermarket service revenue is tilting toward preventive maintenance contracts and recertification programs as hospitals extend equipment life cycles. Drägerwerk AG & Co. KGaA leverages its integrated service network across European tertiary centers to capture recurring revenue streams. STERIS plc anchors its position through R&D intensity focused on infection control integration within pendant architectures. BeaconMedaes competes aggressively on channel control, sustaining direct hospital relationships that bypass distributor markups.
A single-arm medical pendant is a ceiling-suspended or wall-fixed articulating boom system, typically fabricated from aluminum extrusions with sealed bearing joints, designed to route medical gases, electrical power, and data cables to clinical workstations while maintaining a 180- to 340-degree rotation envelope. Its primary purpose is to eliminate floor-based clutter in critical care zones and position life-support utilities within ergonomic reach of surgical teams. Ceiling-mounted configurations dominate current installations due to structural load-bearing capacity and spatial efficiency in hybrid operating rooms. LED lighting and gas management subsystems within the technology stack carry disproportionate margin pools because hospitals prioritize illumination quality and anesthetic gas scavenging precision. Mobile variants represent the fastest-growing product type as ambulatory surgery centers demand reconfigurable layouts without permanent infrastructure investment.
The FDA enforces electrical safety standards under 21 CFR 880.6180 for medical pendant systems marketed in the United States, while the EU Medical Device Regulation mandates CE marking with enhanced clinical evidence requirements for Class IIa devices. BIS certification in India and NMPA registration in China create parallel compliance pathways that shape product localization strategies for multinational suppliers. Stakeholders must monitor how evolving cybersecurity frameworks for networked control systems will reshape data connectivity module specifications and hospital procurement criteria.
Market Dynamics
Hybrid operating room construction in Germany and the United States is compressing installation timelines and forcing pendant manufacturers to coordinate structural engineering with surgical workflow design teams.
Growth Catalysts
- EU Medical Device Regulation:The MDR's enhanced clinical evidence requirements for Class IIa devices is filtering out marginal suppliers and consolidating procurement toward certified manufacturers in tertiary care networks.
- Minimally invasive surgical workflows:Hospitals in India and China are expanding operating room infrastructure to accommodate laparoscopic and robotic-assisted procedures that demand ceiling-mounted utility routing.
- Aluminum extrusion fabrication:Advances in sealed bearing joint technology are extending rotation envelope reliability from 180 to 340 degrees, supporting heavier equipment loads in critical care zones.
Market Restraints
- Input cost volatility:Aluminum alloy pricing fluctuations and specialized medical-grade polymer shortages are compressing margin pools on LED lighting subsystems.
- Supply concentration risk:European bearing and gas valve component suppliers dominate upstream tiers, creating vulnerability to regional logistics disruptions.
- Regulatory friction:Parallel BIS certification in India and NMPA registration in China require redundant testing protocols that extend product launch timelines by twelve to eighteen months.
Strategic Opportunities
- Ambulatory surgery centers:Mobile pendant variants represent unmet demand in reconfigurable layouts across the United States where permanent infrastructure investment is deferred.
- Anesthetic gas scavenging precision:Convergence of gas management subsystems with real-time environmental monitoring is opening premium positioning in hybrid operating rooms.
- Preventive maintenance contracts:Service revenue unbundling from equipment sales is creating recurring income streams as hospitals extend replacement cycles.
Industry Challenges
- Electromagnetic compatibility engineering:Tightening EU MDR requirements for ceiling-mounted equipment are forcing redesigns of data connectivity modules and power distribution architectures.
- Cybersecurity framework compliance:Evolving standards for networked control systems are complicating procurement criteria and requiring firmware validation protocols that most legacy installations lack.
- Integration complexity:Retrofitting single-arm pendants into existing surgical suites requires structural load assessments and ceiling reinforcement that disrupt clinical operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Single-Arm Medical Pendant Market |
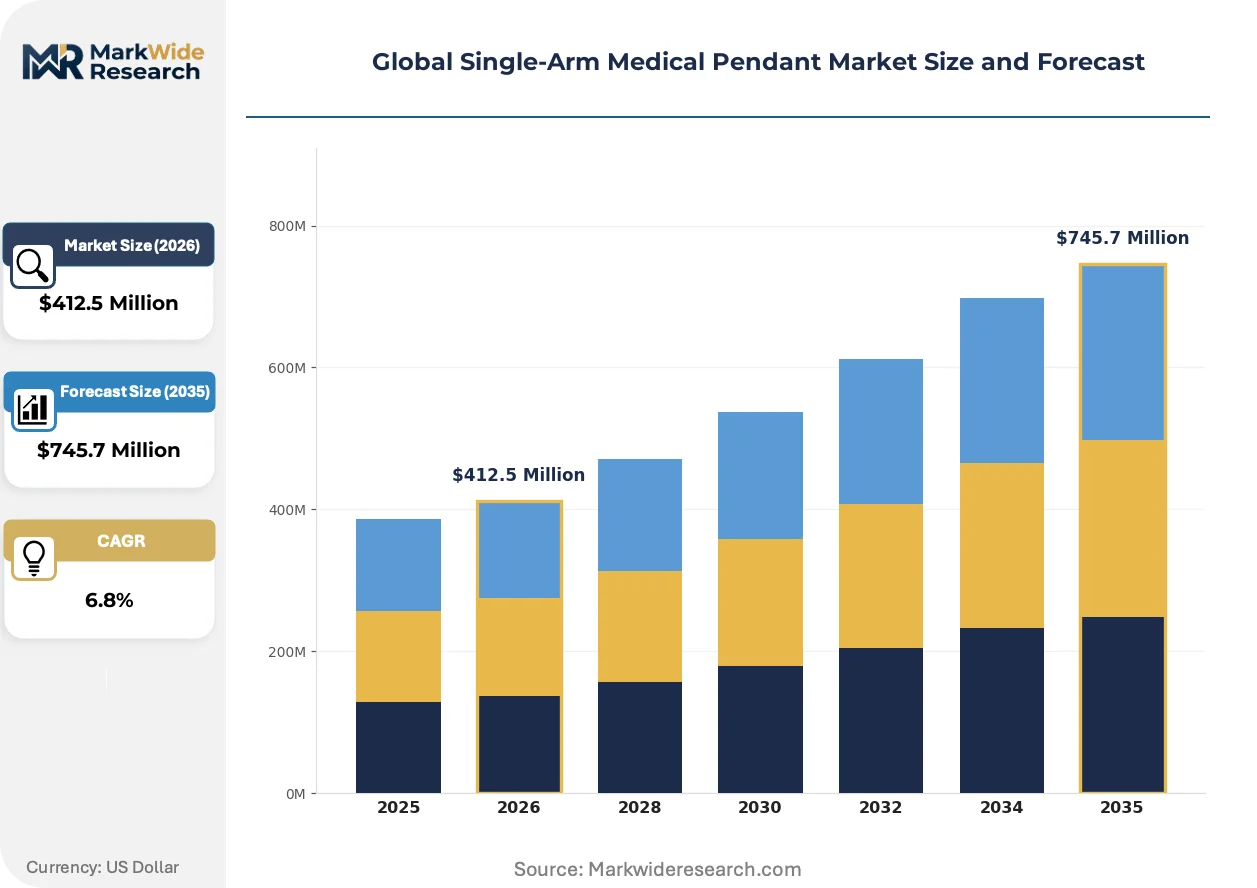
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceiling-Mounted, Wall-Mounted, Mobile, Floor-Standing Technology: LED Lighting, Gas Management, Electrical Outlets, Data Connectivity, Control Systems Application: Operating Rooms, Intensive Care Units, Emergency Rooms, Neonatal Care Units, Diagnostic Centers End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Diagnostic Laboratories |
| Companies Covered | Drägerwerk AG & Co. KGaA, STERIS plc, BeaconMedaes, Ondal Medical Systems, Brandon Medical Co. Ltd, Novair Medical, Starkstrom Ltd, Elektra Hellas S.A., HIPAC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Single-Arm Medical Pendant Market Shifts & Advancements
Digital integration of pendant control systems with hospital information networks is compressing the boundary between mechanical infrastructure and data architecture. This convergence is redrawing supplier capabilities and procurement evaluation criteria.
Modular data connectivity modules with embedded cybersecurity protocols are digitizing how surgical teams interface with ceiling-mounted utility systems. Tertiary care facilities in Germany are piloting these architectures to enable real-time equipment status monitoring and predictive maintenance alerts. The technology is digitizing traditional service relationships by embedding diagnostic capability directly into pendant hardware.
The EU Medical Device Regulation's electromagnetic compatibility mandates are forcing redesigns of power distribution and gas management subsystems. Manufacturers must now submit enhanced clinical evidence for Class IIa ceiling-mounted devices, raising documentation burdens and testing costs. European tertiary centers are responding by consolidating procurement toward suppliers with established notified body relationships and MDR technical file capabilities.
After-sales service unbundling is accelerating as hospitals in the United States negotiate preventive maintenance contracts separate from capital equipment purchases. Ambulatory surgery centers are driving this pattern by demanding flexible cost structures that align spending with utilization rates. This behavioral shift is most visible in metropolitan hospital systems where operating room uptime metrics directly tie to reimbursement formulas.
Global Single-Arm Medical Pendant Market Segmentation
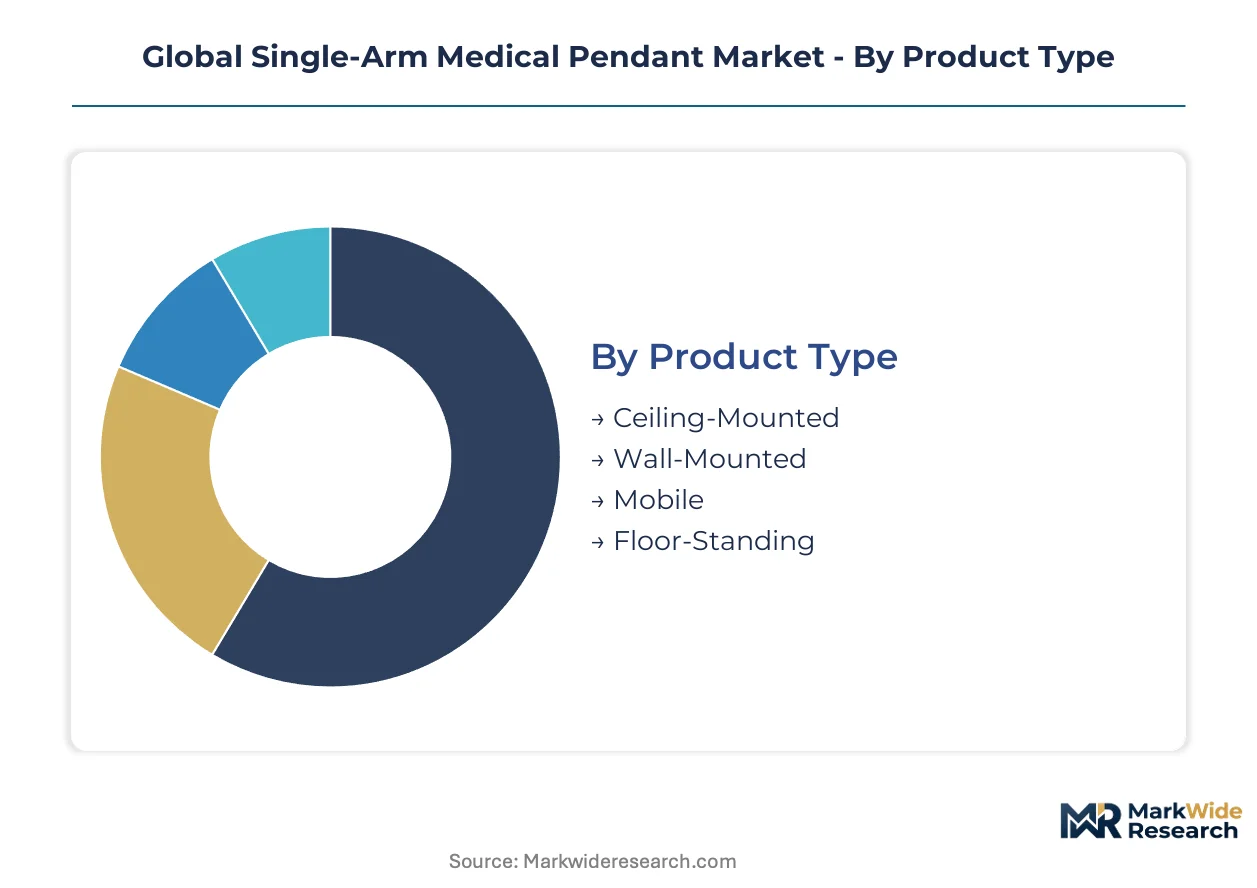
Single-arm medical pendant configurations vary sharply in installation complexity and service attachment rates. Preventive maintenance contracts and recertification programs concentrate around ceiling-mounted systems in tertiary hospitals, while mobile variants attract different service economics in ambulatory settings.
Product Type:
After-sales-service intensity correlates directly with structural permanence and clinical criticality across mounting configurations.
- Ceiling-Mounted:Aluminum extrusion booms with sealed bearing joints support 340-degree rotation envelopes and route medical gases, electrical power, and data cables through ceiling infrastructure. Demand concentrates in hybrid operating rooms across Germany and the United States where structural engineering coordination with surgical workflow design compresses installation timelines and extends service contract durations.
- Mobile:Castor-mounted frames with modular utility routing eliminate permanent infrastructure requirements and enable rapid layout reconfiguration. Ambulatory surgery centers in the United States drive demand for flexible cost structures that align spending with utilization rates rather than capital deployment.
- Wall-Mounted:Fixed articulating arms attach to vertical surfaces in space-constrained clinical zones with lower load-bearing requirements.
- Floor-Standing:Pedestal-based systems serve temporary installations and retrofit scenarios where ceiling reinforcement is structurally prohibitive.
Ceiling-Mounted holds the largest share; momentum sits with Mobile.
Technology:
Margin pools concentrate disproportionately in subsystems where clinical outcomes depend on precision engineering and regulatory compliance.
- LED Lighting:Surgical-grade illumination modules with color temperature control and shadow reduction algorithms command premium positioning. Tertiary care facilities prioritize illumination quality in hybrid operating rooms where visualization directly impacts procedural accuracy.
- Gas Management:Anesthetic gas scavenging systems with real-time environmental monitoring integrate with ceiling-mounted infrastructure. Hybrid operating rooms in Germany pilot convergence with environmental monitoring for premium positioning.
- Electrical Outlets:Medical-grade power distribution with isolation transformers and ground fault protection meets FDA 21 CFR 880.6180 requirements.
- Data Connectivity:Modular modules with embedded cybersecurity protocols digitize surgical team interfaces with networked control systems.
- Control Systems:Integrated touch interfaces and remote monitoring capabilities enable predictive maintenance alerts in digitally advanced facilities.
LED Lighting captures the largest installed base; Gas Management climbs the fastest on regulatory tailwinds.
Application:
Clinical environment determines rotation envelope requirements, utility density, and infection control integration intensity.
- Operating Rooms:Ceiling-mounted configurations with 340-degree rotation and integrated gas scavenging dominate minimally invasive surgical workflows. Hospital construction acceleration across India and China expands infrastructure to accommodate laparoscopic and robotic-assisted procedures.
- Intensive Care Units:High-density utility routing supports life-support equipment clustering at bedside workstations with ergonomic reach requirements.
- Emergency Rooms:Rapid-deployment mobile variants enable trauma bay reconfiguration without structural modification.
- Neonatal Care Units:Compact ceiling systems with low-profile booms accommodate incubator positioning and family-centered care layouts.
- Diagnostic Centers:Wall-mounted and floor-standing configurations serve imaging suites with moderate utility density requirements.
Operating Rooms holds the largest share; Intensive Care Units gains share fastest on critical care infrastructure expansion.
End User:
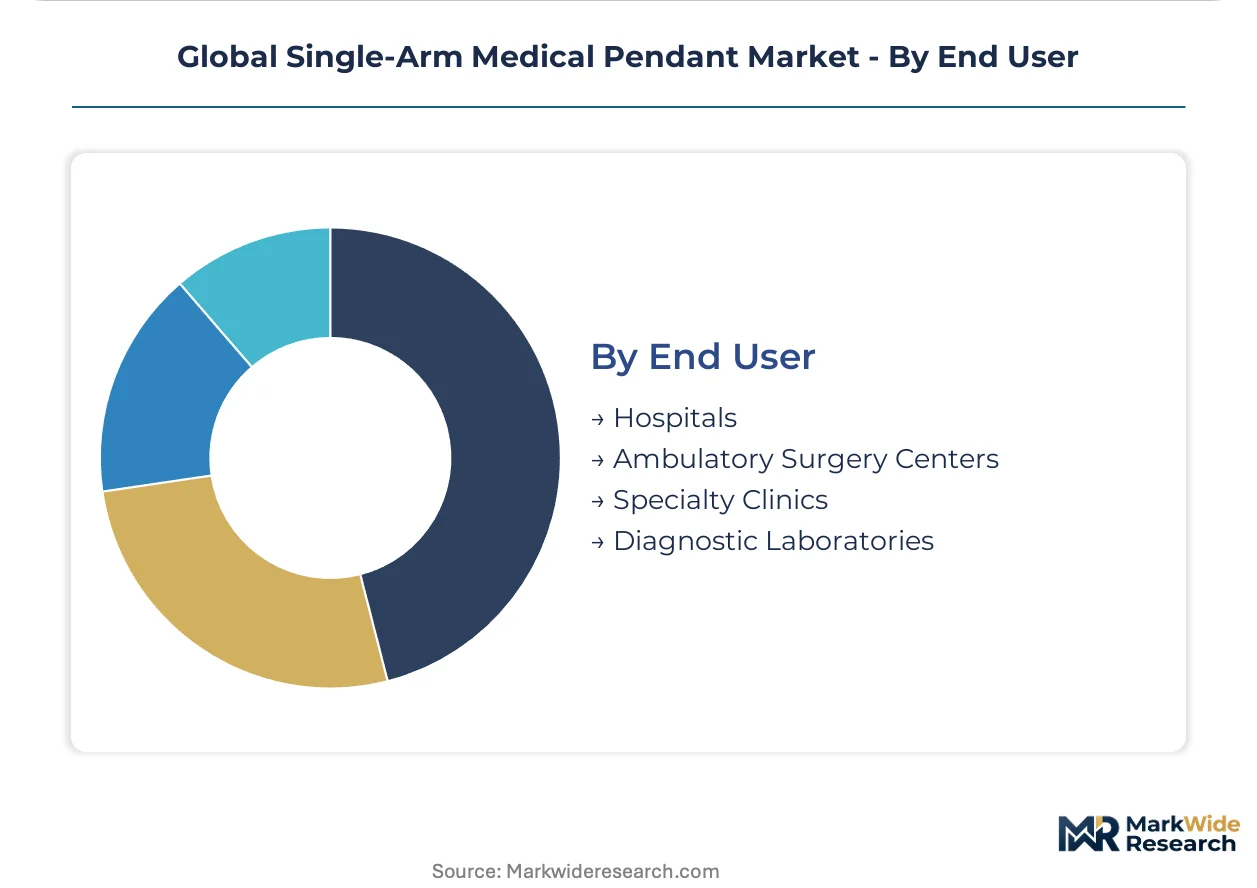
Procurement authority and capital allocation flexibility segment service contract structures and replacement cycle timing.
- Hospitals:Tertiary centers with centralized biomedical engineering departments negotiate unbundled preventive maintenance contracts separate from equipment purchases. Metropolitan hospital systems in the United States tie operating room uptime metrics directly to reimbursement formulas.
- Ambulatory Surgery Centers:Facility operators defer permanent infrastructure investment and prioritize mobile pendant variants with utilization-aligned spending structures.
- Specialty Clinics:Focused procedural centers deploy wall-mounted systems in ophthalmology, endoscopy, and pain management suites.
- Diagnostic Laboratories:Lower-acuity settings utilize floor-standing configurations for specimen processing and limited procedural support.
Hospitals holds the largest share; Ambulatory Surgery Centers expands most quickly on outpatient migration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement environments. Ambulatory surgery centers in the United States demand utilization-aligned spending structures, while tertiary hospitals in Germany absorb premium positioning for integrated gas scavenging systems. This divergence shapes how manufacturers configure product portfolios and service attachment rates by geography.
United States
Metropolitan hospital systems drive demand for ceiling-mounted configurations with predictive maintenance integration. FDA enforcement of 21 CFR 880.6180 electrical safety standards filters procurement toward established notified body relationships. The Greater Boston and Pacific Northwest clusters concentrate hybrid operating room construction where surgical workflow design compresses installation timelines.
Germany
Tertiary centers in Bavaria and North Rhine-Westphalia anchor European demand for 340-degree rotation envelope systems. EU Medical Device Regulation electromagnetic compatibility mandates force redesigns of power distribution architectures. The Stuttgart and Munich medical technology corridors concentrate R&D activity for infection control integration within pendant architectures.
China
NMPA registration requirements and hospital construction acceleration across the Yangtze River Delta expand infrastructure for minimally invasive surgical workflows. The country's national medical device regulator mandates redundant testing protocols that extend product launch timelines. Shanghai and Beijing tertiary care facilities prioritize LED lighting quality in hybrid operating room configurations.
India
BIS certification creates parallel compliance pathways that shape localization strategies for multinational suppliers. New hospital construction in Maharashtra and Karnataka accelerates demand for ceiling-mounted utility routing. The Delhi-NCR and Hyderabad clusters concentrate procurement authority for tertiary care infrastructure expansion.
United Kingdom
NHS procurement frameworks emphasize unbundled preventive maintenance contracts separate from capital equipment purchases. The London/Southeast and Midlands regions concentrate ambulatory surgery center development demanding mobile pendant variants. Manchester and Birmingham hospital systems tie operating room uptime metrics to reimbursement formulas.
Global Single-Arm Medical Pendant Market Competitive Landscape
Capability concentration sits with European specialists possessing MDR technical file expertise; scale advantage sits with diversified medical technology conglomerates. The vendor base organizes into three tiers: integrated service network operators, R&D-intensive infection control specialists, and channel-control-focused direct sellers. Two dominant competitive moves define current positioning: geographic expansion through notified body relationship cultivation, and service revenue unbundling into preventive maintenance contracts.
Within the integrated service tier, Drägerwerk AG & Co. KGaA and STERIS plc exemplify divergent strategic anchors. The Lübeck-based KGaA structure leverages direct hospital relationships across European tertiary centers to capture recurring revenue streams. STERIS plc, organized as a UK-registered public limited company, occupies a position emphasizing R&D intensity for infection control integration. BeaconMedaes represents the channel-control archetype, sustaining direct hospital relationships that bypass distributor markups in procurement-sensitive environments.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| STERIS plc |
| BeaconMedaes |
| Ondal Medical Systems |
| Brandon Medical Co. Ltd |
| Novair Medical |
| Starkstrom Ltd |
| Elektra Hellas S.A. |
| HIPAC |
| Others |
Supply & Pricing Matrix
Aluminum alloy pricing volatility and European bearing supply concentration determine both margin tier spreads and supply chain configuration across the single-arm medical pendant industry. Hospitals extending equipment life cycles compress capital equipment pricing while expanding preventive maintenance contract premiums, reshaping how manufacturers source components and structure service revenue.
Pricing Analysis
Preventive maintenance contract tiers now drive lifetime value capture as hospitals unbundle service from equipment purchases. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified European manufacturers from regional assemblers and refurbished equipment dealers. Cost compression in LED lighting subsystems intensifies because medical-grade polymer shortages and aluminum input volatility squeeze component margins. Ambulatory surgery centers exhibit highest price sensitivity through utilization-aligned spending demands, while German tertiary centers absorb premium positioning for integrated gas scavenging systems.
Supply Chain Analysis
Aluminum extrusion feedstock draws from Chinese smelters, German rolling mills, and Indian secondary processors for boom fabrication and structural components. Sealed bearing joints hinge on German and Swiss precision manufacturers, while medical-grade polymers for gas valve housings sources from Belgian and Dutch compounders. Single-source vulnerability concentrates in European bearing suppliers where regional logistics disruptions propagate through tier-one assembly. Distribution runs through direct hospital relationships in tertiary networks and specialized medical equipment distributors in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital integration of pendant control systems with hospital information networks creates platform-economics inflection as mechanical infrastructure converges with data architecture. Interoperability standards for networked medical devices are redrawing supplier capabilities and procurement evaluation criteria across installed base expansion opportunities.
For Market Incumbents: Build regulatory certification moats through MDR technical file depth and notified body relationship density. Deepen backward integration into aluminum extrusion and sealed bearing joint production to insulate margin pools from input volatility. Anchor position against emerging Asian assemblers by embedding predictive maintenance diagnostics directly into pendant hardware. For New Entrants and Emerging Players: Pursue mobile pendant white-space in United States ambulatory surgery centers where permanent infrastructure investment is deferred. Target India's Maharashtra and Karnataka hospital construction clusters where BIS certification creates parallel compliance pathways for localized assembly. Deploy utilization-based leasing models that align spending with surgical volume rather than capital deployment. For Investors and Strategic Acquirers: EU Medical Device Regulation reshapes the acquisition landscape toward targets with established CE marking pathways and MDR technical file capabilities. Five-to-ten year viability favors specialists with integrated service networks over pure-play hardware manufacturers. Monitor cybersecurity framework evolution for networked control systems as the signal indicating which data connectivity module suppliers will capture premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical File Development | CE marking pathway for Class IIa ceiling-mounted devices opens European tertiary hospital procurement. |
| Preventive Maintenance Contract Unbundling | Recurring revenue streams align with hospital equipment life cycle extension trends in metropolitan systems. |
| Mobile Pendant Platform Launch | Castor-mounted configurations address ambulatory surgery center demand for reconfigurable layouts. |
| Gas Scavenging Integration Partnership | Real-time environmental monitoring convergence captures premium positioning in hybrid operating rooms. |
| Cybersecurity Protocol Embedding | Firmware validation capabilities meet evolving procurement criteria for networked control systems. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR technical file databases, and hospital procurement contract registries preceded structured interviews with biomedical engineering directors, GPO contracts managers, pendant system procurement leads, and aftermarket service heads. Primary fieldwork across German tertiary centers, United States metropolitan hospital systems, and Indian construction clusters combined with secondary validation from customs trade data and SEC medical technology segment disclosures. Bottom-up installation base modeling and top-down healthcare infrastructure spend estimates were triangulated against regional regulatory filing trends.
Assumptions held fixed include MDR enforcement timelines, aluminum alloy price band stability, and hybrid operating room construction momentum in identified clusters; variables tested include NMPA registration pathway duration, cybersecurity framework implementation pace, and ambulatory surgery center outpatient migration rates. Segmentation modeling spanned mounting configuration, technology subsystem, clinical application, and end-user procurement authority across the projection horizon. CAGRs were derived from installed base replacement cycles and new hospital construction pipelines, with surgical procedure volume growth and minimally invasive workflow adoption as procedure-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles, medical device trade policy, or construction materials inflation would shift the trajectory. Forecasts reflect these assumptions and acknowledge that regulatory filing delays or cybersecurity standard acceleration could compress or extend manufacturer margin recovery timelines. Cross-checking against hospital construction pipeline databases and GPO contract award registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Equine Operating Tables Market
Medical Equipment
Medical X-Ray Generators Market
Medical Equipment
Operating Table Market
Medical Equipment
Medical Equipment Reimbursement Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Medical Whirlpool Market
Medical Equipment
Cell Culture Incubator Market
Medical Equipment
Global Platelet Agitator Market
Medical Equipment
Global Medical Equipment Calibration Market
Medical Equipment
Bone Marrow Processing Systems Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
US Biomedical Refrigerators and Freezers Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Global Countertop Platelet Incubator Market
Medical Equipment
Global Microtome Market
Medical Equipment
Blood Bank Refrigerators Market