
 Single-Coated Medical Tape Market | 2026-2036
Single-Coated Medical Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Coated Medical Tape Market Analytics
Homecare wound management is expanding as the fastest-growing end-use channel for single-coated medical tapes, pulling volume away from traditional hospital procurement. 3M Company dominates North American distribution through its extensive clinician training networks. Tesa SE leverages European manufacturing scale to supply ISO-certified tapes for surgical securement. Nitto Denko Corporation anchors Asian demand with silicone adhesive specialization for sensitive skin applications.
Single-coated medical tape consists of a single adhesive layer applied to a flexible backing substrate, typically incorporating acrylic, silicone, or rubber adhesives at coat weights between 20-80 gsm for controlled tack and clean removal. The product secures dressings, tubing, and devices to skin or drape surfaces during acute and chronic care. Silicone tape commands premium positioning due to its gentle adhesion profile and repositionability, while fabric tape retains volume leadership in surgical settings where tensile strength matters most. Paper tape occupies a mature, cost-driven niche in low-trauma dressing applications where breathability outweighs durability requirements.
FDA biocompatibility standards under ISO 10993 and EU MDR conformity procedures shape product development cycles and market access timelines for adhesive medical devices. The EPA and ECHA jointly influence solvent-based adhesive formulations through volatile organic compound restrictions and substance authorization protocols. Stakeholders must monitor evolving silicone raw material availability and regional regulatory divergence to calibrate supply chain and R&D allocation decisions.
Market Dynamics
Homecare wound management is pulling volume away from hospital procurement channels, restructuring how single-coated medical tape manufacturers allocate sales resources and inventory positioning.
Growth Catalysts
- EU MDR Compliance Deadlines:Medical device re-certification under the 2017/745 regulation is forcing tape suppliers to upgrade biocompatibility documentation, advantaging ISO 10993-tested product lines in European tenders.
- Silicone Adhesive Migration:Hospitals and long-term care facilities are converting from rubber-based to silicone adhesives for sensitive-skin patient populations, expanding addressable volume in pediatric and geriatric segments.
- Germany:The country's wound care infrastructure investments and statutory health insurance reimbursement for advanced dressings are concentrating regional demand for premium single-coated tapes.
Market Restraints
- Silicone Raw Material Concentration:Specialty silicone feedstock production clusters in East Asia, exposing Western tape converters to freight cost volatility and supply interruption risks.
- ISO 10993-5 Cytotoxicity Testing:Extended biocompatibility validation timelines under this standard add six to twelve months to new product commercialization, compressing R&D return windows.
- Film Backing Substitution:Polyurethane film dressings with integrated adhesives are displacing separate tape-plus-dressing configurations in surgical applications, eroding unit demand.
Strategic Opportunities
- Japan:Aging demographics and Ministry of Health, Labour and Welfare promotion of home-based care are expanding outpatient wound management, creating channel whitespace for direct-to-patient tape distribution.
- Printed Electronics Convergence:Integration of conductive traces into single-coated tape backings enables wearable biosensor attachment, opening device-securement applications beyond traditional medical settings.
- E-commerce Pharmacy Channels:Online procurement platforms for chronic wound supplies are bypassing traditional distributor markups, allowing tape manufacturers to capture margin through direct fulfillment.
Industry Challenges
- Adhesive Formulation Talent Scarcity:Cross-functional expertise spanning polymer chemistry, dermatological safety, and regulatory submission is concentrated among a narrow cohort of specialists, constraining product pipeline velocity.
- Cleanroom Manufacturing Capex:FDA and EU MDR requirements for controlled-environment production of sterile tape variants demand facility investments that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Coated Medical Tape Market |
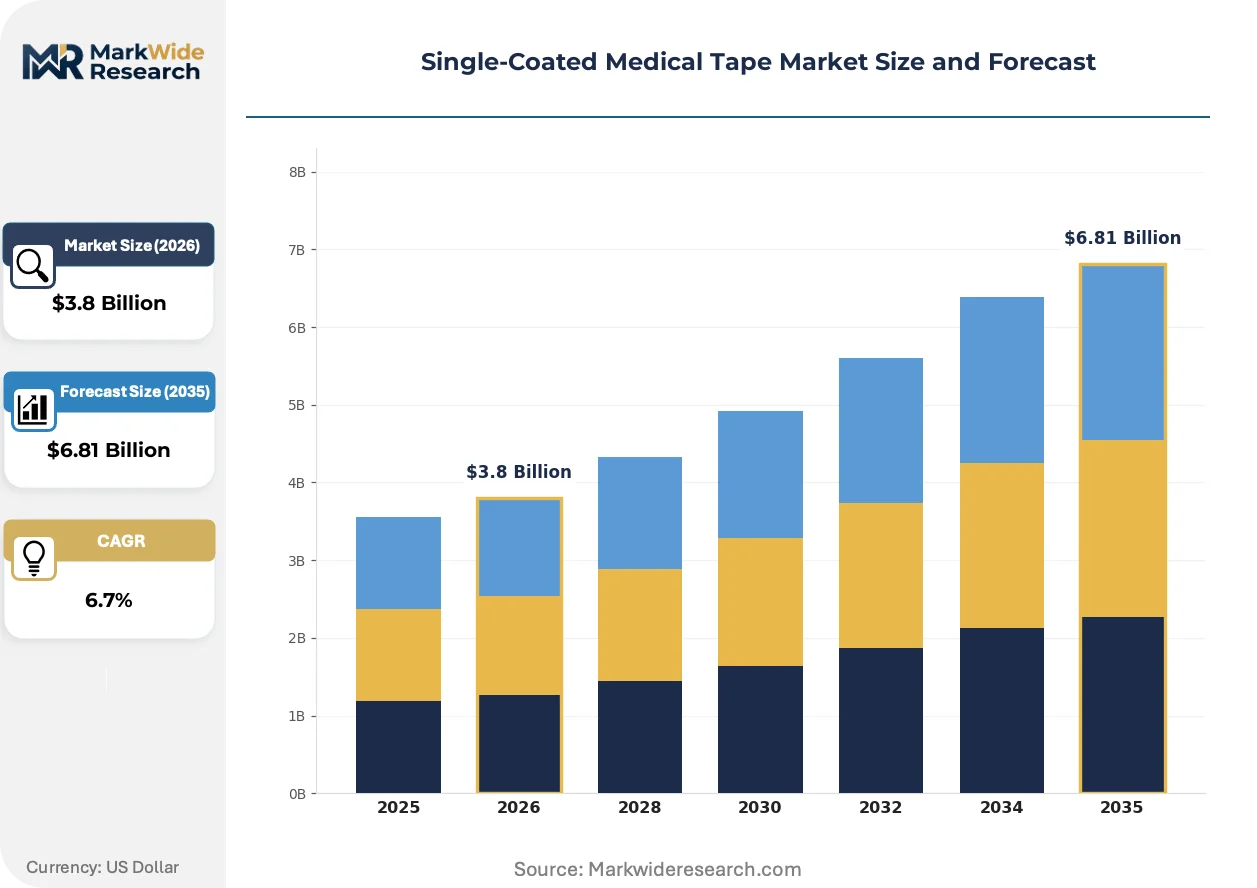
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Tape, Fabric Tape, Plastic Tape, Silicone Tape Application: Wound Care, Surgical Procedures, Securement, Dressing End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Adhesive Type: Hydrocolloid, Acrylic, Rubber, Silicone |
| Companies Covered | Scapa Group plc, Tesa SE, 3M Company, Shurtape Technologies, Lohmann GmbH and Co KG, Avery Dennison Corporation, Nitto Denko Corporation, LINTEC Corporation, Berry Global Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Coated Medical Tape Market Evolving Landscape
Active material science breakthroughs and regulatory recalibration are compressing product lifecycles while opening premium positioning pathways for compliant manufacturers.
Silicone-acrylic hybrid adhesives are electrifying the single-coated medical tape landscape by combining repositionability with aggressive initial tack. Burn centers and neonatal intensive care units are adopting these formulations at accelerated procurement cycles. The technology is electrifying competitive positioning, forcing pure-play silicone and acrylic suppliers toward formulation partnerships or obsolescence.
REACH substance authorization protocols under ECHA jurisdiction are restricting solvent-based adhesive chemistries across European manufacturing. Tape converters are migrating to hot-melt and UV-cured coating processes to maintain market access. Germany-based surgical tape suppliers are most affected, accelerating capital deployment into water-based adhesive lines ahead of 2026 authorization deadlines.
Consolidated buying through group purchasing organizations is compressing vendor rosters and standardizing specifications across hospital networks. Independent distributors are losing shelf space to contract-exclusive supply arrangements. The United States exhibits the most pronounced concentration, with integrated delivery networks now controlling procurement for a majority of acute care beds.
Single-Coated Medical Tape Market Segmentation
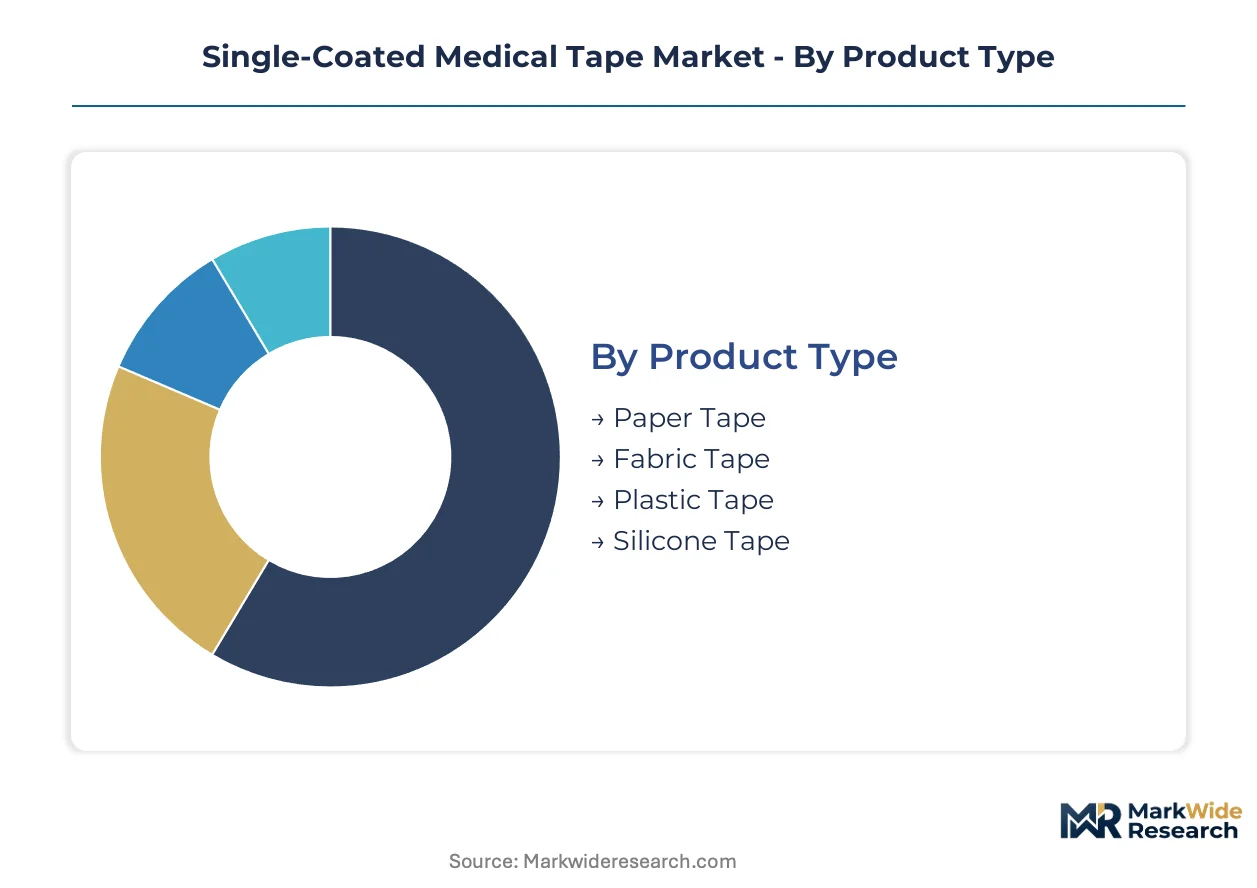
Single-coated medical tape segmentation reveals how adhesive chemistry and backing material choices map to distinct clinical workflows and reimbursement tiers. Manufacturers calibrate R&D spending and production capacity across these dimensions to match procurement patterns in acute versus chronic care settings.
Product Type:
Upgrade cycles from rubber-based to silicone-adhesive products are accelerating replacement demand across hospital formulary reviews and homecare procurement channels.
- Silicone Tape:Gentle adhesion profile enables repositionability without skin trauma, concentrating demand in neonatal intensive care units and geriatric long-term care facilities where epidermal integrity is paramount. Premium pricing captures value from reduced medical adhesive-related skin injuries.
- Fabric Tape:Woven or non-woven textile backings deliver tensile strength for surgical draping and tubing securement, anchoring volume in operating rooms where mechanical reliability outweighs repositionability needs. ISO 10993-10 irritation testing compliance is mandatory for tender participation.
- Paper Tape:Microporous breathable construction serves low-trauma dressing applications with cost-minimized procurement specifications.
- Plastic Tape:Polyethylene or polypropylene film backings provide moisture resistance for wound irrigation and bathing protocols.
Volume placements concentrate in Fabric Tape; the faster expansion belongs to Silicone Tape.
Application:
Cost tier differentiation separates commodity securement from premium wound management applications with specialized biocompatibility documentation requirements.
- Wound Care:Chronic and acute wound dressing fixation demands breathability and moisture vapor transmission rate optimization, with demand clustering in homecare settings where patient self-application drives preference for gentle-removal formulations. Reimbursement coding for advanced dressings expands addressable spend.
- Surgical Procedures:Sterile field maintenance and instrument draping require high-tack immediate adhesion with clean edge lift, anchoring procurement in integrated delivery networks with consolidated vendor rosters. FDA 510(k) clearance timelines shape competitive access.
- Securement:Catheter, tube, and device fixation spans acute and ambulatory settings with specification diversity by securement duration.
- Dressing:Primary and secondary dressing applications split between hospital formulary control and retail pharmacy channels.
Revenue concentration sits with Surgical Procedures; outpatient channel expansion is elevating Wound Care growth velocity.
End User:
Customer type fragmentation is restructuring sales force deployment as procurement authority migrates from materials management to clinical value analysis committees.
- Homecare:Direct-to-patient distribution bypasses traditional distributor markups, with aging demographics and reimbursement shifts toward outpatient wound management expanding channel whitespace. E-commerce pharmacy platforms enable manufacturer margin capture through direct fulfillment.
- Hospitals:Group purchasing organization consolidation compresses vendor rosters to contract-exclusive arrangements, favoring suppliers with ISO 13485 quality management systems and dedicated clinical specialist support.
- Clinics:Ambulatory surgical centers and outpatient wound clinics operate with leaner inventory models and faster procurement cycles.
- Rehabilitation Centers:Long-term care and skilled nursing facilities prioritize cost containment in adhesive consumables with extended wear duration requirements.
Procurement volume aggregates in Hospitals; the steepest expansion trajectory belongs to Homecare.
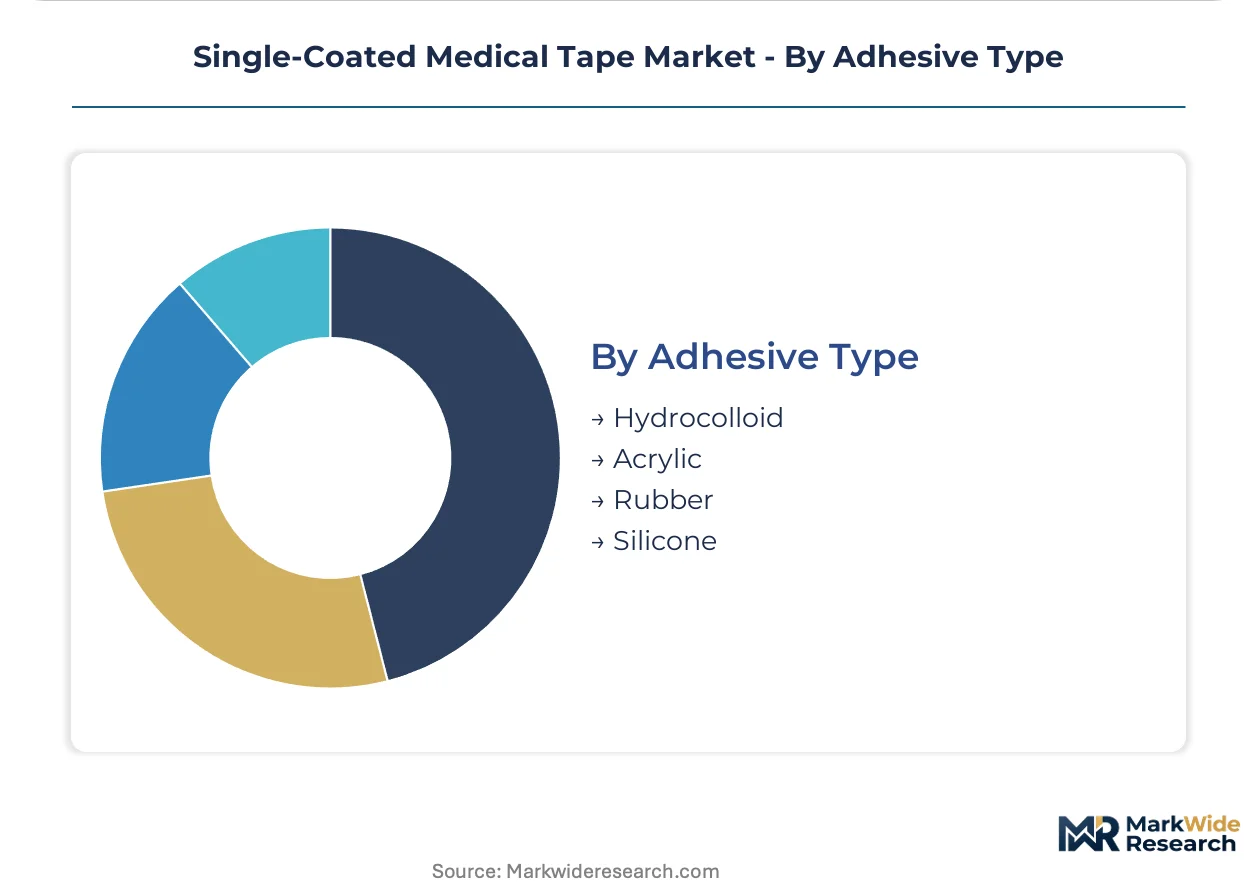
Adhesive Type:
Supply concentration in specialty silicone feedstock production shapes margin structure and geographic sourcing strategy for tape converters.
- Silicone:Soft-gel adhesion chemistry enables gentle skin contact with repositionability, commanding premium positioning in pediatric, geriatric, and burn center applications where epidermal trauma minimization drives formulary preference. East Asian feedstock concentration exposes Western converters to freight cost volatility.
- Acrylic:Aggressive initial tack and broad temperature performance anchor volume in general-purpose surgical and wound care applications with cost-optimized procurement specifications.
- Hydrocolloid:Absorptive gel-forming matrix integrates adhesive and dressing functions for exuding wound management.
- Rubber:Natural and synthetic rubber-based formulations retain niche positioning in cost-sensitive applications with shorter wear duration requirements.
Unit placements dominate in Acrylic; Silicone is climbing the fastest on conversion from rubber-based alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian converters consume the majority of specialty silicone feedstock, while Western markets drive premium formulation demand. This production-consumption asymmetry shapes freight exposure and margin structures across the value chain.
United States
Integrated delivery networks now control procurement for most acute care beds, compressing vendor rosters to contract-exclusive arrangements. FDA 510(k) clearance timelines determine competitive access for new tape introductions. Minneapolis-St. Paul anchors North American distribution infrastructure for medical adhesive products.
Germany
Statutory health insurance reimbursement for advanced wound dressings concentrates regional demand for premium single-coated tapes. ECHA REACH substance authorization protocols are accelerating migration from solvent-based to water-based adhesive coating processes. The Rhine-Ruhr industrial corridor hosts ISO 13485-certified conversion facilities serving European surgical tape tenders.
Japan
Ministry of Health, Labour and Welfare promotion of home-based care expands outpatient wound management channels. PMDA biocompatibility documentation requirements align with ISO 10993 standards for market access. The Kanto region around Tokyo anchors domestic distribution for silicone adhesive specialization targeting geriatric skin applications.
China
NMPA medical device registration reforms are extending approval timelines for imported adhesive products, advantaging domestic converters. Dual carbon goals under MEE jurisdiction are pressuring solvent-based coating operations toward UV-cured and hot-melt alternatives. The Yangtze River Delta clusters specialty silicone feedstock production serving regional tape manufacturers.
India
CDSCO medical device rules implementation is tightening quality system requirements for adhesive product imports. PLI scheme incentives for domestic manufacturing are attracting coating line investments from multinational suppliers. Maharashtra and Gujarat host emerging conversion capacity targeting price-optimized surgical and wound care segments.
Single-Coated Medical Tape Market Competitive Landscape
Top-tier vendors anchor integrated delivery network contracts, while mid-cap specialists occupy regional and application-specific niches. The vendor base stratifies across three tiers: multinational adhesive conglomerates with full regulatory dossiers, regional converters with ISO-certified flexible manufacturing, and commodity suppliers serving price-sensitive tenders. Two dominant competitive moves are reshaping positioning: backward integration into specialty silicone compounding and geographic expansion through distributor acquisition in Asia-Pacific homecare channels.
Among diversified adhesive conglomerates, 3M Company and Nitto Denko Corporation exemplify the premium-tier archetype with extensive regulatory dossiers and clinician training networks. Tesa SE occupies a position within the European manufacturing scale tier, leveraging ISO-certified production for surgical securement tenders. These three anchors represent distinct strategic postures: North American channel control, Asian silicone specialization, and European regulatory compliance scale.
| Leading Market Players |
|---|
| Scapa Group plc |
| Tesa SE |
| 3M Company |
| Shurtape Technologies |
| Lohmann GmbH and Co KG |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| LINTEC Corporation |
| Berry Global Group |
| Others |
Value Network & Pricing Analysis
ECHA REACH substance authorization deadlines for solvent-based adhesive chemistries are gating qualified supply access and segmenting tape manufacturers into premium-tier pricing eligibility versus commodity exclusion. This environmental mandate concentrates pricing power among converters that completed water-based and UV-cured coating line transitions ahead of regulatory enforcement windows.
Pricing Analysis
Margin tightening in economy-tier paper and rubber-adhesive tapes reflects raw material pass-through volatility and hospital GPO consolidation. Three-tier pricing structure across silicone premium, acrylic standard, and rubber economy levels separates ISO 10993-5 certified products commanding formulary preference from uncertified alternatives facing tender exclusion. Cost-down pressure on fabric-backed surgical tapes accelerates because polyurethane film dressing substitution erodes unit volumes. Homecare e-commerce channels exhibit lowest price sensitivity due to direct-to-patient margin capture, while rehabilitation centers drive hardest procurement negotiations.
Supply Chain Analysis
FDA 510(k) and EU MDR quality system certification gates supplier qualification for sterile tape variants, filtering raw material access through ISO 13485-audited converters. Specialty silicone feedstock production concentrates in China, Japan, and South Korea, drawing Western tape manufacturers into freight cost exposure and inventory positioning complexity. Medical-grade adhesive polymer supply rests on petrochemical derivatives and silicone monomer streams vulnerable to energy price swings. Distribution runs through integrated delivery networks in the United States, ISO-certified surgical distributors in Germany, and pharmacy e-commerce platforms in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty silicone compounding capacity scarcity props premium-tier pricing and creates defendable margin pools for qualified manufacturers. Supply-constrained market structure favors incumbents with backward-integrated feedstock positions.
For Market Incumbents: Anchor formulary position through ISO 10993-5 cytotoxicity dossier completeness ahead of EU MDR recertification waves. Defend against silicone-acrylic hybrid displacement by accelerating clinician training network deployment in neonatal and burn center segments. Prioritize captive silicone compounding capacity in East Asian supply clusters to neutralize freight volatility exposure. For New Entrants and Emerging Players: Begin with Japan's homecare channel whitespace where Ministry of Health, Labour and Welfare reimbursement shifts bypass entrenched hospital GPO structures. Target direct-to-patient e-commerce pharmacy fulfillment as the most penetrable route, exploiting distributor markup elimination. Lead with gentle-removal silicone formulations for geriatric skin applications where epidermal trauma sensitivity creates preference stickiness. For Investors and Strategic Acquirers: Nitto Denko Corporation's regional silicone specialization expansion pace is the leading indicator that Asian feedstock integration premiums are widening. Five-to-ten-year viability favors converters with dual FDA-EU MDR regulatory dossiers and water-based coating line depreciation completion. Target acquisition archetype: mid-tier ISO 13485-certified European converters with underutilized cleanroom capacity and pending REACH compliance capex needs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Compounding | Captive East Asian feedstock supply neutralizes freight volatility and secures margin structure. |
| EU MDR Recertification Completion | ISO 10993-5 dossier readiness unlocks German statutory insurance reimbursement tenders. |
| Homecare E-Commerce Channel Launch | Direct-to-patient fulfillment in Japan bypasses distributor markups and captures premium pricing. |
| Water-Based Coating Line Deployment | ECHA REACH solvent authorization compliance maintains European manufacturing market access. |
| Clinician Training Network Expansion | Neonatal and burn center specialist relationships defend against hybrid adhesive substitution. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contract filings, and FDA 510(k) clearance records underwrites the qualitative findings. Primary interviews with biomedical engineers, wound care clinicians, GPO contracts managers, and adhesive formulation chemists combined with secondary validation from customs trade data, SEC 10-K medical device segment disclosures, and EMA medical device registration databases. Bottom-up tape volume modeling and top-down wound care expenditure triangulation cross-check magnitude estimates.
Rate-of-change decomposition across adhesive chemistry substitution curves, end-user channel migration patterns, and regulatory compliance cost absorption shapes the analytical framework. Segmentation dimensions span silicone-acrylic-rubber-hydrocolloid adhesive types, fabric-paper-plastic backings, and hospital-clinic-homecare end-user channels. CAGRs derive from installed base replacement cycles and outpatient wound management reimbursement elasticity. Forecast inputs incorporate silicone raw material freight cost indices and EU MDR recertification timeline assumptions.
Raw material supply interruption, ECHA authorization deadline acceleration, and FDA biocompatibility testing backlog expansion are the dominant revision risks to modeled projections. Forecasts reflect documented assumptions regarding adhesive chemistry conversion rates and channel shift velocities. A model refresh is warranted upon material change in East Asian silicone monomer availability or integrated delivery network vendor roster consolidation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Europe Medical Device Reprocessing Market
Medical Equipment
Bench-Top Dental Autoclaves Market
Medical Equipment
Hybrid Operating Room Market
Medical Equipment
Centrifuge Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Home Medical Equipment Market
Medical Equipment
Dialysis Equipment Market
Medical Equipment
Operating Table Market
Medical Equipment
Global Microtome Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Medical Vending Machines Market
Medical Equipment
Electric Bed Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
Patient Lifting Equipment Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
China Radiotherapy Market