
 Bone Densitometer Systems Market | 2026-2036
Bone Densitometer Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Densitometer Systems Market Outlook
ISO 13485 certification is unwinding the competitive landscape for bone densitometer manufacturers, filtering out suppliers lacking quality management rigor. Hologic Inc. leverages its vertically integrated manufacturing footprint to control production costs across the DXA product line. GE Healthcare anchors its position through deep installed-base relationships in radiology departments. Siemens Healthcare differentiates via software-integrated imaging platforms that streamline clinical workflow.
Bone densitometer systems measure bone mineral density using ionizing or non-ionizing radiation, typically quantifying results in grams per square centimeter to assess skeletal strength and fracture probability. Dual-energy X-ray absorptiometry dominates the product type landscape as the clinical gold standard, while quantitative ultrasound gains traction in point-of-care settings where portability outweighs precision requirements. Peripheral densitometry occupies a mature niche in pharmacy and primary care screening, whereas computed tomography-based assessment remains concentrated in research laboratories due to higher radiation exposure and cost structures.
The FDA 510(k) framework and EU MDR conformity requirements govern market access, with both agencies tightening post-market surveillance for radiological equipment. The EPA and state-level radiation control programs in the United States layer additional operational compliance onto imaging facilities. Stakeholders must monitor reimbursement coding shifts for osteoporosis screening as payor policies increasingly tie coverage to proven clinical outcomes rather than procedural volume alone.
Market Dynamics
Hospital procurement committees now require ISO 13485 certification as a baseline qualification, compressing the vendor pool and elevating quality management rigor from competitive advantage to market entry threshold.
Growth Catalysts
- Aging Demographics in Japan:The world's highest elderly population density sustains diagnostic volume expansion in Tokyo and Osaka metropolitan hospital networks, with the Ministry of Health mandating osteoporosis screening protocols for adults over seventy.
- EU MDR Conformity Requirements:Stricter post-market surveillance for radiological equipment accelerates replacement cycles as legacy devices face re-certification deadlines, channeling procurement toward compliant manufacturers.
- Quantitative Ultrasound:This ionizing-radiation-free modality penetrates pharmacy and primary care settings where point-of-care accessibility outweighs DXA precision, opening screening access beyond hospital radiology departments.
Market Restraints
- Supply Concentration in Precision Detectors:German and Japanese suppliers dominate solid-state detector manufacturing, creating single-source vulnerability for DXA system assemblers seeking dual-qualified vendors.
- Radiation Exposure Liability:CT-based bone assessment remains confined to research laboratories due to cumulative dose concerns and malpractice exposure, capping addressable market expansion for high-resolution alternatives.
- Reimbursement Compression:CMS and private payors in the United States tie coverage to proven clinical outcomes rather than procedural volume, elongating sales cycles as facilities await coding clarity.
Strategic Opportunities
- Rural India Penetration:Under-screened populations in Maharashtra and Tamil Nadu present white space for portable quantitative ultrasound units distributed through government health camps and mobile diagnostic fleets.
- Software-Integrated Platforms:Convergence of DXA hardware with AI-assisted fracture risk scoring and electronic health record interoperability creates premium pricing power and workflow stickiness in integrated delivery networks.
- Pharmacy Channel Expansion:Retail health clinics in Germany and the United Kingdom deploy peripheral densitometry for opportunistic screening, bypassing radiology department queue constraints and capturing incidental patient traffic.
Industry Challenges
- ISO 13485 Certification Timeline:Smaller manufacturers face eighteen-to-twenty-four month quality system implementation periods, delaying market entry as notified body backlogs extend audit scheduling.
- Legacy PACS Integration:New densitometer installations require costly interface engineering with entrenched picture archiving systems, particularly in United States hospital networks running decade-old infrastructure.
- Radiation Physicist Shortage:State-level EPA compliance programs mandate qualified medical physicist oversight for ionizing equipment, with credentialing bottlenecks constraining facility expansion in underserved regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Densitometer Systems Market |
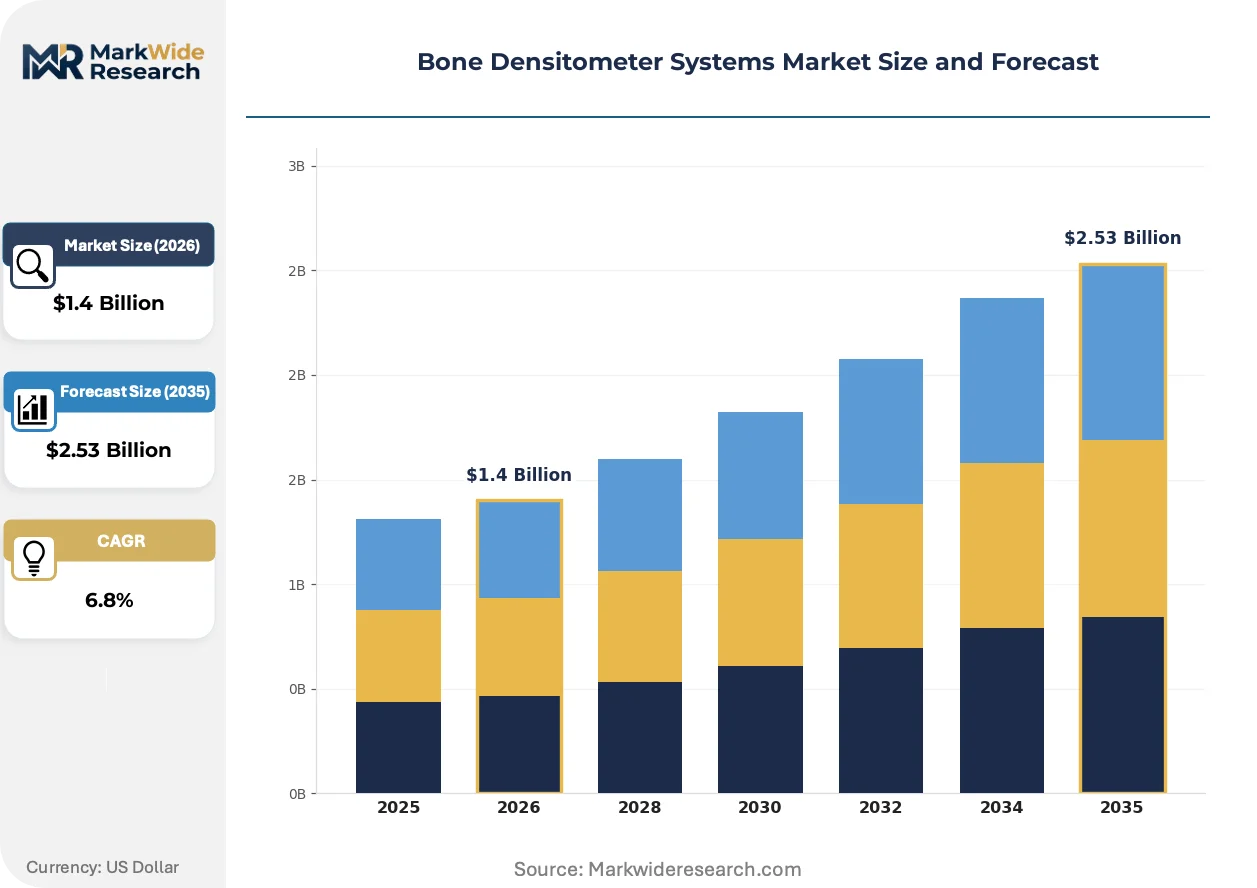
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual-Energy X-Ray Absorptiometry, Quantitative Ultrasound, Peripheral Densitometry, Computed Tomography End User: Hospitals, Diagnostic Centers, Research Laboratories, Home Healthcare Technology: Bone Density Measurement, Imaging Techniques, Software Solutions, Data Analysis Application: Osteoporosis Screening, Fracture Risk Assessment, Clinical Research, Wellness Programs |
| Companies Covered | Hologic Inc., GE Healthcare, Diagnostic Medical Systems (DMS Group), Swissray International, OSTEOSYS Corp., Echolight S.p.A., Siemens Healthcare, FURUNO Electric Co., Ltd., Trivitron Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Densitometer Systems Market Strategic Shifts
Three forces reshape competitive positioning: detector technology evolution, regulatory surveillance intensification, and procurement rationalization toward total cost of ownership rather than capital expenditure minimization.
Silicon photomultiplier arrays are supplanting traditional photomultiplier tubes in high-end DXA systems, offering superior energy resolution and compact form factors. Academic medical centers in Germany and Japan lead adoption, drawn by reduced calibration drift and extended service intervals. This transition compresses maintenance revenue pools for incumbent service organizations while enabling manufacturers to command hardware premiums.
The FDA's 510(k) clearance pathway for radiological devices now demands enhanced post-market performance data, extending pre-submission preparation timelines. Device sponsors face expanded clinical validation requirements for predicate comparisons, particularly for software-as-medical-device components. United States manufacturers respond by front-loading quality system investments and engaging FDA earlier in development cycles.
Buying committees now evaluate densitometer acquisitions through ten-year total cost models encompassing service contracts, phantom calibration schedules, and technologist training requirements. This analytical rigor disadvantages low-cost entrants lacking established service infrastructure. The shift is most pronounced in United States integrated delivery networks and German hospital conglomerates consolidating equipment standardization.
Bone Densitometer Systems Market Segmentation
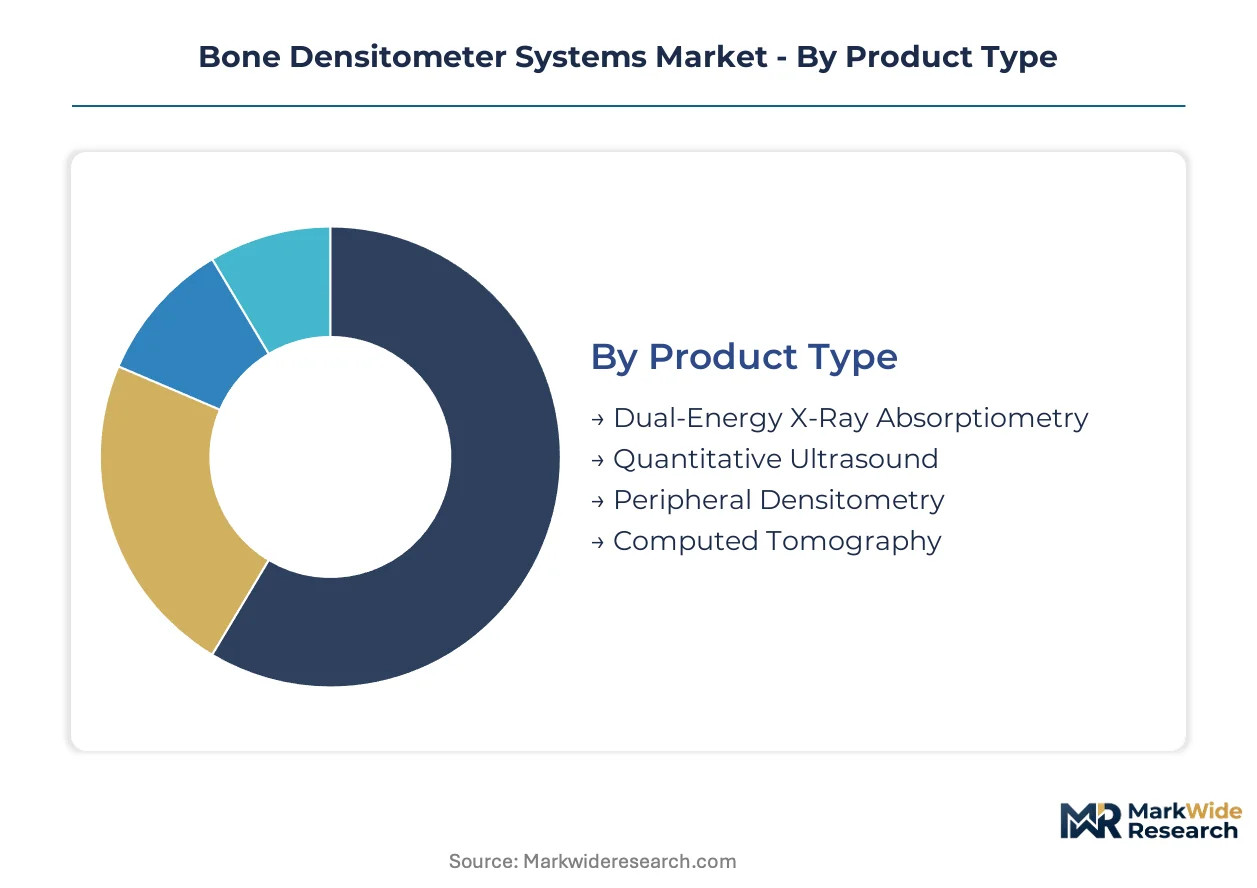
Segmentation reveals how bone densitometer demand fragments across clinical settings, with technology choices and end-user requirements driving divergent procurement patterns. Understanding these divides exposes where manufacturers must tailor specifications versus where standardization prevails.
Product Type:
Dual-energy X-ray absorptiometry dominates domestic hospital procurement in the United States, Germany, and Japan, while quantitative ultrasound gains export traction in emerging markets prioritizing portability over precision.
- Dual-Energy X-Ray Absorptiometry:This modality employs two distinct X-ray energy levels to differentiate bone from soft tissue, achieving precision within 1-2% for lumbar spine and femoral neck measurements. Demand concentrates in tertiary hospital networks across Tokyo, Osaka, and Munich where high diagnostic volume justifies capital investment and dedicated technologist staffing. The FDA's 510(k) pathway governs predicate device comparisons, elongating clearance timelines for system upgrades.
- Quantitative Ultrasound:Operating without ionizing radiation, this technology measures broadband ultrasound attenuation and speed of sound at peripheral skeletal sites. Export-led growth centers on pharmacy chains in the United Kingdom and mobile screening fleets in rural India, where point-of-care accessibility outweighs DXA-grade precision. India's Ministry of Health incorporates these units into government health camp infrastructure.
- Peripheral Densitometry:Compact systems targeting distal radius or calcaneus assessment occupy primary care clinics in Germany and retail health settings where space constraints and lower throughput predominate.
- Computed Tomography:Research laboratories at academic medical centers in Heidelberg and Stanford deploy quantitative CT for volumetric bone density analysis, constrained by radiation dose liability and higher operational costs.
Dual-energy X-ray absorptiometry holds the largest share; momentum sits with quantitative ultrasound.
End User:
Hospital procurement committees drive premium system adoption through total cost-of-ownership models, while diagnostic centers prioritize throughput optimization and home healthcare remains nascent pending reimbursement clarity.
- Hospitals:Integrated delivery networks in the United States and German hospital conglomerates standardize on DXA platforms with PACS interoperability and AI-assisted fracture risk scoring. These institutions command volume discounts through multi-year service contracts and phantom calibration schedules.
- Diagnostic Centers:Independent imaging facilities in Tokyo and Mumbai optimize patient throughput through streamlined technologist workflows and extended operating hours, favoring systems with rapid scan protocols and automated quality assurance.
- Research Laboratories:Academic centers pursue quantitative CT and high-resolution peripheral quantitative CT for longitudinal osteoporosis studies, funded by national health institutes in Japan and the European Research Council.
- Home Healthcare:Portable quantitative ultrasound devices penetrate geriatric home care in Japan's prefectural health programs, though CMS and private payor coding ambiguity constrains United States expansion.
Hospitals anchor revenue concentration; diagnostic centers are climbing the fastest.
Technology:
Hardware differentiation narrows as software and data analytics become primary competitive battlegrounds, with margin accumulation shifting toward workflow integration and predictive algorithms.
- Bone Density Measurement:Core detection technologies—solid-state detectors from German and Japanese suppliers, silicon photomultiplier arrays—determine system precision and calibration stability. Academic medical centers in Berlin and Kyoto lead adoption of next-generation detector platforms.
- Imaging Techniques:Fan-beam versus pencil-beam geometry trade-offs influence scan time and radiation dose, with fan-beam systems dominating high-volume United States hospital networks.
- Software Solutions:AI-assisted vertebral fracture assessment and automated region-of-interest detection reduce technologist interpretation variability. FDA scrutiny of software-as-medical-device components intensifies validation requirements.
- Data Analysis:Integration with electronic health records and population health databases enables longitudinal tracking across integrated delivery networks, particularly in United States Medicare accountable care organizations.
Bone density measurement retains the installed base; software solutions command expanding margin share.
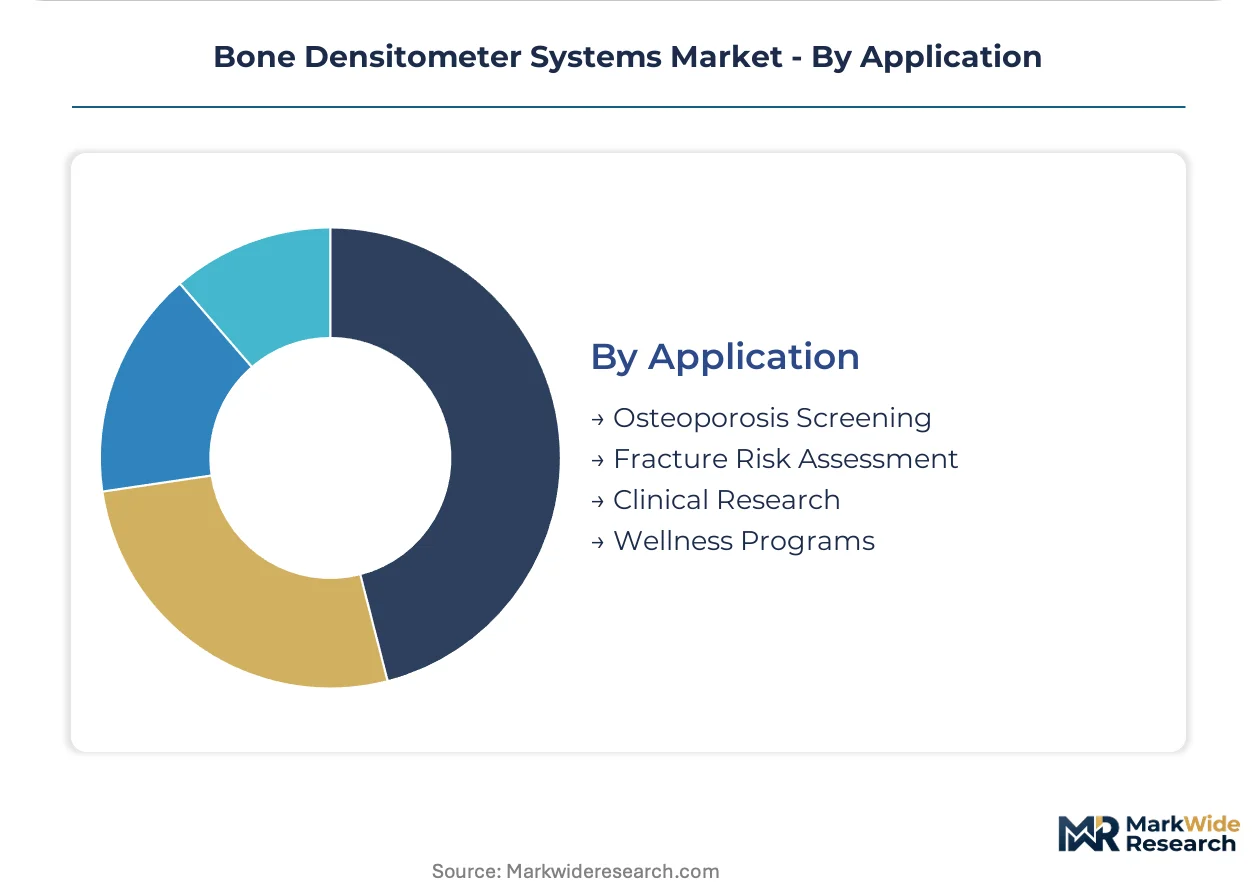
Application:
Clinical utility drives procurement in reimbursed indications, while wellness programs and research applications face funding volatility tied to payer policy and grant cycles.
- Osteoporosis Screening:Japan's Ministry of Health mandates screening for adults over seventy, sustaining diagnostic volume in Tokyo metropolitan networks. The United States Preventive Services Task Force recommendations influence CMS coverage determinations and private payor alignment.
- Fracture Risk Assessment:FRAX algorithm integration with DXA outputs enables 10-year probability calculation, required for treatment reimbursement authorization in German statutory health insurance.
- Clinical Research:Pharmaceutical trials for osteoporosis therapeutics drive demand for central reading facilities with standardized quality control, concentrated in Boston and Basel contract research organizations.
- Wellness Programs:Corporate and direct-to-consumer screening in United States pharmacy chains and fitness centers operates outside reimbursed care, exposing revenue to discretionary spending sensitivity.
Osteoporosis screening generates the volume base; fracture risk assessment shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Ministry of Health mandates osteoporosis screening for adults over seventy, establishing policy-driven diagnostic volume that other aging economies now emulate. Germany's EU MDR re-certification deadlines accelerate equipment replacement cycles. India's government health camps deploy portable units into rural Maharashtra and Tamil Nadu.
United States
CMS reimbursement coding for osteoporosis screening shapes hospital procurement timelines, with integrated delivery networks in Boston and Minneapolis standardizing on DXA platforms. The FDA's 510(k) pathway governs predicate device clearances, elongating pre-submission preparation for software-integrated systems. Academic medical centers at Stanford and Johns Hopkins lead adoption of silicon photomultiplier detector arrays.
Germany
EU MDR conformity requirements and stricter post-market surveillance compress replacement cycles for legacy radiological equipment. Statutory health insurance ties treatment reimbursement to FRAX algorithm integration, mandating software compatibility. Hospital conglomerates in Munich and Heidelberg consolidate equipment standardization through multi-year service contracts.
Japan
The world's highest elderly population density sustains diagnostic volume expansion across Tokyo and Osaka metropolitan networks. PMDA oversight of radiological devices aligns with global harmonization initiatives, streamlining approval pathways. Prefectural health programs in Kanagawa and Aichi deploy portable quantitative ultrasound into geriatric home care settings.
India
Under-screened rural populations in Maharashtra and Tamil Nadu present white space for government health camp infrastructure. The country's national pharmaceutical regulator and central medical device oversight framework govern import licensing for diagnostic equipment. Mobile diagnostic fleets in Gujarat and Karnataka distribute portable units through public-private partnerships.
United Kingdom
Retail pharmacy chains in London and Manchester deploy peripheral densitometry for opportunistic screening outside radiology department queues. MHRA post-market surveillance requirements align with EU MDR transitional provisions, affecting legacy device continuity. NHS England's osteoporosis pathway guidelines influence primary care referral patterns and equipment placement decisions.
Bone Densitometer Systems Market Competitive Environment
Listed leaders compete with private specialists across certification compliance and service infrastructure dimensions. The vendor base concentrates around three tiers: diversified imaging conglomerates with radiology department relationships, mid-scale specialists with ISO 13485 quality systems, and emerging portable-device developers targeting point-of-care expansion. Competitive moves center on software-integrated platform development and ten-year total cost-of-ownership contracting.
Among diversified imaging conglomerates, Hologic Inc. and GE Healthcare exemplify archetypes with entrenched installed-base positions in United States hospital networks. Siemens Healthcare anchors the European tier with workflow-integrated platform specialization. Swissray International and OSTEOSYS Corp. occupy positions within the mid-scale specialist segment, representing quality-certified alternatives for procurement committees filtering on ISO 13485 compliance. Echolight S.p.A. and FURUNO Electric Co., Ltd. sit within the portable-device developer tier, exemplifying radiation-free modality expansion into pharmacy and primary care channels.
| Leading Market Players |
|---|
| Hologic Inc. |
| GE Healthcare |
| Diagnostic Medical Systems (DMS Group) |
| Swissray International |
| OSTEOSYS Corp. |
| Echolight S.p.A. |
| Siemens Healthcare |
| FURUNO Electric Co., Ltd. |
| Trivitron Healthcare |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification gates both supplier qualification and price differentiation in bone densitometer procurement, compressing the vendor pool to quality-certified manufacturers while enabling premium pricing for compliant systems. Hospital procurement committees now treat certification as a non-negotiable baseline, forcing price competition into narrower bands around service infrastructure and software integration rather than hardware cost alone.
Pricing Analysis
Certification level (ISO 13485/FDA-grade/CE-marked) creates the primary spread across three pricing tiers: premium systems with AI-integrated software and ten-year service contracts, standard DXA platforms with phantom calibration schedules, and economy peripheral units for pharmacy screening. Price differentiation hinges on after-sales service bundling and PACS interoperability engineering, with German and Japanese detector sourcing driving hardware cost variance. Pricing pressure stems from CMS reimbursement compression tying coverage to clinical outcomes rather than procedural volume. Diagnostic centers in Mumbai and Tokyo exhibit highest price sensitivity due to throughput-dependent margins, while United States integrated delivery networks prioritize total cost-of-ownership over capital expenditure minimization.
Supply Chain Analysis
Just-in-time inventory strategies dominate detector procurement for DXA system assemblers, though strategic stockpiling of solid-state arrays from German and Japanese suppliers mitigates single-source vulnerability. Manufacturing concentrates in Germany, Japan, and the United States for precision detectors, silicon photomultiplier arrays, and system integration respectively. Raw material dependencies center on rare-earth phosphors, high-purity silicon substrates, and lead-shielding components. Supply chain risk manifests in tariff exposure on Japanese detector imports into the United States and European Union. Distribution runs through radiology equipment distributors with GPO contracts in hospital networks, direct sales forces for academic medical centers, and pharmacy channel partners for portable ultrasound units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs bone densitometer competitive dynamics as software-integrated imaging systems with EHR interoperability create winner-take-most dynamics in integrated delivery networks. The convergence of hardware with AI-assisted fracture risk scoring and automated vertebral assessment shifts margin accumulation toward recurring software revenue and away from capital equipment sales.
For Market Incumbents: Secure installed-base retention through multi-year phantom calibration contracts and PACS interoperability guarantees that raise switching costs for hospital procurement committees. Deepen backward integration into solid-state detector manufacturing to reduce German and Japanese supplier dependency. Prioritize FDA 510(k) pathway front-loading for software-as-medical-device components before predicate comparison requirements tighten further. For New Entrants and Emerging Players: Anchor in rural India's government health camp infrastructure where portable quantitative ultrasound penetration remains minimal and price sensitivity favors radiation-free modalities. Target pharmacy chains in the United Kingdom and Germany for peripheral densitometry deployment outside radiology department queues. Pursue public-private partnership distribution models with state health ministries rather than direct hospital sales forces. For Investors and Strategic Acquirers: EU MDR re-certification deadlines reshape the acquisition landscape by accelerating replacement cycles and channeling procurement toward compliant manufacturers with established notified body relationships. Five-to-ten year viability favors mid-scale specialists with ISO 13485 quality systems and software-integrated platform roadmaps over pure hardware assemblers. Watch CMS reimbursement coding shifts for osteoporosis screening as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Front-loaded quality system investments compress development timelines for software-integrated systems. |
| Hospital System Partnership | Multi-year service contracts with United States integrated delivery networks create switching cost barriers. |
| Software Companion Development | AI-assisted fracture risk scoring shifts margin accumulation toward recurring revenue streams. |
| CE Marking Pathway | EU MDR conformity requirements filter out suppliers lacking post-market surveillance infrastructure. |
| Reimbursement Strategy | CMS coding alignment determines procurement timing in Medicare accountable care organizations. |
Study Parameters
Desk research of FDA 510(k) clearance databases, EU MDR notified body registries, and hospital procurement contract disclosures preceded structured interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and radiology department heads. Secondary validation drew from CMS Medicare reimbursement data, PMDA medical device approval records, and academic medical center capital expenditure surveys. Bottom-up unit shipment estimates triangulated against top-down diagnostic volume projections across the analysis window.
Variance decomposition across product type, end user, technology, and application segments informed volume and value outputs throughout the forecast period. CAGRs derived from regression analysis of historical diagnostic procedure growth against aging demographic trajectories in Japan, Germany, and the United States. Industry-specific inputs incorporated silicon photomultiplier adoption curves, ISO 13485 certification timelines, and reimbursement coding elasticity estimates.
Material uncertainties — regulatory delays in FDA software-as-medical-device clearances, CMS reimbursement compression severity, and German-Japanese detector supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions around EU MDR transitional provision adherence and prefectural health program expansion in Japan. Revision becomes warranted when CMS osteoporosis screening coverage thresholds cross policy inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Europe Nuclear Medicine Equipment Market
Medical Equipment
Blood Bank Refrigerators Market
Medical Equipment
Water Bath Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
Medical Filter Market
Medical Equipment
Medical Equipment Reimbursement Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Europe Medical Automation Market
Medical Equipment
Global Laminar Airflow Cabinets Market
Medical Equipment
Medical Thawing Systems Market
Medical Equipment
Medical Computer Carts Market
Medical Equipment
Global Intraoperative Radiation Therapy Market
Medical Equipment
Durable Medical Equipment Rental Market
Medical Equipment
Medical Carts and Workstations Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Medical Equipment Maintenance Market