
 Instrument Calibration Services Market | 2026-2036
Instrument Calibration Services Market Size, Share, and Industry Trends Forecast 2026-2036
Instrument Calibration Services Market Foresight
Germany's industrial calibration infrastructure is fragmenting as mid-tier service providers multiply around Stuttgart and Munich. Fluke Corporation leverages its handheld reference equipment portfolio to dominate electrical meter calibration workflows across European manufacturing plants. Transcat sustains a dense North American service depot network that positions it for rapid on-site response in aerospace and pharmaceutical corridors. Rohde & Schwarz specializes in RF and microwave instrument calibration, anchoring premium pricing through its accredited laboratory capabilities in Bavaria.
Instrument calibration services encompass the comparison of measurement device outputs against traceable reference standards to quantify and correct deviation, typically performed under controlled environmental conditions with documented uncertainty budgets. These services ensure dimensional, electrical, thermal, and mechanical parameters remain within specified tolerances for quality-critical production, safety systems, and regulatory submissions. Laboratory calibration commands the largest revenue pool due to the capital intensity of climate-controlled facilities and primary standard maintenance, while on-site calibration captures faster growth as just-in-time manufacturing tolerates less instrument downtime. Automated calibration methods are displacing manual workflows in high-volume electrical meter segments, though manual techniques persist for complex multi-variable pressure gauge arrays where technician judgment remains essential.
FDA 21 CFR Part 11 and ISO 17025 shape demand by mandating documented metrological traceability for pharmaceutical and food safety applications, forcing end-users to retain accredited providers with demonstrable measurement uncertainty capabilities. The EU AI Act and Machinery Directive are extending calibration requirements into sensor-equipped autonomous systems, creating new compliance categories for industrial OEMs. Stakeholders must monitor how NIST traceability requirements evolve alongside digital calibration certificates and blockchain-based audit trails.
Market Dynamics
Calibration service providers face mounting pressure to compress turnaround times as pharmaceutical and automotive OEMs adopt just-in-time manufacturing models that tolerate minimal instrument downtime. The convergence of tighter FDA 21 CFR Part 11 documentation requirements and ISO 17025 accreditation standards is forcing mid-tier laboratories to consolidate or exit, reshaping competitive density across industrial corridors.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records and signatures mandates in pharmaceutical manufacturing are expanding quality assurance budgets for documented metrological traceability, pulling demand toward accredited calibration laboratories.
- Automotive OEM clusters:Precision engineering corridors in Germany and Japan require ISO 17025-accredited calibration for metrology chains supporting electric vehicle battery production and autonomous sensor validation.
- RF calibration demand:5G infrastructure deployment and satellite communications proliferation are accelerating requirements for microwave and millimeter-wave instrument calibration in telecommunications manufacturing.
Market Restraints
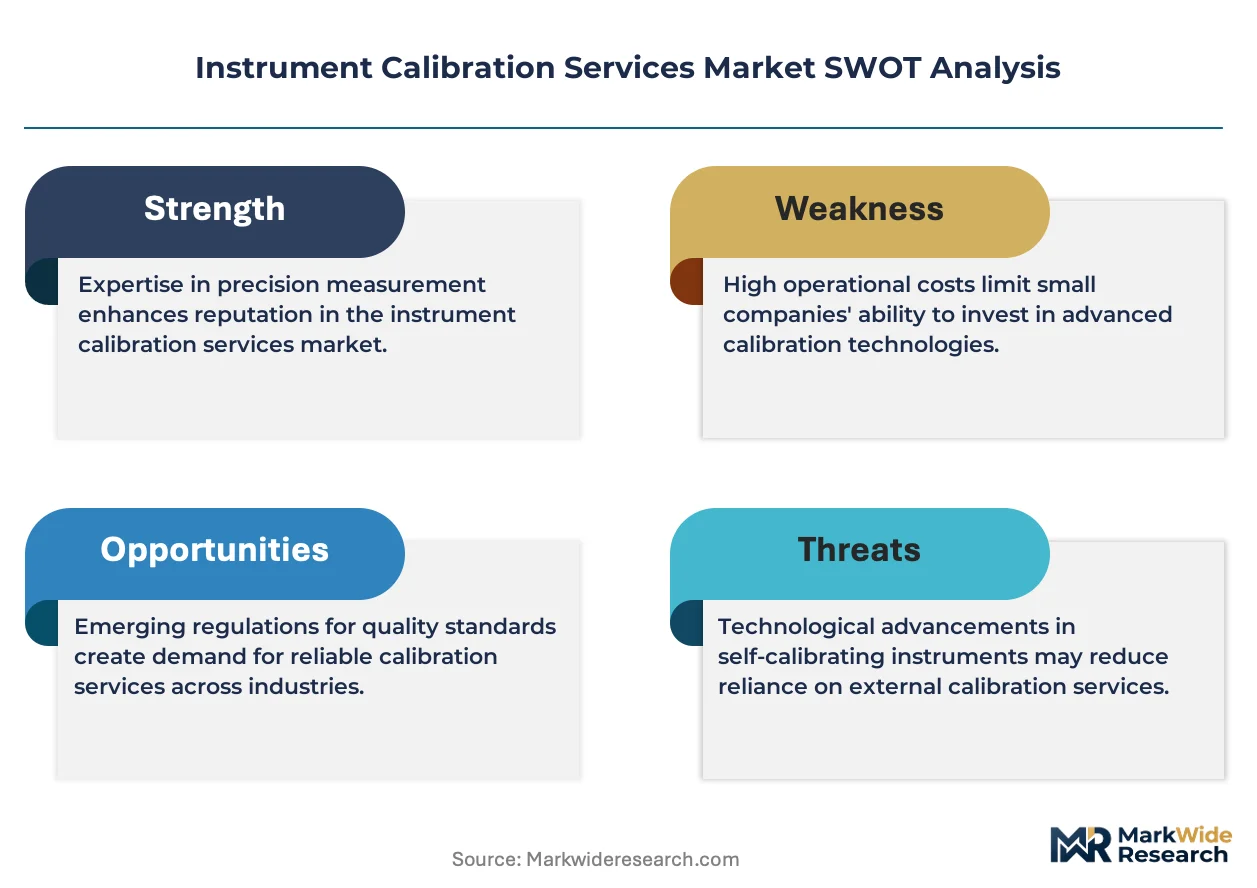
- Primary standard maintenance costs:Climate-controlled laboratory infrastructure and national metrology institute traceability subscriptions impose fixed cost burdens that squeeze margins for regional service providers.
- Technician specialization scarcity:Multi-variable pressure gauge calibration and complex RF measurement uncertainty analysis require rare skill combinations that limit service expansion velocity.
- Automated calibration substitution:High-volume electrical meter segments face displacement by robotic calibration workstations that eliminate manual technician intervention entirely.
Strategic Opportunities
- EU AI Act compliance:Sensor-equipped autonomous systems under the Machinery Directive are creating new calibration categories for industrial OEMs validating AI-driven measurement chains.
- Blockchain audit trails:Digital calibration certificates with immutable documentation are opening premium pricing tiers for pharmaceutical and aerospace clients facing intensified regulatory scrutiny.
- On-site service expansion:Mobile calibration units with environmental control capabilities can capture manufacturing facilities unwilling to ship critical production instrumentation off-site.
Industry Challenges
- Measurement uncertainty documentation:ISO 17025 accreditation requires exhaustive uncertainty budget calculations that extend certification timelines and strain technical staff capacity.
- Legacy system integration:Calibration management software must interface with decades-old enterprise asset management platforms prevalent in established manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instrument Calibration Services Market |
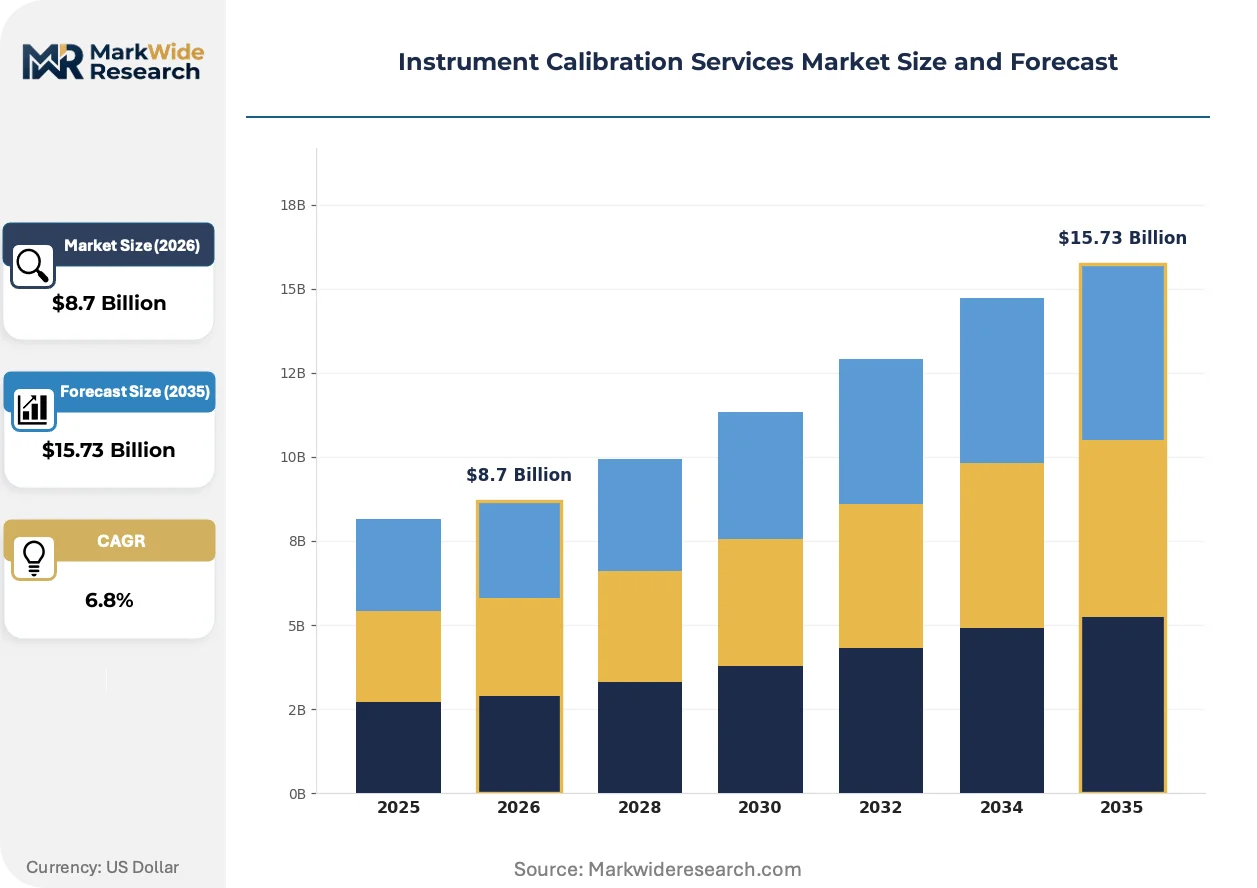
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-site Calibration, Laboratory Calibration, Field Calibration, Accredited Calibration Target Industry: Manufacturing, Aerospace, Healthcare, Telecommunications Calibration Method: Manual Calibration, Automated Calibration, Digital Calibration, Mechanical Calibration Equipment Type: Temperature Sensors, Pressure Gauges, Flow Meters, Electrical Meters |
| Companies Covered | Keysight Technologies, Fluke Corporation, Tektronix, Rohde & Schwarz, Agilent Technologies, Transcat, Trescal Holdings, National Instruments, Endress+Hauser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instrument Calibration Services Market Shifts & Advancements
Digital transformation is penetrating calibration workflows through automated data capture, cloud-based certificate management, and predictive maintenance algorithms that anticipate instrument drift before tolerance breaches occur.
Automated calibration workstations equipped with robotic handlers and machine vision positioning are rendering obsolete manual electrical meter calibration in high-volume manufacturing environments. Tier-one automotive suppliers in Germany and Japan have deployed these systems at scale since 2022, compressing per-unit calibration time from hours to minutes while eliminating technician-induced variability.
The EU AI Act and Machinery Directive are extending calibration requirements into sensor-equipped autonomous systems, forcing industrial OEMs to validate measurement chains within AI-driven decision loops. German automotive manufacturers in Bavaria and Baden-Württemberg are restructuring supplier qualification programs to demand demonstrated metrological traceability for lidar, radar, and camera sensor modules.
Asset-light calibration procurement is displacing long-term service contracts as pharmaceutical and aerospace buyers unbundle after-sales relationships. North American manufacturers now favor spot purchasing through digital platforms that transparently price turnaround time, accreditation scope, and measurement uncertainty, with preference concentrating among multi-site operators seeking vendor consolidation.
Instrument Calibration Services Market Segmentation
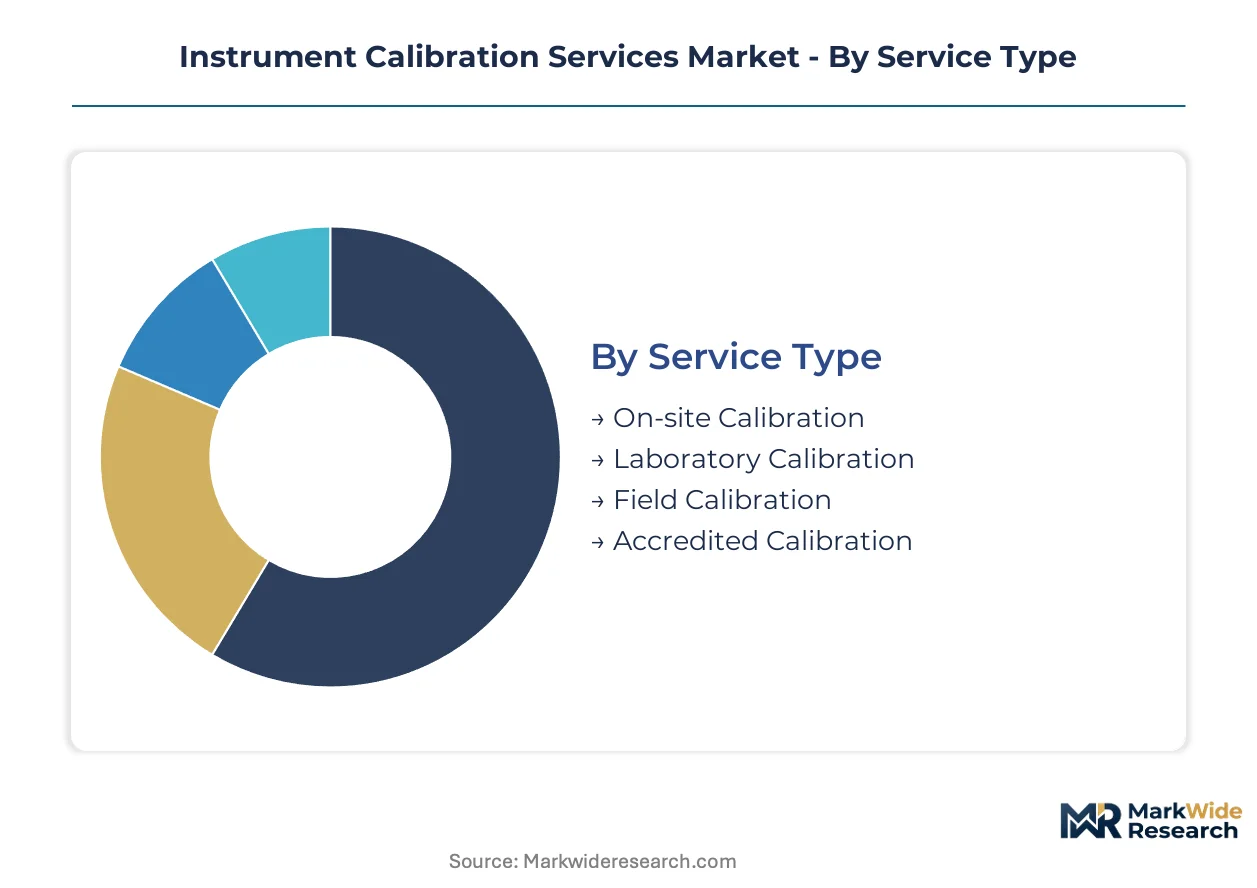
Calibration service procurement patterns diverge sharply across service delivery models, with pharmaceutical and automotive buyers weighing downtime costs against accreditation rigor. Segment boundaries blur as mobile environmental chambers enable laboratory-grade precision at manufacturing sites.
Service Type:
After-sales intensity varies dramatically by service type, with accredited calibration demanding multi-year traceability commitments while on-site offerings compete on emergency response velocity.
- Laboratory Calibration:Climate-controlled facilities with primary standard maintenance generate the highest revenue per engagement. Pharmaceutical manufacturers in Germany and the United States concentrate demand here, driven by FDA 21 CFR Part 11 documentation requirements and ISO 17025 uncertainty budgets that resist field replication.
- On-site Calibration:Mobile units with portable environmental controls reduce instrument downtime for just-in-time production lines. Automotive OEM clusters in Stuttgart and Munich favor this model, though measurement uncertainty capabilities trail fixed laboratories.
- Field Calibration:Technician dispatch to installed equipment addresses infrastructure-scale instrumentation. Utility and telecommunications operators deploy this for distributed sensor networks where shipping is impractical.
- Accredited Calibration:ISO 17025-certified laboratories command premium pricing through demonstrable traceability chains. Aerospace suppliers mandate this tier for regulatory submissions to FAA and EASA.
Laboratory calibration holds the largest share; momentum sits with on-site service expansion.
Target Industry:
Cost tier stratification separates high-compliance verticals willing to absorb accreditation premiums from volume-driven sectors prioritizing turnaround speed.
- Manufacturing:High-volume electrical meter calibration dominates, with automotive and electronics producers in Germany and Japan driving automated workflow adoption. ISO 9001 quality systems mandate periodic calibration without specifying delivery mode.
- Aerospace:NIST-traceable documentation and FAA-compliant uncertainty budgets define procurement. Seattle and Toulouse clusters sustain dedicated service depot networks for flight-critical instrumentation.
- Healthcare:FDA-regulated medical device manufacturing demands 21 CFR Part 11 electronic records. Minnesota and Massachusetts medical technology corridors concentrate accredited laboratory relationships.
- Telecommunications:5G infrastructure deployment accelerates RF and microwave calibration requirements. South Korean and Finnish equipment manufacturers validate millimeter-wave instrumentation for base station production.
Manufacturing commands the largest revenue pool; telecommunications climbs the fastest on 5G and satellite communications proliferation.
Calibration Method:
Volume concentration in electrical meter segments enables automation economies that manual techniques cannot match, while complex multi-variable arrays preserve technician judgment.
- Automated Calibration:Robotic handlers with machine vision positioning compress per-unit processing from hours to minutes. Tier-one automotive suppliers in Bavaria and Baden-Württemberg deployed these systems at scale.
- Manual Calibration:Technician-operated procedures persist for pressure gauge arrays and complex RF configurations where variability demands expert assessment. Small-batch pharmaceutical and aerospace applications retain this mode.
- Digital Calibration:Cloud-connected instruments enable remote drift monitoring and predictive maintenance algorithms. Smart factory initiatives in Japan integrate these capabilities into enterprise asset management platforms.
- Mechanical Calibration:Dimensional and torque instrumentation relies on physical reference artifacts. Precision engineering clusters in Switzerland maintain heritage capabilities for watchmaking and medical device metrology.
Automated calibration dominates high-volume electrical segments; digital methods gain share fastest through Industry 4.0 integration.
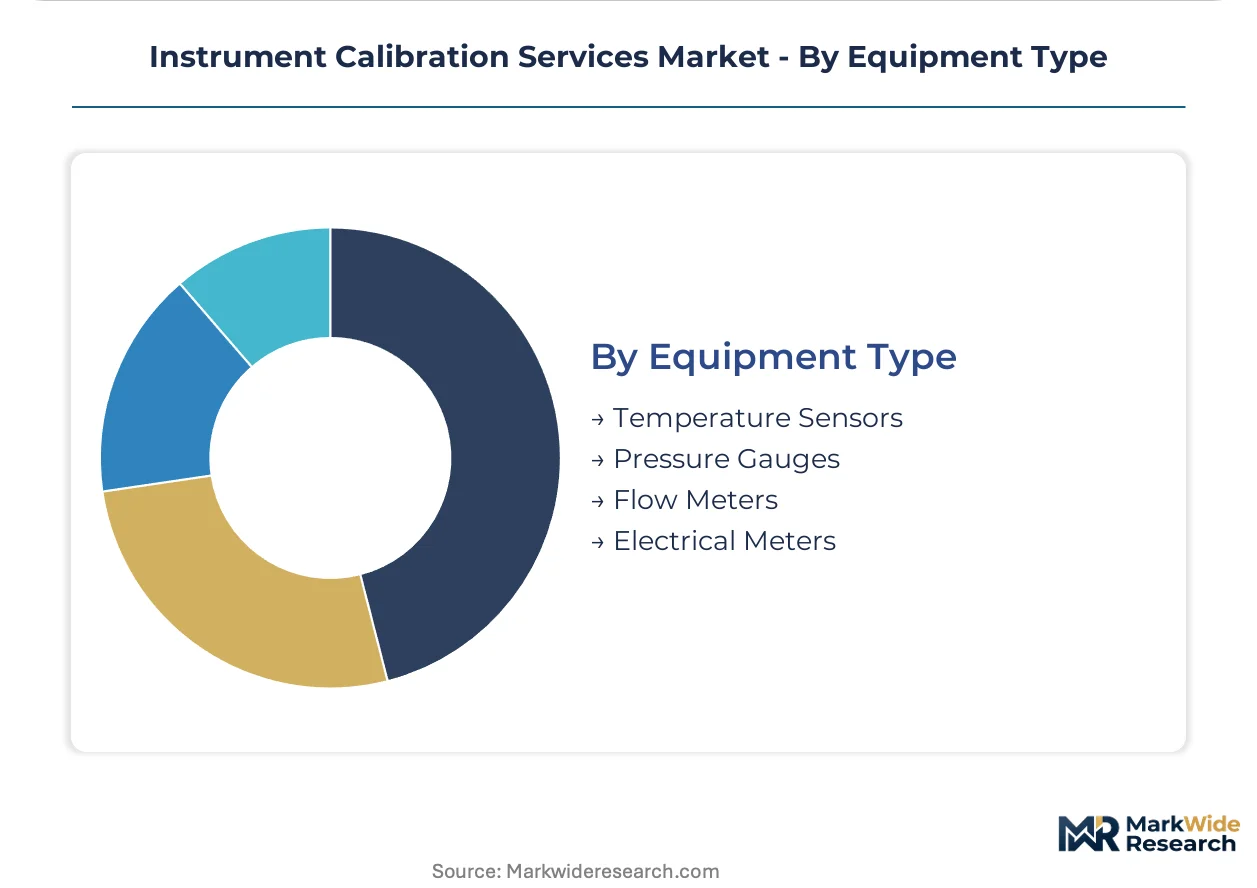
Equipment Type:
Customer type segmentation separates process-critical instrumentation requiring continuous validation from auxiliary equipment with tolerance for extended calibration intervals.
- Electrical Meters:Multimeters, power analyzers, and oscilloscopes constitute the highest calibration volume globally. Manufacturing plants in Germany and the United States generate recurring demand for handheld and benchtop units.
- Temperature Sensors:Thermocouples and RTDs serve pharmaceutical sterilization and semiconductor fabrication. FDA-regulated facilities mandate documented traceability for batch release authority.
- Pressure Gauges:Multi-variable differential and absolute pressure instruments require complex uncertainty analysis. Oil and gas operators in Texas and Alberta sustain specialized service relationships for safety-critical applications.
- Flow Meters:Custody transfer and process control applications demand accredited calibration with Reynolds number matching. Chemical producers in the Netherlands and Belgium prioritize this for batch consistency.
Electrical meters represent the largest equipment category; temperature sensors expand most quickly on biopharmaceutical manufacturing growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites Benelux pharmaceutical distribution, while Germany's Rhine-Main-Danube waterway network anchors precision instrument logistics across Central Europe. These transport arteries concentrate calibration demand in industrial corridors with just-in-time manufacturing tolerances.
United States
FDA 21 CFR Part 11 compliance mandates expand quality assurance budgets across Minnesota and Massachusetts medical technology corridors. The FAA sustains stringent NIST-traceable documentation requirements for Seattle and Los Angeles aerospace clusters. Precision instrument calibration concentrates around Boston's Route 128 biotech belt, where contract manufacturers demand rapid turnaround for production-critical metrology chains.
Germany
Automotive OEMs in Stuttgart and Munich require ISO 17025-accredited calibration for electric vehicle battery production metrology. The EU AI Act extends Machinery Directive compliance into sensor-equipped autonomous systems across Bavaria and Baden-Württemberg. Precision engineering clusters around Karlsruhe and Darmstadt sustain specialized RF calibration relationships for telecommunications equipment manufacturing.
Japan
METI standards enforcement drives automated calibration adoption in Nagoya automotive supplier networks. The PMDA mandates documented traceability for Osaka and Tokyo pharmaceutical manufacturing equipment. Smart factory initiatives in Aichi Prefecture integrate cloud-connected instruments with predictive maintenance algorithms for semiconductor fabrication metrology.
China
NMPA regulatory tightening accelerates accredited laboratory demand in Shanghai and Suzhou pharmaceutical manufacturing zones. MIIT industrial standards propagate through Yangtze River Delta electronics clusters. Shenzhen and Dongguan instrument producers deploy robotic calibration workstations to compress per-unit processing for export-bound electrical meters.
South Korea
MFDS quality system requirements sustain laboratory calibration relationships in Seoul Capital Area biopharmaceutical facilities. 5G infrastructure deployment accelerates millimeter-wave instrument validation for Busan telecommunications equipment manufacturers. Daegu-Gyeongbuk industrial complexes adopt automated calibration methods for high-volume power analyzer production.
Instrument Calibration Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower accreditation scopes. The vendor base stratifies between multinational laboratory networks with primary standard maintenance capabilities and regional service depots competing on emergency response velocity. Three archetypes dominate: accredited laboratory operators with climate-controlled facilities, mobile on-site service providers with portable environmental chambers, and automated workstation manufacturers displacing manual workflows. Consolidation pressures mount as ISO 17025 certification timelines strain mid-tier technical staff capacity, while strategic partnerships between instrument OEMs and calibration houses tighten captive supply relationships.
Among Germany-based precision measurement specialists, Rohde & Schwarz exemplifies premium-tier RF and microwave calibration anchoring through Bavarian laboratory accreditation. Transcat occupies a position within North American service depot density, with geographic coverage spanning aerospace and pharmaceutical manufacturing corridors. Fluke Corporation represents handheld reference equipment dominance, with workflow integration across European electrical meter calibration operations. These three entities illustrate how specialization breadth and accreditation depth determine competitive positioning in fragmented industrial corridors.
| Leading Market Players |
|---|
| Keysight Technologies |
| Fluke Corporation |
| Tektronix |
| Rohde & Schwarz |
| Agilent Technologies |
| Transcat |
| Trescal Holdings |
| National Instruments |
| Endress+Hauser |
| Others |
Supply & Pricing Matrix
The Rhine-Main-Danube waterway network carries precision reference standards between German calibration laboratories and Central European manufacturing clusters, with freight cost volatility compressing margins for regional service providers while enabling accredited operators to sustain premium pricing tiers through faster turnaround guarantees.
Pricing Analysis
Volume-discount tiering structures separate ISO 17025-accredited laboratory calibration from on-site and field service tiers, with pharmaceutical manufacturers absorbing premium rates for documented traceability while automotive OEMs negotiate standardized pricing for high-volume electrical meter programs. Price differentiation hinges on accreditation scope and geographic proximity to primary standards, with margins tightening in commodity electrical segments as automated workstations eliminate technician labor. Aerospace suppliers exhibit lowest price sensitivity due to FAA submission requirements, whereas mid-tier manufacturing buyers drive aggressive spot purchasing through digital procurement platforms.
Supply Chain Analysis
Extended payment terms from pharmaceutical and automotive OEMs strain working capital for mid-tier calibration providers, forcing consolidation among regional laboratories unable to finance climate-controlled infrastructure. Primary standard maintenance draws from Germany, the United States, and Japan, with NIST-traceable artifacts and PTB reference materials anchoring metrological chains. Supply chain risk concentrates in single-source dependencies for specialized RF reference equipment, while distribution runs through accredited laboratory networks and mobile service depots positioned near industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital calibration certificates and blockchain-based audit trails are shifting this market toward platform-economics dynamics, with interoperability between enterprise asset management systems and cloud-based certificate registries determining competitive survival.
For Market Incumbents: Entrench accreditation depth by investing in multi-parameter primary standard capabilities across Bavarian and Baden-Württemberg facilities, while extending mobile environmental chamber fleets to capture on-site demand from just-in-time automotive manufacturers. Consolidate mid-tier competitors facing ISO 17025 certification timeline pressures before automated calibration workstations displace manual service tiers entirely.
For New Entrants and Emerging Players: Pursue white-space opportunities in EU AI Act compliance calibration for sensor-equipped autonomous systems, where demonstrated metrological traceability for lidar and radar modules remains underdeveloped. Target South Korean and Finnish telecommunications equipment manufacturers with millimeter-wave calibration capabilities, leveraging partnerships with RF instrument OEMs to bypass primary standard capital requirements.
For Investors and Strategic Acquirers: Regional service depots with dense geographic coverage and established pharmaceutical relationships represent the most defensible acquisition archetype, given their embedded position in FDA 21 CFR Part 11 compliance workflows. Watch for inflection signals in digital certificate adoption rates, as blockchain-enabled audit trail capabilities will separate premium-tier providers from commodity competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Scope Expansion | Broadening ISO 17025 parameters captures pharmaceutical clients facing tightened FDA documentation mandates. |
| Mobile Service Fleet Deployment | Environmental chamber-equipped units reduce instrument downtime for Stuttgart automotive OEM clusters. |
| Automated Workstation Integration | Robotic calibration compresses per-unit processing for high-volume electrical meter segments. |
| Digital Certificate Platform Development | Blockchain audit trails open premium pricing tiers for aerospace regulatory submissions. |
| RF Calibration Capability Buildout | Millimeter-wave expertise addresses 5G infrastructure deployment in South Korean manufacturing. |
Research Methodology
Desk research of NIST calibration procedure databases, ISO 17025 accreditation registries, and FDA 21 CFR Part 11 guidance documents preceded structured interviews with laboratory operations directors, pharmaceutical quality assurance managers, automotive metrology engineers, and aerospace supplier compliance officers. Secondary validation drew from PTB and NMIJ primary standard documentation, customs records for precision instrument trade flows, and SEC filings of publicly traded calibration service providers. Bottom-up demand modeling triangulated against top-down market sizing across service type, target industry, and equipment category dimensions.
Assumptions held fixed include continued enforcement of FDA 21 CFR Part 11 and ISO 17025 standards, stable primary standard maintenance costs, and sustained just-in-time manufacturing adoption across automotive and pharmaceutical verticals. Variables tested included automated calibration penetration rates, EU AI Act implementation timelines, and blockchain certificate adoption curves. CAGRs derived from segment-level growth drivers across laboratory, on-site, and field service delivery models, with equipment-specific demand weighted by biopharmaceutical manufacturing expansion and 5G telecommunications infrastructure deployment.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles or pharmaceutical R&D funding levels would shift the trajectory. Regulatory changes to NIST traceability requirements or EU Machinery Directive calibration mandates would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Ige Allergy Blood Tests Market
Testing Services
Germany Testing, Inspection and Certification Market
Testing Services
Sickle Cell Anemia Testing and Screening Market
Testing Services
Bleeding Disorders Testing Market
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market
Testing Services
Aerospace and Life Sciences TIC Market
Testing Services
Faecal Calprotectin Testing Market
Testing Services
Thyroid Test Market
Testing Services
Host Cell Protein Testing Market
Testing Services
Global Immunoprecipitation Testing Market
Testing Services
In-Vitro Toxicology Testing Market
Testing Services
Redox Meter Market
Testing Services
Esoteric Testing Market
Testing Services
Nicotine Testing Market
Testing Services
Thrombophilia Testing Market
Testing Services
Mono Rapid Testing Market