
 Global Blood Purification Equipment Market | 2026-2036
Global Blood Purification Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Purification Equipment Market Foresight
German dialyzer manufacturers is rebalancing capacity toward high-flux membrane lines after supply chain disruptions in Asia. Fresenius SE & Co. KGaA anchors European production through captive polymer extrusion facilities. Baxter International, Inc. competes on integrated disposable-to-machine ecosystems. Jafron Biomedical Co., Ltd. dominates adsorption cartridge exports from its Zhuhai base.
Blood purification equipment encompasses electromechanical systems that extract toxins, excess fluids, or pathogenic substances from circulating blood through extracorporeal circuits, typically operating with blood flow rates of 200–500 mL/min and ultrafiltration precision within 10 mL/hour tolerances. Hemodialysis machines command the largest installed base as chronic kidney disease prevalence climbs, while plasmapheresis systems generate premium margins in autoimmune therapeutic protocols. Membrane filtration technology leads volume shipments, though bioartificial systems attract venture funding for liver support applications.
FDA 510(k) pathways and EMA MDR conformity assessments govern device commercialization, with both agencies tightening biocompatibility testing standards for synthetic adsorbents. China's NMPA accelerates review timelines for domestically manufactured CRRT equipment under revised innovation channel rules. Stakeholders must monitor reimbursement parity between home-based and clinic-based modalities as payers recalibrate chronic disease management incentives.
Market Dynamics
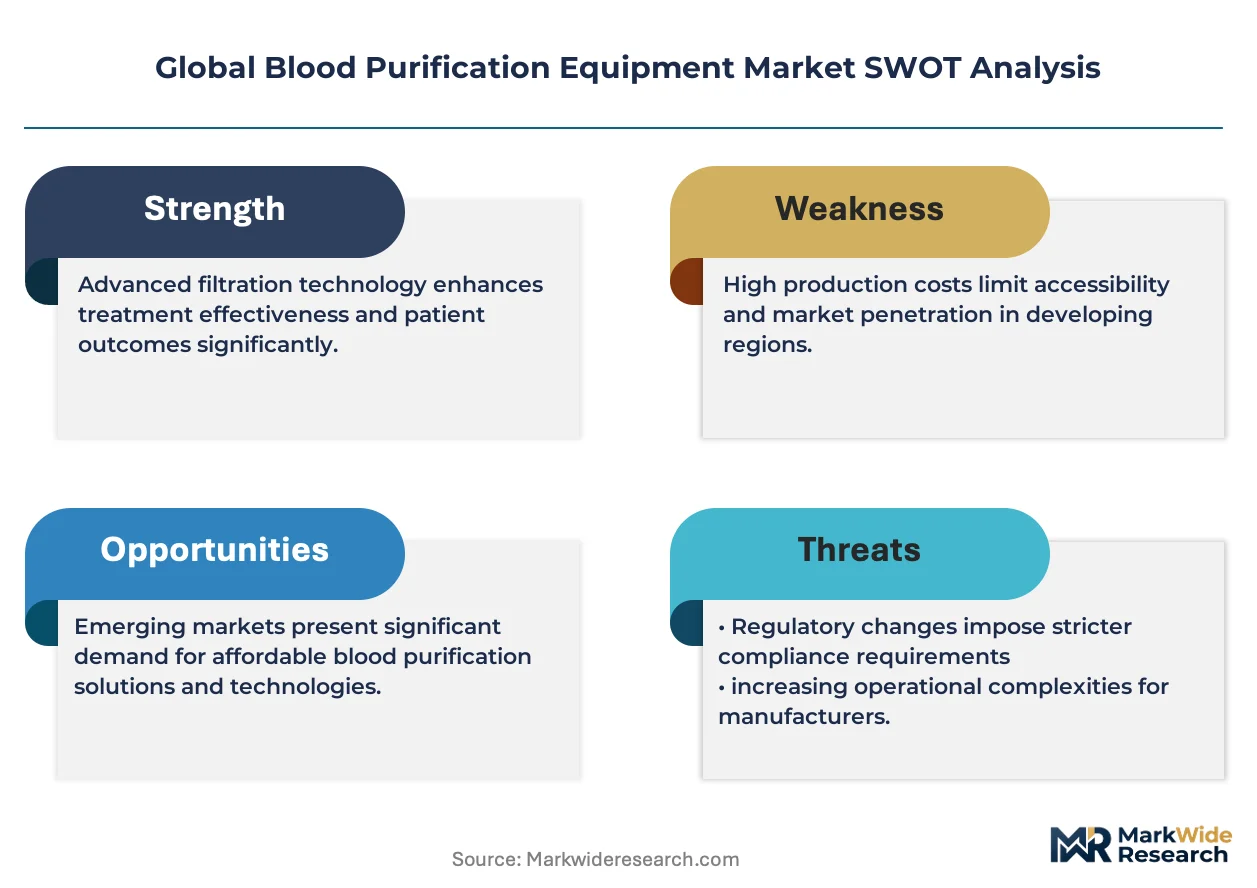
FDA and EMA biocompatibility testing standards are tightening simultaneously, forcing manufacturers to revalidate synthetic adsorbent formulations and extend clinical evidence packages before commercial clearance.
Growth Catalysts
- Chronic Kidney Disease Prevalence:Dialysis centers in the United States, Germany, and China are expanding installed capacity to serve aging populations with diabetes-related renal complications.
- EMA MDR Conformity Assessments:Stricter European device regulations are accelerating hospital procurement of certified high-flux membrane systems with documented safety profiles.
- Bioartificial Liver Support:Venture funding flows toward extracorporeal cellular therapy platforms targeting acute liver failure protocols in tertiary care centers.
Market Restraints
- Polymer Feedstock Volatility:Captive extrusion facilities depend on specialized polysulfone and polyethersulfone resin supplies concentrated in Asian chemical manufacturing clusters.
- Technical Filtration Limitations:Current membrane pore architectures struggle to selectively remove middle-molecular-weight toxins without albumin loss in extended treatments.
- Reimbursement Parity Friction:Payer differentiation between home-based and clinic-based dialysis modalities creates demand uncertainty for portable system developers.
Strategic Opportunities
- Underpenetrated Rural China:County-level hospitals lack continuous renal replacement therapy capacity, creating whitespace for domestically manufactured CRRT equipment under NMPA innovation channel rules.
- Autoimmune Plasmapheresis Expansion:Neurology and rheumatology departments are adopting therapeutic apheresis for myasthenia gravis and Guillain-Barré syndrome protocols.
- Home Hemodialysis Convergence:Wearable artificial kidney prototypes and simplified water purification systems are converging to enable patient-managed nocturnal treatments.
Industry Challenges
- Bioengineer Talent Scarcity:Extracorporeal circuit design requires rare expertise in hemorheology and thrombogenicity assessment that academic programs produce insufficiently.
- 510(k) Timeline Compression:FDA clearance pathways for novel adsorption cartridges demand extended predicate device comparisons and biocompatibility testing protocols.
- Legacy System Integration:Hospital IT infrastructure struggles to interface real-time ultrafiltration data from new machines into existing electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Purification Equipment Market |
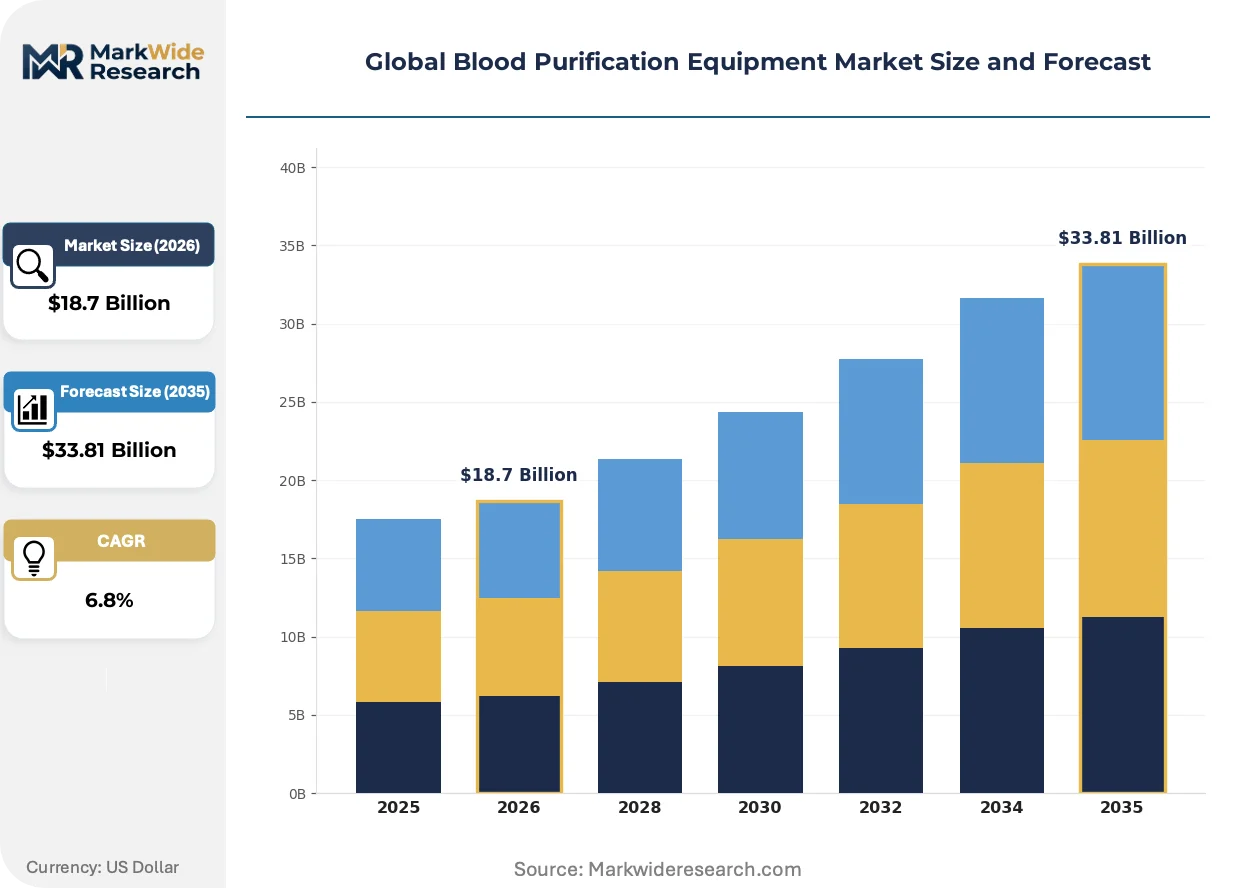
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemodialysis Machines, Hemoperfusion Devices, Plasmapheresis Systems, Continuous Renal Replacement Therapy Machines Technology: Membrane Filtration, Adsorption, Ultrafiltration, Bioartificial Systems Application: Chronic Kidney Disease, Acute Kidney Injury, Liver Failure, Autoimmune Disorders, Poisoning Treatment End User: Dialysis Centers, Specialty Clinics, Research Laboratories, Ambulatory Care Facilities |
| Companies Covered | Cytosorbents Corporation, Baxter International, Inc., Fresenius SE & Co. KGaA, B. Braun Melsungen AG, Jafron Biomedical Co., Ltd., Nikkiso Co, Ltd, Cerus Corporation, Spectra Medical, Inc., Aethlon Medical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Purification Equipment Market Shifts & Advancements
Portable and wearable blood purification systems are compressing the traditional clinic-centric care model, while regulatory agencies on three continents tighten evidence requirements for novel materials.
Portable hemodialysis machines with miniaturized sorbent regeneration cartridges are decentralizing treatment delivery from fixed dialysis centers to patient homes and travel settings. Medicare Advantage plans in the United States are piloting reimbursement for these systems, accelerating manufacturer investment in battery-operated platforms. Home-based modalities are compressing incumbent clinic operators' utilization rates and forcing asset-light service models.
EMA MDR biocompatibility testing standards now mandate extended cytotoxicity and hemocompatibility validation for all new synthetic adsorbent materials entering European markets. Manufacturers must submit comprehensive biological evaluation reports covering complement activation and platelet adhesion profiles. High-flux dialyzer lines with novel membrane chemistries face the steepest compliance burdens and longest review timelines.
Hospital procurement committees are unbundling after-sales service contracts from equipment purchases, forcing manufacturers to compete on transparent parts pricing and remote diagnostic capabilities. German university hospitals lead this shift, demanding predictive maintenance algorithms and guaranteed uptime clauses separate from capital equipment financing. Incumbent suppliers with captive service networks face margin compression as third-party technical service organizations gain certification credentials.
Global Blood Purification Equipment Market Segmentation
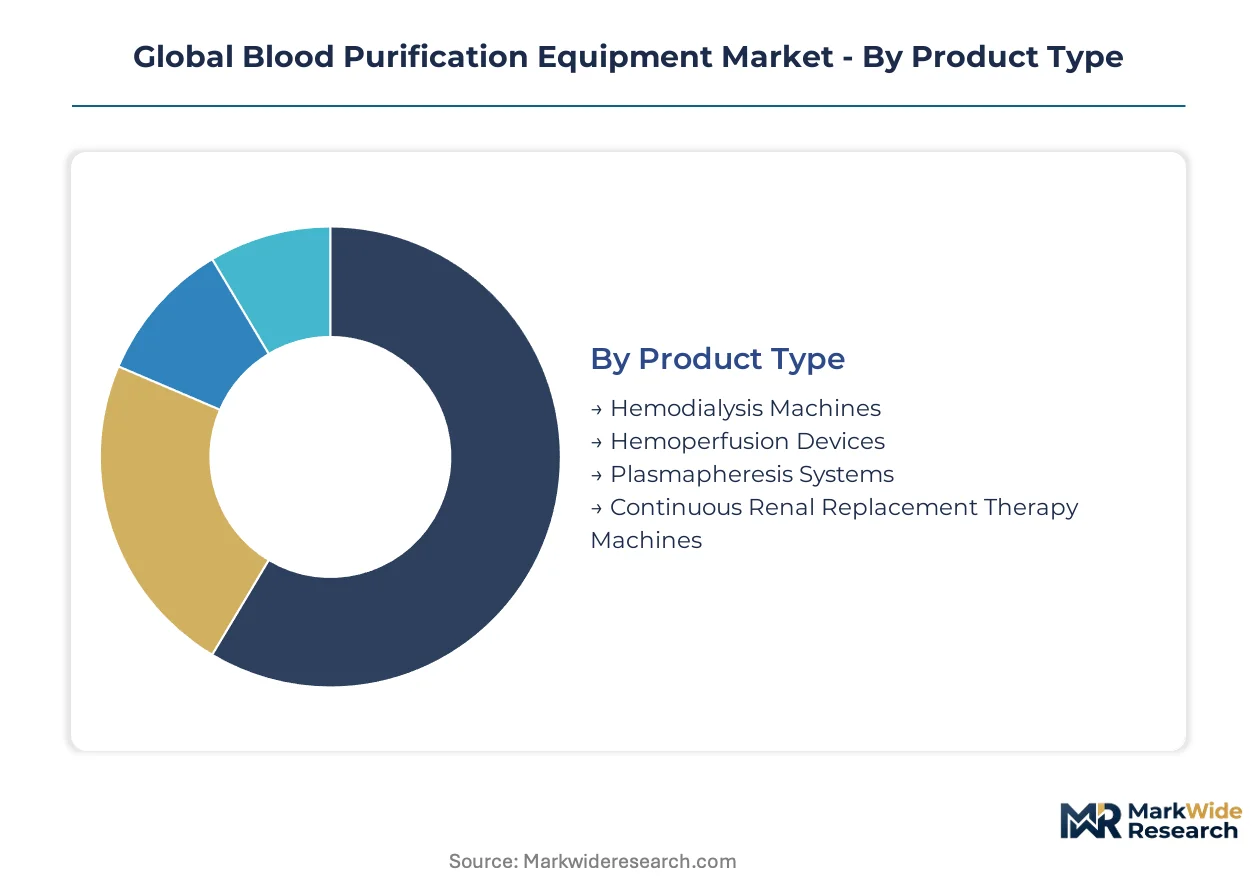
Blood purification equipment segments diverge sharply between high-volume chronic therapy installations and premium-margin acute intervention platforms. Understanding these splits reveals where procurement budgets concentrate and which technology trajectories attract R&D investment.
Product Type:
Hemodialysis machines anchor volume procurement, while specialized acute systems command premium pricing tiers.
- Hemodialysis Machines:These systems process 200–500 mL/min blood flows through hollow-fiber dialyzers, serving chronic kidney disease patients on thrice-weekly schedules. Dialysis centers in the United States, Germany, and China are expanding installed bases to accommodate aging populations with diabetes-related renal complications.
- Plasmapheresis Systems:Centrifugal or membrane-based separation platforms extract plasma for autoimmune therapeutic protocols. Neurology and rheumatology departments in tertiary hospitals are adopting these systems for myasthenia gravis and Guillain-Barré syndrome treatments, generating premium margins through disposable circuit consumption.
- Hemoperfusion Devices:Adsorption-based systems circulate blood through activated carbon or resin cartridges for toxin removal. Emergency departments deploy these for acute poisoning cases.
- Continuous Renal Replacement Therapy Machines:Slower, gentler filtration systems designed for hemodynamically unstable ICU patients. County-level hospitals in China lack this capacity, creating whitespace for domestic manufacturers.
Mature deployment sits with hemodialysis machines. Newer deployment is concentrated in continuous renal replacement therapy machines.
Technology:
Membrane architectures dominate commercial shipments, though bioartificial platforms attract venture funding for organ support applications.
- Membrane Filtration:Polysulfone and polyethersulfone hollow-fiber configurations achieve selective solute clearance through pore size gradients. German manufacturers are rebalancing capacity toward high-flux lines after Asian supply chain disruptions, with EMA MDR biocompatibility testing standards tightening validation requirements for novel membrane chemistries.
- Bioartificial Systems:Extracorporeal cellular therapy platforms incorporate living hepatocytes or renal tubule cells for metabolic support. Liver failure protocols in tertiary care centers are driving venture funding toward these experimental platforms, though FDA 510(k) pathways demand extended clinical evidence packages.
- Adsorption:Synthetic resins and activated carbons bind specific toxins through surface chemistry. Sorbent regeneration cartridges are enabling portable hemodialysis miniaturization.
- Ultrafiltration:Pressure-driven fluid removal without solute clearance, deployed for acute decompensated heart failure. Precision tolerances within 10 mL/hour are mandatory.
Volume leadership belongs to membrane filtration. Steepest expansion trajectory is bioartificial systems.
Application:
Chronic conditions sustain recurring revenue streams, while acute indications drive technology upgrade cycles.
- Chronic Kidney Disease:Long-term dialysis dependency creates predictable equipment utilization and disposable consumption. Medicare Advantage plans in the United States are piloting reimbursement for home-based modalities, compressing traditional clinic-centric service models.
- Autoimmune Disorders:Therapeutic apheresis protocols for neurological and rheumatological conditions require specialized plasma separation. Academic medical centers are expanding service lines for these indications.
- Acute Kidney Injury:ICU-based continuous renal replacement therapy demands 24-hour operational reliability. Hospital procurement committees are unbundling service contracts from equipment purchases.
- Liver Failure:Bioartificial support systems target acute liver failure as a bridge to transplant. Regulatory clearance pathways remain extended.
- Poisoning Treatment:Emergency hemoperfusion for drug overdose and toxic ingestion. Deployment concentrates in urban emergency departments.
Recurring revenue concentrates in chronic kidney disease. Technology upgrade urgency is highest in autoimmune disorders.
End User:
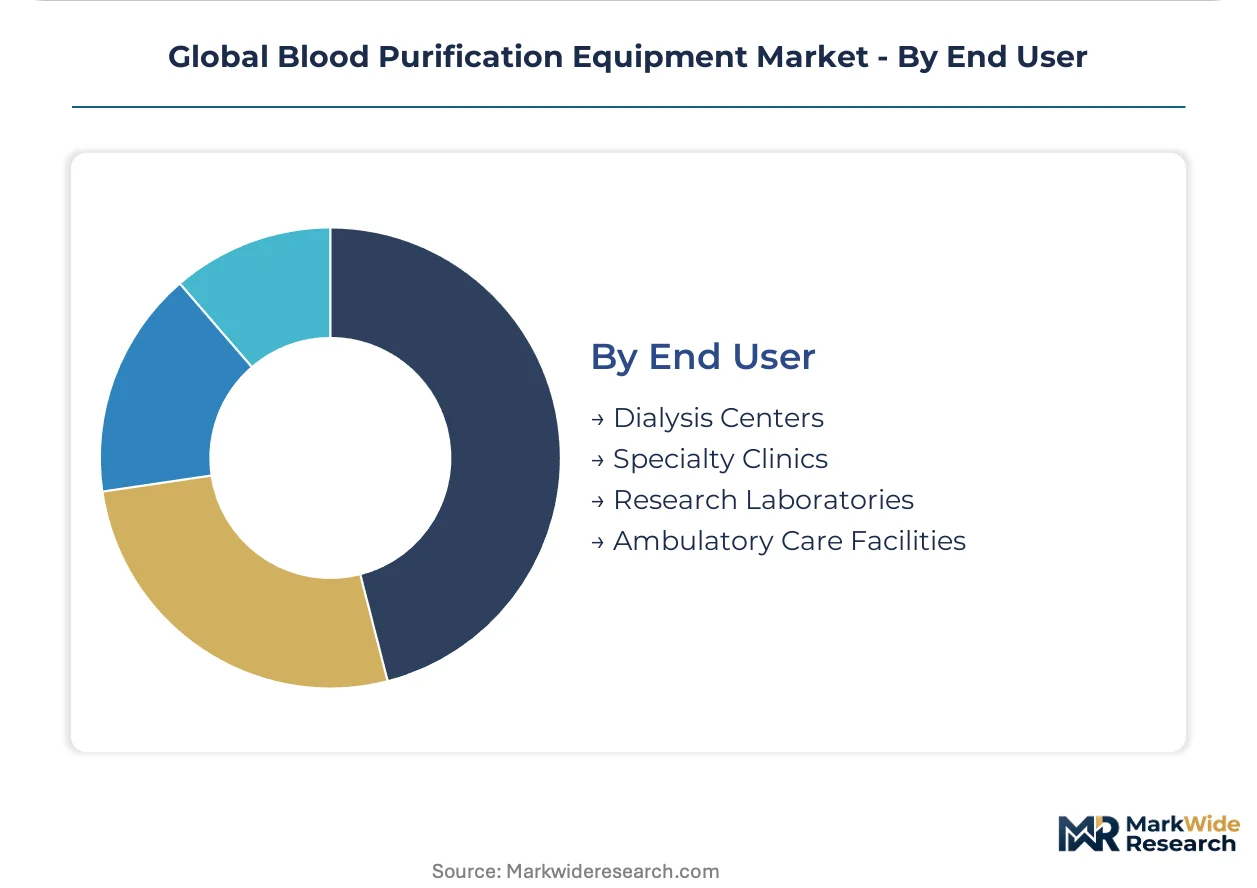
Dialysis centers consolidate purchasing power, while ambulatory settings fragment procurement across smaller-scale decisions.
- Dialysis Centers:Large-scale operators negotiate fleet pricing for hemodialysis machines and captive consumables. Fresenius SE & Co. KGaA and Baxter International, Inc. compete on integrated disposable-to-machine ecosystems, with German university hospitals demanding predictive maintenance algorithms separate from capital financing.
- Specialty Clinics:Neurology and rheumatology-focused facilities procure plasmapheresis systems for therapeutic apheresis. These sites prioritize disposable supply security over equipment capital costs.
- Research Laboratories:Bioartificial system developers and membrane material scientists acquire prototype-scale equipment. NMPA innovation channel rules in China are accelerating domestic CRRT equipment reviews for these users.
- Ambulatory Care Facilities:Smaller-volume sites face reimbursement parity friction between home-based and clinic-based modalities, creating demand uncertainty for portable system developers.
Consolidated purchasing power sits with dialysis centers. Procurement fragmentation is expanding in ambulatory care facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polysulfone and polyethersulfone resin supplies concentrate in Asian chemical manufacturing clusters, particularly around Shanghai and Osaka. German manufacturers maintain captive polymer extrusion facilities to buffer against feedstock volatility. This geographic split shapes procurement patterns across three continents.
United States
Medicare Advantage plans pilot reimbursement for home-based hemodialysis modalities, compressing traditional clinic-centric service models. FDA 510(k) pathways demand extended predicate device comparisons and biocompatibility testing protocols for novel adsorption cartridges. Greater Boston anchors bioartificial liver support venture funding toward extracorporeal cellular therapy platforms.
Germany
University hospitals unbundle after-sales service contracts from equipment purchases, demanding predictive maintenance algorithms separate from capital financing. EMA MDR conformity assessments mandate extended cytotoxicity and hemocompatibility validation for synthetic adsorbent materials. Baden-Württemberg concentrates high-flux membrane manufacturing with captive polymer extrusion capacity.
China
County-level hospitals lack continuous renal replacement therapy capacity, creating whitespace for domestically manufactured equipment. NMPA accelerates review timelines under revised innovation channel rules for CRRT systems. Zhuhai anchors adsorption cartridge export manufacturing from Jafron Biomedical's production base.
Japan
PMDA maintains stringent biocompatibility benchmarks for membrane filtration systems entering domestic markets. METI funding supports wearable artificial kidney prototype development for patient-managed nocturnal treatments. Osaka-Kobe industrial corridor concentrates precision hollow-fiber dialyzer component manufacturing.
Global Blood Purification Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bioartificial organ support applications. The vendor base stratifies across integrated disposable-to-machine ecosystems, specialized adsorption cartridge suppliers, and venture-backed cellular therapy platforms. Three archetypes dominate: captive polymer extrusion specialists, sorbent regeneration innovators, and service-unbundled equipment providers. Competitive moves concentrate on backward integration into resin supply chains and geographic licensing partnerships for regulatory market access.
Within the integrated systems tier, Fresenius SE & Co. KGaA and Baxter International, Inc. exemplify European and North American market anchoring through disposable-to-machine ecosystem control. Jafron Biomedical Co., Ltd. represents the specialized adsorption archetype, occupying a position tied to Zhuhai-based export manufacturing. These three entities illustrate how competitive positioning diverges between captive supply chain control and focused component specialization.
| Leading Market Players |
|---|
| Cytosorbents Corporation |
| Baxter International, Inc. |
| Fresenius SE & Co. KGaA |
| B. Braun Melsungen AG |
| Jafron Biomedical Co., Ltd. |
| Nikkiso Co, Ltd |
| Cerus Corporation |
| Spectra Medical, Inc. |
| Aethlon Medical, Inc. |
| Others |
Supply & Pricing Matrix
Captive polymer extrusion integration by German manufacturers anchors both supply security and premium pricing power against Asian resin volatility. This backward integration into polysulfone and polyethersulfone production shields high-flux membrane lines from feedstock price swings while supporting service-unbundled contract terms demanded by university hospitals.
Pricing Analysis
Warranty and predictive maintenance bundling separates capital equipment quotes from aftermarket service agreements in German procurement. Three-tier pricing structure across premium certified, standard compliant, and economy domestic tiers reflects EMA MDR validation burdens and FDA 510(k) pathway costs. Price differentiation stems from biocompatibility certification grade and geographic service density. Cost compression in economy tiers intensifies as county-level Chinese hospitals prioritize NMPA innovation channel approvals over European compliance. Dialysis centers show lowest price sensitivity due to fleet-scale purchasing power.
Supply Chain Analysis
Single-source vulnerability sits with specialized polysulfone resin production concentrated in China, Germany, and Japan. Raw material flows draw from Shanghai and Osaka chemical clusters for membrane substrates, while captive extrusion facilities in Baden-Württemberg buffer feedstock volatility. Tariff exposure on Asian resin imports threatens margin stability for non-integrated assemblers. Distribution runs through GPO contracts in the United States, direct hospital sales in Germany, and provincial tender processes in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioartificial cellular therapy platforms are displacing membrane filtration in acute liver support applications, compressing technology transition timelines for legacy equipment portfolios.
For Market Incumbents: Cement captive polymer supply through upstream control over Asian resin partnerships or European extrusion capacity expansion. Defend against sorbent regeneration miniaturization by embedding predictive maintenance algorithms in hemodialysis fleet contracts. Prioritize NMPA innovation channel registrations to preempt domestic Chinese CRRT challengers.
For New Entrants and Emerging Players: The premium-economy price gap in portable hemodialysis creates whitespace for battery-operated platforms with simplified water purification. Target county-level Chinese hospitals lacking continuous renal replacement therapy capacity. Pursue Medicare Advantage pilot reimbursement partnerships to bypass entrenched clinic networks.
For Investors and Strategic Acquirers: Exit pathways concentrate in bioartificial platform acquisitions by integrated dialysis ecosystems. Five-to-ten year viability favors cellular therapy developers with FDA breakthrough device designation progress. Watch for EMA MDR conformity assessment timeline compression as inflection signal for membrane chemistry valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR biocompatibility validation unlocks German university hospital procurement committees. |
| Hospital System Partnership | Fresenius and Baxter compete on integrated disposable-to-machine ecosystems through GPO contracts. |
| Reimbursement Strategy | Medicare Advantage home hemodialysis pilots compress traditional clinic-centric service models. |
| Software Companion Development | Predictive maintenance algorithms satisfy German procurement demands for uptime guarantees. |
| Backward Integration | Captive polymer extrusion buffers Jafron and German manufacturers against Asian resin volatility. |
Research Methodology
Independent corroboration across hospital purchasing committees, biomedical engineering directors, and GPO contracts managers underwrites the qualitative findings. Primary interviews with dialysis center operations heads and regulatory affairs specialists at EMA-notified bodies combined with secondary validation from FDA 510(k) filings, NMPA innovation channel announcements, and hospital procurement databases. Bottom-up installed base counts and top-down equipment spending estimates triangulate market sizing.
Comparable-period anchoring to historical dialysis center expansion rates and CRRT adoption curves shaped the projection horizon. The analytical framework models product type, technology architecture, application severity, and end-user purchasing consolidation across the forecast period. CAGRs derive from segment-level growth rate reconciliation against aggregate market trajectory. Inputs include chronic kidney disease prevalence projections and venture funding flows into bioartificial platforms.
Inputs from EMA MDR conformity assessment timelines and NMPA review databases were available through the study window; gaps in real-time county-level Chinese hospital procurement data introduce uncertainty bands. Forecasts reflect assumptions on reimbursement parity evolution and polymer feedstock price stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Fluid Bags Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
Global Radiation Therapy Equipment Market
Medical Equipment
Proctologic Table Market
Medical Equipment
Clinical Microscopes Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Terminal Sterilization Market
Medical Equipment
Life Support Systems Market
Medical Equipment
Urodynamic Equipment and Consumables Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
Healthcare Simulators Market
Medical Equipment
Centrifuge Market
Medical Equipment
Global Operating Table Mattresses Market
Medical Equipment
Refurbished MRI Systems Market