
 North America Medical Carts Market | 2026-2036
North America Medical Carts Market Size, Share, and Industry Trends Forecast 2026-2036
North America Medical Carts Market Analytics
UL 60601-1 certification for medical electrical equipment is unwinding the competitive landscape, forcing smaller fabricators to absorb testing costs or exit hospital procurement channels. Capsa Healthcare leverages its vertically integrated manufacturing footprint in the Pacific Northwest to sustain price competitiveness on medication carts. Ergotron, Inc. anchors its position through ergonomic design patents that dominate the powered workstation segment. Harloff Company differentiates via specialized procedure cart configurations for emergency departments.
North America medical carts are wheeled healthcare furniture systems engineered to transport equipment, medications, and supplies within clinical environments, typically constructed from powder-coated steel or antimicrobial polymer composites with load ratings exceeding 150 pounds and caster systems tested to ANSI/BIFMA standards. Their primary purpose is to enable mobile point-of-care delivery while maintaining infection control protocols and electrical safety for integrated devices. Mobile carts lead product type demand as hospitals replace fixed-wall workstations with flexible fleet deployments. Stainless steel material selections command premium positioning in operating suites and sterile processing departments where autoclave compatibility governs procurement. Emergency rooms represent the fastest-growing end user channel as throughput pressures drive investment in crash cart standardization.
FDA 510(k) clearance requirements for carts incorporating powered devices, Joint Commission environment-of-care standards, and OSHA ergonomic guidelines collectively shape product development priorities and hospital purchasing criteria across the United States and Canada. State-level e-prescribing mandates and DEA controlled-substance storage regulations further segment medication cart feature requirements. Stakeholders must monitor how cybersecurity frameworks for networked medical devices extend to smart carts with embedded computing and wireless connectivity.
Market Dynamics
Hospital consolidation across the United States and Canada is compressing supplier bases and mandating fleet standardization, forcing cart manufacturers to absorb compliance costs while defending price positions against integrated health system procurement offices.
Growth Catalysts
- Joint Commission environment-of-care standards:Accreditation requirements for infection control and electrical safety are accelerating replacement cycles for aging cart fleets in U.S. acute care facilities.
- Powered mobile computing:Battery-swappable workstation platforms are enabling point-of-care documentation at the bedside, driving procurement in emergency departments and perioperative suites.
- Great Lakes hospital corridor concentration:Health system headquarters in Chicago, Cleveland, and Detroit are consolidating purchasing decisions, creating volume opportunities for vendors meeting unified specifications.
Market Restraints
- UL 60601-1 testing cost structure:Third-party certification for medical electrical equipment imposes five-figure validation burdens that smaller metal fabricators cannot amortize across limited production runs.
- Steel and aluminum input volatility:Powder-coated steel chassis and antimicrobial polymer composites face commodity price swings that compress margin visibility on multi-year hospital contracts.
- FDA 510(k) clearance timelines:Powered cart configurations with integrated computing require premarket notification reviews that extend product launch windows by nine to fourteen months.
Strategic Opportunities
- Canadian provincial health authority consolidation:Ontario and British Columbia are centralizing medical equipment procurement, creating entry points for U.S. manufacturers with Health Canada-compliant product lines.
- Cybersecurity framework extension:FDA guidance on networked medical devices is creating demand for smart carts with embedded encryption and wireless access point isolation.
- DEA controlled-substance storage mandates:State-level e-prescribing regulations are expanding the addressable market for medication carts with biometric locking and audit trail capabilities.
Industry Challenges
- ANSI/BIFMA caster testing bottlenecks:Load-rated mobility systems require specialized laboratory validation that extends supplier qualification timelines.
- OSHA ergonomic guideline implementation:Hospital risk managers are rejecting cart designs that fail height-adjustability standards, forcing redesign cycles on legacy platforms.
- Legacy wall workstation integration:IT departments face cabling and power infrastructure conflicts when migrating from fixed installations to mobile fleet deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Medical Carts Market |
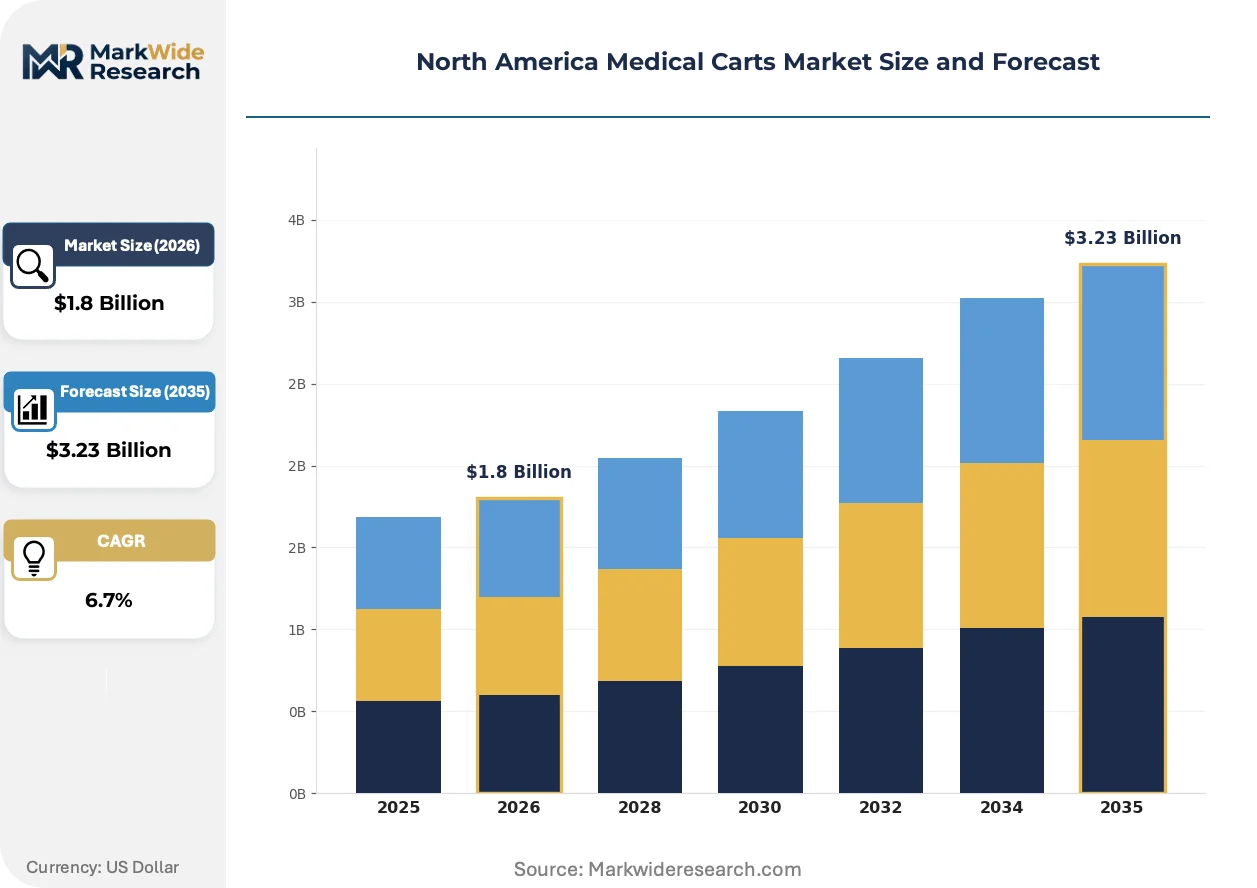
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Carts, Mobile Carts, Procedure Carts, Medication Carts End User: Hospitals, Clinics, Long-term Care Facilities, Emergency Rooms Material: Stainless Steel, Aluminum, Plastic, Wood Application: Patient Transport, Equipment Storage, Medication Delivery, Procedure Support |
| Companies Covered | Capsa Healthcare, Ergotron, Inc., Harloff Company, Omnicell, Inc., Medline Industries, Inc., AFC Industries Inc., TouchPoint Medical, Armstrong Medical Industries, Inc., Enovate Medical, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Medical Carts Market Evolving Landscape
Antimicrobial material science and embedded computing architectures are converging to redefine cart functionality, while procurement centralization is compressing the vendor landscape. Three developments are commanding strategic attention.
Lithium iron phosphate battery systems are displacing sealed lead-acid power modules in powered workstation carts. Hospital materials management departments are specifying these platforms for twenty-four-hour clinical shifts. The technology is displacing incumbent chemistries by eliminating mid-shift battery swaps and reducing total cost of ownership calculations.
FDA draft guidance on cybersecurity for networked medical devices is tightening design requirements for smart carts with wireless connectivity. Manufacturers must now document threat modeling and software bill of materials submissions. Emergency departments and perioperative suites are most affected, with buyers demanding pre-integrated encryption modules rather than aftermarket retrofit.
Health system procurement offices are consolidating vendor panels and mandating enterprise-wide cart standardization. Independent hospitals are losing autonomy over equipment selection as regional headquarters centralize purchasing. This concentration is most visible in the U.S. Northeast, where Catholic health systems and academic medical centers are unifying specifications across dozens of facilities.
North America Medical Carts Market Segmentation
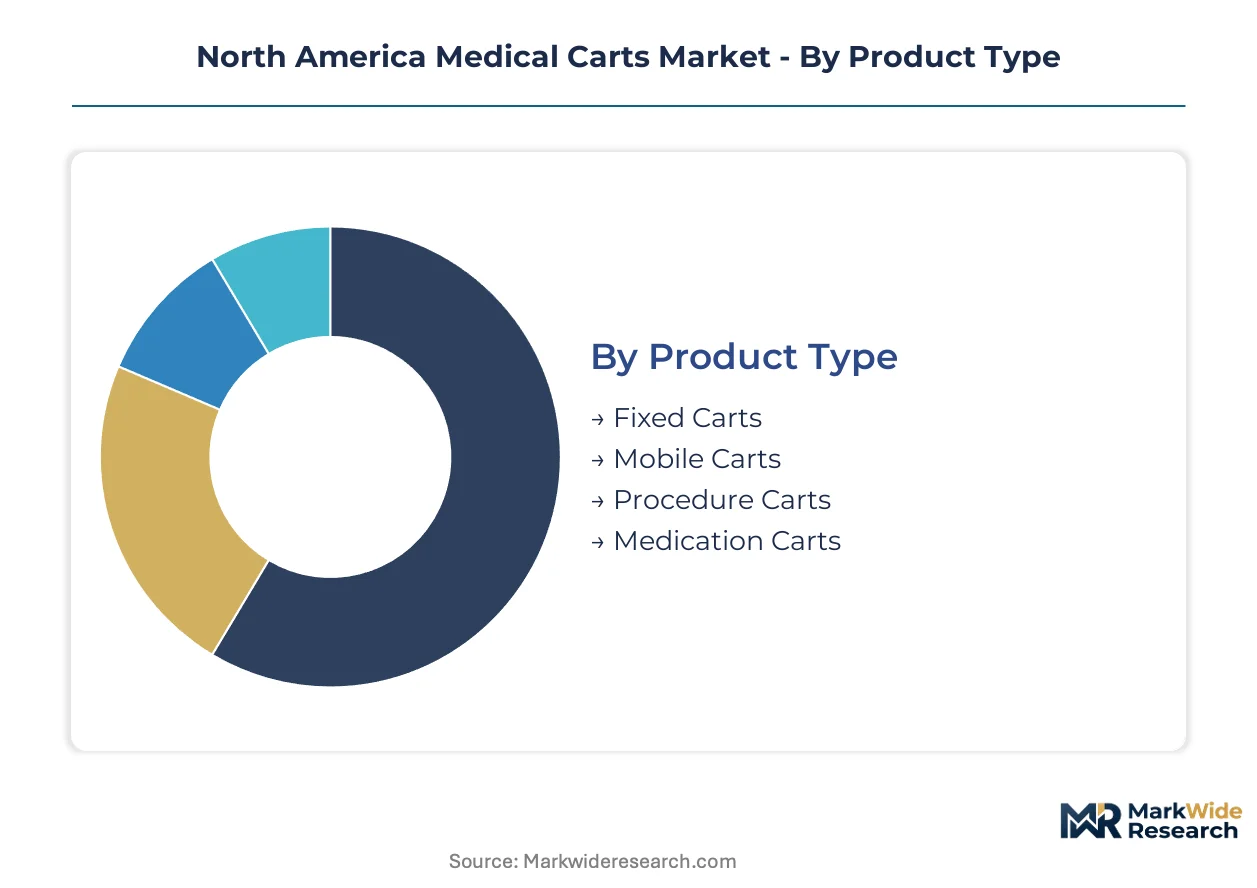
Medical cart procurement across the United States and Canada fragments across four distinct classification axes. Each dimension carries specific regulatory, technical, and budgetary implications that reshape vendor positioning and health system purchasing criteria.
Product Type:
Fixed-wall installations face the most acute substitution pressure from mobile fleet deployments as hospitals prioritize flexibility over permanent infrastructure.
- Mobile Carts:Battery-integrated platforms with hot-swappable power modules enable continuous bedside computing across twenty-four-hour clinical shifts. Demand concentrates in emergency departments and perioperative suites at academic medical centers in the U.S. Northeast, where Joint Commission environment-of-care standards accelerate replacement cycles for aging fleets.
- Medication Carts:Biometric locking systems and automated dispensing drawers address DEA controlled-substance storage mandates and state-level e-prescribing regulations. Health system consolidation across the Great Lakes corridor is standardizing specifications for these units, compressing supplier bases and favoring vendors with vertically integrated manufacturing footprints.
- Procedure Carts:Configured for crash cart standardization in high-throughput emergency settings.
- Fixed Carts:Wall-mounted workstations with declining procurement volumes as mobile alternatives gain preference.
Mobile carts anchor the volume base while medication carts gain share at the steepest rate.
End User:
Cost tier segmentation separates capital-intensive hospital deployments from budget-constrained outpatient and post-acute settings.
- Hospitals:Multi-site health systems command enterprise-scale procurement volumes with unified technical specifications. U.S. acute care facilities in the Great Lakes and Northeast corridors drive fleet standardization mandates that reshape vendor competitive dynamics.
- Emergency Rooms:Throughput pressures and crash cart standardization requirements fuel the steepest expansion trajectory among all end-user channels. These units demand rapid-deployment configurations with integrated power and infection control features.
- Clinics:Outpatient facilities prioritize cost efficiency and space optimization over advanced feature sets.
- Long-term Care Facilities:Skilled nursing and assisted living operators face reimbursement constraints that limit capital equipment refresh cycles.
Hospitals dominate absolute procurement value while emergency rooms expand most quickly as a channel.
Material:
Application environment dictates material selection, with sterile processing and surgical settings imposing the most stringent durability and compatibility requirements.
- Stainless Steel:Autoclave-compatible chassis with antimicrobial surface properties command premium positioning in operating suites and sterile processing departments. These specifications align with FDA device classification frameworks and tightening infection control protocols.
- Plastic:Antimicrobial polymer composites reduce weight and enable color-coded departmental identification systems. Powder-coated formulations face commodity price volatility that compresses margin visibility on multi-year hospital contracts.
- Aluminum:Lightweight structural components for mobility-intensive applications with moderate load requirements.
- Wood:Limited to non-clinical administrative and patient comfort applications with minimal regulatory exposure.
Stainless steel captures premium segment value while plastic dominates unit volume across standard care environments.
Application:
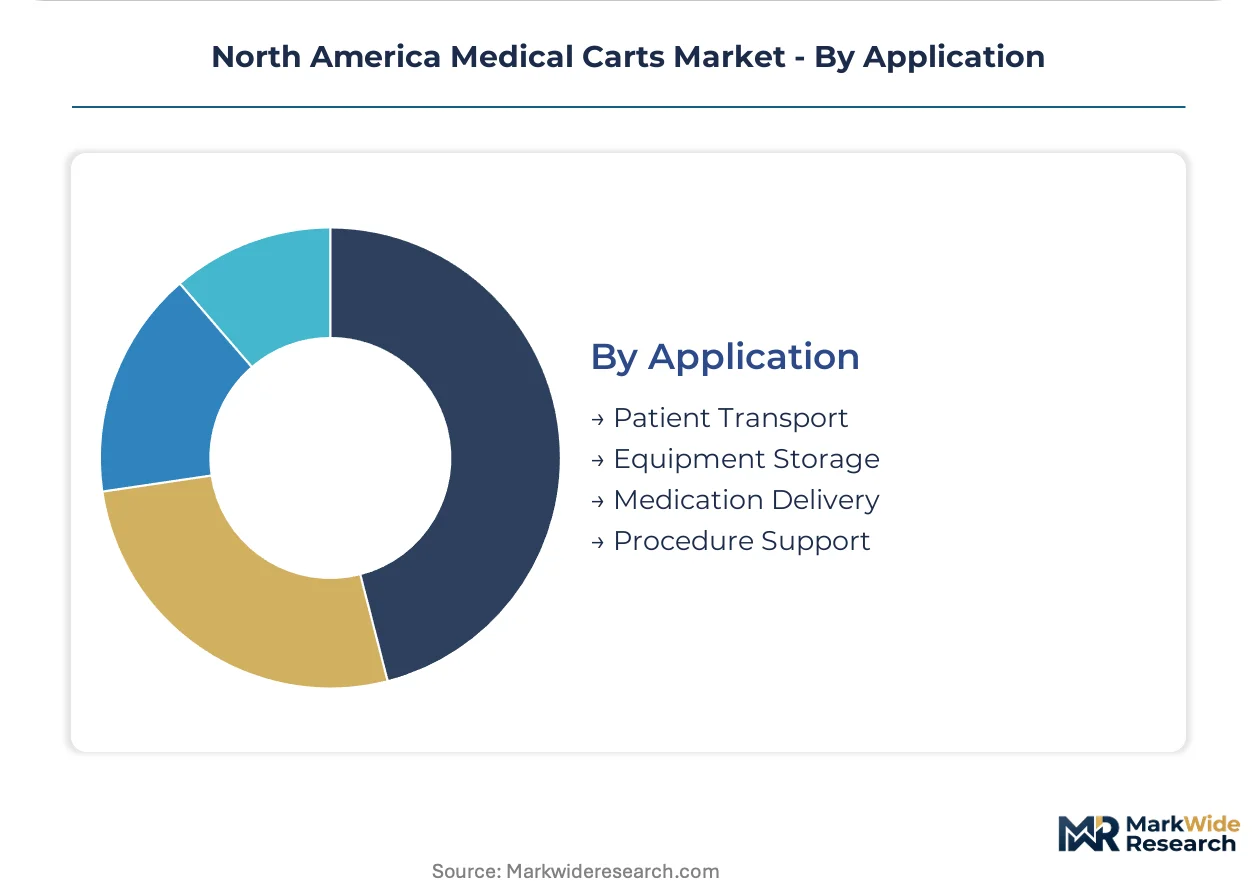
Customer workflow integration separates point-of-care computing platforms from storage and logistics-focused configurations.
- Equipment Storage:General supply and device transport functions with established procurement patterns and limited technology differentiation.
- Medication Delivery:Integrated computing, barcode verification, and controlled-substance security features align with DEA regulations and state e-prescribing mandates.
- Patient Transport:Specialized chassis with load ratings exceeding ANSI/BIFMA standards for safe intra-facility movement.
- Procedure Support:Emergency and perioperative configurations with rapid-access drawer systems and power integration.
Equipment storage maintains the largest installed base while medication delivery applications climb the fastest on regulatory compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA device classification frameworks and Joint Commission accreditation standards are tightening electrical safety requirements across hospital systems. Health system consolidation in the Great Lakes and Northeast corridors is standardizing procurement specifications and compressing supplier bases.
United States
The Great Lakes hospital corridor anchored by Chicago, Cleveland, and Detroit is consolidating purchasing decisions across multi-site health systems. FDA 510(k) clearance requirements for powered carts with integrated computing extend product launch timelines. Academic medical centers in the U.S. Northeast are unifying specifications across dozens of facilities under Catholic health system and university hospital networks.
Canada
Ontario and British Columbia are centralizing medical equipment procurement through provincial health authority consolidation. Health Canada medical device regulations align with FDA frameworks while maintaining distinct labeling and quality system requirements. Vancouver and Toronto health clusters are creating entry points for U.S. manufacturers with compliant product lines.
Mexico
Border state hospital systems in Baja California and Chihuahua are expanding capacity through public-private partnership models. Federal Commission for Protection against Sanitary Risk (COFEPRIS) medical device regulations govern importation and local manufacturing. Monterrey and Tijuana medical device manufacturing clusters are developing regional supply capabilities for North American distribution.
North America Medical Carts Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, creating a bifurcated structure where scale advantages meet niche compliance expertise. Publicly traded automation vendors and privately held metal fabricators coexist across distinct procurement channels. Three archetypes dominate: vertically integrated manufacturers with captive testing laboratories, ergonomic design specialists holding patent portfolios, and regional fabricators serving single-state hospital networks. Consolidation pressures and enterprise fleet standardization are the dominant competitive moves reshaping vendor positioning.
Among Pacific Northwest-based manufacturers, Capsa Healthcare exemplifies the vertically integrated archetype with manufacturing footprint control. Ergotron, Inc. occupies a position representing ergonomic design specialization in powered workstation segments. Harloff Company anchors the procedure-specific configuration tier for emergency department applications.
| Leading Market Players |
|---|
| Capsa Healthcare |
| Ergotron, Inc. |
| Harloff Company |
| Omnicell, Inc. |
| Medline Industries, Inc. |
| AFC Industries Inc. |
| TouchPoint Medical |
| Armstrong Medical Industries, Inc. |
| Enovate Medical |
| Others |
Value Network & Pricing Analysis
Ninety-day steel and aluminum inventory cycles at Pacific Northwest fabricators concentrate pricing power with vertically integrated manufacturers while forcing smaller metalworkers into spot-market vulnerability on powder-coated chassis and antimicrobial polymer inputs.
Pricing Analysis
Certification level creates the primary spread across the North America medical carts market, with UL 60601-1-validated powered workstations commanding premium positioning against uncertified storage units. Three-tier pricing structure across premium, standard, and economy levels reflects this compliance hierarchy, with FDA 510(k) clearance adding further differentiation. Cost compression in the standard tier is intensifying because health system procurement offices are consolidating vendor panels and mandating fleet standardization. Outpatient clinics and long-term care facilities exhibit the highest price sensitivity, while academic medical centers prioritize certification and ergonomic specifications over unit cost.
Supply Chain Analysis
Port congestion on the Shanghai-Long Beach trade lane elevates inbound logistics costs for antimicrobial polymer resins and lithium iron phosphate battery cells sourced from East Asian suppliers. Manufacturing concentration centers on the United States, Mexico, and Canada, with Monterrey and Tijuana clusters developing regional supply capabilities for North American distribution. Raw material dependencies include powder-coated steel, aluminum structural components, and medical-grade polymer composites. Single-source vulnerability in battery cell supply creates exposure to semiconductor-style allocation constraints. Distribution runs through group purchasing organizations and direct health system contracts, bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins are compressing as procurement centralization accelerates, yet software-enabled fleet management and cybersecurity upgrade subscriptions are expanding at multiples of base equipment sales, creating a durable service-attach layer.
For Market Incumbents: Secure UL 60601-1 testing laboratory accreditation to internalize certification costs and accelerate product launch timelines against smaller competitors facing five-figure third-party validation burdens. Expand backward integration into powder-coated steel fabrication to buffer commodity price volatility on multi-year hospital contracts. Lock in preferred supplier status with consolidating Great Lakes health systems before procurement offices finalize enterprise-wide cart standardization mandates.
For New Entrants and Emerging Players: Differentiate on embedded cybersecurity architectures pre-integrated with FDA draft guidance for networked medical devices, targeting emergency departments where smart cart demand outpaces established vendor capacity. Penetrate the Canadian provincial health authority segment through Health Canada-compliant product lines as Ontario and British Columbia centralize medical equipment procurement. Pursue direct contracting with independent hospitals losing autonomy under regional health system consolidation.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because vendor panel compression and fleet standardization mandates favor scale operators with captive testing infrastructure and multi-site service networks. Target acquisition candidates with Health Canada registrations and established relationships with Catholic health system networks in the U.S. Northeast. Monitor FDA cybersecurity guidance finalization as the inflection signal for smart cart valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| UL 60601-1 Testing Laboratory Accreditation | Internalizes five-figure validation costs and compresses product launch timelines against smaller metal fabricators. |
| Health Canada Registration Pathway | Creates entry points into Ontario and British Columbia provincial procurement centralization. |
| Hospital System Partnership | Locks in preferred supplier status before Great Lakes and Northeast corridor standardization mandates finalize. |
| Software Companion Development | Captures cybersecurity upgrade subscriptions expanding faster than base hardware sales. |
| Backward Integration into Steel Fabrication | Buffers margin compression from powder-coated steel commodity price volatility on multi-year contracts. |
Research Methodology
The analysis maps mobile carts, medication carts, procedure carts, and fixed installations, each validated through hospital purchasing committees, biomedical engineers, GPO contracts managers, and health system procurement executives. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, Joint Commission accreditation databases, hospital procurement records, and steel and aluminum commodity trade data. Bottom-up unit demand modeling and top-down health system capital expenditure triangulation anchored volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include product type, end user channel, material specification, and application workflow. CAGRs derived from replacement cycle analysis, fleet standardization adoption curves, and regulatory compliance-driven upgrade patterns. Forecast inputs incorporated Joint Commission environment-of-care standard revision timelines and provincial health authority consolidation schedules.
Material uncertainties — FDA cybersecurity guidance finalization, steel and aluminum commodity price shocks, and health system merger completion rates — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement intensity and procurement centralization velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Apheresis Equipment Market
Medical Equipment
Europe Medical Carts Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
Surgical Lighting System Market
Medical Equipment
Medical Cart Battery Market
Medical Equipment
Cell Culture Incubator Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
US Radiotherapy Market
Medical Equipment
Global Medical Carts Market
Medical Equipment
New-Born Screening Equipment Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Global Surgical Table Market
Medical Equipment
Electric Bed Market
Medical Equipment
Autoclaves Market
Medical Equipment
Medical Equipment Management Software Market