
 North America Biobanks Market | 2026-2036
North America Biobanks Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biobanks Market Analytics
The FDA's 21st Century Cures Act implementation is restructuring compliance obligations for biobank operators across the United States. Thermo Fisher Scientific leverages its end-to-end cold-chain infrastructure to dominate sample storage logistics in high-volume research corridors. Becton, Dickinson and Company anchors its position through automated biospecimen processing systems that reduce contamination risk in clinical-grade repositories. Qiagen N.V. specializes in nucleic acid stabilization chemistries that differentiate its offering for genomic biobanking workflows.
A biobank constitutes a structured repository of biological specimens—human tissues, cells, blood derivatives, DNA, RNA, and associated clinical data—maintained under controlled temperature regimes, typically between minus 80 degrees Celsius and liquid nitrogen vapor-phase storage, to preserve molecular integrity for longitudinal research. These facilities serve as critical infrastructure for translational medicine, enabling reproducible biomarker discovery and therapeutic target validation across pharmaceutical and academic research programs. Disease-specific biobanks command concentrated investment as oncology and rare-disease sponsors prioritize annotated cohorts with linked clinical outcomes. Blood samples represent the highest-throughput matrix, though tissue biobanks capture premium valuation where spatial transcriptomics and organoid derivation require fresh-frozen archival quality.
The FDA, Health Canada's Biologics and Genetic Therapies Directorate, and the NIH's Genomic Data Sharing Policy collectively govern specimen consent protocols, chain-of-custody documentation, and cross-border data transfer limitations that shape operational scope for biobank administrators. The Office for Human Research Protections and institutional review boards enforce evolving informed-consent standards that directly affect sample usability for secondary research applications. Stakeholders must monitor emerging state-level bioprivacy legislation in California and New York that could fragment compliance requirements beyond federal baselines.
Market Dynamics
The FDA's 21st Century Cures Act implementation is restructuring compliance obligations for biobank operators across the United States. Thermo Fisher Scientific leverages its end-to-end cold-chain infrastructure to dominate sample storage logistics in high-volume research corridors. Becton, Dickinson and Company anchors its position through automated biospecimen processing systems that reduce contamination risk in clinical-grade repositories. Qiagen N.V. specializes in nucleic acid stabilization chemistries that differentiate its offering for genomic biobanking workflows.
Growth Catalysts
- Precision oncology pipelines:Pharmaceutical sponsors are expanding biorepository partnerships to accelerate biomarker discovery and therapeutic target validation programs.
- NIH Genomic Data Sharing Policy:Federal mandates for data accessibility are driving standardization investments across academic medical centers.
- Liquid nitrogen vapor-phase storage:Advanced cryopreservation protocols are extending molecular integrity windows for longitudinal research cohorts.
Market Restraints
- Specialized cold-chain logistics:Transportation of specimens between minus 80 degrees Celsius and liquid nitrogen temperatures requires capital-intensive infrastructure.
- Consent protocol fragmentation:Evolving informed-consent standards from the Office for Human Research Protections create sample usability uncertainty for secondary research.
- Cross-border data transfer limitations:Health Canada's Biologics and Genetic Therapies Directorate imposes restrictions that constrain operational scope for multinational biobank networks.
Strategic Opportunities
- California bioprivacy legislation:Emerging state-level mandates could create first-mover advantages for compliance-ready operators.
- Spatial transcriptomics demand:Fresh-frozen tissue archival requirements are elevating premium valuations for high-quality biorepositories.
- Organoid derivation workflows:Three-dimensional cell culture applications are opening new service revenue streams for tissue biobanks.
Industry Challenges
- Chain-of-custody documentation:FDA and institutional review boards enforce escalating audit requirements that strain quality management systems.
- Annotation specialist scarcity:Clinical data linkage expertise remains concentrated among northeastern United States academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biobanks Market |
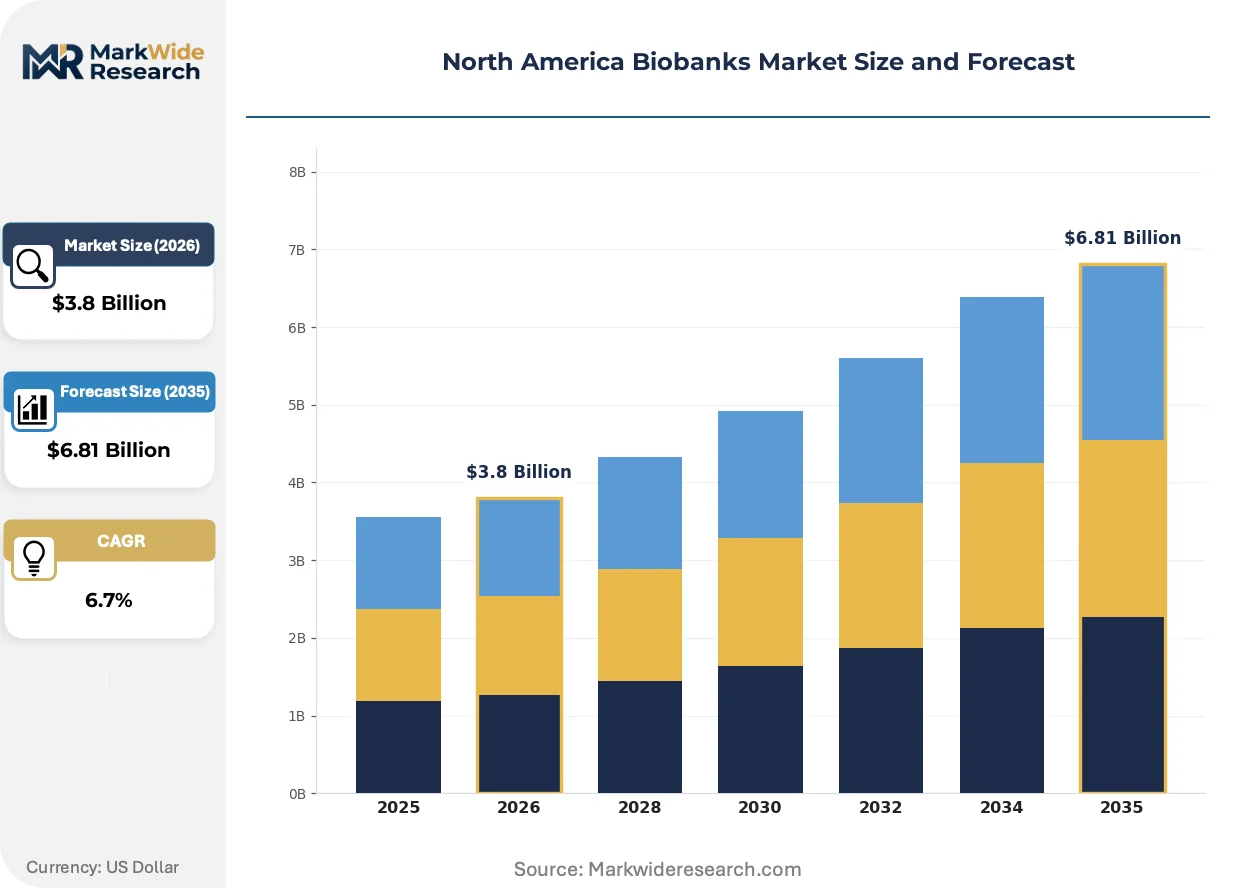
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Biobank Type: Population Biobanks, Disease-Specific Biobanks, Tissue Biobanks, Cell Line Biobanks Sample Type: Blood Samples, Tissue Samples, DNA Samples, RNA Samples Application: Genetic Research, Drug Development, Personalized Medicine, Clinical Trials End User: Pharmaceutical Companies, Academic Institutions, Research Organizations, Hospitals |
| Companies Covered | Thermo Fisher Scientific, Becton, Dickinson and Company, Qiagen N.V., Hamilton Company, STEMCELL Technologies, BioLife Solutions, Lonza Group AG, Guardant Health, Charles River Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biobanks Market Evolving Landscape
Automation and digitization are compressing turnaround times while elevating specimen traceability standards across the North American biobanking sector. Three developments merit particular attention.
Automated biospecimen processing systems are reducing human touchpoints in clinical-grade repositories. Academic medical centers in Boston and New York are deploying these platforms at accelerated pace. The technology is modularizing quality control workflows into discrete, auditable steps that satisfy FDA evolving guidance on human cell and tissue products.
The FDA's tightening quality benchmarks on human cell and tissue products are forcing infrastructure upgrades across United States and Canadian facilities. Biobank administrators must now demonstrate validated temperature monitoring and alarm systems to maintain operational licenses. Disease-specific repositories, particularly those serving oncology sponsors, are absorbing disproportionate compliance costs.
Research sponsors are consolidating vendor relationships around end-to-end service capabilities rather than discrete storage contracts. Contract research organizations clustered around major metropolitan hubs are displacing standalone biorepositories. This concentration is most visible in the northeastern United States, where pharmaceutical companies prioritize annotated cohorts with linked clinical outcomes.
North America Biobanks Market Segmentation
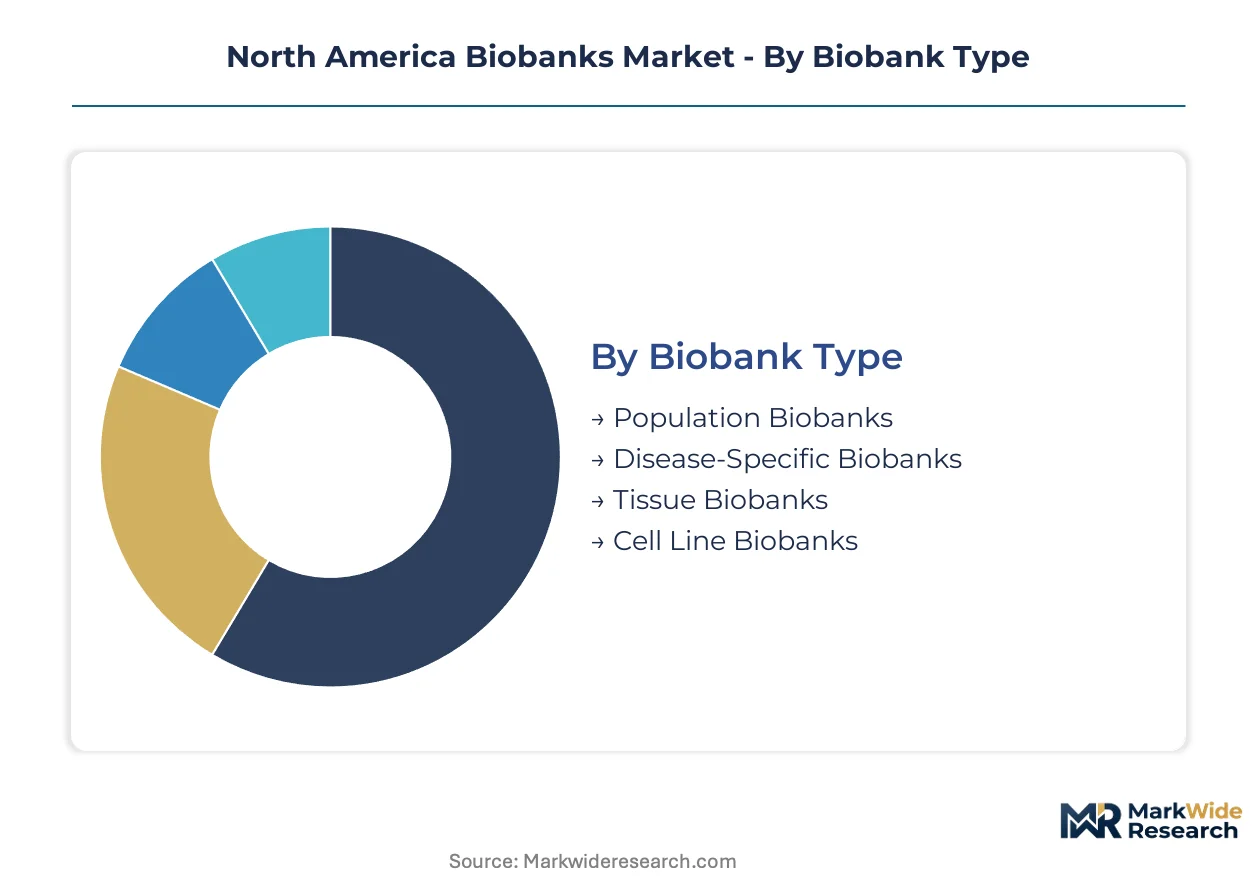
Biobank operators must align infrastructure investments with distinct specimen workflows and sponsor requirements. Each segmentation dimension reveals divergent capital intensity, compliance burdens, and partnership dynamics across the North American market.
Biobank Type:
Supply concentration in high-volume research corridors favors operators with disease-specific depth over generalist repositories.
- Disease-Specific Biobanks:Curated collections target oncology, rare diseases, or neurological conditions with linked clinical annotations. Pharmaceutical sponsors in Boston and New York corridors prioritize these repositories for biomarker discovery pipelines. FDA evolving guidance on human cell and tissue products elevates compliance costs disproportionately here.
- Tissue Biobanks:Fresh-frozen archival quality supports spatial transcriptomics and organoid derivation workflows. Academic medical centers command premium valuations where specimen integrity windows are narrowest. Liquid nitrogen vapor-phase storage infrastructure separates viable competitors from marginal operators.
- Population Biobanks:Longitudinal cohorts spanning diverse demographics enable epidemiological research and public health surveillance.
- Cell Line Biobanks:Immortalized cultures serve standardized assay platforms and reproducibility studies across distributed research networks.
Today's leader: Disease-Specific Biobanks. Tomorrow's challenger: Tissue Biobanks.
Sample Type:
Cost tier differentiation separates commodity high-throughput matrices from premium specimen categories requiring specialized handling protocols.
- Blood Samples:Plasma, serum, and peripheral blood mononuclear cells dominate processing volumes across clinical-grade repositories. Automated biospecimen processing systems reduce contamination risk in high-throughput workflows. Contract research organizations consolidate contracts around operators with validated cold-chain logistics.
- Tissue Samples:Surgical resections and biopsies demand rapid stabilization and cryopreservation to preserve molecular integrity. Qiagen nucleic acid stabilization chemistries differentiate service providers in genomic biobanking workflows. Annotation specialist scarcity constrains expansion beyond northeastern United States academic medical centers.
- DNA Samples:Extracted genomic material enables genotyping arrays and sequencing applications with extended storage stability.
- RNA Samples:Transcriptomic analyses require stringent RNase-free handling and rapid stabilization post-collection.
Blood Samples anchor current revenue. Tissue Samples are climbing the fastest as spatial omics applications multiply.
Application:
Customer type fragmentation separates transactional storage contracts from integrated research partnerships with multi-year horizons.
- Drug Development:Pharmaceutical sponsors demand annotated cohorts with chain-of-custody documentation for regulatory submissions. Thermo Fisher end-to-end cold-chain infrastructure dominates sample storage logistics in sponsor-preferred corridors. NIH Genomic Data Sharing Policy mandates drive standardization investments.
- Personalized Medicine:Companion diagnostic development requires prospective specimen collection with linked clinical outcomes. Becton Dickinson automated processing systems reduce turnaround times for time-sensitive biomarker assays. Emerging state-level bioprivacy legislation in California and New York creates compliance complexity.
- Genetic Research:Academic investigators prioritize accessible archives with broad consent protocols for secondary use.
- Clinical Trials:Multi-site studies require harmonized collection protocols and centralized biorepository services.
Drug Development commands the largest contract values. Personalized Medicine shows the steepest expansion trajectory as precision oncology pipelines mature.
End User:
Geographic clustering concentrates purchasing power in metropolitan hubs with dense research infrastructure.
- Pharmaceutical Companies:Sponsors consolidate vendor relationships around integrated capabilities rather than discrete storage. Precision oncology pipelines accelerate biorepository partnership expansion across the northeastern United States. Cross-border data transfer limitations constrain Health Canada Biologics and Genetic Therapies Directorate compliance for multinational networks.
- Academic Institutions:Medical centers and universities anchor specimen collection with NIH funding dependencies. Institutional review boards enforce evolving informed-consent standards that affect sample usability. Office for Human Research Protections oversight escalates audit requirements.
- Research Organizations:Non-profit and government laboratories prioritize accessible archives with standardized data formats.
- Hospitals:Clinical biobanks support quality improvement and translational research with residual specimen utilization.
Pharmaceutical Companies drive premium pricing. Academic Institutions are gaining share fastest as federal research budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American biobanking industry traces its institutional roots to the National Cancer Institute's tissue repository network established in the 1970s, which established the cold-chain protocols and consent frameworks that shaped modern repository standards across the continent.
United States
Pharmaceutical sponsors in the northeastern corridor drive concentrated demand for oncology-focused biorepositories with linked clinical annotations. The FDA's 21st Century Cures Act implementation tightens quality benchmarks for human cell and tissue products nationwide. Boston and New York academic medical centers anchor the highest-density cluster of contract research organizations and precision medicine pipelines.
Canada
Federal research funding through the Canadian Institutes of Health Research sustains population-scale longitudinal cohorts for epidemiological studies. Health Canada's Biologics and Genetic Therapies Directorate imposes cross-border data transfer restrictions that constrain multinational biobank network expansion. Toronto and Montreal house the principal concentration of university-affiliated tissue repositories with genomic data sharing capabilities.
California
Emerging state-level bioprivacy legislation creates compliance complexity for operators serving personalized medicine developers. The California Consumer Privacy Act and subsequent amendments establish consent protocol requirements beyond federal baselines. San Diego and San Francisco biotech corridors attract venture-backed cell therapy sponsors demanding annotated specimen collections.
Texas
MD Anderson Cancer Center and adjacent research hospitals anchor one of the largest disease-specific tissue repositories in the southern United States. State medical center funding programs support biobank infrastructure expansion for translational oncology research. The Houston medical corridor concentrates specialized cold-chain logistics providers serving multi-site clinical trials.
Illinois
Midwest pharmaceutical manufacturing presence generates demand for clinical-grade biospecimen processing and storage services. The University of Chicago and Northwestern Medicine anchor academic biorepository networks with NIH-funded genomic research programs. Chicago serves as a distribution hub for specimen transport between coastal research centers and central U.S. clinical sites.
North America Biobanks Market Competitive Landscape
The competitive structure tilts toward integrated service providers with end-to-end cold-chain capabilities rather than standalone storage operators. Tier-one players combine automated processing systems with nucleic acid stabilization chemistries to capture pharmaceutical sponsor contracts. Three archetypes dominate: equipment-integrated service providers, specialized biospecimen processors, and genomic workflow specialists. Consolidation through strategic partnerships and capacity expansion in high-volume research corridors represent the dominant competitive vectors.
Among equipment-integrated service providers, Thermo Fisher Scientific exemplifies the archetype combining cold-chain infrastructure with sample storage logistics. Becton, Dickinson and Company occupies a parallel position through automated biospecimen processing systems. Qiagen N.V. represents the genomic workflow specialist tier with nucleic acid stabilization offerings.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Becton, Dickinson and Company |
| Qiagen N.V. |
| Hamilton Company |
| STEMCELL Technologies |
| BioLife Solutions |
| Lonza Group AG |
| Guardant Health |
| Charles River Laboratories |
| Others |
Value Network & Pricing Analysis
Annotation specialist scarcity in the northeastern United States compresses labor-cost differentials between premium clinical-grade repositories and standard storage facilities, widening pricing-tier spreads as pharmaceutical sponsors absorb specialist premiums for linked clinical outcomes.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated repositories with automated processing systems from commodity storage operators. Price differentiation hinges on certification grade against evolving FDA guidance on human cell and tissue products and geographic delivery cost to Boston-New York corridors. Cost compression in the economy tier is intensifying because contract research organizations consolidate contracts around integrated capabilities. Academic medical centers show least price sensitivity for fresh-frozen tissue archival, while standalone biorepositories face greatest pricing pressure from vendor consolidation trends.
Supply Chain Analysis
Domestic-content mandates under the FDA's 21st Century Cures Act implementation are reshaping sourcing toward United States-based cold-chain infrastructure and automated processing equipment. Supply concentrates in the United States for clinical-grade repositories, Canada for population-scale longitudinal cohorts, and Germany for nucleic acid stabilization chemistries. The supply chain draws from liquid nitrogen production facilities, automated biospecimen processing hardware, and specialized temperature monitoring systems. Single-source vulnerability in vapor-phase cryopreservation equipment creates structural risk. Distribution runs through contract research organization networks clustered around metropolitan research hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as pharmaceutical sponsors shift demand toward premium repositories with validated chain-of-custody documentation for regulatory submissions.
For Market Incumbents: Acquire automated biospecimen processing capabilities to defend against displacement by end-to-end service providers. Expand liquid nitrogen vapor-phase storage capacity in the northeastern United States corridor where demand concentrates. Pursue backward integration into nucleic acid stabilization chemistries to capture margin from genomic biobanking workflows. For New Entrants and Emerging Players: Mid-tier academic medical centers outside Boston and New York clusters present underserved buyer archetype opportunities with federal research budget expansion. California bioprivacy legislation compliance services offer penetrable entry point as state mandates outpace federal baselines. Organoid derivation workflow partnerships provide differentiated go-to-market angle for tissue biobank specialists. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone storage operators lacking automated processing or clinical annotation capabilities. Long-term viability favors integrated service providers with end-to-end cold-chain infrastructure across the analysis window. Watch FDA enforcement patterns against evolving human cell and tissue product guidance as inflection indicator for compliance-cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Processing System Deployment | Reduces contamination risk for FDA clinical-grade repository validation requirements. |
| Liquid Nitrogen Infrastructure Expansion | Extends molecular integrity windows for spatial transcriptomics research sponsors. |
| Clinical Annotation Specialist Acquisition | Addresses scarcity constraining biobank expansion beyond northeastern United States. |
| State-Level Bioprivacy Compliance Program | Creates first-mover positioning for California and New York legislative mandates. |
| Organoid Derivation Service Launch | Opens revenue streams from three-dimensional cell culture therapeutic applications. |
Research Methodology
Coverage spans the United States and Canada, with primary inputs from each market combining structured interviews with biobank operations directors, pharmaceutical sponsor procurement leads, academic medical center research administrators, and regulatory affairs specialists at FDA and Health Canada. Secondary validation draws from FDA guidance documents, Health Canada Biologics and Genetic Therapies Directorate filings, NIH Genomic Data Sharing Policy records, and institutional review board protocol databases. Bottom-up facility capacity assessments triangulate against top-down pharmaceutical R&D expenditure patterns.
Rate-of-change decomposition separates volume growth in specimen processing from value expansion in premium service tiers across the modeling period. Segmentation dimensions include biobank type, sample matrix, application workflow, and end-user category with geographic regulatory cluster overlay. CAGRs derive from longitudinal cohort demand projections and precision oncology pipeline expansion rates. Forecast inputs incorporate liquid nitrogen infrastructure investment cycles and evolving informed-consent standard adoption timelines.
Underlying measurement precision varies by segment; pharmaceutical sponsor contract values carry tighter precision than academic institution funding allocations. Forecasts reflect assumptions around FDA enforcement intensity and Health Canada cross-border data transfer policy stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Mice Model Technologies Market
Medical Research
Medical Device Contract Research Organization Market
Medical Research
Metabolomics Market
Medical Research
US Academic Medical Centers Market
Medical Research
Forensic Medicine Market
Medical Research
Global Mice Model Market
Medical Research
Precision Medicine Market
Medical Research
Global in Vitro Lung Model Market
Medical Research
Epigenetics Market
Medical Research
Global Human Liver Models Market
Medical Research
Organoids and Spheroids Market
Medical Research
Malaria Vaccine Market
Medical Research
Global Humanized Mouse Model Market
Medical Research
Epigenomics Market
Medical Research
Europe AMH Market
Medical Research
PDX Models Market