
 Germany Refined Petroleum Products Market | 2026-2036
Germany Refined Petroleum Products Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Refined Petroleum Products Market Foresight
Refinery margin capture from low-carbon fuel blending is reshaping competitive economics across Germany's downstream sector. Shell Deutschland leverages its extensive fuel station network to sustain retail diesel volumes. BP Europa SE anchors its position through hydrogen-ready refinery investments at its Gelsenkirchen complex. Bayernoil Raffineriegesellschaft mbH specializes in high-sulfur fuel oil processing for industrial heating customers in Bavaria.
Germany refined petroleum products encompass hydrocarbon fuels produced through atmospheric and vacuum distillation, catalytic cracking, and hydrotreating of crude oil, with specifications governed by EN 228 for gasoline and EN 590 for diesel sulfur content. These products serve as energy carriers for mobility, industrial process heat, and agricultural mechanization. Diesel dominates product type demand through logistics fleet consumption and manufacturing plant backup power systems. Jet fuel represents the fastest-growing application segment as Frankfurt and Munich airports expand long-haul route capacity. Fuel oil maintains structural relevance in industrial heating across chemical parks in Ludwigshafen and Leverkusen.
The Federal Network Agency (Bundesnetzagentur) enforces storage and grid access rules for petroleum products, while KBA certifies fuel quality compliance with EU emission standards. The EU Green Deal mandates progressive carbon intensity reductions that force refiners to integrate biofuel blending or face demand erosion. Stakeholders must monitor hydrogen refinery retrofits and renewable fuel certificate markets to preserve margin pools.
Market Dynamics
The EU Green Deal's carbon intensity benchmarks are forcing German refiners to reconfigure processing units for biofuel blending, compressing traditional margin pools while hydrogen-ready retrofits absorb capital deployment.
Growth Catalysts
- Logistics Fleet Dieselization:Heavy freight operators in North Rhine-Westphalia are expanding procurement of EN 590-compliant diesel for long-haul corridors. This concentrates demand around the Ruhr refinery cluster.
- F-Gas Regulation:The EU F-Gas Regulation is tightening emission thresholds for industrial process heat, preserving structural demand for low-sulfur fuel oil in chemical parks.
- Jet Fuel Infrastructure:Frankfurt and Munich airports are expanding long-haul route capacity, pulling additional kerosene throughput from Bayernoil and Shell Deutschland storage terminals.
Market Restraints
- Crude Supply Concentration:German refiners depend on Russian and Caspian pipeline crude that transits through Ukrainian and Polish territory, exposing throughput to transit disruption risk.
- Carbon Border Adjustment:The EU Carbon Border Adjustment Mechanism is elevating input costs for imported crude feedstocks, squeezing cracking margins at inland refineries.
- Electrification Substitution:Battery-electric trucks and rail electrification are capturing last-mile freight volumes, eroding the addressable market for road diesel.
Strategic Opportunities
- Renewable Fuel of Non-Biological Origin:The EU Green Deal mandates for e-fuels create offtake certainty for hydrogen-derived synthetic diesel at Gelsenkirchen and Leuna refinery complexes.
- Industrial Heat Decarbonization:Chemical parks in Ludwigshafen and Leverkusen require transitional low-carbon fuel oil blends during their 2040 net-zero transitions.
- Aviation Biofuel Certification:The KBA's enforcement of EU emission standards for sustainable aviation fuel opens premium pricing for hydrotreated esters and fatty acids at Frankfurt airport supply points.
Industry Challenges
- Hydrotreater Retrofit Complexity:Conventional desulfurization units require complete catalyst replacement and reactor reconfiguration to process pyrolysis oil and Fischer-Tropsch syncrude blends.
- Renewable Fuel Certificate Tracking:The Bundesnetzagentur's storage and grid access rules demand granular mass-balance documentation that legacy ERP systems cannot automate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Refined Petroleum Products Market |
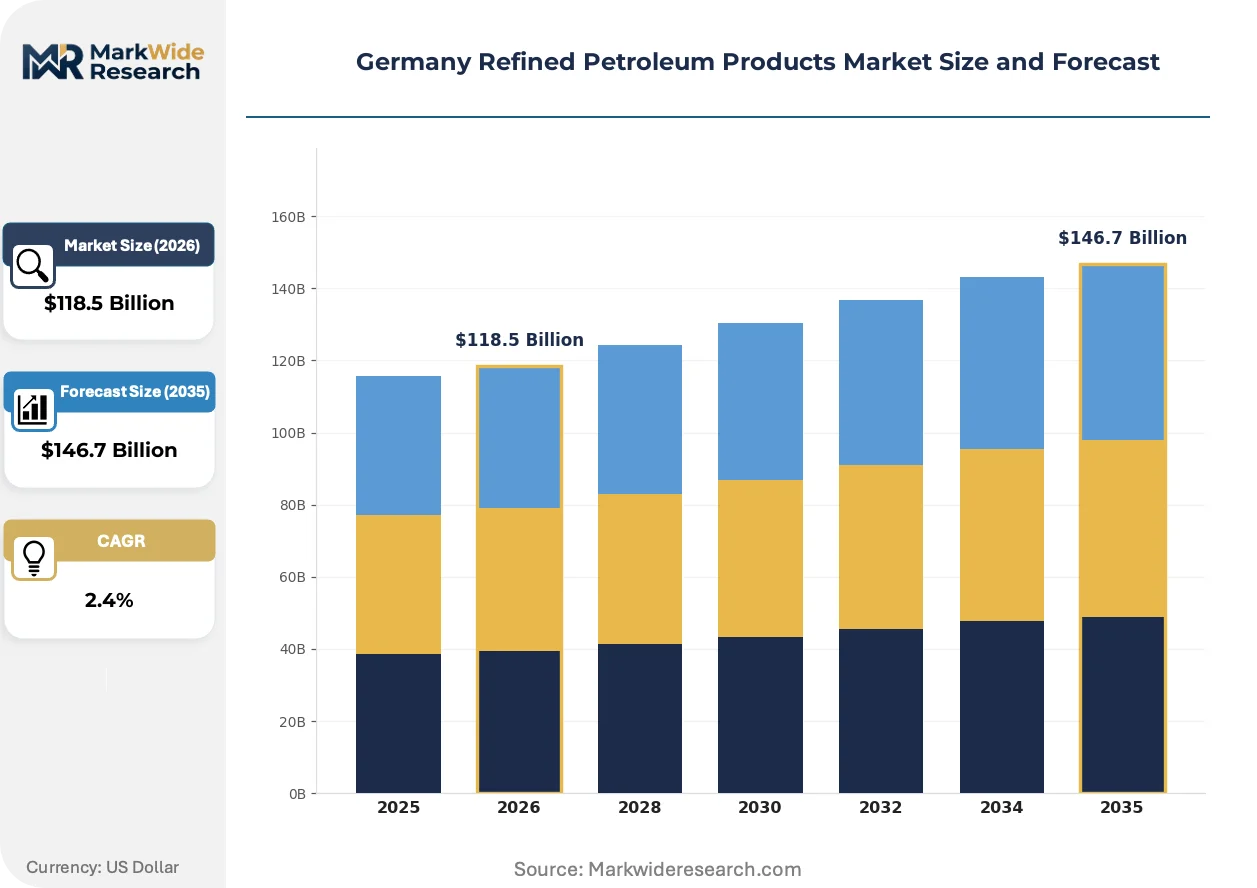
| Market Size in 2026 | $118.5 Billion |
| Market Size in 2035 | $146.7 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Kerosene, Jet Fuel, Fuel Oil, Lubricants Application: Transportation, Industrial Heating, Aviation, Marine Fuel, Power Generation, Agriculture Distribution Channel: Fuel Stations, Direct Sales, Bulk Supply, Wholesale, Automotive Service Centers End User: Logistics Companies, Manufacturing Plants, Airlines, Shipping Firms, Farming Operations |
| Companies Covered | Rosneft Deutschland GmbH, PCK Raffinerie GmbH, BP Europa SE, Eni SpA, Exxon Mobil Corporation, Shell Deutschland, TotalEnergies SE, Bayernoil Raffineriegesellschaft mbH, HOLBORN Europa Raffinerie GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Refined Petroleum Products Market Shifts & Advancements
Refinery configuration is pivoting from crude-centric processing to flexible feedstock platforms that can co-process biogenic oils and synthetic intermediates without full unit replacement.
Co-processing technology is hybridizing conventional fluid catalytic crackers with dedicated bio-oil injection systems. Bayernoil and BP Europa SE are retrofitting riser reactors to handle 20-30% pyrolysis oil co-feed. This hybridizing approach preserves existing capital while meeting EU Green Deal carbon intensity benchmarks without greenfield construction.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in industrial refrigeration, indirectly preserving fuel oil demand for process heat in chemical manufacturing. Refiners are responding by certifying low-sulfur residual fuel for combined heat and power applications. North Rhine-Westphalia's chemical parks are the primary beneficiaries of this thermal energy transition pathway.
Fleet operators are consolidating diesel procurement through direct refinery offtake agreements rather than spot market purchases. Logistics companies in Bavaria and Baden-Württemberg are bypassing wholesale distributors to secure volume commitments from Bayernoil and Shell Deutschland. This disintermediation concentrates buying power among the largest freight operators while compressing margins for independent fuel traders.
Germany Refined Petroleum Products Market Segmentation
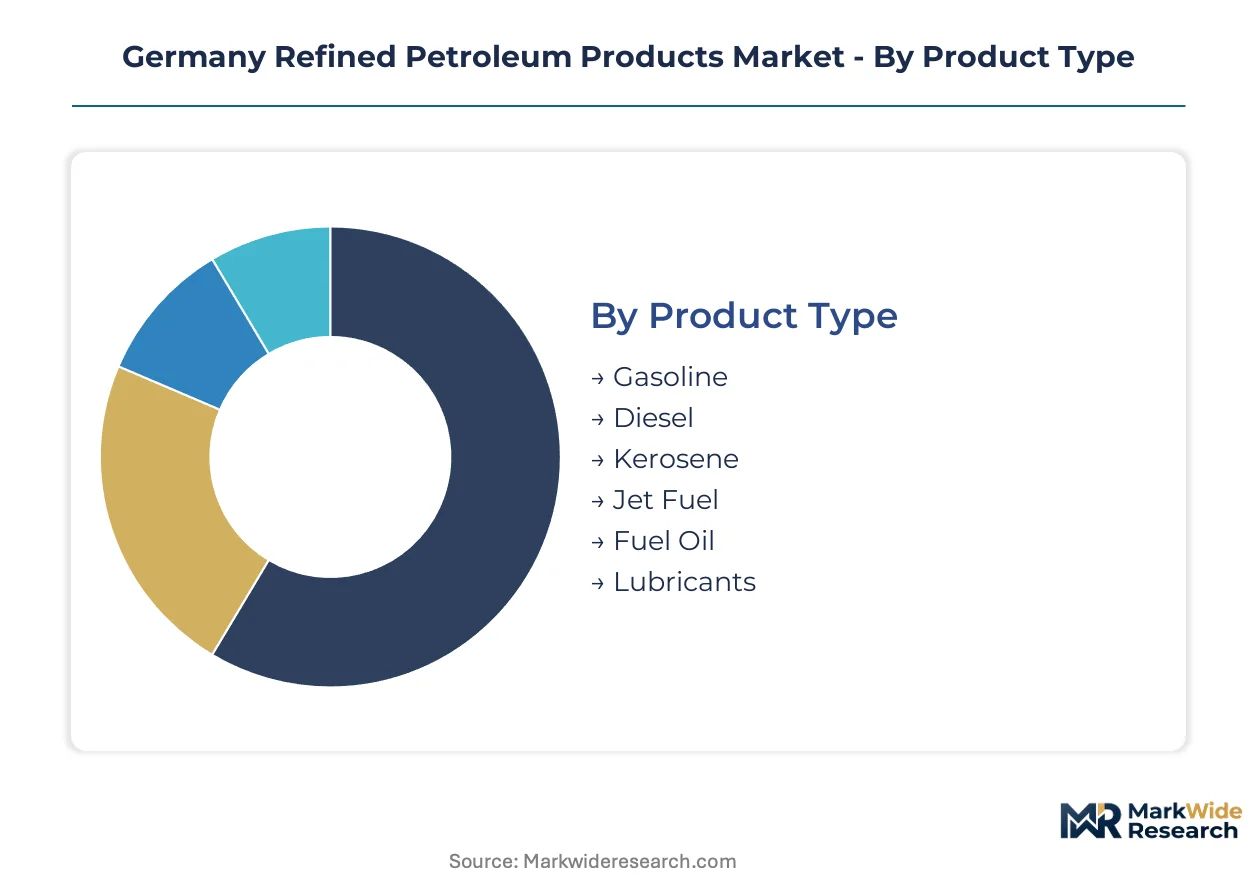
German refiners configure product slates around EN 228 and EN 590 specifications that govern sulfur limits and biofuel blending mandates. Segmentation clarity determines margin capture as hydrogen-ready retrofits and renewable fuel certificates reshape downstream economics.
Product Type:
Mature distillates dominate throughput volumes while emerging synthetic alternatives reconfigure long-term refinery yields.
- Diesel:EN 590-compliant middle distillate with maximum 10 ppm sulfur content serves logistics fleets and manufacturing plant backup power. Demand concentrates in North Rhine-Westphalia's Ruhr refinery cluster where heavy freight operators procure directly from Shell Deutschland and BP Europa SE storage terminals.
- Jet Fuel:Kerosene-grade aviation turbine fuel meeting DEF STAN 91-91 specifications pulls expanding throughput from Bayernoil and Shell Deutschland facilities. Frankfurt and Munich airports drive the steepest demand expansion as long-haul route capacity grows.
- Gasoline:EN 228-compliant motor spirit with bioethanol blending requirements serves private vehicle fleets across Baden-Württemberg and Bavaria.
- Kerosene:Illuminating and heating kerosene maintains niche demand in rural heating applications.
- Fuel Oil:High-sulfur and low-sulfur residual grades supply industrial process heat in Ludwigshafen and Leverkusen chemical parks.
- Lubricants:Base oils and finished lubricants serve manufacturing maintenance schedules.
Diesel retains volume leadership; jet fuel holds the steepest expansion curve.
Application:
Transport energy consumption anchors refinery output allocation while industrial decarbonization pathways create transitional fuel demand.
- Transportation:Road diesel and gasoline consumption by logistics fleets and passenger vehicles generates the majority of refinery margin capture. Fleet operators in Bavaria and Baden-Württemberg are consolidating procurement through direct refinery offtake agreements.
- Aviation:Kerosene demand from Frankfurt and Munich airports climbs fastest as international route networks expand. The KBA's enforcement of EU emission standards for sustainable aviation fuel opens premium pricing for certified supply points.
- Industrial Heating:Low-sulfur fuel oil maintains structural relevance in chemical manufacturing process heat.
- Marine Fuel:IMO 2020-compliant very low sulfur fuel oil serves inland waterway and coastal shipping.
- Power Generation:Distillate and residual fuel oils provide grid backup and remote power.
- Agriculture:Diesel fuel powers mechanized farming operations across grain and livestock regions.
Transportation commands the largest throughput share; aviation climbs fastest as airport capacity expands.
Distribution Channel:
Channel selection determines working capital intensity and margin retention as disintermediation concentrates buying power among the largest operators.
- Direct Sales:Refinery-to-fleet contracts eliminate wholesale markups for logistics companies with predictable consumption profiles. Bayernoil and Shell Deutschland have expanded dedicated supply agreements with North Rhine-Westphalia freight operators.
- Bulk Supply:Terminal-to-consumer deliveries serve manufacturing plants and chemical parks requiring continuous process heat. The Bundesnetzagentur's storage and grid access rules govern these infrastructure-dependent transactions.
- Fuel Stations:Retail network sales capture margin from private vehicle owners and small commercial operators.
- Wholesale:Distributor-mediated sales face margin compression as large buyers bypass intermediaries.
- Automotive Service Centers:Lubricant and specialty product sales attach to maintenance services.
Direct sales capture the highest volume growth; bulk supply retains structural importance for industrial offtake.
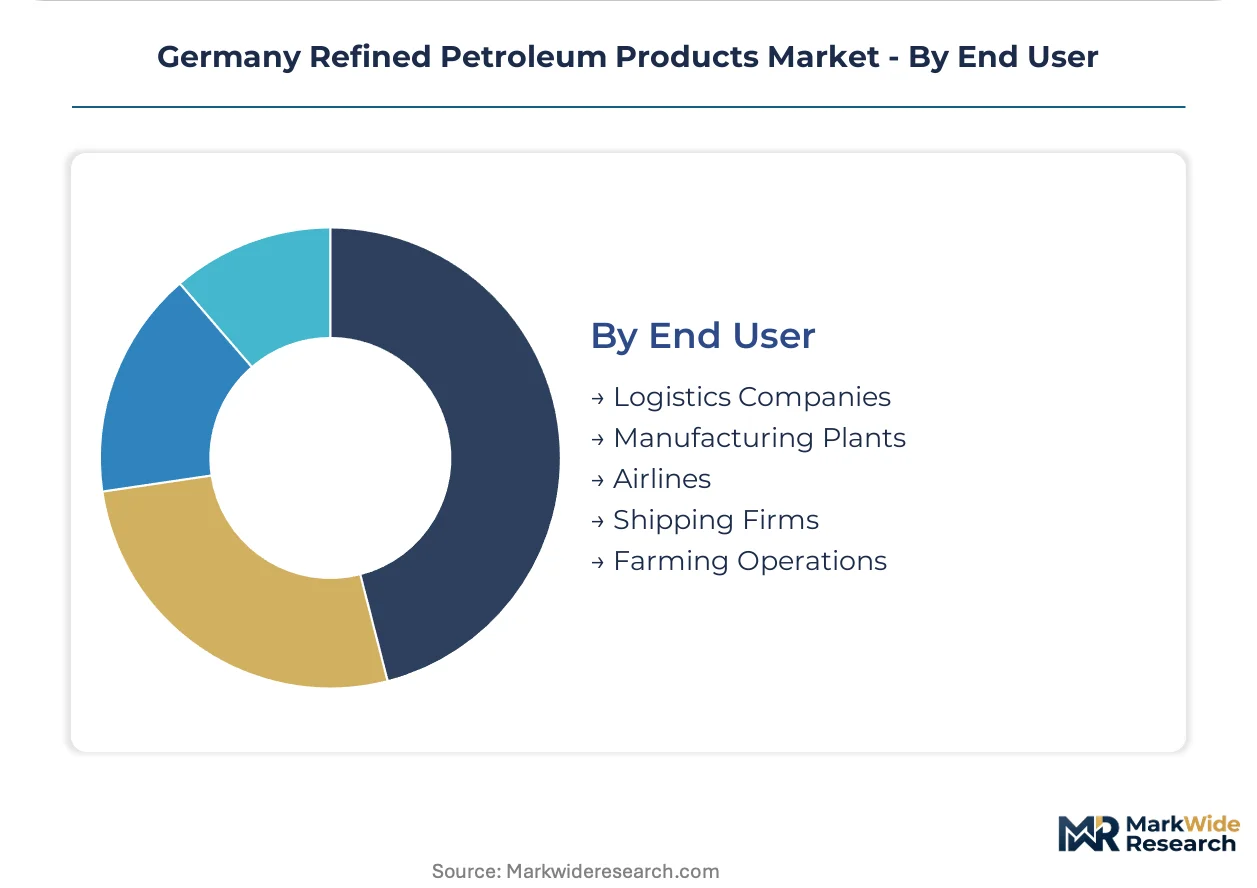
End User:
User scale determines procurement leverage and contract structure as certificate tracking requirements complicate legacy supply relationships.
- Logistics Companies:Heavy freight operators with EN 590-compliant diesel requirements drive demand concentration around the Ruhr refinery cluster. These firms leverage volume commitments to secure price advantages over spot market purchases.
- Airlines:Lufthansa Group and international carriers at Frankfurt and Munich airports pull certified jet fuel through dedicated supply infrastructure. Sustainable aviation fuel mandates from the EU Green Deal force sourcing diversification.
- Manufacturing Plants:Chemical parks in Ludwigshafen and Leverkusen require transitional low-carbon fuel oil blends during net-zero transitions.
- Shipping Firms:Inland waterway and coastal operators purchase IMO-compliant marine fuels.
- Farming Operations:Agricultural mechanization generates seasonal diesel demand patterns.
Logistics companies dominate procurement volumes; airlines face the steepest compliance-driven sourcing transformation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German refiners cluster processing capacity in North Rhine-Westphalia, where pipeline networks and chemical park demand concentrate throughput. This geographic bias shapes regional fuel supply dynamics and infrastructure investment patterns across federal states.
North Rhine-Westphalia
Heavy freight operators in the Ruhr region procure EN 590-compliant diesel directly from refinery storage terminals. The EU Green Deal mandates carbon intensity reductions that force local processors to integrate biofuel blending systems. Gelsenkirchen anchors hydrogen-ready refinery investments as BP Europa SE reconfigures cracking units for synthetic fuel production.
Bavaria
Bayernoil's Ingolstadt complex supplies jet fuel to Munich Airport's expanding long-haul route network. The KBA enforces fuel quality compliance with EU emission standards for all aviation turbine fuel distributed through regional terminals. Chemical parks in Ludwigshafen and Leverkusen pull low-sulfur fuel oil for industrial process heat during net-zero transitions.
Baden-Württemberg
Logistics companies in Stuttgart and Mannheim consolidate diesel procurement through direct refinery offtake agreements rather than wholesale channels. The Bundesnetzagentur governs storage and grid access rules for petroleum products moving through Rhine river terminals. Shell Deutschland maintains retail network coverage across the state's automotive manufacturing corridor.
Lower Saxony
Agricultural mechanization in grain and livestock regions generates seasonal diesel demand patterns for farming cooperatives. The EU F-Gas Regulation preserves structural demand for low-sulfur fuel oil in food processing and cold chain facilities. Wilhelmshaven's deepwater port enables crude import diversification away from Russian pipeline dependence.
Hesse
Frankfurt Airport drives the steepest jet fuel demand expansion as international route capacity grows. Sustainable aviation fuel mandates from the EU Green Deal force Lufthansa Group and international carriers to diversify sourcing through certified supply points. The Rhine-Main logistics hub concentrates trucking fleet diesel consumption around refinery-direct contracts.
Germany Refined Petroleum Products Market Competitive Landscape
Integrated majors and regional specialists split the market between scale-driven infrastructure plays and feedstock-flexible processing niches. The downstream sector exhibits moderate consolidation around refinery clusters with high pipeline interconnectivity. Three archetypes dominate: hydrogen-ready integrated refiners, biofuel-co-processing specialists, and industrial fuel oil distributors. Competitive moves center on refinery retrofit partnerships and direct fleet procurement agreements that disintermediate wholesale distributors.
Among Germany-based integrated refiners, Shell Deutschland and BP Europa SE exemplify the hydrogen-ready archetype through their North Rhine-Westphalia complexes. Bayernoil Raffineriegesellschaft mbH occupies a position within the co-processing specialist tier, leveraging Bavaria's aviation and industrial demand concentration. Rosneft Deutschland GmbH anchors the import-dependent refinery segment, reflecting feedstock sourcing challenges facing Caspian-linked processors.
| Leading Market Players |
|---|
| Rosneft Deutschland GmbH |
| PCK Raffinerie GmbH |
| BP Europa SE |
| Eni SpA |
| Exxon Mobil Corporation |
| Shell Deutschland |
| TotalEnergies SE |
| Bayernoil Raffineriegesellschaft mbH |
| HOLBORN Europa Raffinerie GmbH |
| Others |
Supply & Pricing Matrix
Russian and Caspian pipeline crude transit through Ukrainian and Polish territory anchors upstream supply concentration, feeding margin pools toward refiners with hydrogen-ready retrofit capabilities and direct fleet procurement contracts. This feedstock geography compresses cracking margins at inland processors while rewarding those with storage flexibility and biofuel blending infrastructure.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across Germany's downstream sector. Contract-based long-term offtake agreements dominate volume transactions, with price differentiation driven by carbon intensity certification under EU emission standards and volume scale commitments from logistics fleets. Pricing pressure stems from the EU Carbon Border Adjustment Mechanism elevating imported crude input costs, eroding margins at refiners without biofuel integration. Small independent fuel traders exhibit highest price sensitivity due to disintermediation by direct refinery contracts, while airlines securing sustainable aviation fuel certification accept premium tiers for compliance certainty.
Supply Chain Analysis
Tariff exposure between Russia and EU member states dominates supply chain risk calculus for German refiners. Feedstock sourcing concentrates in Russia, Kazakhstan, and Azerbaijan, with crude oil, natural gas, and hydrogen feedstocks forming critical input dependencies. Single-source vulnerability persists around the Druzhba pipeline corridor, forcing inventory builds at Wilhelmshaven for maritime diversification. Distribution runs through Rhine river terminals, pipeline networks to North Rhine-Westphalia, and direct refinery-to-fleet agreements that bypass wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's refined petroleum products sector is a service-attach opportunity where renewable fuel certificate tracking and refinery-direct supply contracts expand faster than commodity spot trading. After-sales layers including mass-balance documentation systems and certified sustainable fuel procurement advisory are capturing disproportionate value.
For Market Incumbents: Entrench hydrogen-ready refinery positions through catalyst replacement programs at Gelsenkirchen and Leuna complexes. Secure backward integration into pyrolysis oil supply chains to preserve margin pools against electrification substitution in last-mile freight. Lock in direct procurement contracts with North Rhine-Westphalia logistics fleets before independent traders consolidate remaining spot volumes. For New Entrants and Emerging Players: Establish a beachhead in renewable fuel certificate tracking software serving Bundesnetzagentur compliance requirements. Target agricultural cooperatives in Lower Saxony with seasonal diesel procurement platforms that aggregate fragmented farming demand. Leverage digital procurement marketplaces to bypass entrenched wholesale distributor relationships in Baden-Württemberg. For Investors and Strategic Acquirers: Capital is best deployed toward hydrogen-ready refinery complexes with existing pipeline interconnectivity and chemical park offtake agreements. Long-term viability hinges on feedstock flexibility platforms capable of processing 20-30% biogenic co-feed without greenfield construction. Monitor sustainable aviation fuel certification penetration at Frankfurt and Munich airports as the inflection indicator for premium pricing durability.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Refinery Retrofit | BP Europa SE's Gelsenkirchen complex preserves margin pools under EU Green Deal carbon intensity benchmarks. |
| Direct Fleet Procurement Agreement | Shell Deutschland bypasses wholesale intermediaries to capture volume commitments from Ruhr region logistics operators. |
| Pyrolysis Oil Co-Processing Investment | Bayernoil's riser reactor retrofit enables 20-30% biogenic feedstock integration without full unit replacement. |
| Sustainable Aviation Fuel Certification | KBA enforcement at Frankfurt airport opens premium pricing for hydrotreated esters and fatty acids supply points. |
| Renewable Fuel Certificate Tracking Platform | Mass-balance documentation automation addresses Bundesnetzagentur compliance gaps in legacy ERP systems. |
Research Methodology
Desk research of customs and trade flow databases, refinery throughput disclosures, and EU regulatory filings preceded structured interviews with refinery operations managers, logistics fleet procurement directors, chemical park energy officers, and sustainable fuel certification auditors. Secondary validation drew from Bundesnetzagentur storage reports, KBA fuel quality enforcement records, and EU ETS carbon market data. Bottom-up volume modeling triangulated against top-down refinery capacity utilization assessments across the analysis window.
Assumptions around EU Green Deal carbon intensity reduction trajectories and sustainable aviation fuel mandate timelines were held fixed, while crude supply disruption scenarios and electrification penetration rates were stress-tested across sensitivity bands. Segmentation modeling incorporated product type, application, distribution channel, and end-user scale dimensions. CAGRs were derived from trend extrapolation of refinery yield shifts and biofuel blending obligation compliance curves, with hydrogen refinery retrofit capex cycles and renewable fuel certificate market liquidity serving as industry-specific forecast inputs.
Sensitivities concentrate around Druzhba pipeline transit disruptions, EU Carbon Border Adjustment Mechanism implementation stringency, and battery-electric truck adoption curves in German logistics corridors. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and feedstock substitution economics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Performance Oil Sales Market
Petroleum Products
Quenching Oil Market
Petroleum Products
Uganda Petroleum Products Market
Petroleum Products
Crude Oil Market
Petroleum Products
Oil Refinery Market
Petroleum Products
Petroleum Liquid Feedstock Market
Petroleum Products
Crude Oil Pour Point Depressant Market
Petroleum Products
Paraffin Oil Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Ultra Low Sulphur Fuel Oil (ULSFO) Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
Marine Minerals Market
Petroleum Products
Natural Gas Liquid Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Base Oil Market
Petroleum Products
Pyrolysis Oil Market