
 Spindle Oil Market | 2026-2036
Spindle Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Spindle Oil Market Intelligence
The shift towards vendor-managed inventory and extended payment terms is narrowing the competitive field to suppliers with strong balance sheets. ExxonMobil leverages its vast distribution network to service large-scale industrial accounts. Fuchs specializes in high-performance synthetic oils for niche, precision machining applications. Royal Dutch Shell competes on the basis of its global brand recognition and comprehensive lubricant portfolio.
Spindle oil is a low-viscosity lubricant specifically formulated for high-speed machine tool spindles and other precision components. Characterized by low viscosity grades such as ISO VG 2, it minimizes friction and dissipates heat effectively in high-RPM operations. While mineral oil products dominate volume in cost-sensitive metalworking, synthetic oil is expanding its share. The superior thermal stability of synthetics is essential for the performance demanded by advanced textile machinery and woodworking equipment.
The European Union’s REACH regulation and the US EPA's guidelines on hazardous substances influence the chemical composition of spindle oils. These frameworks compel manufacturers to shift towards formulations with lower environmental toxicity and improved worker safety, often verified through ISO certifications. The key decision for end-users will be balancing the higher initial cost of compliant, high-performance synthetic oils against the long-term benefits of equipment protection and regulatory adherence.
Market Dynamics
The spindle oil market's evolution is defined by the dual pressures of advancing machinery complexity and tightening environmental compliance. Demand for higher productivity from CNC machines and textile equipment requires lubricants with superior thermal stability, while regulations like the EU's REACH framework simultaneously restrict formulation options.
Growth Catalysts
- Automation in Manufacturing:The expansion of automated textile production in India and CNC machining centers in Vietnam directly correlates with increased consumption of low-viscosity spindle oils to support higher operational speeds and precision.
- Stringent Environmental Regulations:Mandates such as the EU's REACH and the US EPA's hazardous substance guidelines are compelling a shift from conventional mineral oils to higher-performance synthetic formulations with lower toxicity profiles.
- Growth in Precision Engineering:The aerospace and medical device sectors in Germany and Japan require lubricants that offer exceptional thermal and oxidative stability for high-speed spindles, driving demand for premium synthetic products.
Market Restraints
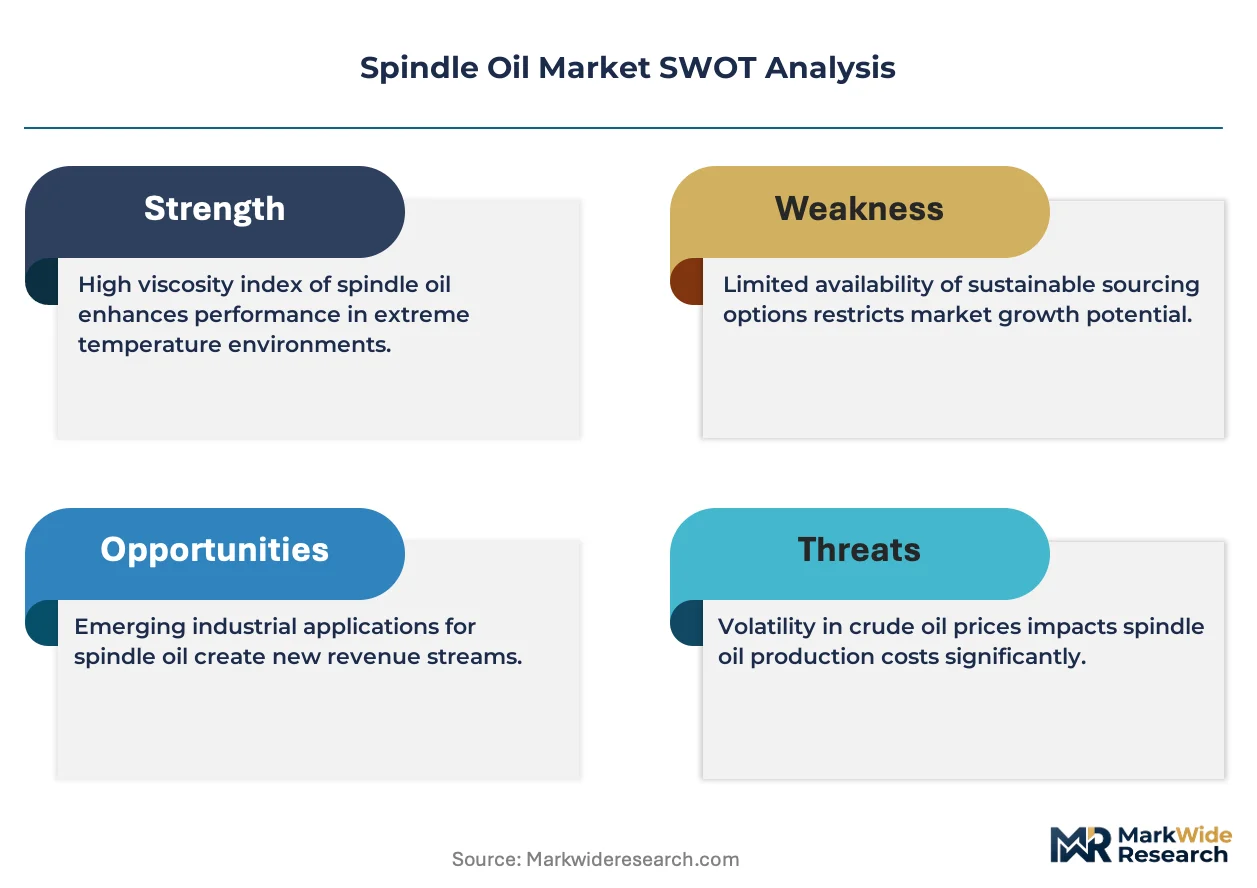
- Base Oil Price Volatility:Unpredictable costs for Group I and Group II mineral base oils, tied to global crude oil price fluctuations, compress margins for manufacturers of cost-sensitive, conventional spindle oil products.
- Threat from Grease Lubrication:In lower-RPM and less demanding applications, advanced lubricating greases can offer longer service intervals, presenting a direct substitution threat to spindle oils.
- Technical Limits of Mineral Oils:Conventional mineral-based spindle oils lack the necessary thermal stability and oxidation resistance for modern ultra-high-speed spindles, limiting their applicability in advanced machinery.
Strategic Opportunities
- Bio-based Formulations:Developing biodegradable spindle oils from renewable esters and other bio-feedstocks creates an avenue to meet corporate sustainability mandates and capture demand from environmentally focused customers in Europe.
- Electric Vehicle Manufacturing:The global expansion of EV production provides a new application space for specialized spindle oils used in the high-speed machining of lightweight aluminum and copper components.
- Digital Lubrication Services:Integrating sensor-based oil condition monitoring with predictive maintenance analytics offers a high-margin, service-based business model that moves beyond the sale of the physical lubricant.
Industry Challenges
- Complex OEM Approvals:Securing performance approvals from numerous original equipment manufacturers for a single formulation is a time-consuming and expensive process that can delay market entry for new lubricant technologies.
- End-User Education on Total Cost:Overcoming the initial price objection from smaller machine shops requires extensive educational efforts to demonstrate the long-term value of premium synthetics in reducing wear and extending equipment life.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spindle Oil Market |
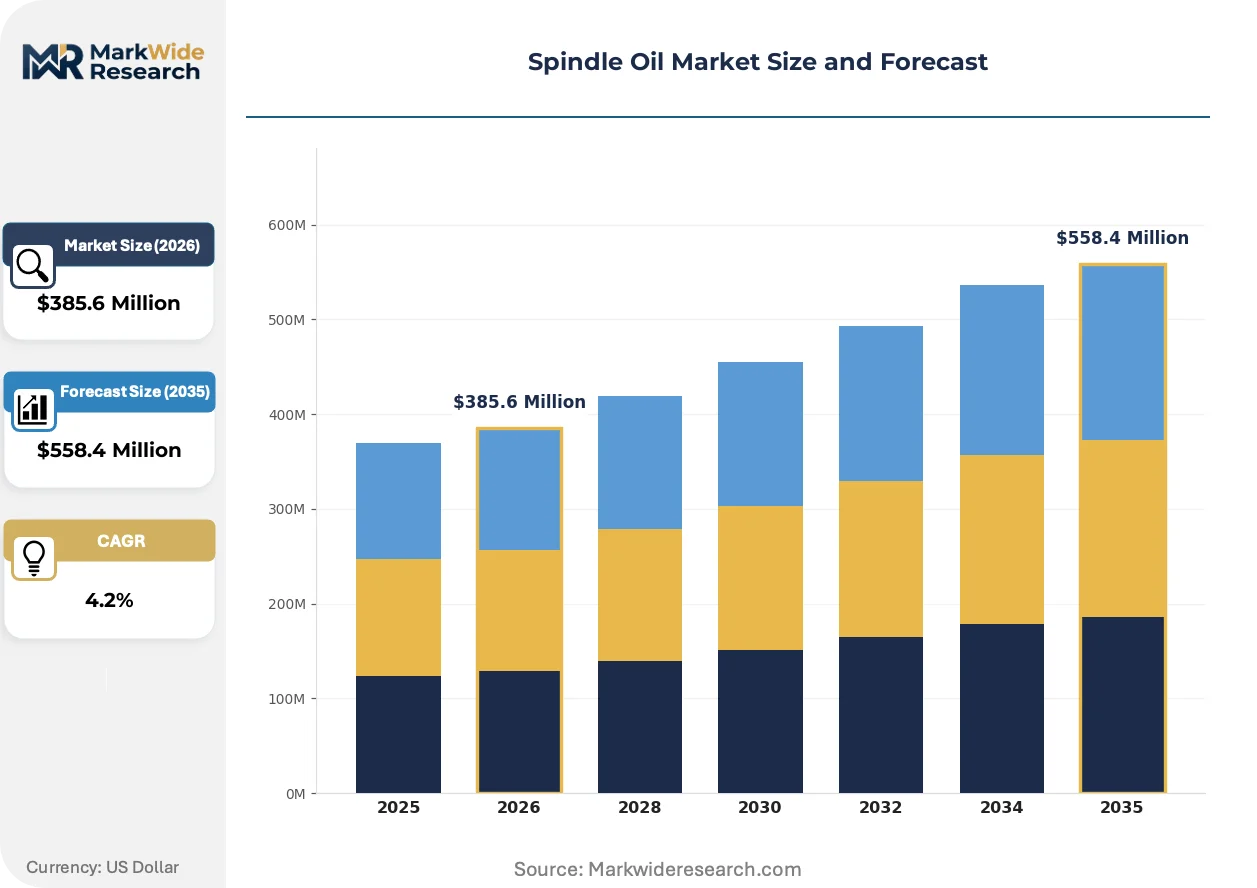
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $558.4 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Oil, Mineral Oil, Semi-Synthetic Oil, Bio-Based Oil, Ester Oil Application: Metalworking, Textile Machinery, Woodworking, Printing, Packaging Equipment End User: Machining Centers, Textile Manufacturers, Wood Product Makers, Printing Firms, Packaging Plants Packaging Type: Drums, Bottles, Cans, Bulk Containers, Pails |
| Companies Covered | Castrol Limited, Phillips 66 Lubricants, ExxonMobil, Valvoline Inc., Fuchs, Royal Dutch Shell, Total S.A., HP Lubricants, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spindle Oil Market Strategic Shifts & Innovations
The competitive landscape is being redefined by the convergence of digital maintenance tools and advanced material science. These developments are altering how lubricants are formulated, selected, and managed to satisfy new benchmarks for both operational performance and environmental sustainability.
Digital twin technology is a key innovation in industrial lubrication. These virtual models simulate the physical and chemical properties of spindle oil within a specific machine tool under real-world operating loads. Large-scale automotive and aerospace manufacturers are adopting this approach to optimize fluid performance. This technology is virtualizing wear prediction and oil degradation analysis, enabling a shift from scheduled to condition-based maintenance.
Regulatory frameworks in Asia are becoming a major influence on product formulation. China's GB standards for industrial lubricants, coupled with its national "dual carbon" policy, mandate improved energy efficiency and lower volatile organic compound (VOC) emissions. This is forcing a reformulation away from traditional solvent-refined base oils. The metalworking fluid segment is most affected, accelerating its transition toward synthetic and semi-synthetic products.
A notable behavioral change is the move away from purely transactional purchasing toward more integrated fluid management partnerships. This shift disrupts the traditional distributor model, which often competes solely on the price per drum of lubricant. The replacement model involves vendor-managed inventory (VMI) systems where the supplier assumes responsibility for on-site fluid monitoring and top-offs, which is most visible in large-scale manufacturing plants in the United States and Germany.
Spindle Oil Market Segmentation

The spindle oil market segmentation provides a granular view of product types, applications, and end-user demands influencing market dynamics. Understanding these distinct categories helps manufacturers align product development with specific performance requirements. This detailed breakdown clarifies where value creation and operational efficiencies are most critical.
Product Type:
The product type dimension delineates spindle oils based on their base stock composition and performance characteristics.
- Synthetic Oil:High-performance lubricants engineered from chemically synthesized base fluids, offering superior thermal stability and oxidation resistance. Demand concentrates in precision engineering sectors like aerospace and medical devices in Germany and Japan, driven by requirements for ultra-high-speed spindles.
- Mineral Oil:Derived from petroleum, these conventional lubricants are cost-effective and widely used for general-purpose applications. Volume demand remains dominant in cost-sensitive metalworking operations, particularly in industrial clusters within India.
- Semi-Synthetic Oil:Formulations blending mineral and synthetic base oils, offering an intermediate performance and price point.
- Bio-Based Oil:Environmentally friendly lubricants derived from renewable resources like vegetable oils and esters, gaining traction in Europe due to sustainability mandates.
- Ester Oil:A specific type of synthetic oil known for excellent thermal stability and biodegradability, often used in niche high-temperature applications.
Mineral Oil commands the established base. The steepest expansion runs through Synthetic Oil.
Application:
Volume consumption patterns are significantly shaped by the diverse industrial applications requiring spindle lubrication.
- Metalworking:Spindle oils are critical for CNC machines and other metal cutting/shaping equipment, ensuring precision and tool longevity. Demand is high in regions with strong manufacturing bases, including Vietnam and India, for both high-speed and general machining.
- Textile Machinery:Essential for lubricating high-speed textile machinery, preventing wear, and dissipating heat during continuous operation. Consumption is directly correlated with the expansion of automated textile production, especially in India.
- Woodworking:Lubricants for high-speed routers, shapers, and other woodworking equipment, particularly for precision and finish quality.
- Printing:Specialized oils for high-speed printing presses, reducing friction and ensuring consistent operation in paper and packaging industries.
- Packaging Equipment:Spindle oils maintain the smooth, high-speed operation of automated packaging lines, critical for efficiency.
Metalworking applications represent the largest segment. Textile Machinery is gaining share fastest, driven by automation.
End User:
Customer type segmentation highlights the specific operational environments and purchasing behaviors across industrial sectors.
- Machining Centers:These facilities operate a range of CNC and conventional machine tools, requiring various spindle oil grades for metal removal. Their demand is driven by the need for precision and extended equipment life in high-volume production.
- Textile Manufacturers:Companies involved in yarn production, weaving, and knitting rely on spindle oils for their high-speed, continuous operations. Automation initiatives in countries like India directly increase their consumption of specialized lubricants.
- Wood Product Makers:Businesses using woodworking machinery, from furniture manufacturing to construction component production, require lubricants for their precision tools.
- Printing Firms:Commercial and industrial printing operations use spindle oils to maintain the performance and reliability of their high-speed presses.
- Packaging Plants:Facilities involved in automated packaging processes utilize spindle oils to ensure the efficient and consistent operation of their machinery.
Machining Centers consume the largest volume of spindle oils. Demand from Textile Manufacturers is expanding most quickly.
Packaging Type:
Supply concentration for spindle oils is influenced by the diverse packaging types required by different customer scales.
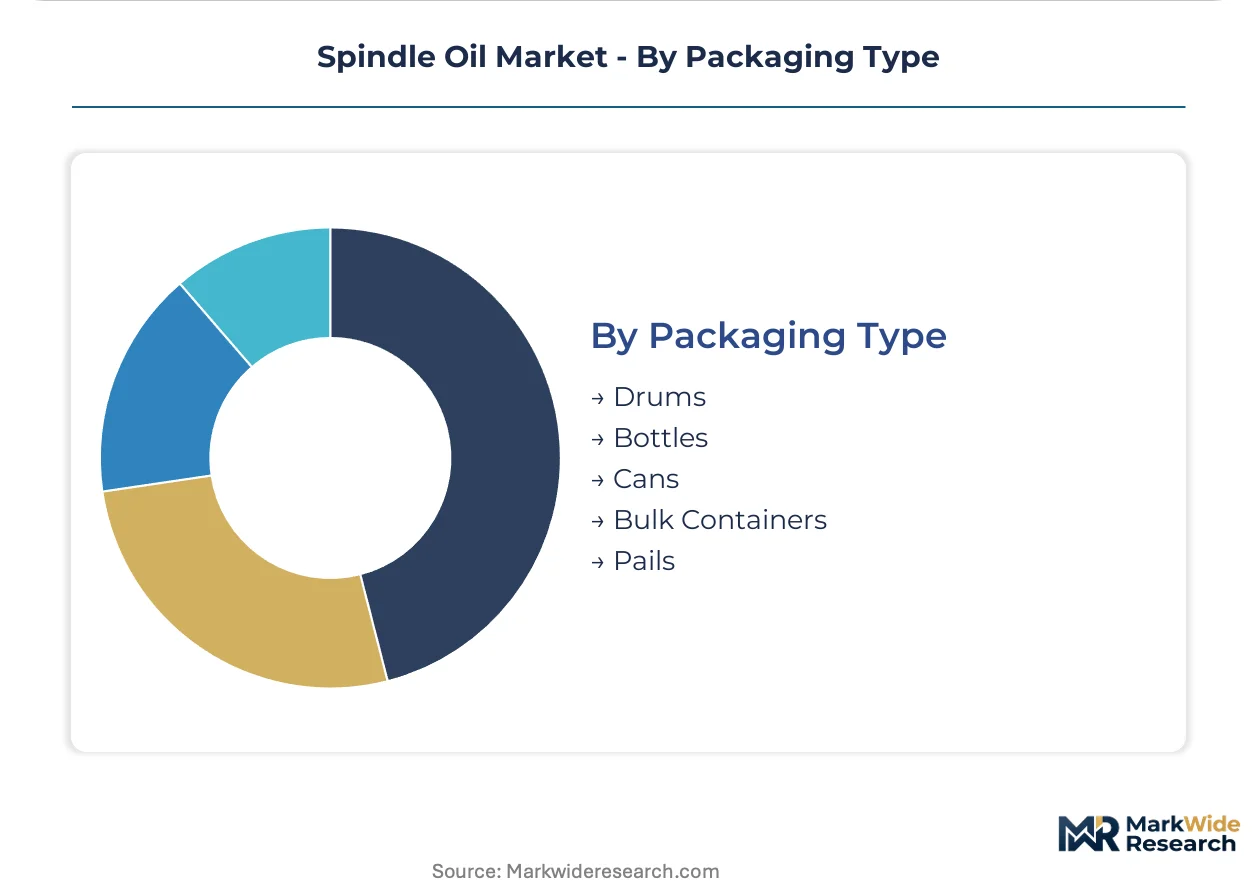
- Drums:Standard industrial packaging for bulk quantities, typically 200-liter capacity, used by medium to large-scale industrial users. These are common for general-purpose mineral oils in metalworking shops.
- Bottles:Smaller volume packaging, often 1-5 liter, catering to smaller workshops or for specific, lower-volume precision applications. This format is crucial for specialized synthetic oils used in niche machinery.
- Cans:Intermediate packaging volumes, often 5-20 liters, suitable for smaller industrial users or for specific machinery maintenance requirements.
- Bulk Containers:Very large volume packaging, such as IBCs or tanker trucks, serving large-scale manufacturing plants with vendor-managed inventory systems.
- Pails:Medium-sized containers, typically 20-25 liters, offering a convenient option for workshops with moderate consumption or for specific machine top-offs.
Drums dominate the distribution of spindle oils. Bulk Containers are climbing the fastest, driven by VMI models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Policy initiatives across major industrial economies influence spindle oil consumption patterns. Environmental regulations like the EU's REACH framework drive demand for advanced synthetic formulations. Automation in manufacturing sectors like textiles and CNC machining also dictates regional lubricant needs.
India
Demand for spindle oils in India correlates with the expansion of automated textile production and metalworking operations. The PLI scheme for textile manufacturing incentivizes new machinery installations, increasing lubricant requirements. Industrial clusters in Gujarat and Maharashtra utilize significant volumes for both high-speed textile machinery and cost-sensitive metalworking.
Germany
Precision engineering sectors in Germany require high-performance synthetic spindle oils for advanced aerospace and medical device components. The EU's REACH regulation necessitates lower-toxicity formulations, impacting product development. Manufacturing hubs in Bavaria and Baden-Württemberg adopt vendor-managed inventory systems for specialized lubricants.
China
China's industrial growth drives substantial spindle oil consumption in metalworking and other manufacturing segments. The national "dual carbon" policy and GB standards mandate improved energy efficiency and lower VOC emissions in industrial lubricants. Manufacturing centers in the Yangtze River Delta are transitioning towards synthetic and semi-synthetic metalworking fluids.
United States
The United States sees demand for spindle oils driven by high-speed machining centers and automated production lines in automotive and general manufacturing. EPA guidelines on hazardous substances influence the chemical composition of lubricants, promoting safer alternatives. Large-scale manufacturing plants in the Midwest increasingly implement digital lubrication services and bulk container deliveries.
Vietnam
Automation in manufacturing, particularly CNC machining centers, fuels increased consumption of low-viscosity spindle oils in Vietnam. Government incentives for foreign direct investment in high-tech manufacturing boost the need for precision lubricants. Industrial zones near Ho Chi Minh City are expanding their metalworking capabilities, requiring consistent lubricant supply.
Spindle Oil Market Key Industry Players
Channel-controlling players compete with product-specialist players in the spindle oil market, creating a tiered competitive structure. The market features a mix of large integrated energy companies leveraging extensive distribution and smaller, agile firms focused on high-performance formulations. Strategic archetypes include global portfolio providers, niche high-performance synthetic specialists, and regional volume suppliers. Dominant competitive moves involve expanding distribution networks into emerging industrial clusters and forming strategic partnerships for advanced additive technology development.
Scale-driven global suppliers like ExxonMobil and Royal Dutch Shell anchor the high-volume segments, leveraging their vast distribution networks and comprehensive lubricant portfolios to service large industrial accounts. These entities often provide a wide range of mineral and synthetic options across multiple industrial applications, competing on brand recognition and supply chain efficiency. Fuchs, a German-based specialist, exemplifies the high-performance synthetic oil archetype, focusing on niche, precision machining applications where superior thermal stability is critical. These specialized firms often differentiate through technical service, product customization, and adherence to stringent industry certifications.
| Leading Market Players |
|---|
| Castrol Limited |
| Phillips 66 Lubricants |
| ExxonMobil |
| Valvoline Inc. |
| Fuchs |
| Royal Dutch Shell |
| Total S.A. |
| HP Lubricants |
| Chevron Corporation |
| Others |
Cost & Logistics Intelligence
Industrial clusters in India, particularly those focused on textile and metalworking, drive significant spindle oil demand, influencing regional pricing dynamics through their aggregate purchasing power. This market navigates the complex interplay between feedstock availability, regulatory compliance costs, and end-user performance requirements.
Pricing Analysis
Certification level (ISO/REACH compliance) creates the primary spread in spindle oil pricing, particularly for synthetic formulations. The dominant pricing structure is contract-based long-term offtake for large industrial consumers, while smaller shops often use transactional per-unit purchasing. Price differentiation stems from base oil quality (mineral vs. synthetic) and after-sales service bundles like vendor-managed inventory. Cost compression for conventional mineral oils intensifies due to base oil price volatility. Machining centers using general-purpose mineral oils exhibit the highest price sensitivity, whereas aerospace manufacturers prioritize performance over initial cost.
Supply Chain Analysis
Upstream feedstock for spindle oils draws from global crude oil refining centers, primarily for Group I and Group II mineral base oils. Geographic supply concentration for these base oils includes the Middle East and parts of Asia, while specialized synthetic base stocks like esters are produced in Europe and North America. The supply chain relies on a consistent flow of performance additives from specialized chemical manufacturers. Commodity price volatility in crude oil presents a structural risk to base oil costs. Downstream distribution runs through a hybrid model of direct sales to large manufacturing plants and extensive distributor networks serving smaller industrial users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spindle oil market presents a high-growth disruption, driven by the dual inflections of advanced manufacturing automation and tightening environmental regulations.
For Market Incumbents:Insulate core market share by investing heavily in R&D for bio-based and high-performance synthetic formulations. Expand digital lubrication services, integrating sensor-based monitoring to offer predictive maintenance solutions. This strategy counters the threat from advanced grease lubrication and tightening environmental regulations like REACH. Control distribution channels through enhanced vendor-managed inventory programs, especially in emerging industrial clusters.
For New Entrants and Emerging Players:Underpenetration in specialized applications within electric vehicle manufacturing provides a clear entry point. Target precision machining of lightweight aluminum and copper components, which requires superior thermal stability. Focus on developing niche, high-performance synthetic oils with rapid OEM approval pathways. A strong go-to-market angle involves offering bundled solutions that include technical support and sustainability certifications, appealing to environmentally conscious customers.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized synthetic oil producers and digital service providers. Long-term viability for spindle oils is assured by the continued expansion of high-speed manufacturing across global industrial economies. Identify acquisition targets that possess proprietary additive technologies or strong regional distribution in high-growth areas like Vietnam. The signal to watch is the adoption rate of digital twin technology in industrial lubrication, indicating a shift towards advanced fluid management.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Synthetic Base Stocks | Ensures supply resilience for high-performance lubricants demanded by precision industries. |
| Green Manufacturing Transition | Aligns product portfolios with corporate sustainability mandates and regulatory frameworks. |
| Digital Lubrication Service Integration | Transforms transactional sales into high-margin, service-based revenue streams through analytics. |
| Strategic Partnership with OEMs | Accelerates market entry for new formulations by securing critical equipment performance approvals. |
| Distribution Channel Optimization | Enhances market reach and efficiency, particularly for bulk deliveries and vendor-managed inventory. |
Research Approach
A standing panel of plant managers, R&D chemists, procurement leads, and equipment OEMs provided ongoing calibration for market sizing and forecast validation. This study combined extensive primary interviews with industry stakeholders and rigorous secondary validation. Secondary data sources included industry association reports, government trade statistics, regulatory body publications from EPA and REACH, and company financial filings. Both bottom-up and top-down triangulation methods were employed to ensure data accuracy and consistency.
The forecast framework utilized scenario-based modeling to project market trajectories across the analysis window. Segmentation dimensions modeled included product type, application, end-user, packaging type, and regional industrial clusters. Compound annual growth rates were derived through regression analysis on historical data and forward-looking projections of key market drivers. Automation adoption rates in textile and metalworking, alongside regulatory compliance timelines, served as critical forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by base oil suppliers or specialized additive manufacturers would shift outcomes. Forecasts reflect assumptions documented through extensive industry research and expert consultations. Cross-checking against industry association forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Natural Gas Liquid Market
Petroleum Products
France Refined Petroleum Product Market
Petroleum Products
United States Refined Petroleum Products Market
Petroleum Products
Oil Shale Market
Petroleum Products
Oil Refinery Market
Petroleum Products
Balanos Oil Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Longitudinal Submerged-Arc Welded (LSAW) Pipes Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
Crude Oil Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Asia Pacific Base Oil Market
Petroleum Products
Nigeria Petrol Station Market