
 North America Oil and Gas Lubricants Market | 2026-2036
North America Oil and Gas Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Oil and Gas Lubricants Market Analytics
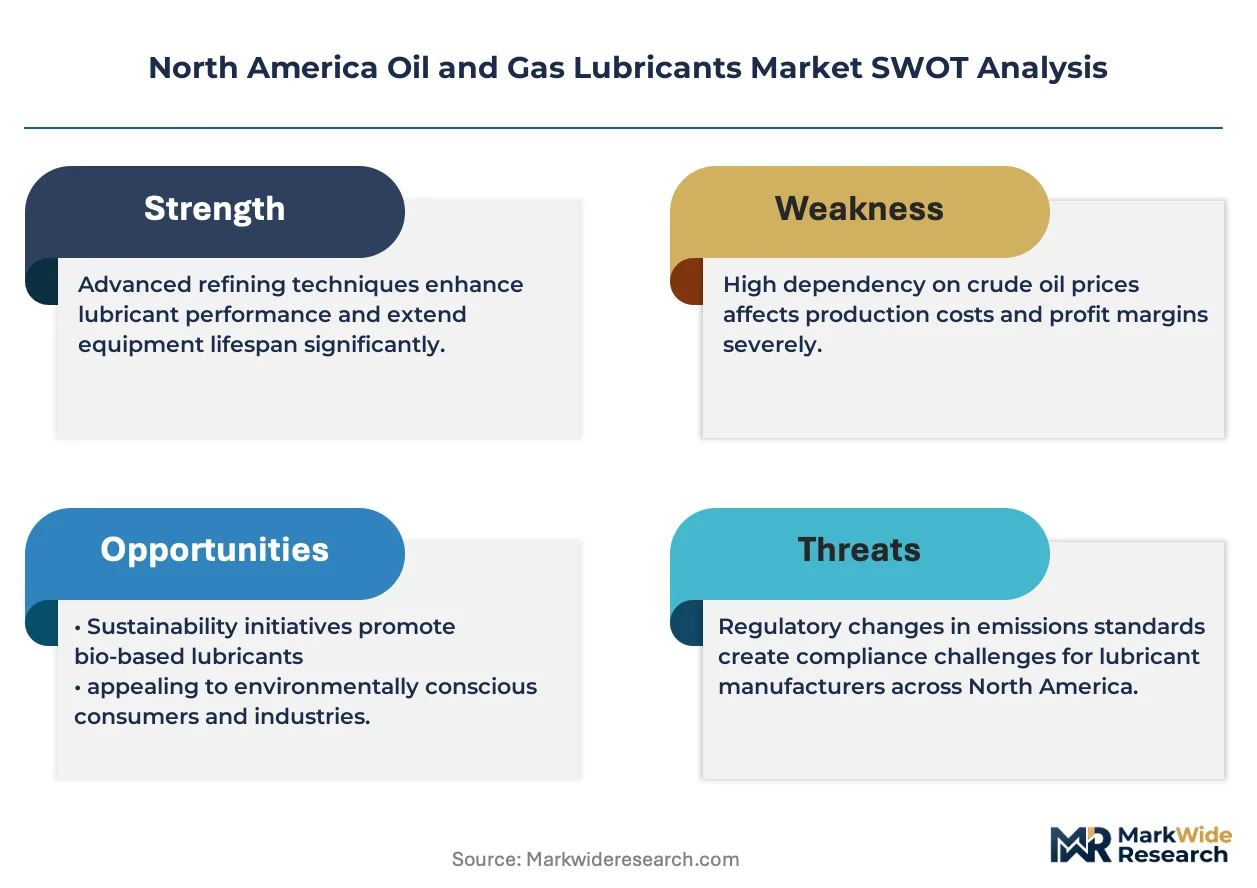
EPA methane regulations is decoupling baseline lubricant specifications from legacy formulations, forcing reformulation investments that smaller blenders cannot absorb. Exxon Mobil Corporation leverages its integrated base oil and additive supply chain to absorb these compliance costs internally. Chevron Corporation anchors its position through captive PAO production in the Gulf Coast. Shell plc competes by extending its premium synthetic portfolio across Permian drilling contractors.
North America oil and gas lubricants are formulated fluid systems engineered to operate across extreme pressure differentials, temperature swings from sub-zero arctic flows to deep-well heat above 150°C, and corrosive hydrogen sulfide environments. Their primary purpose is to reduce mechanical wear in reciprocating engines, hydraulic fracturing pumps, and gearbox transmissions while extending equipment uptime in continuous-duty extraction. Engine oils dominate volume demand across the Permian and Bakken basins where high-compression natural gas engines power drilling rigs. Synthetic oil technology captures expanding share as operators push longer drain intervals to minimize downtime in remote pad locations. Biodegradable lubricants remain niche but grow fastest around offshore California and Gulf Coast platforms facing state-level discharge scrutiny.
FERC pipeline safety standards, EPA Tier 4 emissions compliance, and API specification updates collectively shape product certification requirements and procurement eligibility across the continent. These frameworks push lubricant suppliers toward lower-viscosity, ash-reduced formulations that protect exhaust aftertreatment systems without sacrificing wear protection. Stakeholders must monitor how state-level carbon intensity scoring in California and pending Alberta methane regulations redirect specification roadmaps before committing capital to new blending capacity.
Market Dynamics
EPA methane regulations are forcing wholesale reformulation of base oil and additive packages across the North American oilfield services sector, compressing margins for independent blenders while integrated majors absorb compliance costs through captive supply chains.
Growth Catalysts
- Permian Basin synthetic adoption:Unconventional shale operators in West Texas and New Mexico are extending drain intervals through high-performance PAO formulations, reducing rig downtime in remote pad drilling locations.
- FERC pipeline safety mandates:Compressor station operators face upgraded lubricant specifications for reciprocating engines, creating replacement demand for ash-reduced, lower-viscosity certified products.
- Alberta oil sands thermal extraction:Steam-assisted gravity drainage operations in the Athabasca region require specialized high-temperature hydraulic fluids that resist thermal degradation above 150°C.
Market Restraints
- Group III/IV base oil supply concentration:Gulf Coast refinery capacity constraints limit synthetic feedstock availability, exposing blenders to price volatility from integrated producers.
- API specification lag:Updated service categories for natural gas engine oils face delayed ratification, freezing product development roadmaps and procurement eligibility for Tier 4 compliance.
- Electrification substitution threat:Grid-tied drilling rigs and battery-electric frac pumps in the Permian eliminate engine oil consumption entirely in select pad configurations.
Strategic Opportunities
- California offshore biodegradable mandate:State-level discharge scrutiny around Santa Barbara and Long Beach platforms creates niche demand for ester-based hydraulic fluids with rapid marine biodegradation profiles.
- Digital oilfield integration:Convergence of IoT sensor networks with predictive maintenance platforms enables condition-based lubricant replenishment, opening subscription service models for major suppliers.
- Bakken basin underpenetration:North Dakota operators lag Permian synthetic adoption rates by approximately five years, presenting conversion runway for premium formulation suppliers.
Industry Challenges
- Formulation chemist scarcity:The specialized knowledge required for methane-compliant, low-ash natural gas engine oil development exceeds current talent pipeline output from North American chemical engineering programs.
- Dual-certification timeline compression:Simultaneous EPA Tier 4 and pending Alberta methane regulation compliance requires parallel testing protocols that strain R&D laboratory capacity.
- Legacy equipment compatibility:Decades-old drilling rig engines and frac pumps in the Anadarko and Niobrara basins cannot tolerate reduced-ash formulations without seal and gasket replacement programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Oil and Gas Lubricants Market |
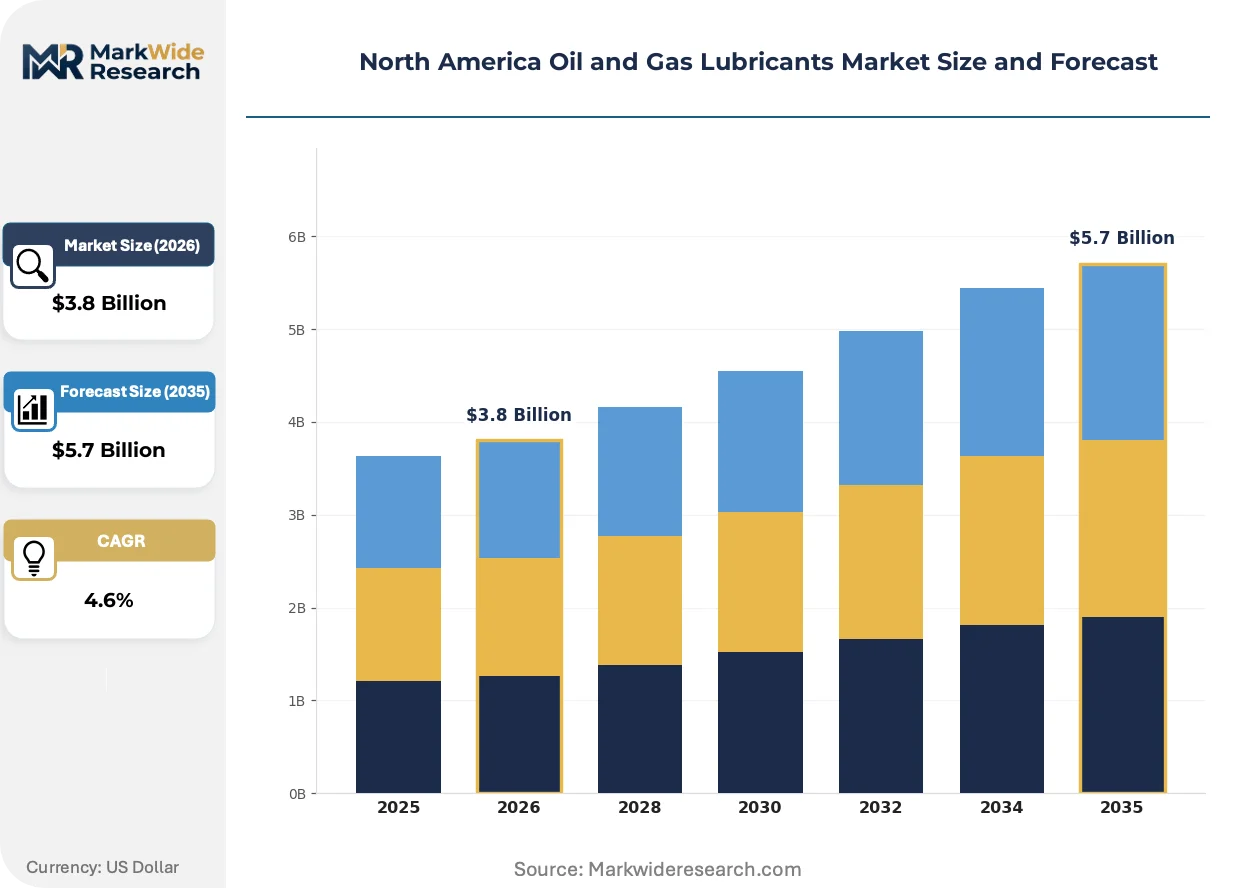
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Fluids, Gear Oils, Engine Oils, Greases Application: Exploration, Drilling, Production, Refining End User: Oil Field Services, Refineries, Industrial Users, Transportation Technology: Mineral Oil, Synthetic Oil, Biodegradable Lubricants, Additive Technology |
| Companies Covered | Exxon Mobil Corporation, Chevron Corporation, Shell plc, BP p.l.c., TotalEnergies SE, LUKOIL, Schlumberger Limited, Petro-Canada Lubricants, Lubrication Engineers Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Oil and Gas Lubricants Market Evolving Landscape
Synthetic formulation chemistry, regulatory compliance architecture, and procurement digitization are converging to restructure how lubricant value flows from base oil production through to wellsite consumption.
Polyalphaolefin-based synthetic blends are decentralizing the traditional supply relationship between major integrated suppliers and independent drilling contractors. PAO technology enables 500-hour drain intervals in natural gas engines, slashing logistics costs for remote Permian pad operations. Smaller regional blenders now source Group IV base stocks through merchant channels, fragmenting what was once a concentrated procurement hierarchy.
EPA's methane emissions rules are forcing additive package reformulations that protect exhaust aftertreatment systems without sacrificing wear protection in high-sulfur wellhead environments. Lubricant suppliers must now certify low-ash, low-phosphorus formulations that maintain piston deposit control under extended drain conditions. Natural gas engine oil categories face the most acute compliance pressure, with procurement eligibility contingent on pre-approval documentation.
Drilling contractors are consolidating lubricant purchasing through integrated supply agreements that bundle fluids, filters, and condition monitoring. This procurement compression displaces spot-market transactions and fragments distributor relationships across the Permian and Bakken. Large independent operators like Diamondback and Pioneer Natural Resources now negotiate direct supply contracts, bypassing traditional oilfield service intermediaries entirely.
North America Oil and Gas Lubricants Market Segmentation
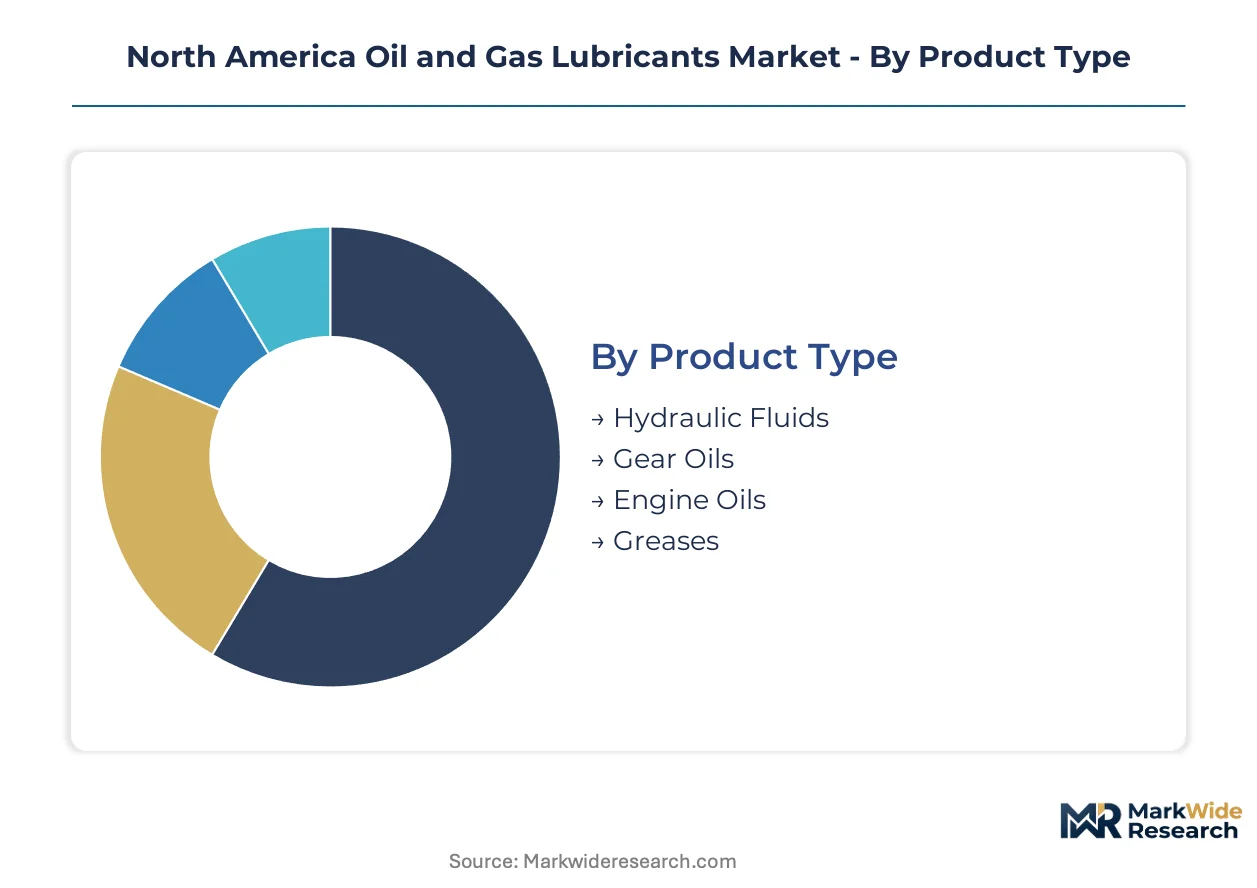
Segmentation in North America oil and gas lubricants determines procurement eligibility through API certification tiers, EPA compliance pathways, and end-use specification thresholds. Understanding these divisions reveals where formulation investments concentrate and which customer types absorb premium pricing.
Product Type:
API specification categories and EPA Tier 4 emissions compliance create divergent certification burdens across fluid types, with natural gas engine oils facing the most stringent additive package requirements.
- Engine Oils:Formulated for high-compression natural gas engines powering Permian drilling rigs, these lubricants must meet low-ash, low-phosphorus mandates to protect exhaust aftertreatment systems. Demand concentrates in West Texas and New Mexico where extended drain intervals reduce remote pad logistics costs.
- Hydraulic Fluids:Specialized formulations resist thermal degradation above 150°C in steam-assisted gravity drainage operations across Alberta's Athabasca region. PAO-based synthetics capture share as operators push equipment uptime in continuous-duty thermal extraction.
- Gear Oils:Extreme pressure formulations protect transmissions in hydraulic fracturing pumps facing corrosive hydrogen sulfide environments.
- Greases:Thickener-stabilized lubricants seal bearings in sub-zero arctic flows and deep-well heat applications.
Leading the category by volume: Engine Oils. Growing fastest: Hydraulic Fluids.
Application:
Cost tier stratification separates commodity-grade mineral formulations in legacy infrastructure from premium synthetics in new capital deployments.
- Drilling:Synthetic PAO formulations enable 500-hour drain intervals in natural gas engines, slashing downtime costs for remote Permian pad operations. Unconventional shale operators in West Texas and New Mexico drive specification upgrades as rig mobility demands fluid reliability.
- Production:Continuous-duty extraction requires lubricants operating across pressure differentials and temperature swings from sub-zero flows to deep-well heat above 150°C.
- Exploration:Seismic equipment and mobile drilling units demand portable lubricant supply chains with rapid replenishment capabilities.
- Refining:Fixed infrastructure enables bulk lubricant delivery with less emphasis on extended-drain synthetic performance.
Drilling commands the largest application share by value. Production expands most quickly as thermal extraction intensifies.
End User:
Customer type determines procurement leverage, with integrated operators negotiating direct supply contracts while fragmented service companies rely on distributor networks.
- Oil Field Services:Drilling contractors and hydraulic fracturing operators face the steepest specification pressure from EPA methane regulations and FERC pipeline safety mandates. Large independents now negotiate integrated supply agreements bundling fluids, filters, and condition monitoring.
- Refineries:Captive blending capacity at integrated majors insulates these end users from merchant market volatility in Group III/IV base oils.
- Industrial Users:Midstream compressor stations and pipeline operators drive replacement demand for ash-reduced, lower-viscosity certified products under FERC mandates.
- Transportation:Crude haulers and equipment logistics providers represent spot-market volume with limited specification influence.
Oil Field Services dominates end-user procurement value. Industrial Users gain share fastest as pipeline infrastructure expands.
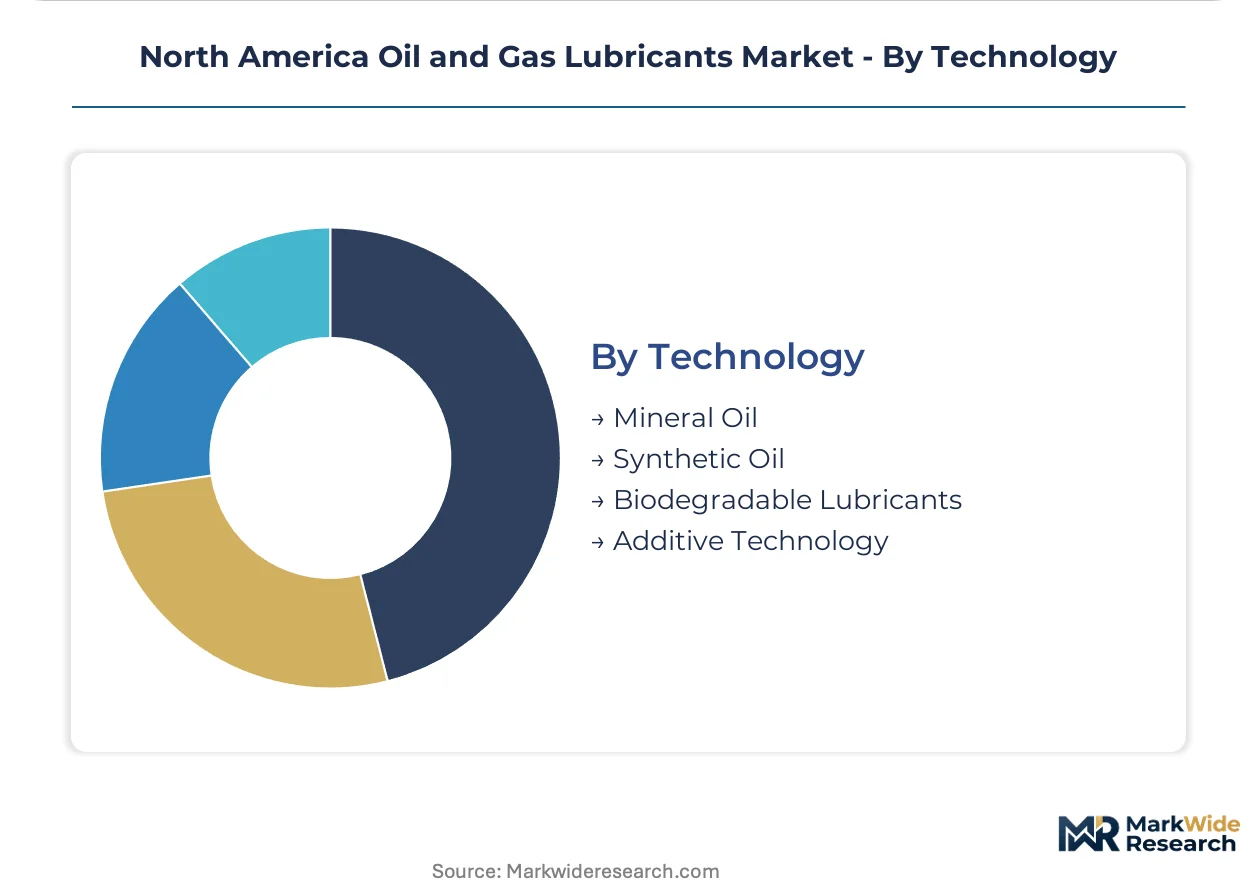
Technology:
Supply concentration in Gulf Coast Group III/IV base oil production shapes technology adoption curves and price volatility exposure.
- Synthetic Oil:PAO and ester-based formulations extend drain intervals and protect exhaust aftertreatment systems. Permian Basin operators lead adoption as remote pad locations magnify logistics cost savings from reduced fluid changes.
- Biodegradable Lubricants:Ester-based hydraulic fluids with rapid marine biodegradation profiles capture niche demand around California offshore platforms facing state-level discharge scrutiny.
- Mineral Oil:Group I and II base stocks retain volume in legacy equipment across Anadarko and Niobrara basins where seal compatibility limits reformulation.
- Additive Technology:Low-ash, low-phosphorus packages enable EPA Tier 4 compliance while maintaining wear protection in high-sulfur wellhead environments.
Synthetic Oil leads technology value share. Biodegradable Lubricants climb the fastest as coastal regulation tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin's designated Foreign Trade Zone No. 68 concentrates lubricant demand through tariff-advantaged supply chains serving West Texas and southeastern New Mexico drilling corridors.
United States
EPA methane regulations and FERC pipeline safety mandates drive specification upgrades across Texas, New Mexico, and North Dakota production zones. The EPA's Tier 4 emissions compliance framework forces reformulation of natural gas engine oils for exhaust aftertreatment protection. Midland-Odessa anchors synthetic lubricant consumption as Permian operators extend drain intervals to cut remote pad logistics costs.
Canada
Alberta's steam-assisted gravity drainage operations demand high-temperature hydraulic fluids resistant to thermal degradation above 150°C. Pending provincial methane regulations parallel federal EPA frameworks, compressing dual-certification timelines for cross-border suppliers. The Athabasca oil sands corridor around Fort McMurray concentrates specialized lubricant procurement for continuous-duty thermal extraction equipment.
Mexico
Energy reform implementation attracts Permian-style unconventional development in the Burgos Basin and Eagle Ford extension. Mexican federal environmental standards increasingly align with EPA benchmarks, creating specification overlap for multinational lubricant suppliers. Nuevo León and Tamaulipas states host emerging drilling contractor clusters importing synthetic formulations through Laredo-Nuevo Laredo logistics channels.
North America Oil and Gas Lubricants Market Competitive Landscape
Gulf Coast integrated producers anchor one tier through captive base oil and additive supply chains; independent regional blenders hold specialist positions in basin-specific formulation services. Market structure tilts toward consolidation as EPA compliance costs absorb smaller operators. Three archetypes dominate: vertically integrated majors with backward integration into Group III/IV feedstocks; mid-scale blenders leveraging merchant base oil channels; and niche specialists in biodegradable and high-temperature hydraulic formulations. Competitive moves center on strategic partnerships for digital oilfield integration and capacity expansion in synthetic blending infrastructure.
Among integrated majors, Exxon Mobil Corporation and Chevron Corporation exemplify the captive supply chain archetype, while Shell plc occupies a position bridging premium synthetic portfolios with direct contractor engagement. These three entities represent distinct competitive vectors: internal cost absorption through base oil ownership, Gulf Coast PAO production anchoring, and Permian-focused direct supply relationships respectively.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Chevron Corporation |
| Shell plc |
| BP p.l.c. |
| TotalEnergies SE |
| LUKOIL |
| Schlumberger Limited |
| Petro-Canada Lubricants |
| Lubrication Engineers Inc. |
| Others |
Value Network & Pricing Analysis
Permian Basin drilling contractors concentrate procurement leverage through integrated supply agreements, anchoring contract-based long-term offtake pricing that bundles fluids, filters, and condition monitoring services. EPA methane compliance costs flow downstream to independent blenders unable to absorb reformulation investments internally.
Pricing Analysis
Short lead-time premiums apply to spot synthetic base oil purchases when Gulf Coast refinery constraints disrupt Group III/IV feedstock availability. Three-tier pricing structure across premium PAO formulations, standard mineral blends, and economy Group I/II base stocks separates certification-grade synthetics from commodity alternatives. Cost compression in the independent blender tier is intensifying because integrated majors internalize compliance spend through captive supply chains. Oil field services companies show highest price sensitivity due to margin pressure from drilling activity fluctuations, while integrated operators absorb premium pricing through operational efficiency gains.
Supply Chain Analysis
Direct-to-driller channels handle large independent operator demand through bypass arrangements that displace traditional oilfield service intermediaries. Supply concentrates in the United States Gulf Coast for Group III/IV base oil production, with secondary sourcing from Canadian synthetic feedstock producers and merchant channels for regional blenders. Formulation chemistry rests on polyalphaolefin base stocks, low-ash additive packages, and ester-based biodegradable components. Single-source vulnerability emerges from Gulf Coast refinery concentration exposing blenders to integrated producer pricing power. Distribution runs through bulk terminal networks serving Midland-Odessa and Fort McMurray corridors with remote pad logistics capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America oil and gas lubricants market functions as a cost-of-compliance arena where EPA methane regulations erect barrier-to-entry moats favoring players with captive R&D laboratory capacity and backward-integrated base oil supply.
For Market Incumbents: To counter electrification substitution eliminating engine oil demand in grid-tied Permian drilling configurations, deepen synthetic formulation expertise in high-temperature hydraulic fluids for Alberta thermal extraction. Prioritize capacity addition in biodegradable ester production to capture California offshore mandate premiums before specification windows close. For New Entrants and Emerging Players: Bakken basin operators lag Permian synthetic adoption by approximately five years, presenting conversion runway for premium PAO suppliers willing to shoulder extended payment terms. Target direct supply relationships with mid-scale drilling contractors excluded from major integrated procurement hierarchies, leveraging digital oilfield integration as a service differentiator against established distributor networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale blenders with merchant base oil channel relationships and basin-specific formulation expertise in the Niobrara and Anadarko corridors. Long-term viability hinges on synthetic technology licensing positions and EPA pre-approval documentation portfolios. Watch API specification ratification timelines as inflection indicators for procurement eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group IV Base Oil Production | Captive PAO supply insulates margin pressure from Gulf Coast refinery concentration. |
| Digital Oilfield Platform Partnership | IoT-enabled condition monitoring opens subscription revenue streams with Permian contractors. |
| Biodegradable Formulation Certification | California offshore discharge mandates create niche premium positioning for ester-based products. |
| Direct Supply Agreement Expansion | Bypassing distributor networks captures margin from Diamondback and Pioneer procurement consolidation. |
| Dual-Certification R&D Investment | Parallel EPA Tier 4 and Alberta methane compliance testing accelerates procurement eligibility. |
Research Methodology
Document review covered API specification databases, EPA regulatory filings, FERC pipeline safety standards, and Alberta provincial environmental disclosures, complemented by interviews with lubricant formulation chemists, drilling contractor procurement directors, and base oil refinery operations managers. Secondary validation drew from customs trade records, SEC 10-K filings of integrated majors, and oilfield services expenditure surveys. Bottom-up segment sizing triangulated against top-down energy production forecasts across the analysis window.
Cross-referencing historical synthetic adoption curves with expert panel input on electrification substitution timelines shaped the projection framework. Segmentation dimensions modeled include product type, application, end user, and technology tier across the projection horizon. CAGRs derived from equipment fleet turnover rates, regulatory compliance deadlines, and drilling activity elasticity to crude price movements. Forecast inputs incorporated Permian Basin well completion counts and Alberta steam-assisted gravity drainage expansion plans.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electrification penetration rates and API specification ratification delays. Forecasts reflect assumptions regarding methane regulation enforcement stringency and synthetic base oil capacity expansion timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Gasoline Octane Improvers Market
Fuels
United Kingdom Bunker Fuel Market
Fuels
Gasoline As a Fuel Market
Fuels
Hydrogen Tube Trailer Market
Fuels
Pyrolysis Gas Market
Fuels
Fuel Grinder Market
Fuels
Global Liquid Gas Cylinder (LGC) Market
Fuels
Australia Coal Market
Fuels
Wood Charcoal Market
Fuels
Global Charcoal Market
Fuels
Underground Coal Gasification Market
Fuels
Liquefied Helium Tanks Market
Fuels
Coal Liquefaction Market
Fuels
Diesel Fuel Water Separator Market
Fuels
Europe Aviation Fuel Market
Fuels
Canada Bunker Fuel Market