
 Automotive Oil Strainer Market | 2026-2036
Automotive Oil Strainer Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Oil Strainer Market Analysis
Tool-and-die craftsmanship is bifurcating the competitive landscape as veteran machinists retire faster than apprentices qualify for micron-tolerance work. MANN+HUMMEL leverages its Swabian engineering base to sustain captive production of woven stainless steel mesh. Mahle anchors European OEM supply through integrated aluminum casting and pleating operations. Bosch competes on sensor-integrated strainer modules that merge filtration with oil-condition monitoring.
An automotive oil strainer is a filtration device installed within engine lubrication circuits, typically constructed from pleated stainless steel mesh or engineered polymer housings rated for operating temperatures exceeding 150°C and pressure differentials up to 5 bar, designed to trap metallic debris, carbon particulate, and sludge before oil reaches bearings and valvetrain components. Car oil strainers represent the mature volume base with thinning margins, while heavy-duty oil strainers command premium positioning due to extended service intervals and severe-duty thermal cycling requirements. Component material selection increasingly favors aluminum and composite formulations as OEMs pursue mass reduction targets without sacrificing burst strength.
NHTSA durability standards and EPA emissions compliance protocols in the United States compel strainer designs that maintain filtration efficiency across extended drain intervals, directly elevating OEM specification stringency. EMA homologation requirements and REACH material restrictions in Europe constrain polymer additive packages and mandate recyclability disclosures for replacement components. Stakeholders must monitor evolving powertrain electrification timelines to calibrate strainer portfolio exposure between internal combustion platforms and hybrid lubrication architectures.
Market Dynamics
Powertrain electrification timelines are compressing investment horizons for internal combustion lubrication components, forcing suppliers to hedge portfolios between declining ICE volumes and emerging hybrid thermal management requirements.
Growth Catalysts
- EPA emissions enforcement tightening:Commercial vehicle fleets in the United States are expanding preventive maintenance programs to ensure continuous compliance, directly elevating replacement strainer specifications.
- Extended drain interval mandates:NHTSA durability standards compel strainer designs that maintain filtration efficiency across longer service cycles, pushing OEM specification stringency upward.
- Germany's precision manufacturing corridor:Concentrated demand for OEM-grade woven stainless steel mesh sustains captive production capabilities and anchors premium pricing power.
Market Restraints
- Tool-and-die craftsmanship scarcity:Veteran machinists capable of micron-tolerance pleating operations are retiring faster than apprenticeship pipelines can replenish, constraining quality-tier supply expansion.
- Aluminum input cost volatility:Fluctuating LME aluminum prices compress margins on cast housing components, particularly for mid-tier suppliers without long-term smelter contracts.
- REACH material restrictions:ECHA constraints on polymer additive packages limit formulation flexibility for high-temperature composite housings, forcing costly reformulation cycles.
Strategic Opportunities
- Sensor-integrated strainer modules:Convergence of filtration hardware with oil-condition monitoring electronics creates premium positioning for suppliers with embedded systems capabilities.
- Hybrid lubrication architectures:Dual-circuit thermal management in plug-in hybrids demands specialized strainer geometries for both ICE and e-motor cooling loops.
- India's commercial vehicle upfit:BIS certification requirements for heavy-duty filtration are tightening, creating upgrade demand in a historically price-sensitive replacement market.
Industry Challenges
- Micron-tolerance pleating qualification:Apprenticeship programs lack sufficient throughput to replace retiring Swabian tool-and-die specialists, creating capability scarcity at the premium tier.
- EMA homologation timelines:Extended certification cycles for new composite formulations delay product launches, compressing effective revenue windows before platform redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Oil Strainer Market |
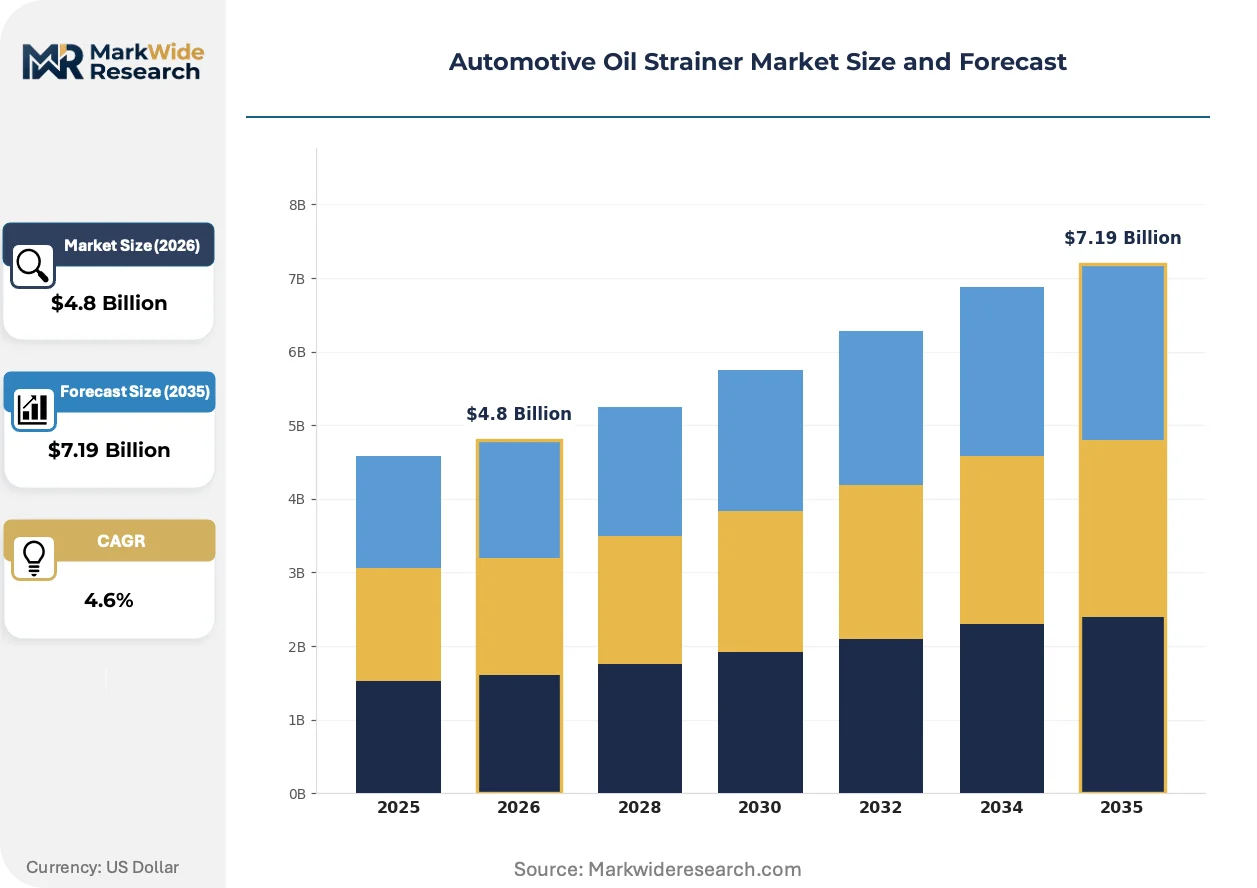
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Car Oil Strainers, Truck Oil Strainers, Motorcycle Oil Strainers, Heavy-Duty Oil Strainers Component Material: Stainless Steel, Plastic, Aluminum, Composite Installation Type: Inline, Cartridge, Drop-in, Spin-on Quality Grade: OEM, Aftermarket, Premium, Standard |
| Companies Covered | MANN+HUMMEL, Mahle, Bosch, Parker Hannifin Corporation, Donaldson Company, Inc., Cummins Filtration, Sogefi Group, Denso Corporation, Hengst SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Oil Strainer Market Emerging Trajectories
Material science advances and embedded electronics are redefining strainer value propositions, shifting competition from pure filtration efficiency toward predictive maintenance integration and thermal-mechanical durability.
Woven stainless steel mesh with engineered wire diameters below 50 microns is supplanting traditional punched metal screens in high-performance applications. European OEM powertrain divisions are adopting these specifications for next-generation turbocharged engines. The transition is compressing addressable market share for stamped-component specialists while elevating barrier-to-entry for woven mesh production.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating legacy non-stick coatings from polymer housing interiors. ECHA enforcement is forcing reformulation of composite additives rated for sustained 150°C oil exposure. Suppliers with fluorine-free surface treatments are capturing specification share in German and French OEM supply chains.
Fleet operators are consolidating aftermarket purchasing through authorized service networks, displacing fragmented independent distributor relationships. This channel compression is most visible in North American Class 8 truck segments, where telematics-integrated maintenance scheduling now dictates strainer replacement timing rather than traditional mileage intervals.
Automotive Oil Strainer Market Segmentation
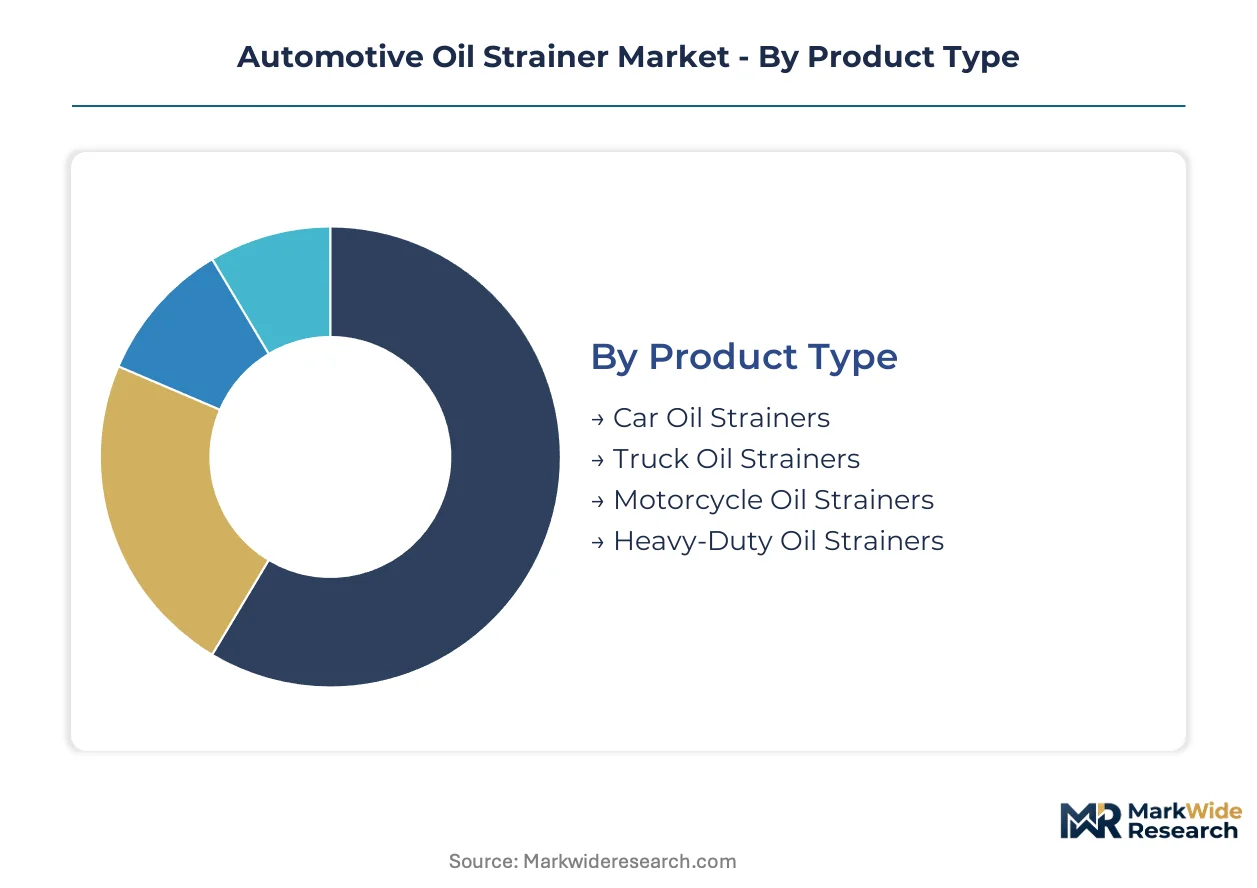
Segmentation in automotive oil strainers reveals how procurement channels bifurcate between captive OEM supply and fragmented aftermarket distribution. Understanding these divides exposes where specification power concentrates and where price competition erodes returns.
Product Type:
Channel mix varies sharply across vehicle categories, with heavy-duty fleets consolidating through authorized service networks while passenger car replacement flows through independent distributors.
- Car Oil Strainers:Pleated stainless steel mesh or engineered polymer housings rated for 150°C operation serve mass-market passenger vehicles. Demand concentrates in Germany's precision manufacturing corridor where OEM-grade woven mesh specifications dominate procurement, though thinning margins pressure mid-tier suppliers.
- Heavy-Duty Oil Strainers:Extended service interval designs withstand severe-duty thermal cycling for commercial vehicle applications. North American Class 8 truck fleets drive replacement volume through telematics-integrated maintenance scheduling rather than traditional mileage intervals, elevating premium positioning.
- Truck Oil Strainers:Intermediate duty cycle products bridge light commercial and heavy-duty specifications.
- Motorcycle Oil Strainers:Compact drop-in configurations address high-revving small displacement engines with space-constrained installations.
Car oil strainers dominate installed base. Heavy-duty oil strainers are where expansion concentrates.
Component Material:
Cost tier stratification separates premium woven mesh from economy stamped alternatives, with aluminum and composite formulations capturing OEM mass reduction mandates.
- Stainless Steel:Woven wire below 50 microns supersedes punched screens in turbocharged engine applications. Swabian engineering bases sustain captive production capabilities for this premium tier, though retiring tool-and-die specialists constrain quality-tier supply expansion.
- Aluminum:Cast housings meet burst strength requirements while shaving grams from powertrain assemblies. Fluctuating LME aluminum prices compress margins for suppliers without long-term smelter contracts.
- Composite:High-temperature polymer formulations face REACH substance restrictions on per- and polyfluoroalkyl substances, forcing fluorine-free surface treatment development.
- Plastic:Injection-molded housings serve economy replacement channels with cost-optimized durability.
Stainless steel commands specification power. Aluminum and composite materials are climbing the fastest as OEM mass targets tighten.
Installation Type:
Volume concentration favors spin-on convenience for aftermarket channels, while inline and cartridge designs anchor OEM original equipment supply.
- Spin-on:Self-contained filter-strainer combinations dominate quick-lube service bays and fleet maintenance depots for rapid replacement cycles.
- Cartridge:Reusable housing with replaceable element reduces material waste and aligns with EMA homologation recyclability disclosures.
- Inline:Fixed-position strainers integrate directly into lubrication circuit architecture for OEM first-fit applications.
- Drop-in:Pan-mounted suction strainers serve motorcycle and compact engine installations with minimal tooling requirements.
Spin-on configurations anchor aftermarket volume. Cartridge designs are gaining share fastest as sustainability compliance tightens.
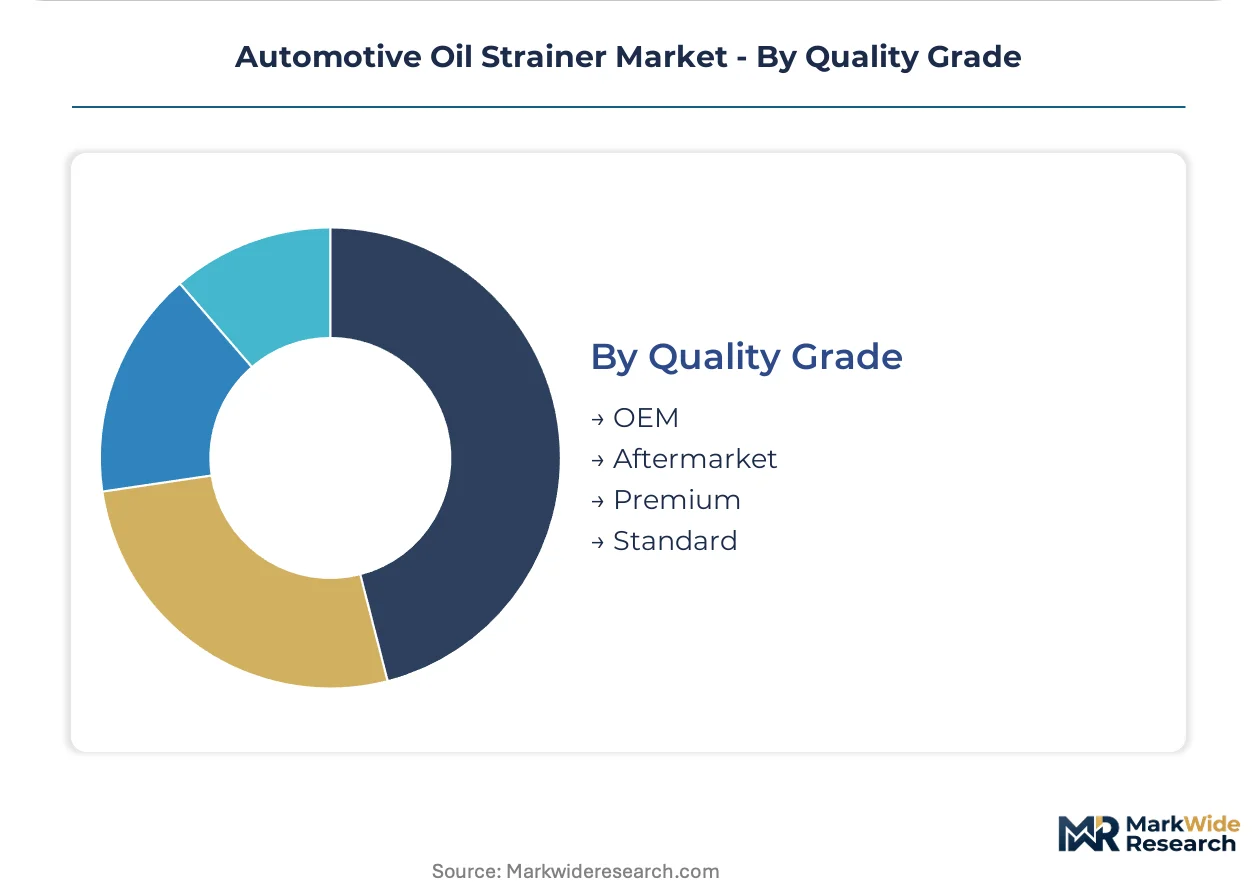
Quality Grade:
Customer type separates OEM specification control from aftermarket price sensitivity, with premium tiers emerging around sensor-integrated modules.
- OEM:Micron-tolerance pleating and woven mesh specifications maintain filtration efficiency across extended drain intervals mandated by NHTSA durability standards. EMA homologation timelines constrain new composite formulation launches.
- Premium:Sensor-integrated strainer modules merge filtration hardware with oil-condition monitoring electronics, creating positioning for embedded systems capabilities.
- Aftermarket:Price-competitive replacements serve independent repair channels with functional equivalence to original specifications.
- Standard:Economy-tier products address cost-sensitive fleet operators and developing market upgrade cycles.
OEM grade dominates specification power. Premium grade is where technology differentiation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Germany's precision manufacturing corridor demands woven stainless steel mesh for OEM-grade specifications, while North American fleets prioritize sensor-integrated modules for predictive maintenance. India's commercial vehicle upfit market is tightening certification requirements, creating upgrade demand in a historically price-sensitive replacement channel.
United States
Class 8 truck fleets drive replacement volume through telematics-integrated maintenance scheduling rather than traditional mileage intervals. EPA emissions enforcement tightening compels strainer designs that maintain filtration efficiency across extended drain intervals. Detroit's automotive engineering cluster anchors OEM specification development for turbocharged engine applications.
Germany
Swabian engineering bases sustain captive production capabilities for micron-tolerance woven mesh as veteran tool-and-die specialists retire. EMA homologation requirements and REACH material restrictions constrain polymer additive packages and mandate recyclability disclosures. Stuttgart's precision manufacturing corridor concentrates demand for OEM-grade specifications that dominate procurement decisions.
China
Domestic OEMs are adopting dual-circuit thermal management for plug-in hybrids, demanding specialized strainer geometries for both ICE and e-motor cooling loops. MIIT fuel consumption regulations and GB standards for commercial vehicle durability elevate specification stringency. Yangtze River Delta manufacturing clusters are scaling composite housing production despite fluorine-free coating reformulation challenges.
India
BIS certification requirements for heavy-duty filtration are tightening, creating upgrade demand in a historically price-sensitive replacement market. Commercial vehicle upfit programs in Maharashtra and Gujarat are shifting procurement toward authorized service networks. Pune's automotive component belt is absorbing technology transfer from European joint ventures for woven mesh qualification.
Japan
METI carbon neutrality targets are compressing ICE platform investment horizons while preserving hybrid lubrication architecture demand. JIS standards for extended drain intervals sustain premium positioning for sensor-integrated modules. Nagoya's powertrain engineering cluster maintains specification control over woven stainless steel mesh for next-generation turbocharged engines.
Automotive Oil Strainer Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a bifurcated structure where specification power concentrates with vertically capable incumbents. The upper tier commands OEM supply relationships through captive manufacturing of woven mesh and aluminum casting operations. Mid-tier players compete on aftermarket volume with stamped-component alternatives. Strategic moves center on sensor-integrated module development and hybrid thermal management diversification.
Among German-based engineering groups, MANN+HUMMEL, Mahle, and Bosch occupy positions across the premium tier. MANN+HUMMEL exemplifies the woven mesh specialist archetype with Swabian manufacturing heritage. Mahle represents the integrated casting-and-pleating model that anchors European OEM supply. Bosch sits within the embedded systems convergence vector, merging filtration hardware with oil-condition monitoring electronics. These three entities collectively illustrate how specification power flows to players controlling both material science and sensor integration capabilities.
| Leading Market Players |
|---|
| MANN+HUMMEL |
| Mahle |
| Bosch |
| Parker Hannifin Corporation |
| Donaldson Company, Inc. |
| Cummins Filtration |
| Sogefi Group |
| Denso Corporation |
| Hengst SE |
| Others |
Supply Flow & Price Mechanics
Woven stainless steel mesh below 50 microns supplanting punched metal screens is redrawing procurement geography toward Swabian engineering clusters while compressing margins for stamped-component specialists locked into spot aluminum markets.
Pricing Analysis
Long-term offtake contracts dominate woven mesh procurement from German suppliers, insulating OEM-grade tiers from LME aluminum volatility while spot-market exposure punishes mid-tier cast housing producers. Price differentiation separates sensor-integrated premium modules from economy stamped alternatives, with certification tier and volume scale as the decisive levers. Cost compression in composite formulations is intensifying because REACH-mandated fluorine-free coating reformulation extends development cycles. Fleet operators consolidating through authorized service networks exhibit lowest price sensitivity; independent distributors serving passenger car replacement channels face acute margin pressure.
Supply Chain Analysis
Inbound logistics costs on Asia-Europe container lanes fluctuate with port congestion at Rotterdam and Hamburg, compressing just-in-time delivery windows for Yangtze River Delta composite housing suppliers. Captive production concentrates in Germany, China, and Japan; woven mesh draws from Swabian tool-and-die bases while aluminum casting feeds from Yangtze and Nagoya manufacturing clusters. Single-source vulnerability sits with retiring micron-tolerance pleating specialists whose apprenticeship pipelines lack throughput. Distribution runs through OEM captive supply for first-fit, authorized service networks for fleet replacement, and independent distributors for fragmented aftermarket volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain electrification compressing ICE investment horizons creates high-growth disruption for suppliers hedging between declining combustion volumes and emerging hybrid thermal management architectures.
For Market Incumbents: Consolidate backward integration into woven mesh production to defend against Swabian capability scarcity, while accelerating sensor-integrated module R&D to capture specification power as NHTSA extends drain interval mandates. Channel control through authorized service network partnerships insulates premium positioning from independent distributor price erosion. For New Entrants and Emerging Players: BIS certification fast-track for heavy-duty filtration in India's commercial vehicle upfit market opens white-space penetration in a historically price-sensitive replacement channel. Target Maharashtra and Gujarat fleet operators shifting procurement toward authorized networks. Embed European joint venture technology transfer for woven mesh qualification as the decisive go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier stamped-component specialists facing margin compression from aluminum volatility and mesh substitution. Five-to-ten-year viability hinges on hybrid lubrication architecture diversification. Watch EPA emissions enforcement intensity as the inflection signal for replacement specification upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Module Development | Merges Bosch-style oil-condition monitoring with filtration hardware for predictive maintenance positioning. |
| Backward Integration into Woven Mesh | Secures captive supply of micron-tolerance stainless steel wire as Swabian tool-and-die specialists retire. |
| Fluorine-Free Coating Reformulation | Aligns composite housing production with ECHA REACH substance restrictions for German OEM supply qualification. |
| Authorized Service Network Partnership | Captures fleet replacement volume as North American Class 8 operators consolidate through telematics-integrated channels. |
| Hybrid Thermal Management Diversification | Addresses dual-circuit strainer demand from China's MIIT-regulated plug-in hybrid powertrain proliferation. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across OEM platform engineering, Tier 1 supplier procurement, aftermarket distribution, and fleet maintenance operations. Primary fieldwork combined with secondary validation from vehicle production databases, IHS Markit registration data, EPA enforcement disclosures, and ECHA substance restriction filings. Bottom-up volume triangulation against top-down value estimates anchored forecast integrity.
Across the projection horizon, the analytical framework modeled segmentation by vehicle class, propulsion architecture, component material, and installation type. CAGRs derived from historical production trajectories, OEM platform lifecycle schedules, and regulatory compliance timeline acceleration. Forecast inputs incorporated powertrain electrification adoption curves and REACH reformulation cost pass-through assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA emissions enforcement and Swabian mesh production continuity; material deviation would warrant model refresh. Specific risks include faster-than-projected ICE platform phase-out, aluminum price spike persistence, and EMA homologation timeline extension. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
Hydrocarbon Market
Petroleum Products
Oil Shale Market
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Naphtha Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
Performance Oil Sales Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Tar Oil Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
Paraffin Oil Market
Petroleum Products
Natural Gas Liquid Market