
 Crude Oil Pour Point Depressant Market | 2026-2036
Crude Oil Pour Point Depressant Market Size, Share, and Industry Trends Forecast 2026-2036
Crude Oil Pour Point Depressant Market Insights
Performance-based chemical management contracts is repositioning how pour point depressants are procured and priced in the upstream sector. Clariant leverages its integrated wax control portfolio to anchor long-term supply agreements with major pipeline operators. Evonik Industries competes through specialized polymer architectures that sustain treat rates across variable crude compositions. The Lubrizol Corporation dominates the North American midstream channel through backward integration into polymeric dispersant manufacturing.
Crude oil pour point depressants are polymeric additives, typically polymethacrylates or alkylated naphthalene copolymers, formulated to disrupt paraffin crystal lattice formation and reduce the temperature at which crude oil ceases to flow. These chemicals function by co-crystallizing with wax molecules to modify crystal morphology, enabling pipeline transport and storage operations in ambient conditions as low as minus forty degrees Celsius without heating infrastructure. Paraffin inhibitors command the largest share of product-type revenue due to their established efficacy across light-to-medium waxy crudes, though asphaltene dispersants represent the fastest-growing category as heavy oil production expands. Within applications, pipeline treatment generates the most stable margin pools because of continuous injection requirements and contracted volume commitments, while production-field deployment offers higher growth velocity tied to greenfield developments in cold-climate basins.
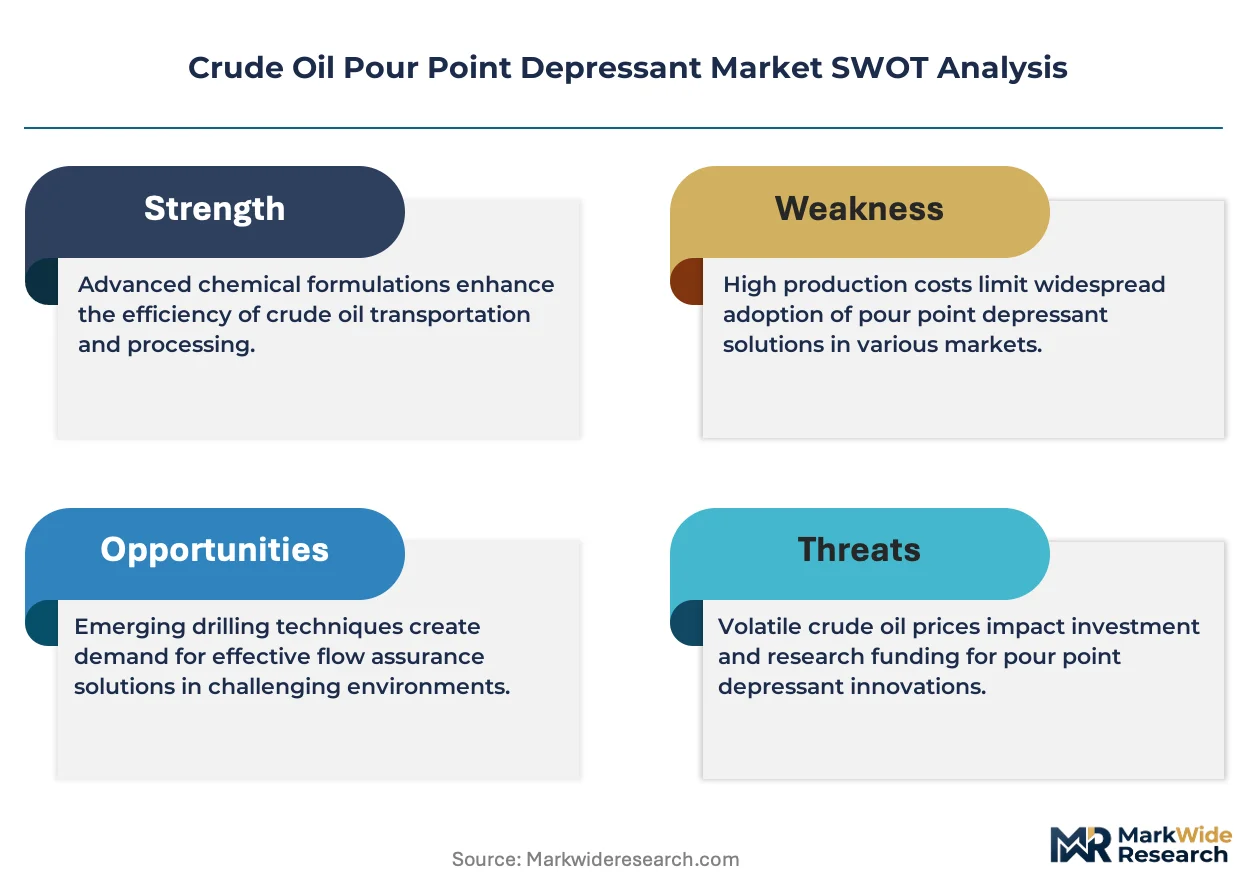
The EPA enforces spill prevention and flow assurance standards under the Clean Water Act that mandate chemical compatibility testing for additives used in interstate pipeline systems. Transport Canada's Energy Regulator imposes parallel requirements for thermal stability and environmental fate assessment of pour point depressants deployed on cross-border routes. China's MEE has introduced stricter discharge limits for production chemicals that are forcing reformulation of legacy dispersant chemistries. Stakeholders must monitor how evolving biodegradability mandates and carbon-intensity disclosure rules reshape product registration pathways and procurement criteria across jurisdictions.
Market Dynamics
Performance-based chemical management contracts are compressing traditional spot procurement for pour point depressants, forcing suppliers to absorb inventory risk and guarantee flow assurance outcomes across variable crude assays.
Growth Catalysts
- Subzero Pipeline Expansion:Permian Basin operators are extending unheated gathering lines into North Dakota and Montana, creating continuous demand for polymethacrylate formulations that sustain flow at minus forty degrees Celsius.
- EPA Spill Prevention Mandates:Updated Clean Water Act rules now require documented chemical compatibility testing for all additives in interstate crude systems, accelerating replacement of legacy dispersants with registered alternatives.
- Waxy Crude Upgrading:Steam-assisted gravity drainage in Alberta oil sands is yielding heavier paraffin content, requiring higher treat rates and specialized alkylated naphthalene copolymers at the production field.
Market Restraints
- Feedstock Concentration:Specialty methacrylate monomers rely on concentrated supply from Texas Gulf Coast petrochemical complexes, exposing formulators to hurricane-related disruption.
- Biodegradability Thresholds:China's MEE discharge limits for production chemicals are forcing reformulation of established polymeric architectures, extending product registration timelines.
- Thermal Stability Limits:Polymethacrylates degrade above one hundred twenty degrees Celsius, constraining deployment in high-temperature downhole applications where asphaltene dispersants remain necessary.
Strategic Opportunities
- Brazil Pre-Salt Development:Deepwater fields off Santos Basin require cold-flow assurance for subsea tiebacks, opening demand for high-pressure compatible pour point depressants.
- Carbon-Intensity Disclosure:EU CSRD reporting requirements are creating preference for bio-based dispersant chemistries with verified lifecycle emissions data.
- Real-Time Injection Control:Integration of fiber-optic monitoring with automated chemical skids is enabling dose optimization and outcome-based contracting models.
Industry Challenges
- Wax Deposition Modeling:Predicting paraffin crystallization kinetics across blended crude streams requires scarce computational fluid dynamics expertise and validated field data.
- Cross-Border Registration:Transport Canada's thermal stability standards diverge from EPA protocols, forcing dual testing protocols for additives serving Alberta-to-Midwest pipeline routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crude Oil Pour Point Depressant Market |
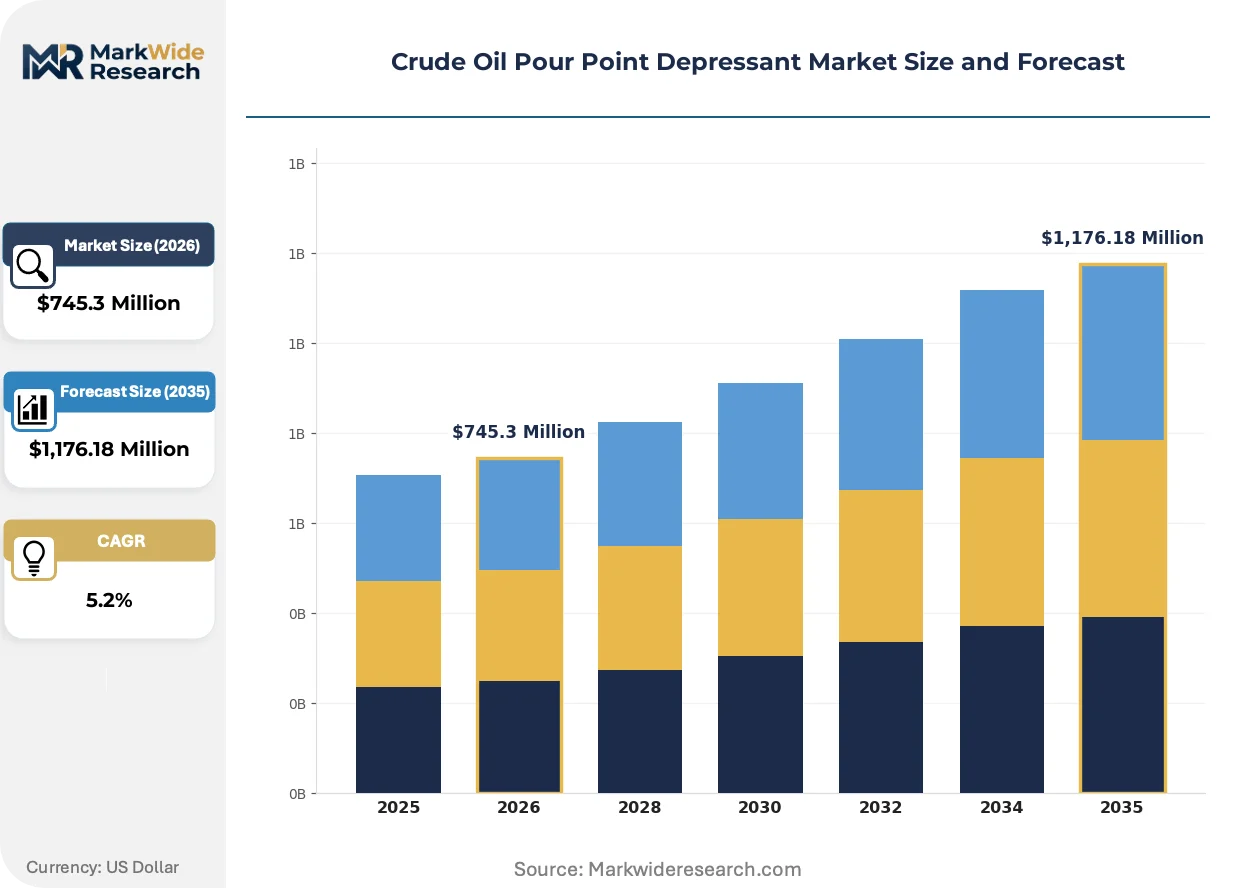
| Market Size in 2026 | $745.3 Million |
| Market Size in 2035 | $1,176.18 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paraffin Inhibitors, Asphaltene Dispersants, Wax Modifiers, Flow Improvers Application: Refinery, Pipeline, Production, Transportation Delivery Mode: Bulk, Packaged, Customized, Blended End User: Oil & Gas Companies, Refiners, Transporters, Distributors |
| Companies Covered | Clariant, Evonik Industries, The Lubrizol Corporation, Afton Chemical, BASF SE, Croda International, Infineum International, Chevron Phillips Chemical, AkzoNobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crude Oil Pour Point Depressant Market Trends and Innovations
Digitalization of chemical injection systems and bio-based formulation chemistry are converging to reshape how pour point depressants are specified, dosed, and validated in cold-climate crude operations.
Microencapsulated paraffin inhibitors are decentralizing chemical deployment from centralized tank farms to distributed injection skids along gathering networks. Midstream operators in the Bakken formation are piloting these solid-phase formulations to eliminate heated storage tanks and reduce trucking frequency. The technology is decentralizing supply chain architecture by enabling just-in-time dosing at well pads rather than batch treatment at pipeline headers.
REACH authorization requirements for persistent organic pollutants are tightening acceptable thresholds for certain alkyl phenol ethoxylates used in legacy dispersant formulations. European formulators are accelerating substitution with biodegradable alternatives ahead of sunset dates. The regulation is compressing product development cycles for suppliers serving North Sea offshore platforms and Rotterdam refining corridors.
Buyers are consolidating chemical spend under integrated service contracts that bundle pour point depressants with corrosion inhibitors and demulsifiers. Large Permian Basin producers are negotiating three-year sole-source agreements with guaranteed throughput penalties. This concentration is visible most acutely in Texas and New Mexico, where top-ten operators now control over half of chemical procurement decisions.
Crude Oil Pour Point Depressant Market Segmentation
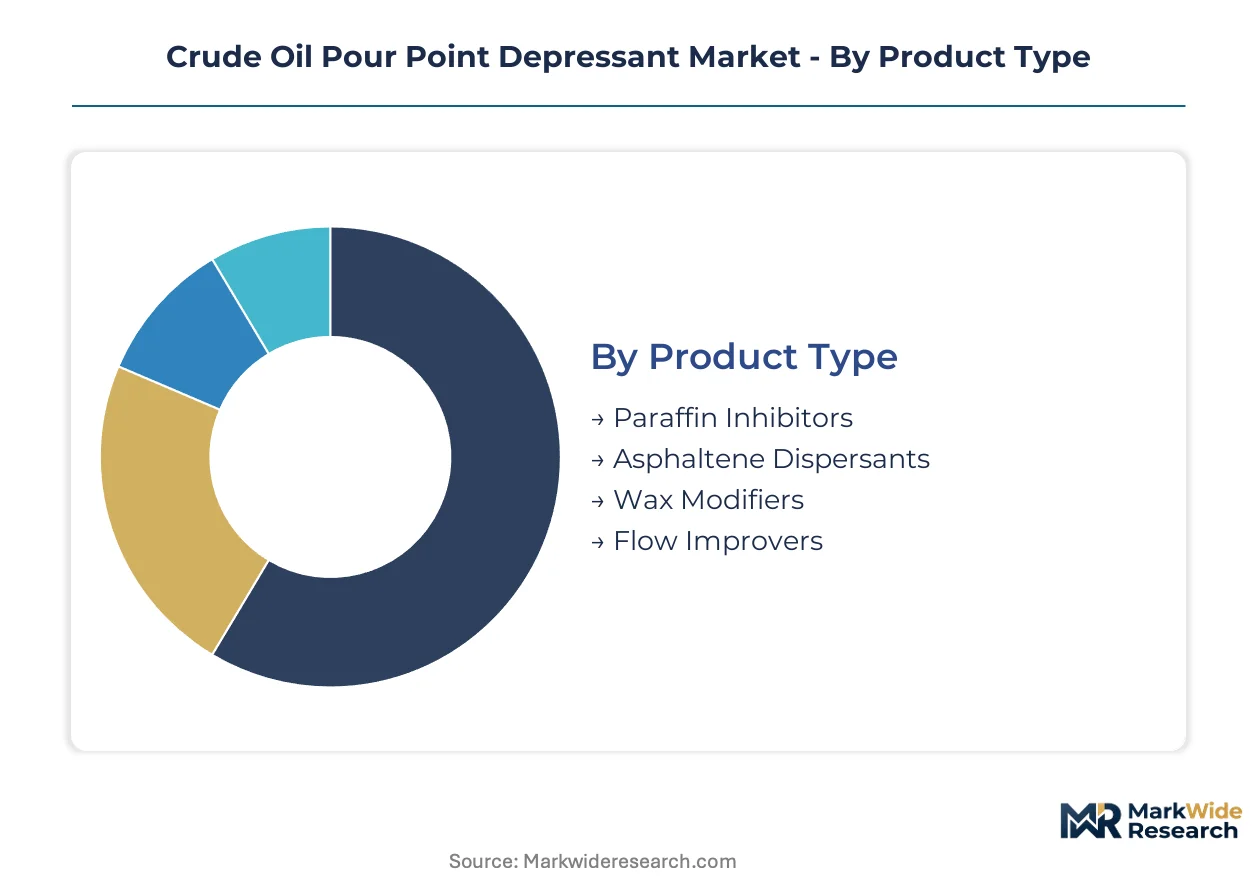
Pour point depressant procurement varies sharply across operational contexts, with pipeline operators prioritizing continuous injection reliability while production-field buyers optimize for variable treat-rate flexibility. The segmentation reveals how formulation chemistry, delivery logistics, and end-user risk profiles intersect to determine supplier selection criteria and contract structures.
Product Type:
Replacement cycles for pour point depressants accelerate when crude assays shift toward heavier paraffin content or when regulatory biodegradability mandates obsolete legacy chemistries.
- Paraffin Inhibitors:Polymethacrylate and alkylated naphthalene copolymer formulations co-crystallize with wax molecules to modify crystal morphology and sustain flow at subzero temperatures. Demand concentrates in Permian Basin gathering systems where waxy crude production rises and unheated pipeline extensions into North Dakota and Montana require proven cold-flow assurance.
- Asphaltene Dispersants:Polymeric and surfactant-based chemistries prevent asphaltene aggregation in heavy crude streams where thermal degradation of polymethacrylates above 120°C constrains alternative deployment. Alberta oil sands operators deploy these additives in steam-assisted gravity drainage production where higher paraffin content demands specialized treatment.
- Wax Modifiers:Crystal habit modifiers alter paraffin deposition patterns without full flow-point suppression, serving niche applications in blended crude systems.
- Flow Improvers:Viscosity-reducing additives complement primary pour point depressants in high-pour-point crude transport scenarios.
Volume placements concentrate in Paraffin Inhibitors; the faster expansion belongs to Asphaltene Dispersants.
Application:
Margin structures diverge across application contexts, with continuous injection requirements in pipeline systems supporting long-term contracting while production-field deployment rewards formulation flexibility.
- Pipeline:Continuous injection mandates at compressor stations and pump headers generate contracted volume commitments with stable margin pools. North American midstream operators favor three-year sole-source agreements bundling pour point depressants with corrosion inhibitors and demulsifiers.
- Production:Wellpad and gathering-system deployment requires variable treat-rate adjustment based on real-time crude assay changes, favoring suppliers with rapid-response logistics. Greenfield developments in cold-climate basins drive higher growth velocity as operators extend unheated infrastructure.
- Refinery:Storage tank and unit feed conditioning applications demand thermal stability across broader temperature ranges than transport applications.
- Transportation:Rail and marine loading terminals require rapid-acting formulations compatible with limited residence time in transfer systems.
Revenue stability clusters in Pipeline; Production claims the steepest expansion trajectory.
Delivery Mode:
Supply chain configuration shapes procurement economics, with centralized bulk supply dominating high-volume corridors while distributed delivery models penetrate remote production areas.
- Bulk:Tanker-truck and railcar delivery to centralized tank farms serves major pipeline headers and refinery complexes with predictable offtake volumes. Texas Gulf Coast petrochemical concentration exposes this mode to hurricane-related disruption risk.
- Packaged:Drum and tote delivery enables smaller operators and remote wellpads to maintain inventory without heated storage infrastructure.
- Customized:Assay-specific blending at regional service centers addresses variable crude composition across blended stream systems.
- Blended:Pre-formulated multi-functional packages combining pour point depressants with paraffin dispersants or corrosion inhibitors reduce injection point complexity.
Throughput scale favors Bulk; operational flexibility drives Customized adoption.
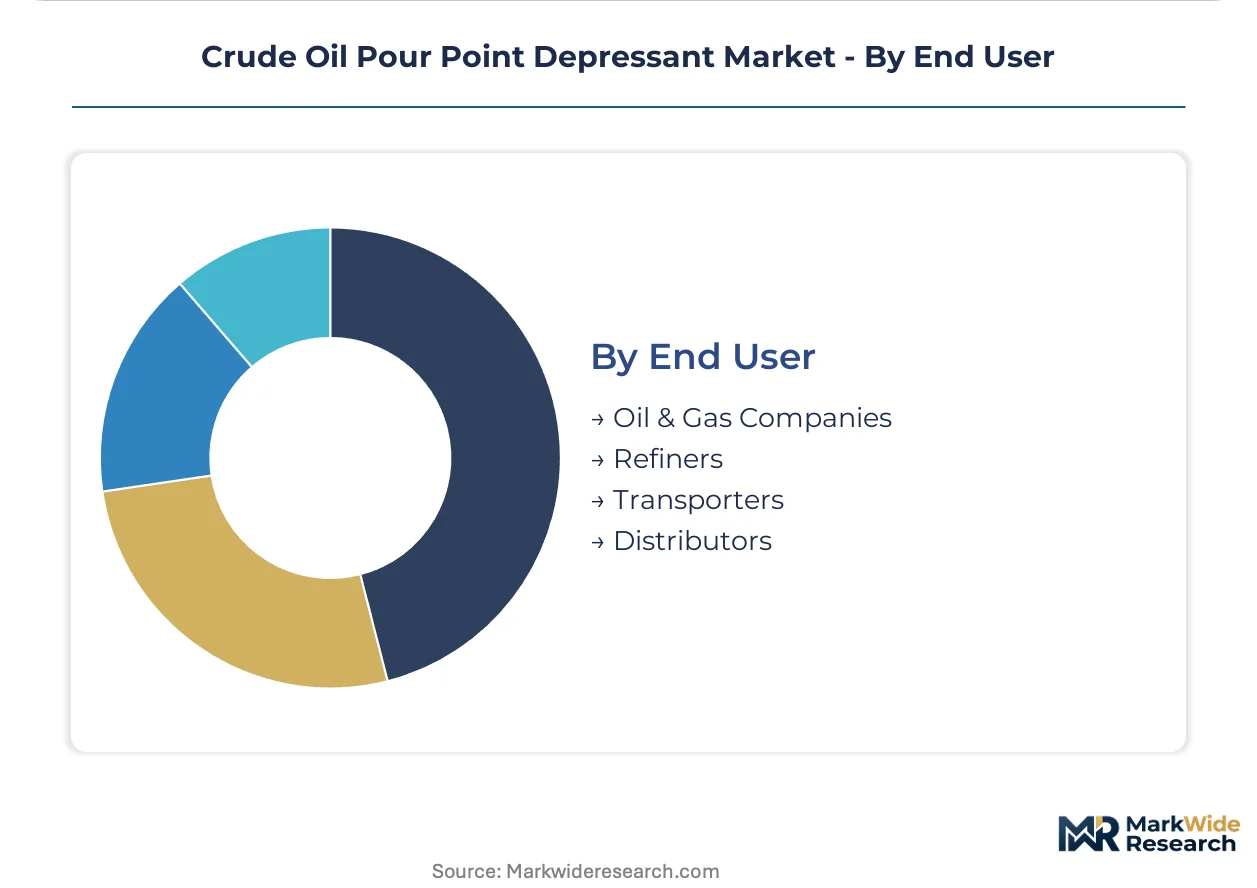
End User:
Procurement sophistication varies with organizational scale, with integrated majors leveraging performance-based contracts while independent operators prioritize spot availability.
- Oil & Gas Companies:Upstream operators with proprietary pipeline networks negotiate integrated chemical management contracts transferring inventory risk to suppliers. Top-ten Permian Basin producers now control over half of regional chemical procurement decisions.
- Refiners:Downstream processors specify additives based on crude slate flexibility requirements and unit feed compatibility testing.
- Transporters:Common carrier pipeline operators face EPA Clean Water Act mandates for documented chemical compatibility testing in interstate systems.
- Distributors:Regional chemical marketers serve independent producers with limited technical staff, requiring supplier-provided dosing guidance and field support.
Contract value aggregates with Oil & Gas Companies; Distributors expand reach into fragmented independent production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin spanning West Texas and southeastern New Mexico anchors global pour point depressant consumption as operators extend unheated gathering infrastructure into subzero territories.
United States
EPA spill prevention mandates under the Clean Water Act now require documented chemical compatibility testing for all additives in interstate crude systems. Bakken formation operators in North Dakota pilot microencapsulated paraffin inhibitors to eliminate heated storage tanks at well pads. Midstream consolidators in Texas and New Mexico negotiate three-year sole-source agreements bundling pour point depressants with corrosion inhibitors.
Canada
Transport Canada imposes parallel thermal stability and environmental fate assessment requirements for additives on cross-border Alberta-to-Midwest routes. Steam-assisted gravity drainage in the Alberta oil sands yields heavier paraffin content demanding specialized alkylated naphthalene copolymers. Calgary-based chemical service centers provide assay-specific blending for variable crude composition across blended stream systems.
China
MEE discharge limits for production chemicals force reformulation of legacy polymeric architectures and extend product registration timelines. Daqing oilfield operators in Heilongjiang province require cold-flow assurance for waxy crude transport through subzero winters. State pipeline companies consolidate chemical procurement under integrated service contracts with guaranteed throughput penalties.
Brazil
ANVISA regulates chemical fate assessment for offshore production additives deployed in sensitive marine environments. Deepwater pre-salt fields off the Santos Basin require high-pressure compatible pour point depressants for subsea tiebacks. Petrobras anchors demand as the national operator extends unheated subsea infrastructure into colder Atlantic depths.
Saudi Arabia
The national oil company maintains stringent internal specifications for chemical thermal stability in high-temperature reservoir applications. Eastern Province production facilities deploy asphaltene dispersants where downhole temperatures exceed polymethacrylate degradation thresholds. Aramco's chemical management contracts transfer inventory risk to suppliers while mandating real-time injection monitoring.
Crude Oil Pour Point Depressant Market Competitive Landscape
Capital-heavy integrated petrochemical producers compete with asset-light specialty formulators for pour point depressant market position. The supplier base concentrates around three strategic tiers: diversified chemical majors with backward integration into monomer production, mid-sized specialty polymer houses with regional formulation expertise, and niche technology licensors with patented molecular architectures. Competitive moves center on long-term performance-based contracting that absorbs customer inventory risk and vertical integration into captive methacrylate supply.
Within the diversified chemical major tier, Clariant exemplifies the integrated wax control portfolio approach while BASF SE occupies a position anchored in broad petrochemical feedstock access. Evonik Industries represents the specialty polymer architecture archetype with concentrated expertise in methacrylate chemistry. These three companies illustrate how supplier positioning diverges between feedstock security and formulation specialization.
| Leading Market Players |
|---|
| Clariant |
| Evonik Industries |
| The Lubrizol Corporation |
| Afton Chemical |
| BASF SE |
| Croda International |
| Infineum International |
| Chevron Phillips Chemical |
| AkzoNobel |
| Others |
Pricing and Supply Chain Analysis
Microencapsulated paraffin inhibitor deployment simultaneously compresses logistics costs and decentralizes supply chain nodes away from Gulf Coast concentration. This solid-phase formulation shift enables just-in-time dosing at well pads while eliminating heated storage infrastructure, redistributing procurement power toward regional service centers.
Pricing Analysis
Throughput-guarantee contracts anchor pricing structures, with suppliers absorbing inventory risk and penalties for flow assurance failures. Price differentiation separates EPA-registered formulations from legacy chemistries facing sunset dates, while volume scale drives negotiation leverage for Permian Basin operators. Cost compression in standard-grade polymethacrylates is intensifying because of methacrylate monomer oversupply from Texas Gulf Coast expansions. Independent distributors exhibit highest price sensitivity; integrated majors with captive pipeline networks demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Calgary, Houston, and Rotterdam anchor hub-and-spoke patterns for assay-specific blending and rapid field response. Specialty methacrylate monomers draw from Texas Gulf Coast and Rotterdam petrochemical complexes, with alkylated naphthalene feedstocks sourcing from South Korean and German aromatics producers. Single-source vulnerability concentrates around hurricane-exposed Gulf Coast methacrylate capacity. Distribution runs through midstream chemical service companies bundling pour point depressants with corrosion inhibitors and demulsifiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Clean Water Act chemical compatibility mandates construct a cost-of-compliance moat that favors registered incumbents with established testing protocols and disadvantages unregistered import alternatives.
For Market Incumbents: Deepen backward integration into captive methacrylate supply to insulate margin structures from Gulf Coast feedstock volatility. Secure three-year sole-source agreements with top-ten Permian Basin producers before microencapsulated formulation patents expire. Certification investment in dual EPA-Transport Canada testing protocols defends against cross-border registration divergence.
For New Entrants and Emerging Players: Enter via bio-based dispersant chemistry development targeting EU CSRD carbon-intensity disclosure requirements. Brazil pre-salt deepwater fields offer the most penetrable geography, with ANVISA marine fate assessment creating barrier advantages for compliant formulators. Partner with fiber-optic monitoring system integrators to bundle real-time injection control as differentiated service.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty polymer architecture acquisition by diversified chemical majors seeking wax control portfolio gaps. Long-term viability hinges on biodegradability-mandated reformulation capability across the analysis window. Watch China's MEE discharge limit enforcement velocity as inflection indicator for legacy chemistry obsolescence timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methacrylate Monomers | Captive supply from Texas Gulf Coast complexes insulates formulators from hurricane disruption risk. |
| Long-term Performance-Based Supply Agreement | Three-year sole-source contracts with Permian Basin operators transfer inventory risk to suppliers. |
| Bio-Based Formulation Development | Biodegradable dispersant chemistries satisfy EU CSRD carbon-intensity disclosure requirements. |
| Joint Venture with Fiber-Optic Monitoring Provider | Real-time injection control integration enables outcome-based contracting and dose optimization. |
| Dual EPA-Transport Canada Registration Investment | Cross-border testing protocols capture Alberta-to-Midwest pipeline route volume. |
Research Methodology
Trade databases, SEC 10-K chemical segment disclosures, and EPA spill prevention compliance filings formed the secondary backbone. Primary interviews with pipeline operations managers, chemical procurement leads at integrated majors, regional service center technical directors, and EHS compliance officers validated formulation efficacy claims and contract structures. Bottom-up volume modeling across product type, application, and delivery mode segments triangulated against top-down petrochemical capacity analysis.
Bottom-up segment sizing anchored forecast construction, with top-down macro constraints from crude production outlooks and pipeline expansion timelines. Modeled dimensions span paraffin inhibitor versus asphaltene dispersant chemistry, pipeline versus production-field deployment, bulk versus packaged delivery, and regional regulatory cluster. CAGRs derived from segment-level volume trajectory analysis incorporating treat rate intensification from heavier crude assays and greenfield cold-climate infrastructure.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt biodegradability mandate acceleration or Gulf Coast methacrylate supply disruption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Germany Refined Petroleum Products Market
Petroleum Products
Malaysia Refined Petroleum Products Market
Petroleum Products
Petcoke Market
Petroleum Products
LPG [Liquefied Petroleum Gas] Market
Petroleum Products
Oil Storage Sales Market
Petroleum Products
Pale Oil Market
Petroleum Products
North Africa Refined Petroleum Products Market
Petroleum Products
Petroleum Benzine Market
Petroleum Products
Hydrocarbon Market
Petroleum Products
Quenching Oil Market
Petroleum Products
Spindle Oil Market
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
Crude Oil Market
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
East Africa Refined Petroleum Products Market
Petroleum Products
Paraffin Oil Market