
 Crude Tall Oil Market | 2026-2036
Crude Tall Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Crude Tall Oil Market Analysis
Modular fractionation is hardening as the dominant supply configuration, letting buyers purchase discrete cuts rather than full crude streams. Ingevity Corporation leverages captive kraft mill partnerships to secure feedstock priority across the US Southeast. Forchem Oyj anchors its margin structure through backward integration into Finnish and Swedish pulp assets. Kraton Corporation competes on rosin acid purity grades for adhesives and tackifier applications.
Crude tall oil is a dark, viscous liquid byproduct of kraft pulp cooking, comprising fatty acids, rosin acids, and sterols in varying proportions depending on wood species and digester conditions. The material serves primarily as a renewable feedstock for chemical fractionation into adhesives, lubricants, surfactants, and increasingly biofuel intermediates. Fatty acids and rosin acids together constitute the bulk of commercial value extraction, with sterols representing a higher-margin specialty tier due to pharmaceutical and nutraceutical end uses. Application demand in surfactants and adhesives tracks broader industrial output, while biofuels end use is expanding fastest on renewable diesel and sustainable aviation fuel blending mandates.
EPA renewable fuel standards in the United States and EU Green Deal biomass sustainability criteria shape product qualification and market access for CTO-derived materials. REACH registration requirements and ECHA guidance on substance evaluation add compliance layers for European fractionators exporting derivative chemicals. Stakeholders must monitor feedstock competition from other lipid pathways and pulp mill energy-transition decisions that could alter CTO availability independent of chemical demand cycles.
Market Dynamics
Modular fractionation infrastructure is restructuring how buyers source crude tall oil, decoupling procurement of fatty acid cuts from rosin acid streams and enabling spot-market purchasing that bypasses traditional long-term offtake contracts.
Growth Catalysts
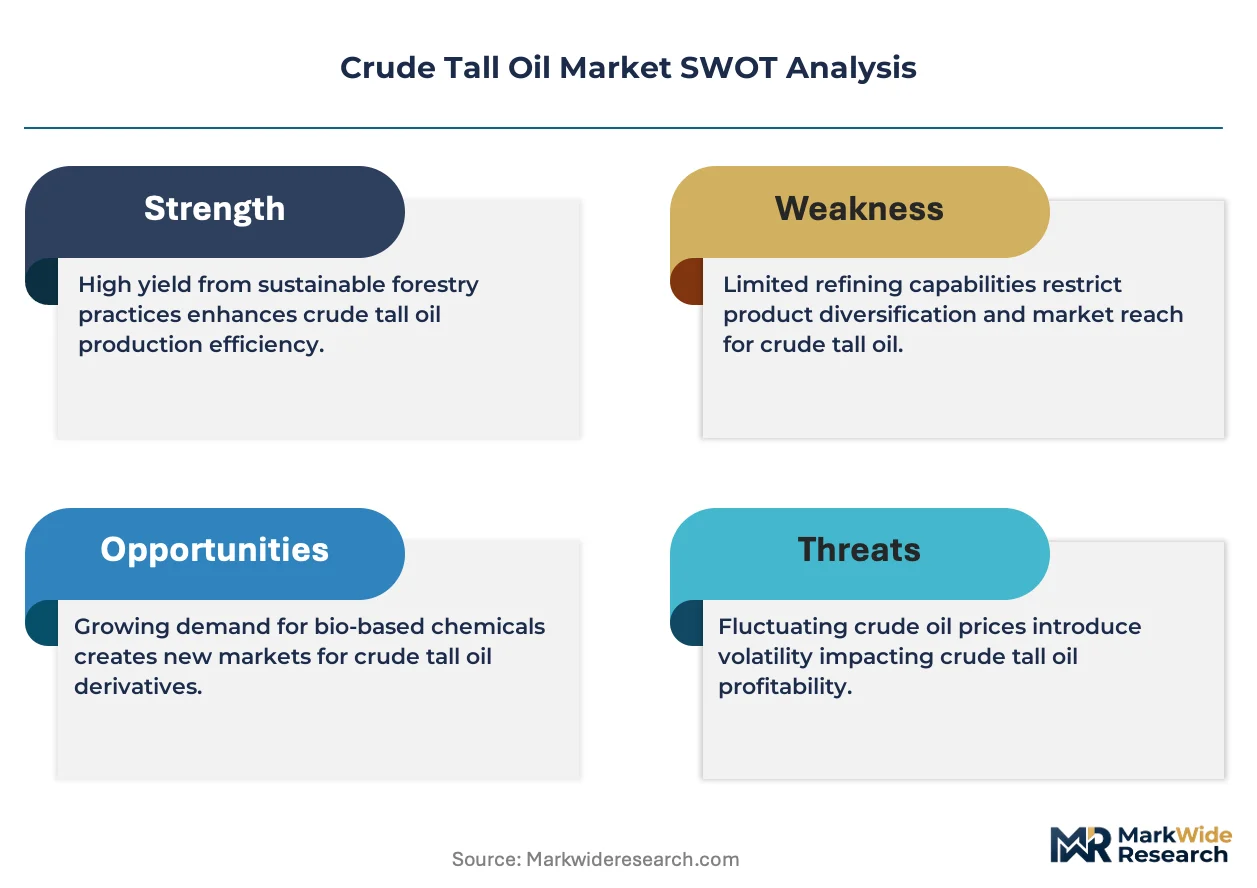
- EU Green Deal biomass criteria:Renewable Energy Directive II qualification pathways for CTO-derived sustainable aviation fuel are opening premium pricing tiers for compliant fractionators.
- Biofuel blending mandates:EPA renewable fuel standards in the United States are pulling distillation residues into renewable diesel hydroprocessing at refineries from Texas to Louisiana.
- Nordic pulp-to-chemicals integration:Finnish and Swedish kraft complexes are anchoring supply security through captive CTO recovery systems that stabilize feedstock access.
Market Restraints
- Pine chemical substitution:Gum rosin from Chinese tapping operations and petroleum-derived hydrocarbon resins are compressing price ceilings for standard-grade rosin acids in adhesives.
- Feedstock competition:Pulp mill energy-transition investments into black liquor gasification threaten CTO diversion to on-site power generation rather than chemical extraction.
- REACH registration burdens:ECHA substance evaluation timelines for derivative tall oil fatty acid esters are extending market access delays for European fractionators.
Strategic Opportunities
- Sustainable aviation fuel qualification:ASTM D7566 annex pathways for biomass-derived lipids are creating first-mover advantages for CTO hydroprocessed esters.
- Pharmaceutical sterol demand:Cholesterol-lowering drug intermediates and vitamin D precursors are commanding 4-6x fatty acid margins for purified sitosterol and campesterol fractions.
- Direct refinery offtake contracting:Bypassing traditional chemical distributors, biofuel producers are negotiating direct supply relationships with Scandinavian pulp operators.
Industry Challenges
- Fractionation technician scarcity:Specialized distillation expertise for heat-sensitive rosin acid recovery is concentrating among retiring operators at legacy pine chemical facilities.
- Multi-jurisdiction compliance layering:Simultaneous EPA pathway approvals, EU sustainability certification, and ISCC PLUS chain-of-custody audits are stretching quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crude Tall Oil Market |
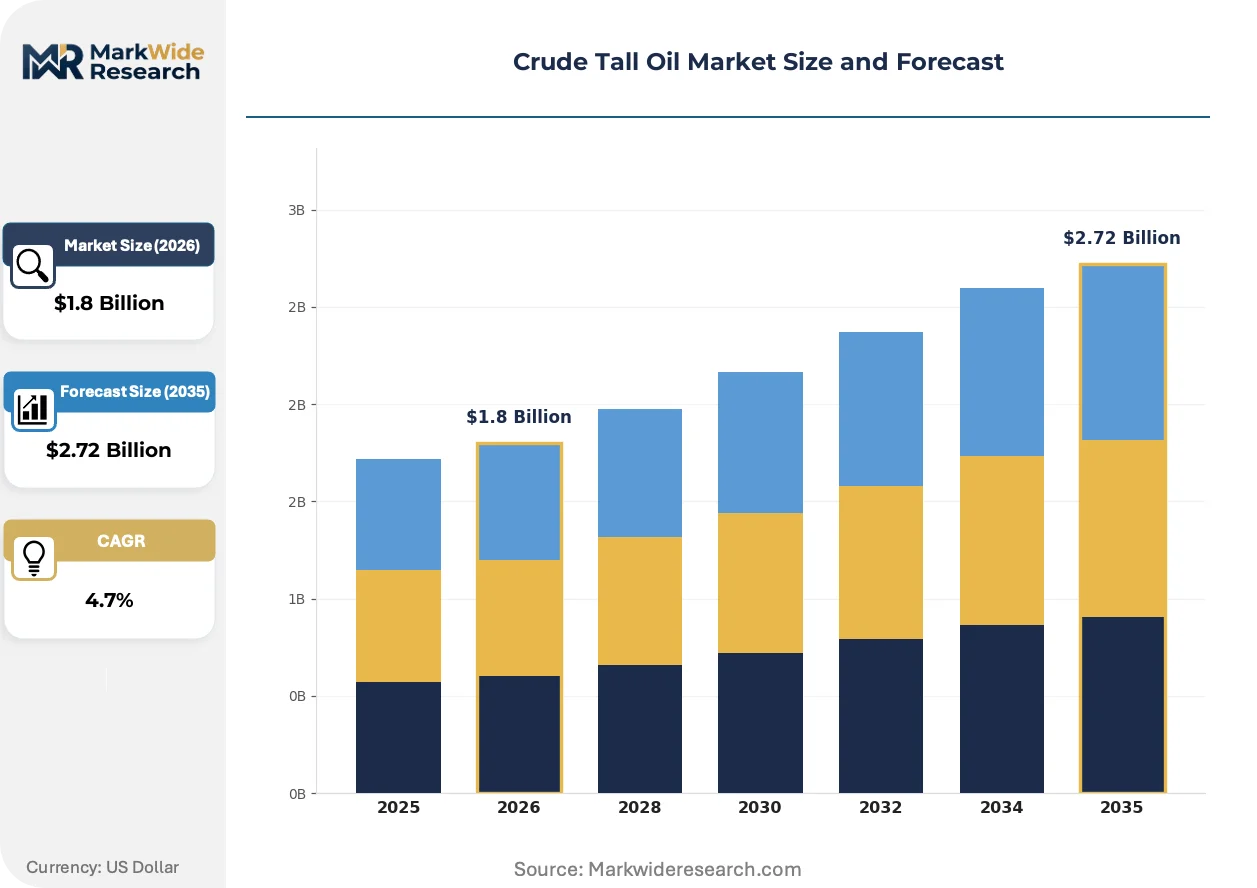
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fatty Acids, Rosin Acids, Sterols, Alcohols Application: Surfactants, Coatings, Adhesives, Lubricants End User: Pulp and Paper, Paints and Coatings, Personal Care, Biofuels Sales Channel: Direct Sales, Distributors, Online Retail, B2B Platforms |
| Companies Covered | Ingevity Corporation, Forchem Oyj, Kraton Corporation, Georgia-Pacific Chemicals, Citec Group Oy Ab, UPM-Kymmene Corporation, Stora Enso Oyj, Pine Chemical Group, SunPine AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crude Tall Oil Market Emerging Trajectories
Process intensification and digital distillation control are compressing capital requirements for entry-scale fractionation, while regulatory carbon-accounting rules are rewriting which CTO derivatives qualify for premium biofuel markets.
Supercritical fluid extraction is expanding into sterol purification from crude tall oil pitch residues, delivering pharmaceutical-grade purity without thermal degradation. Specialty chemical buyers in nutraceutical applications are adopting this route faster than conventional crystallization methods. The technology is expanding into higher-margin product tiers that conventional vacuum distillation cannot access.
EU Green Deal sustainability criteria are tightening chain-of-custody documentation for biomass-derived chemicals entering European biofuel pools. Fractionators must now demonstrate mass-balance traceability from specific pulp mill sources through derivative production. Nordic suppliers with integrated kraft operations are responding fastest due to captive feedstock control.
Buyers are consolidating procurement through direct mill relationships rather than merchant distributors, compressing intermediary margins. Refinery offtake teams are embedding sourcing specialists at pulp facilities in Finland and Sweden to secure volume commitments. This pattern is most visible in sustainable aviation fuel supply chains where certification requirements demand feedstock specificity.
Crude Tall Oil Market Segmentation
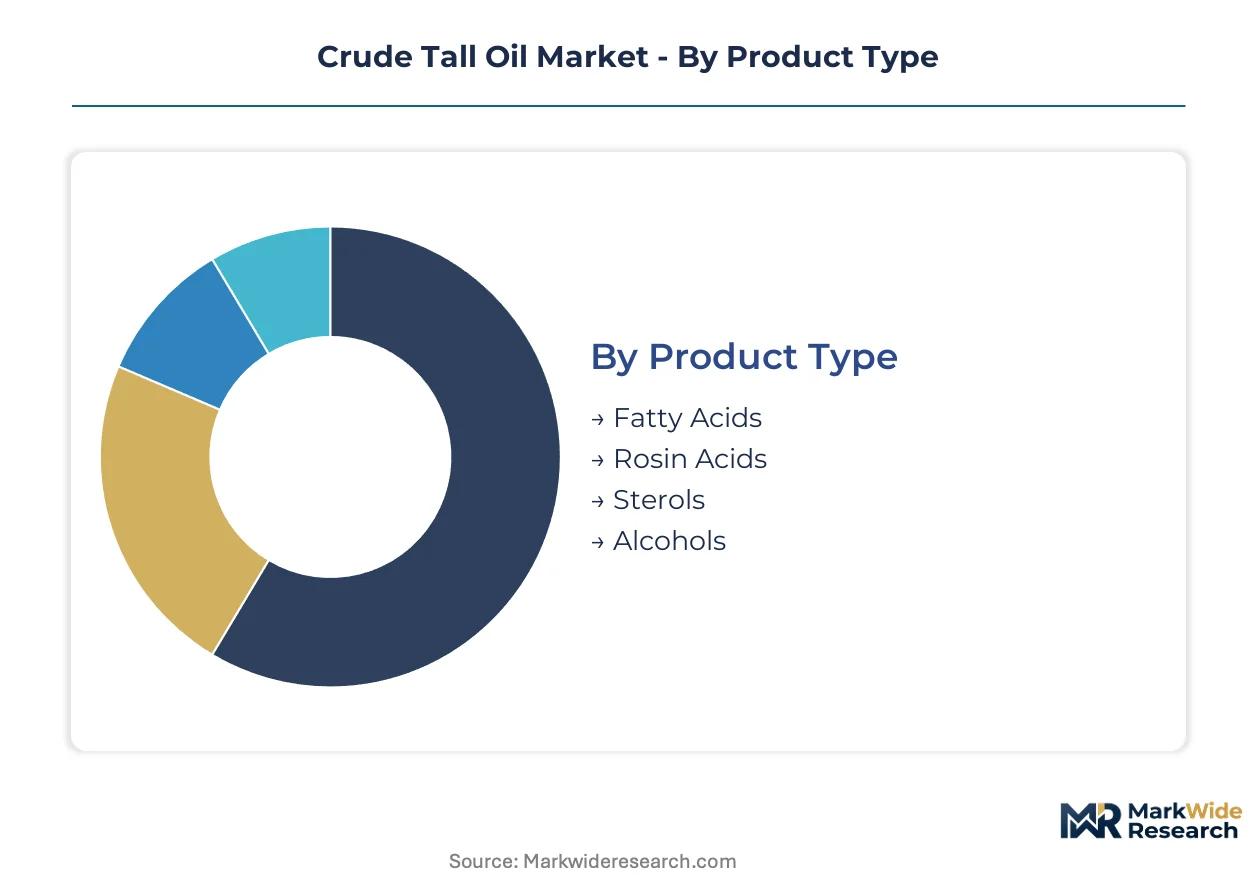
Crude tall oil fractionation yields chemically distinct cuts with divergent margin profiles and end-use specifications. Buyers configure procurement around discrete product streams rather than full crude purchases, reshaping how suppliers structure commercial relationships and inventory commitments.
Product Type:
Standalone commodity cuts dominate merchant trade, while embedded specialty fractions require captive distillation infrastructure and direct mill relationships.
- Fatty Acids:C18 unsaturated chains comprising 40-60% of typical crude composition, these serve as feedstock for dimer acids, alkyd resins, and renewable diesel hydroprocessing. Demand concentrates in US Gulf Coast refineries where EPA renewable fuel standards pull distillation residues into biofuel blending pools.
- Rosin Acids:Abietic and pimaric acid fractions deliver tackifier functionality for hot-melt adhesives and printing ink binders. Finnish and Swedish integrated pulp-to-chemicals complexes anchor supply security through captive recovery systems that stabilize Nordic rosin acid availability.
- Sterols:Purified sitosterol and campesterol command pharmaceutical-grade premiums for cholesterol-lowering drug intermediates.
- Alcohols:Hydrogenated tall oil alcohols serve surfactant and lubricant esterification routes.
Fatty acids lead volumes today; sterols are gaining share fastest.
Application:
Cost-tier stratification separates specification-grade coatings from commodity surfactant feedstocks, with biofuel intermediates disrupting traditional pricing bands.
- Surfactants:Tall oil fatty acid ethoxylates and sulfonates serve industrial cleaning and personal care formulations. REACH registration requirements and ECHA substance evaluation timelines constrain European fractionator market access for derivative esters.
- Coatings:Alkyd resin binders leverage rosin acid-modified fatty acids for drying oil performance in architectural and industrial paints. Nordic suppliers with integrated kraft operations respond fastest to EU Green Deal sustainability documentation demands.
- Adhesives:Gum rosin competition from Chinese tapping operations compresses price ceilings for standard-grade rosin acid tackifiers.
- Lubricants:Ester base stocks derived from tall oil fatty acids serve biodegradable hydraulic fluid and metalworking applications.
Surfactants anchor current volume; coatings are climbing the fastest on construction chemical demand.
End User:
Customer-type concentration distinguishes captive pulp mill operators from merchant chemical buyers with divergent supply security requirements.
- Pulp and Paper:Integrated kraft complexes recover CTO as process byproduct, with black liquor gasification investments threatening diversion to on-site power generation rather than chemical extraction.
- Paints and Coatings:Formulators source specification-grade rosin acid derivatives for alkyd resin production, with ASTM D7566 annex pathways for biomass-derived lipids creating first-mover advantages for qualified fractionators.
- Personal Care:Pharmaceutical sterol demand for vitamin D precursors commands 4-6x fatty acid margins.
- Biofuels:Renewable diesel and sustainable aviation fuel producers negotiate direct offtake relationships with Scandinavian pulp operators, bypassing traditional chemical distributors.
Pulp and paper leads volumes today; biofuels are expanding most quickly on blending mandate expansion.
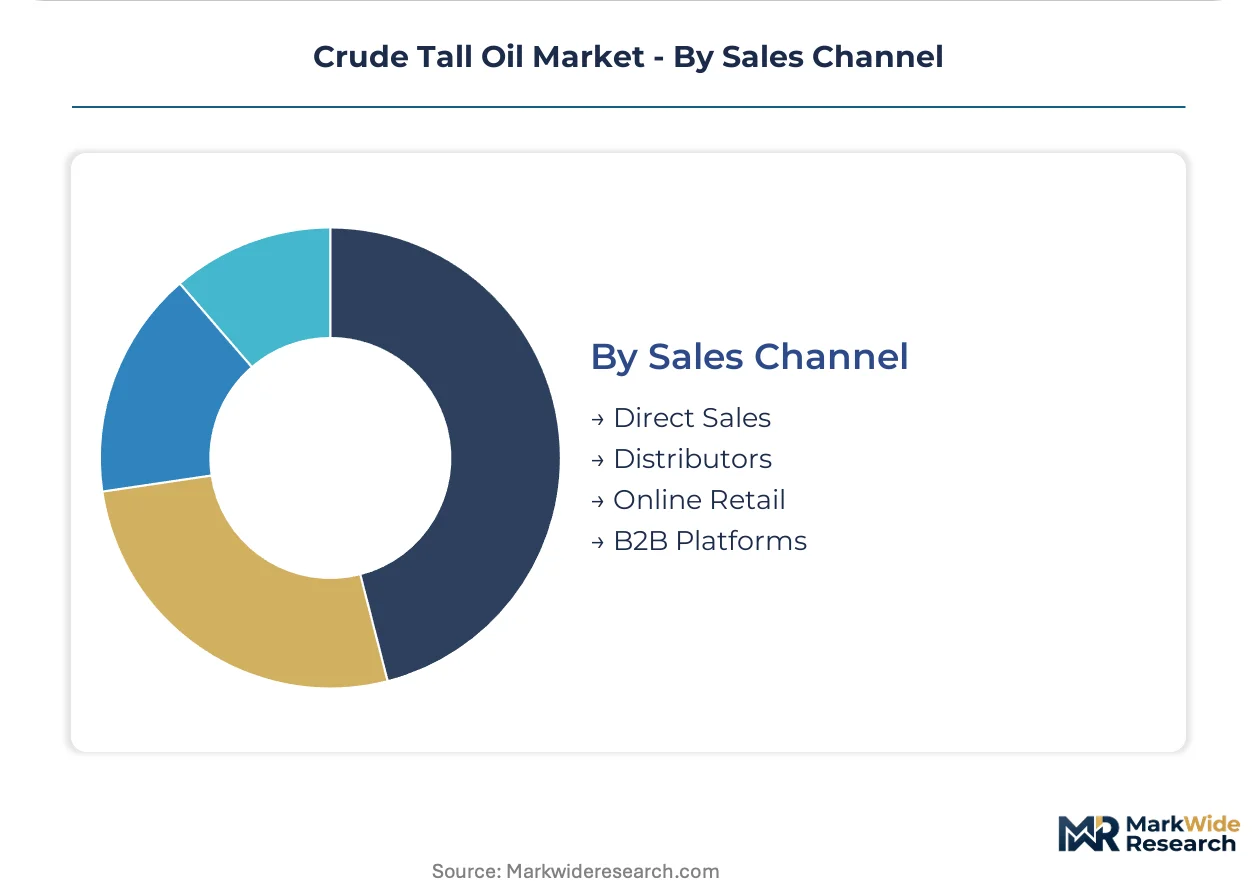
Sales Channel:
Supply concentration in Nordic integrated operations favors direct mill relationships over intermediary distribution for volume buyers.
- Direct Sales:Refinery offtake teams embed sourcing specialists at Finnish and Swedish pulp facilities to secure volume commitments with feedstock specificity for certification requirements.
- Distributors:Merchant channels serve smaller coatings and adhesives formulators lacking procurement scale for direct mill negotiations.
- Online Retail:Specialty sterol and pharmaceutical-grade fractions move through digital platforms for nutraceutical compounders.
- B2B Platforms:Spot-market purchasing for standard fatty acid cuts enables flexible procurement that bypasses traditional long-term offtake contracts.
Direct sales leads volumes today; B2B platforms are gaining share fastest on modular fractionation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The kraft pulping industry first commercialized crude tall oil recovery in Scandinavia during the 1930s, establishing Finland and Sweden as the historical foundation for global supply. Integrated pulp-to-chemicals complexes in these countries continue to anchor production infrastructure that newer markets reference for technology transfer and operational standards.
United States
EPA renewable fuel standards pull distillation residues into renewable diesel hydroprocessing at Gulf Coast refineries from Texas to Louisiana. The Southeast kraft belt spanning Georgia, Alabama, and the Carolinas hosts captive CTO recovery systems tied to containerboard and tissue production. Ingevity Corporation leverages mill partnerships across this region to secure feedstock priority for fractionation operations.
Finland
Forchem Oyj anchors margin structures through backward integration into domestic pulp assets, while UPM-Kymmene and Stora Enso operate integrated recovery systems at multiple mill sites. EU Green Deal sustainability criteria and Renewable Energy Directive II qualification pathways shape export market access for CTO-derived sustainable aviation fuel intermediates. The Kemi-Tornio industrial cluster concentrates advanced fractionation capacity serving European biofuel refiners.
Sweden
SunPine AB operates specialized refining infrastructure in the Piteå region, converting CTO into renewable diesel feedstocks for Preem and other Nordic fuel distributors. The country's national energy regulator, Energimyndigheten, oversees compliance with EU biomass sustainability certification requirements. Gothenburg's chemicals corridor hosts downstream esterification capacity for lubricant and surfactant applications.
Germany
REACH registration requirements and ECHA substance evaluation timelines constrain market access for derivative tall oil fatty acid esters, favoring established fractionators with regulatory compliance bandwidth. The country's adhesives and coatings formulators in North Rhine-Westphalia source specification-grade rosin acid derivatives for alkyd resin production. BASF and Evonik operate tall oil derivative processing at Ludwigshafen and Marl sites.
China
Gum rosin from tapping operations in Guangxi and Yunnan provinces competes with imported CTO-derived rosin acids in adhesives applications, compressing price ceilings for standard grades. The country's national standardization administration, SAMR, oversees GB standards for pine chemical derivatives. Shandong Province hosts surfactant manufacturers consuming hydrogenated tall oil alcohols for industrial cleaning formulations.
Crude Tall Oil Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the sterol-pharmaceutical and specialty ester segments, while standard fatty acid and rosin acid operations compete on feedstock access and fractionation scale. The vendor base stratifies into three archetypes: integrated pulp-to-chemicals operators with captive supply security, independent fractionators dependent on merchant feedstock procurement, and biofuel refiners securing direct mill relationships to bypass traditional distribution. Dominant competitive moves include backward integration into kraft mill partnerships and direct refinery offtake contracting that disintermediates chemical distributors.
Among Nordic integrated operators, Forchem Oyj and SunPine AB exemplify the captive-feedstock archetype, with the former representing traditional chemical fractionation and the latter illustrating biofuel-focused vertical configuration. Ingevity Corporation occupies a position as the leading US-based independent, demonstrating merchant-processor scale without pulp mill ownership. Kraton Corporation and Georgia-Pacific Chemicals sit within the specialty derivatives tier, anchoring rosin acid purity competition for adhesives and tackifier applications.
| Leading Market Players |
|---|
| Ingevity Corporation |
| Forchem Oyj |
| Kraton Corporation |
| Georgia-Pacific Chemicals |
| Citec Group Oy Ab |
| UPM-Kymmene Corporation |
| Stora Enso Oyj |
| Pine Chemical Group |
| SunPine AB |
| Others |
Supply Flow & Price Mechanics
Family-owned Finnish pulp operators anchor supply discipline through multi-decade kraft mill relationships that constrain spot-market volatility and sustain premium pricing for certified biofuel intermediates. This ownership pattern limits aggressive price competition while concentrating margin capture in integrated Nordic complexes.
Pricing Analysis
Contract-based long-term offtake agreements dominate crude tall oil procurement, with three-tier pricing structure across premium, standard, and economy levels differentiated by ISCC PLUS certification status and volume scale. Premium tiers attach to sustainable aviation fuel qualification pathways under EU Green Deal criteria, while standard grades face cost compression from gum rosin substitution in adhesives. Biofuel refiners exhibit lowest price sensitivity due to blending mandate compliance requirements, whereas coatings formulators negotiate aggressively on rosin acid specifications.
Supply Chain Analysis
Single-source vulnerability sits with Scandinavian kraft complexes in Finland and Sweden that feed 60% of European fractionation capacity. Feedstock draws from pine and spruce pulping operations, with distillation residues and pitch fractions as secondary outputs. Tariff exposure on Chinese gum rosin imports threatens rosin acid margin structures. Distribution runs through direct mill relationships for volume buyers, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crude tall oil functions as a stable compounder anchored by renewable diesel and sustainable aviation fuel blending mandates that institutionalize demand growth regardless of chemical cycle volatility.
For Market Incumbents: Anchor feedstock security through captive kraft mill partnerships in the US Southeast or Nordic regions, countering black liquor gasification threats that divert CTO to on-site power generation. Deepen ISCC PLUS certification bandwidth to capture EU Green Deal premium tiers, while expanding distillation capacity for pharmaceutical-grade sterol fractions that command 4-6x fatty acid margins. For New Entrants and Emerging Players: Enter via supercritical fluid extraction technology for sterol purification from pitch residues, targeting nutraceutical compounders with pharmaceutical-grade purity requirements. White-space availability concentrates in North American biofuel refinery offtake contracting, where EPA renewable fuel standards pull distillation residues into renewable diesel hydroprocessing without established Nordic supplier relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among independent US fractionators lacking captive pulp assets but holding EPA pathway approvals and Gulf Coast refinery relationships. Long-term viability frames around 5-10 year renewable fuel standard durability and aviation fuel decarbonization mandates. Monitor black liquor gasification investment announcements at major kraft complexes as feedstock availability inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Assets | Forchem Oyj demonstrates margin stability through Finnish pulp captive supply. |
| Sustainable Aviation Fuel Qualification | ASTM D7566 annex pathways create first-mover premiums for compliant fractionators. |
| Direct Refinery Offtake Contracting | Preem and SunPine AB bypass distributors with Piteå region supply integration. |
| Supercritical Sterol Extraction Scale-Up | Pharmaceutical-grade purification from pitch residues accesses 4-6x margin tiers. |
| ISCC PLUS Certification Investment | EU Green Deal mass-balance traceability requirements favor integrated Nordic operators. |
Methodological Framework
Direct dialogue with kraft mill operations managers, biofuel refinery procurement leads, fractionation plant engineers, and pharmaceutical sterol buyers grounded qualitative assessment, cross-checked against customs trade data, SEC filings from listed pine chemical specialists, EPA renewable fuel standard docket records, and EU ECHA substance evaluation timelines. Bottom-up volume builds from individual mill recovery rates and top-down demand validation from end-use industry consumption patterns were triangulated to constrain estimate variance.
Top-down macroeconomic drivers and bottom-up segment-specific demand elasticities were modeled across the projection horizon, with CAGRs derived from regression analysis against industrial output indices and biofuel blending mandate trajectories. Segmentation dimensions included product cut specifications, application end-uses, customer-type concentration, and regional production hub classification. Forecast inputs incorporated pulp mill energy-transition investment pipelines and REACH registration timeline delays for derivative esters.
Inputs from kraft mill operators and biofuel refiners were available through the study window; gaps in black liquor gasification project commitment data introduce uncertainty bands around long-term feedstock availability assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Southeast Asia Refined Petroleum Products Market
Petroleum Products
United States Refined Petroleum Products Market
Petroleum Products
Hydrocarbon Market
Petroleum Products
Pale Oil Market
Petroleum Products
Underground Storage Tanks Market
Petroleum Products
Floating Roof Tank Market
Petroleum Products
Helical Submerged Arc Welded Pipe Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
LPG [Liquefied Petroleum Gas] Market
Petroleum Products
Green Petcoke Market
Petroleum Products
South Africa Petroleum Market
Petroleum Products
Australia Refined Petroleum Products Market
Petroleum Products
Marine Minerals Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Pygas (Pyrolysis Gasoline) Market